
 Global Tangential Flow Filtration Market | 2026-2036
Global Tangential Flow Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tangential Flow Filtration Market Foresight
Membrane manufacturing capacity in Germany and the United States is broadening as bioprocessing demand intensifies. Danaher Corporation leverages its Pall Life Sciences unit to control hollow fiber supply chains for cell culture harvest applications. Merck KGaA sustains R&D intensity in ultrafiltration cassettes for viral vector purification. Sartorius AG anchors European demand through integrated single-use TFF skids that reduce cleanroom validation burden.
Tangential flow filtration employs crossflow velocity to sweep retained species across a membrane surface, minimizing fouling while separating molecules by size using pores typically ranging from 1 kDa to 0.45 μm. The technology serves primarily to concentrate and diafilter biomolecules without denaturation in biopharmaceutical downstream processing. Hollow fiber membranes dominate installed base owing to high surface-area-to-volume ratios, yet flat sheet cassettes capture expanding share in contract manufacturing organizations seeking modularity. Ultrafiltration leads technology adoption for protein concentration, while diafiltration growth accelerates with rising buffer exchange requirements in gene therapy workflows.
The FDA enforces process validation guidelines under ICH Q5A-Q5D that mandate viral clearance documentation for TFF steps in biologics licensure. The European Medicines Agency applies MDR Annex I general safety requirements to membrane devices classified as Class IIa or IIb medical devices in ex vivo applications. China's National Medical Products Administration aligns GMP inspections with PIC/S standards for imported filtration equipment. Stakeholders must monitor evolving regulatory divergence between FDA process analytical technology expectations and EMA's quality-by-design enforcement to avoid dual validation costs.
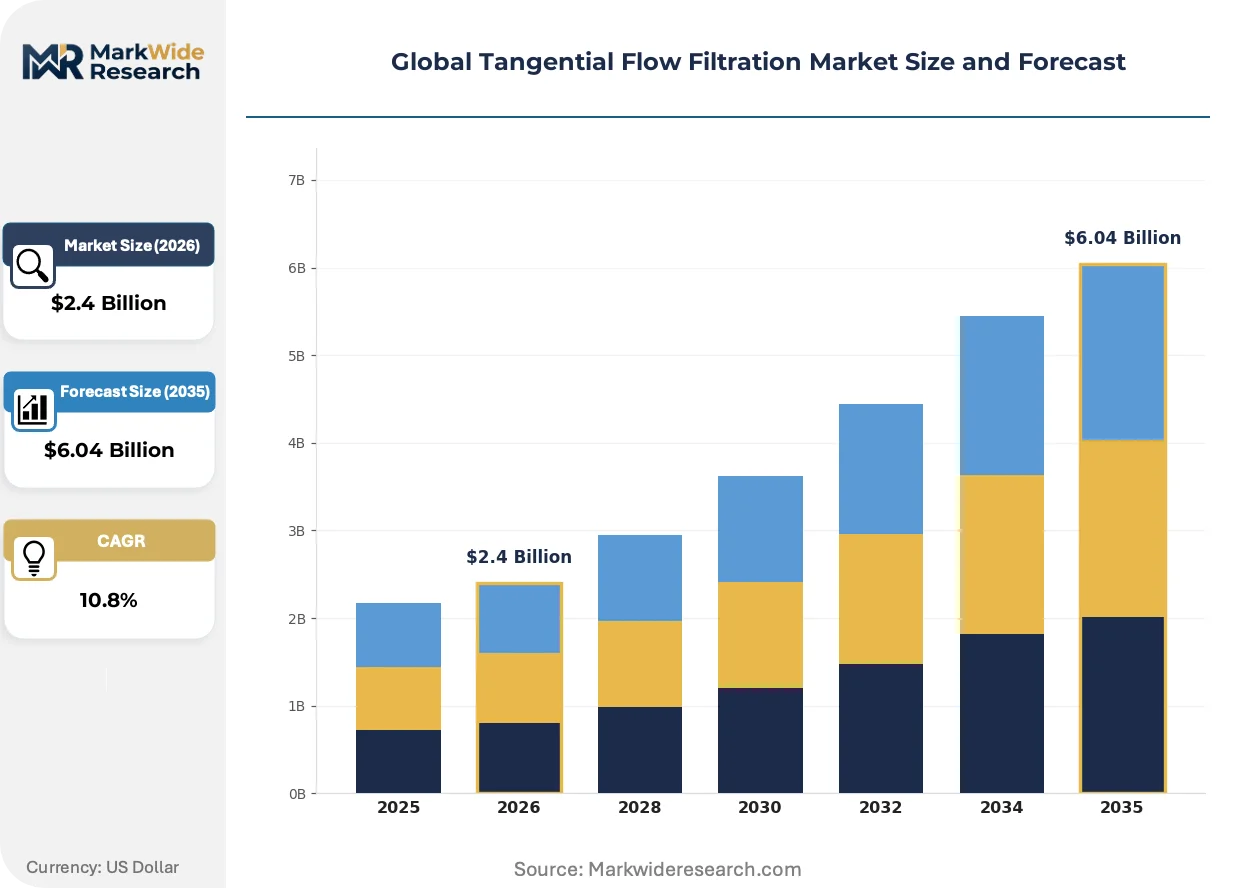
Market Dynamics
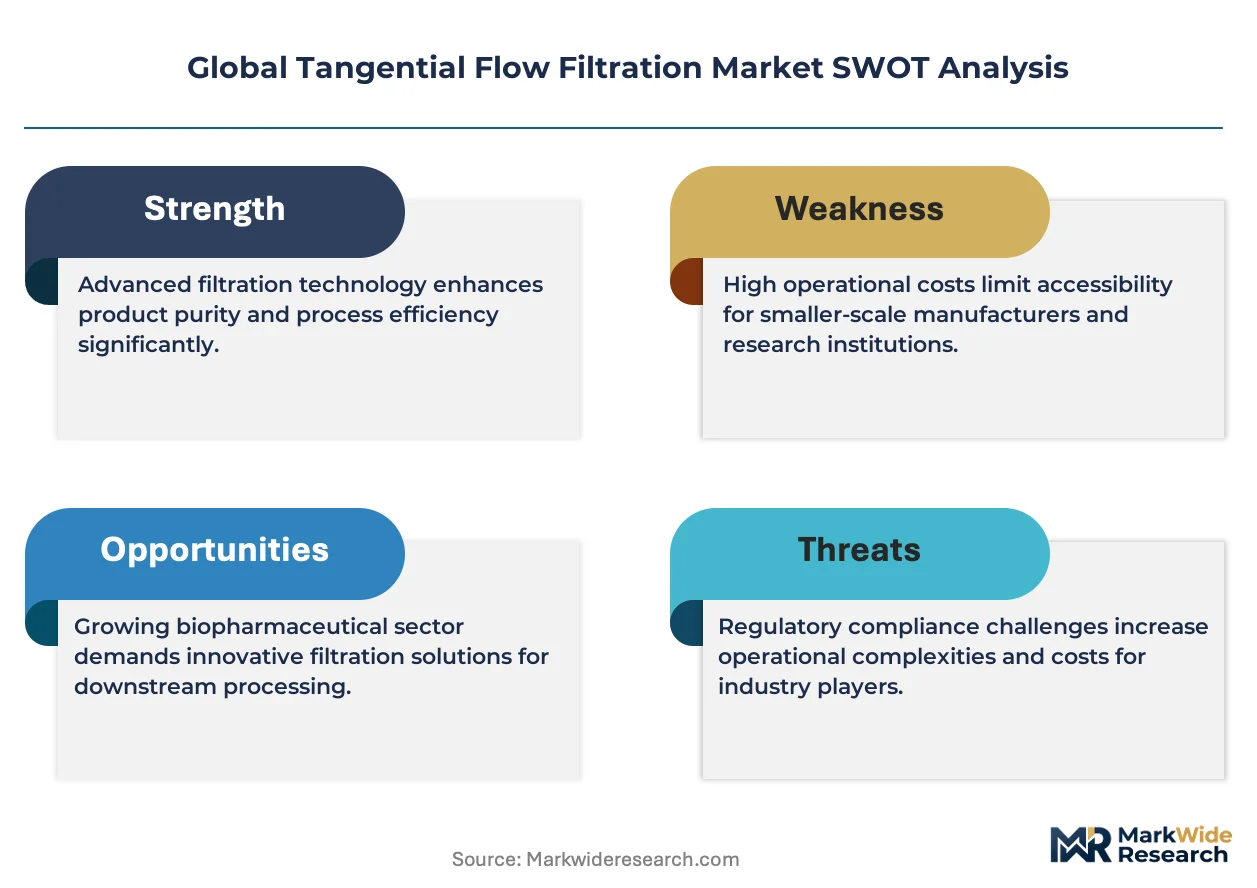
Single-use TFF systems are compressing capital deployment timelines for biopharmaceutical manufacturers, collapsing the traditional stainless-steel validation cycle from months to weeks while forcing membrane suppliers to reconfigure production lines for gamma-sterilized disposable formats.
Growth Catalysts
- Gene therapy manufacturing scale-up:Viral vector production requires diafiltration steps for buffer exchange, pulling membrane capacity toward 750 kDa and 1000 kDa molecular weight cutoffs. Contract development and manufacturing organizations in the United States and Germany are tripling TFF skid installations.
- FDA process analytical technology mandates:Real-time release testing requirements under ICH Q8-Q12 guidelines compel bioprocessors to integrate in-line turbidity sensors and UV monitors with TFF skids, driving replacement of legacy batch-controlled systems.
- Polyethersulfone membrane chemistry advances:Modified hydrophilic surface treatments reduce protein binding losses below 5% for monoclonal antibody applications, accelerating adoption in high-value biologics where yield preservation commands priority.
Market Restraints
- Regenerated cellulose supply concentration:Hollow fiber production depends on cellulose ester precursors sourced from a limited supplier base in Western Europe, exposing membrane manufacturers to input cost volatility and force majeure risk.
- Gamma sterilization capacity bottlenecks:Single-use TFF assemblies require cobalt-60 or e-beam terminal sterilization, with irradiation facility queues in North America extending lead times beyond 16 weeks during peak biologics campaign seasons.
- Silicone tubing substitution threat:Thermoplastic elastomer alternatives for fluid path components are capturing share in low-risk applications, compressing addressable market for platinum-cured silicone assemblies in standard ultrafiltration cassettes.
Strategic Opportunities
- Continuous bioprocessing integration:Perfusion cell culture systems require real-time concentration and diafiltration, creating white space for TFF modules designed for 24/7 operation with automated cleaning-in-place protocols.
- India biologics manufacturing emergence:CDSCO alignment with PIC/S GMP standards for imported filtration equipment is unlocking demand from Indian biosimilar producers seeking to supply regulated export markets.
- mRNA lipid nanoparticle purification:Emerging workflows for COVID-19 and oncology vaccines require tangential flow filtration for buffer exchange and contaminant removal, representing an application segment with limited incumbent supplier presence.
Industry Challenges
- Bioprocess engineering talent scarcity:Skilled operators capable of troubleshooting fouling, optimizing transmembrane pressure, and validating viral clearance claims command premium compensation, constraining facility expansion timelines.
- Dual validation burden:Divergent FDA process analytical technology expectations and EMA quality-by-design documentation requirements force manufacturers to maintain parallel validation protocols, inflating regulatory affairs headcount and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tangential Flow Filtration Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Hollow Fiber Membranes, Flat Sheet Membranes, Spiral Wound Membranes Technology: Crossflow Filtration, Ultrafiltration, Microfiltration, Diafiltration Application: Biopharmaceutical Production, Food & Beverage Processing, Water Treatment, Chemical Processing End User: Contract Manufacturing Organizations, Bioprocessing Firms, Food Processors, Water Purification Companies |
| Companies Covered | Danaher Corporation, Merck KGaA, Sartorius AG, Repligen Corporation, Parker Hannifin Corporation, Alfa Laval Corporate AB, ANDRITZ, Synder Filtration, Inc., Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tangential Flow Filtration Market Shifts & Advancements
Membrane chemistry, regulatory data requirements, and procurement contracting models are simultaneously evolving, compressing product development cycles while expanding the technical specifications that suppliers must satisfy to remain qualified vendors.
Single-pass tangential flow filtration (SPTFF) is overtaking traditional multi-pass batch concentration for high-titer monoclonal antibody processes. SPTFF modules process feed streams in a single continuous pass, eliminating hold tanks and reducing product residence time. Biologics manufacturers in Massachusetts and Bavaria are adopting SPTFF for 10 g/L+ titers, collapsing footprint requirements by 60% while forcing incumbent cassette suppliers to develop high-shear-tolerant membrane formats.
The European Union's Medical Device Regulation (MDR) Annex I general safety requirements are reclassifying certain ex vivo TFF devices as Class IIb medical devices, triggering notified body involvement and clinical evaluation obligations that did not apply under the prior Medical Device Directive. Membrane device manufacturers serving cell therapy applications must now maintain technical documentation and post-market surveillance systems comparable to implantable device suppliers, with Swissmedic and TGA adopting parallel stringency for market access.
Biopharmaceutical procurement teams are consolidating filtration spend under multi-year enterprise agreements with single-source membrane suppliers, displacing the historical practice of qualifying 2-3 vendors per manufacturing site. CDMOs in the Research Triangle Park and Basel regions are negotiating total-cost-of-ownership contracts that bundle membrane consumption, skid maintenance, and regulatory support, compressing commercial access for specialized regional suppliers lacking global service infrastructure.
Global Tangential Flow Filtration Market Segmentation
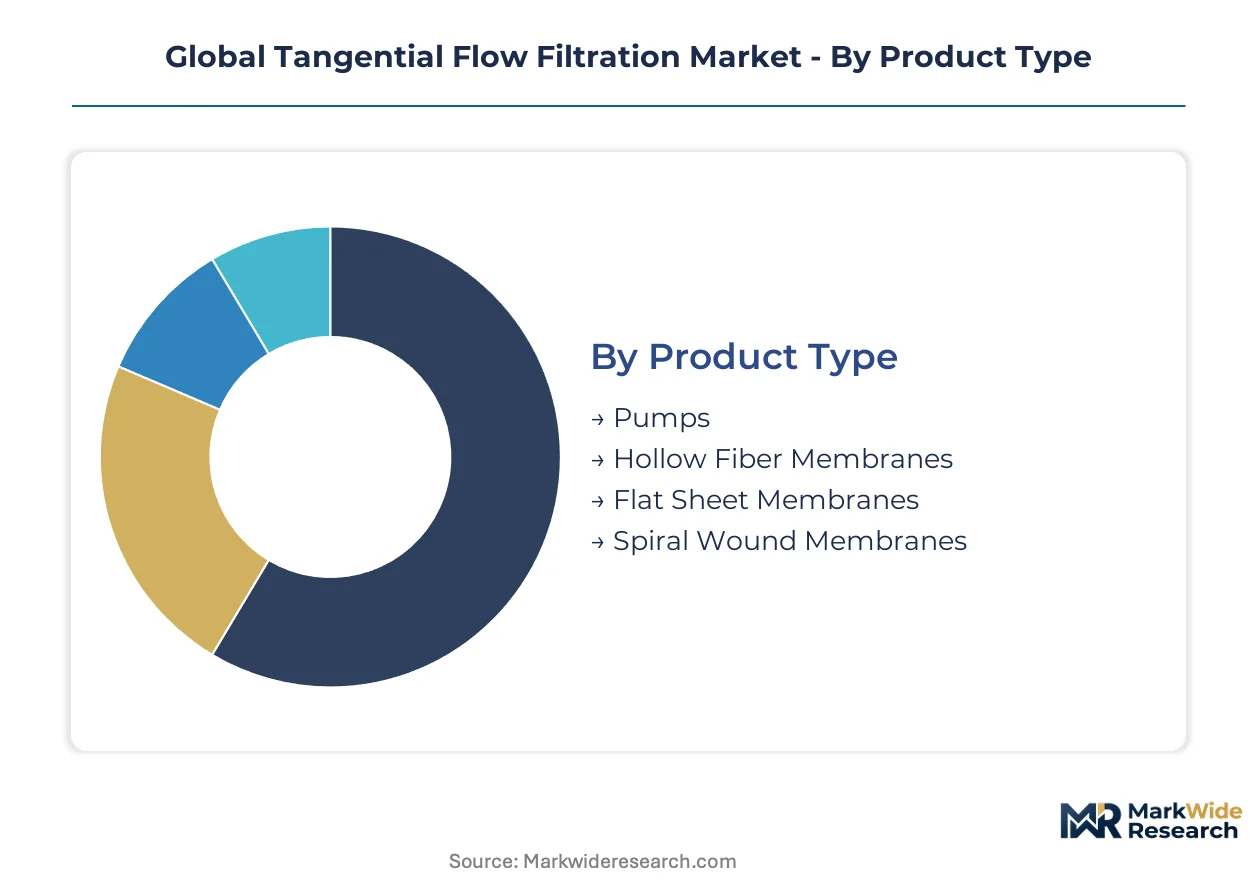
Tangential flow filtration markets fragment across membrane geometry, separation mechanism, and end-use workflow requirements. Each segmentation dimension carries distinct supply chain configurations and margin profiles that determine vendor positioning strategies.
Product Type:
Hollow fiber capacity concentrates among three suppliers controlling regenerated cellulose precursor access, while flat sheet manufacturing disperses across contract converters.
- Hollow Fiber Membranes:These cylindrical configurations pack high surface-area-to-volume ratios into compact cartridges, enabling high-throughput cell culture harvest operations. Bioprocessing demand clusters in Massachusetts and Bavaria, where perfusion bioreactor adoption is forcing membrane suppliers to scale gamma-irradiated disposable formats.
- Flat Sheet Membranes:Layered cassette constructions deliver modularity for contract manufacturing organizations running multiproduct campaigns. German and Swiss CDMOs are tripling flat sheet procurement as they pivot from stainless-steel validation cycles toward single-use skids.
- Pumps:Peristaltic and rotary lobe configurations dominate fluid movement in TFF skids, with magnetic levitation variants capturing share in shear-sensitive protein applications.
- Spiral Wound Membranes:These configurations serve lower-value water treatment and chemical processing segments where cost-per-square-meter dominates selection criteria.
Today's leader: Hollow Fiber Membranes. Tomorrow's challenger: Flat Sheet Membranes.
Technology:
Cost tier separation distinguishes high-value biopharmaceutical separation from commodity industrial clarification, with membrane chemistry and validation documentation driving price multiples.
- Ultrafiltration:Molecular weight cutoff membranes ranging 1-1000 kDa concentrate proteins and viral vectors without denaturation. FDA process analytical technology mandates under ICH Q8-Q12 are compelling real-time transmembrane pressure monitoring integration, displacing legacy batch-controlled systems in United States facilities.
- Diafiltration:Continuous buffer exchange workflows enable formulation of gene therapy vectors and mRNA lipid nanoparticles. The technology is gaining share fastest in ex vivo cell therapy applications where EMA MDR Annex I reclassification to Class IIb medical devices is tightening documentation requirements.
- Microfiltration:0.1-0.45 μm pore structures retain cells and cell debris upstream of finer separations, with ceramic membranes capturing share in aggressive chemical environments.
- Crossflow Filtration:The foundational velocity-sweep mechanism underlies all tangential flow operations, with single-pass configurations collapsing footprint requirements for high-titer monoclonal antibody processes.
Ultrafiltration commands current revenue concentration. Diafiltration climbs the fastest as gene therapy manufacturing scales.
Application:
Volume distribution skews heavily toward biopharmaceutical production, though water treatment maintains installed base dominance in absolute unit terms.
- Biopharmaceutical Production:Downstream purification of monoclonal antibodies, recombinant proteins, and viral vectors requires validated viral clearance documentation under ICH Q5A-Q5D guidelines. China's NMPA alignment with PIC/S GMP standards is unlocking demand from domestic biosimilar producers seeking regulated export market access.
- Water Treatment:Municipal and industrial wastewater clarification employs lower-specification membranes with reduced validation burdens. The segment's margin compression intensifies as Chinese membrane manufacturers expand polyethersulfone production capacity.
- Food & Beverage Processing:Dairy protein concentration and wine clarification apply sanitary-grade membranes with 3-A sanitary standards compliance.
- Chemical Processing:Solvent-resistant membrane chemistries enable pharmaceutical intermediate recovery and specialty chemical purification.
Biopharmaceutical Production anchors value capture. Food & Beverage Processing offers margin expansion potential through hygienic design premiums.
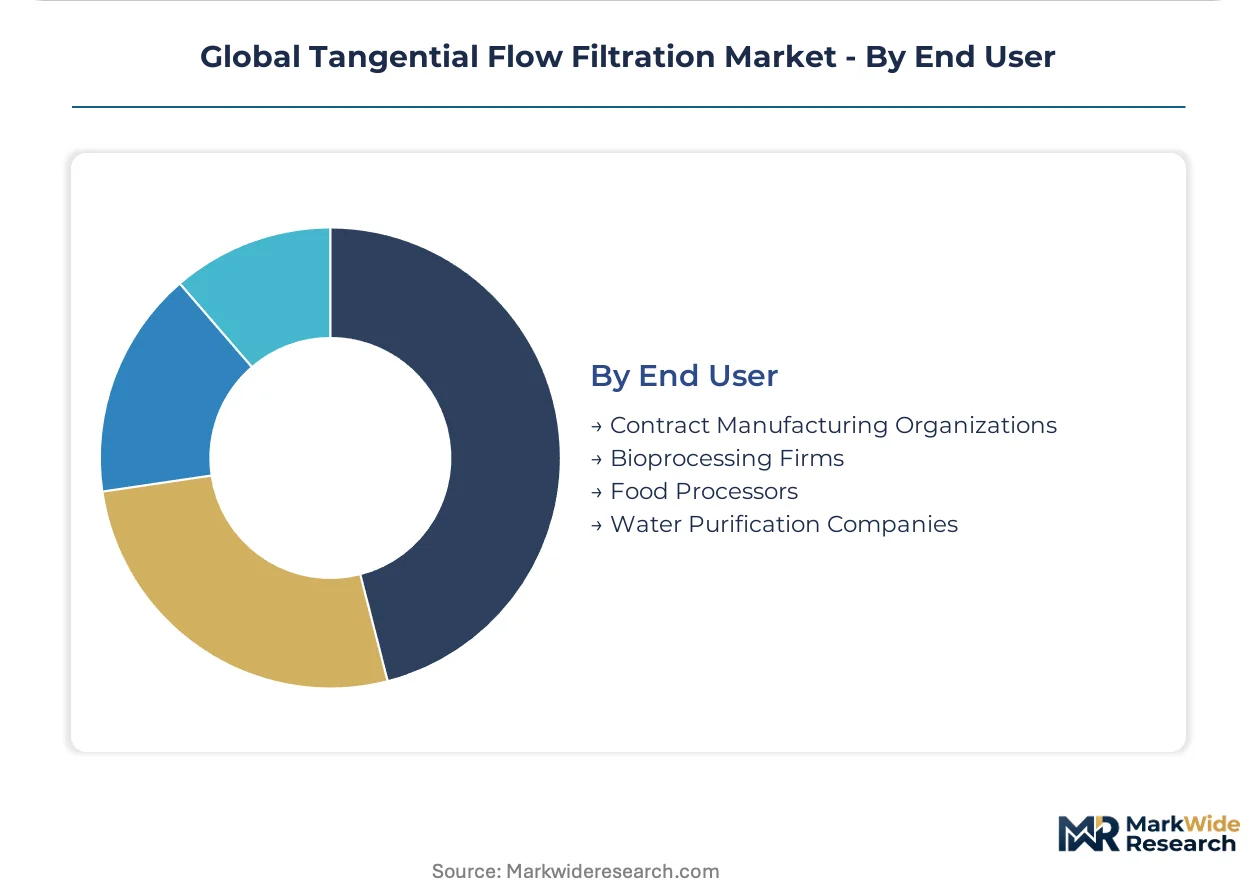
End User:
Customer type determines procurement contracting models, with bioprocessing firms consolidating spend under enterprise agreements while contract manufacturers demand supply flexibility.
- Bioprocessing Firms:Integrated pharmaceutical manufacturers operate captive TFF skids for clinical and commercial production. German and United States facilities are retrofitting stainless-steel infrastructure with single-use assemblies to compress campaign changeover timelines.
- Contract Manufacturing Organizations:CDMOs in Research Triangle Park and Basel negotiate total-cost-of-ownership contracts bundling membrane consumption, skid maintenance, and regulatory support. Their multiproduct flexibility requirements favor modular flat sheet cassettes over dedicated hollow fiber installations.
- Food Processors:Dairy and beverage manufacturers prioritize clean-in-place compatibility and membrane lifetime over separation precision.
- Water Purification Companies:Municipal utilities and industrial water treatment operators select on capital expenditure and energy efficiency metrics.
Bioprocessing Firms currently dominate membrane consumption value. Contract Manufacturing Organizations represent the steepest expansion trajectory as outsourced biologics manufacturing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing bioprocessing capacity toward jurisdictions where validation costs and approval timelines compress project economics. Manufacturers now site facilities based on cumulative compliance burden rather than labor costs alone.
United States
FDA process analytical technology mandates under ICH Q8-Q12 are accelerating TFF skid replacement cycles in Massachusetts and North Carolina bioclusters. CDMOs in Research Triangle Park tripled single-use system installations to serve gene therapy viral vector demand. The agency's real-time release testing requirements favor suppliers integrating in-line sensors.
Germany
EMA MDR Annex I reclassification of ex vivo TFF devices to Class IIb medical devices is tightening documentation obligations for membrane manufacturers. Bavarian CDMOs negotiate total-cost-of-ownership contracts bundling membrane consumption with regulatory support. Swissmedic adopts parallel stringency, extending compliance costs to Basel-region suppliers.
China
NMPA alignment with PIC/S GMP standards is unlocking demand from domestic biosimilar producers seeking regulated export market access. Yangtze River Delta biologics clusters are expanding membrane validation capabilities. The regulator's inspection intensity for imported filtration equipment is rising with domestic substitution policy support.
India
CDSCO harmonization with PIC/S standards is enabling Indian biosimilar manufacturers to supply regulated markets. Maharashtra and Karnataka bioprocessing parks are attracting TFF system deployments for insulin and monoclonal antibody production. The country's national pharmaceutical regulator is intensifying GMP enforcement for filtration equipment imports.
Switzerland
Swissmedic's adoption of EU MDR-equivalent stringency for membrane-based medical devices is elevating technical documentation requirements. Basel-region bioprocessing firms consolidate filtration spend under enterprise agreements. The country's central location anchors supply chain coordination between German manufacturing and Italian pharmaceutical demand.
Global Tangential Flow Filtration Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue continuous bioprocessing integration and mRNA application specialization. The vendor base concentrates among diversified life sciences conglomerates controlling membrane chemistry and gamma-sterilization infrastructure. Three archetypes dominate: integrated filtration system suppliers, specialized membrane chemists, and contract manufacturing enablers. Competitive moves center on multi-year enterprise contracting and backward integration into regenerated cellulose precursor supply.
Among diversified life sciences conglomerates, Danaher Corporation, Merck KGaA, and Sartorius AG exemplify distinct strategic positioning. Danaher occupies a position anchored in hollow fiber supply chain control through its Pall Life Sciences unit. Merck KGaA represents the membrane chemistry intensivist archetype with ultrafiltration cassette specialization. Sartorius AG sits within the European integrated skid supplier tier, reducing cleanroom validation burden for contract manufacturers. These three entities collectively illustrate how scale, chemistry depth, and regional anchoring segment competitive advantage in biopharmaceutical filtration.
| Leading Market Players |
|---|
| Danaher Corporation |
| Merck KGaA |
| Sartorius AG |
| Repligen Corporation |
| Parker Hannifin Corporation |
| Alfa Laval Corporate AB |
| ANDRITZ |
| Synder Filtration, Inc. |
| Pall Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into regenerated cellulose precursor supply anchors both cost position and pricing power for hollow fiber membrane manufacturers serving biopharmaceutical clients in Massachusetts and Bavaria. Gamma-sterilized disposable formats command premium positioning against reusable stainless-steel alternatives as CDMOs compress campaign validation timelines.
Pricing Analysis
Distributor margins in the 15-25% range separate membrane manufacturers from end-user bioprocessing facilities, with direct-to-OEM contracts for enterprise-scale CDMOs compressing channel layers. Three-tier pricing structure across validated premium, standard GMP-grade, and economy industrial tiers differentiates based on FDA master file documentation depth and viral clearance validation data. Cost compression in standard ultrafiltration cassettes is intensifying because Chinese membrane manufacturers are expanding polyethersulfone production capacity. Contract manufacturing organizations exhibit highest price sensitivity due to multiproduct campaign economics, while integrated bioprocessing firms prioritize yield preservation over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta biologics clusters are reshaping sourcing patterns for imported filtration equipment as NMPA inspection intensity rises. Manufacturing concentrates in Germany, the United States, and China, with hollow fiber production drawing from regenerated cellulose precursor supply concentrated in Western Europe. Single-source vulnerability in gamma-irradiation capacity creates bottlenecks extending assembly lead times during peak campaign seasons. Distribution runs through authorized distributors serving regional bioclusters, with direct service contracts capturing share among large CDMOs in Research Triangle Park and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as gene therapy manufacturing scale-up pulls membrane specifications toward premium diafiltration formats with enhanced viral clearance documentation. FDA process analytical technology mandates and EMA MDR reclassification are simultaneously elevating technical barriers to vendor qualification.
For Market Incumbents: Anchor market position through captive supply of regenerated cellulose precursors and gamma-sterilization infrastructure to defend against emerging membrane chemists from Asia. Incumbents must accelerate continuous bioprocessing module development to preempt displacement by specialized entrants targeting perfusion culture integration. Certification investment in FDA master file depth and EMA notified body relationships constitutes the critical defensive lever as regulatory documentation requirements tighten across both jurisdictions. For New Entrants and Emerging Players: Enter via mRNA lipid nanoparticle purification workflows where incumbent presence remains limited and technical specifications are still stabilizing. India biosimilar manufacturing expansion under CDSCO PIC/S alignment offers the most penetrable geography for qualified filtration equipment. A service-led go-to-market bundling regulatory support with membrane supply addresses the dual validation burden constraining facility expansion timelines. For Investors and Strategic Acquirers: Roll-up economics work for specialized membrane chemists with proprietary surface modification IP because biopharmaceutical procurement consolidation is displacing multi-vendor qualification practices. The 5-10 year viability window favors targets with gamma-sterilization infrastructure and FDA master file portfolios over pure technology plays. Watch CDMO capital expenditure announcements in gene therapy viral vector capacity as the inflection signal for diafiltration membrane demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive cellulose ester access insulates margin from Western European supply concentration. |
| Gamma Sterilization Capacity Expansion | Proprietary irradiation infrastructure collapses lead times below 16-week industry peaks. |
| Continuous Bioprocessing Module Development | 24/7 TFF operation protocols capture perfusion culture demand from Massachusetts bioclusters. |
| Regulatory Support Service Bundling | Dual FDA-EMA validation documentation reduces CDMO regulatory affairs headcount burden. |
| mRNA Application Specialization | Limited incumbent presence in lipid nanoparticle workflows creates white space for technical positioning. |
Research Methodology
Direct dialogue with bioprocess engineering directors, regulatory affairs leads at membrane device manufacturers, CDMO procurement managers, and gamma-irradiation facility operators grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation databases, ICH Q5A-Q5D viral clearance guidelines, and NMPA GMP inspection records. Bottom-up membrane consumption modeling across hollow fiber, flat sheet, and cassette formats triangulated against top-down biologics manufacturing capacity expansion data.
Segment-level projections across membrane geometry, separation technology, and end-user archetype fed into analytical frameworks spanning the projection horizon. Modeled dimensions included molecular weight cutoff tier, single-use versus reusable format, biopharmaceutical versus industrial application, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, gene therapy manufacturing scale-up trajectories, and continuous bioprocessing adoption curves. Forecast inputs incorporated gamma-sterilization capacity constraints and regenerated cellulose precursor supply elasticity.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time CDMO capital expenditure disclosure introduce uncertainty bands around near-term capacity expansion timing. Forecasts reflect assumptions regarding PIC/S GMP alignment persistence in China and India, ICH guideline implementation consistency, and membrane chemistry innovation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Activated Carbon Filter Market
Filters
Air Filtration Media Market
Filters
Nonwoven Filter Media Market
Filters
Global Gas Phase Filtration Market
Filters
Global Depth Filtration Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Fabric Filter System Market
Filters
Global Pleated Filters Market
Filters
Global Industrial Filters Market
Filters
Single-Use Filtration Assemblies Market
Filters
Activated Carbon Market
Filters
US Baghouse Filters Market
Filters
Global High Temperature Filters Market
Filters
Global Cartridge Filters Market
Filters
Industrial Filter Paper Market
Filters
Filtering Centrifuges Market