
 Global Recycled Plastics Market | 2026-2036
Global Recycled Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recycled Plastics Market Outlook
Chemical recycling breakthroughs in pyrolysis and depolymerization are reshaping how post-consumer mixed plastics re-enter virgin-quality supply chains. Veolia leverages its integrated waste-to-polymer platform across European sorting and reprocessing assets. Indorama Ventures Public Company Limited anchors global rPET capacity through bottle-to-bottle recycling investments in multiple continents. REMONDIS SE & Co. KG differentiates via closed-loop collection systems tied to automotive and electronics OEMs.
Recycled plastics comprise reprocessed thermoplastic polymers recovered from post-industrial and post-consumer waste streams, typically re-melted, filtered, and pelletized to achieve melt flow indices between 2 and 30 g/10 min for injection molding or extrusion compatibility. These materials primarily displace virgin resin in applications where technical specifications permit partial or full substitution, reducing fossil feedstock dependence and landfill diversion costs. Recycled PET dominates packaging applications due to established bottle collection infrastructure and FDA EFSA food-contact approvals, while Recycled HDPE commands premium positioning in construction pipes and automotive fuel tanks where durability standards are stringent. Recycled LDPE in film applications faces margin compression from lightweighting trends but sustains volume through e-commerce stretch wrap demand.
The EU Green Deal's recycled content mandates, coupled with FDA food-contact notification requirements for rPET in the United States and China's GB standards for plastics recycling quality, collectively determine market access thresholds and product certification costs for processors. REACH registration obligations for chemical recyclers in Europe add compliance layers that favor scaled operators with dedicated regulatory affairs capabilities. Stakeholders must monitor chemical recycling scale-up economics against mechanical recycling yield rates, as the technology mix selected over the next investment cycle will lock in cost structures for decades.
Market Dynamics
The EU Green Deal's mandatory recycled content targets are forcing virgin-to-recycled substitution across consumer goods supply chains, while chemical recycling scale-up economics compete against mechanical recycling yield rates to determine the technology mix that will lock in cost structures for decades.
Growth Catalysts
- EU Green Deal mandates:Mandatory recycled content thresholds in packaging and automotive components are compelling OEMs to redesign specifications around post-consumer feedstocks.
- Pyrolysis commercialization:Chemical recycling breakthroughs in depolymerization are enabling mixed plastic waste streams to re-enter virgin-quality supply chains at scale.
- Germany's Rhine-Ruhr corridor:Mechanical recycling infrastructure and chemical recycling pilot plants cluster around this industrial zone, concentrating technical talent and feedstock access.
Market Restraints
- Feedstock price volatility:Virgin resin pricing fluctuations compress recycled polymer margins when oil prices drop below threshold levels that justify collection and reprocessing costs.
- Collection infrastructure gaps:Post-consumer film and flexibles lack equivalent recovery systems to bottle-to-bottle PET, constraining supply availability for LDPE recycling at scale.
- REACH registration burdens:Chemical recyclers in Europe face compliance layers that favor scaled operators with dedicated regulatory affairs capabilities over mid-tier entrants.
Strategic Opportunities
- India's informal sector formalization:Integration of waste picker networks into certified collection systems could unlock substantial post-consumer feedstock volumes for export processing.
- Automotive closed-loop contracts:Tier-1 suppliers are negotiating direct offtake agreements with recyclers for bumper-to-bumper and interior component recovery programs.
- FDA food-contact notifications:Expanded rPET approvals for thermoformed packaging applications are opening substitution pathways beyond beverage bottles into deli containers and trays.
Industry Challenges
- Polymer-specific sorting expertise:Near-infrared spectroscopy technicians and materials scientists command premium wages as facilities expand mixed-waste processing capacity.
- Food-grade certification timelines:EFSA and FDA notification processes extend 18-24 months, delaying revenue recognition for recyclers targeting premium packaging segments.
- Legacy extrusion equipment retrofitting:Mechanical recyclers face capital intensity when adapting lines designed for virgin resin to handle variable melt flow indices of post-consumer feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recycled Plastics Market |
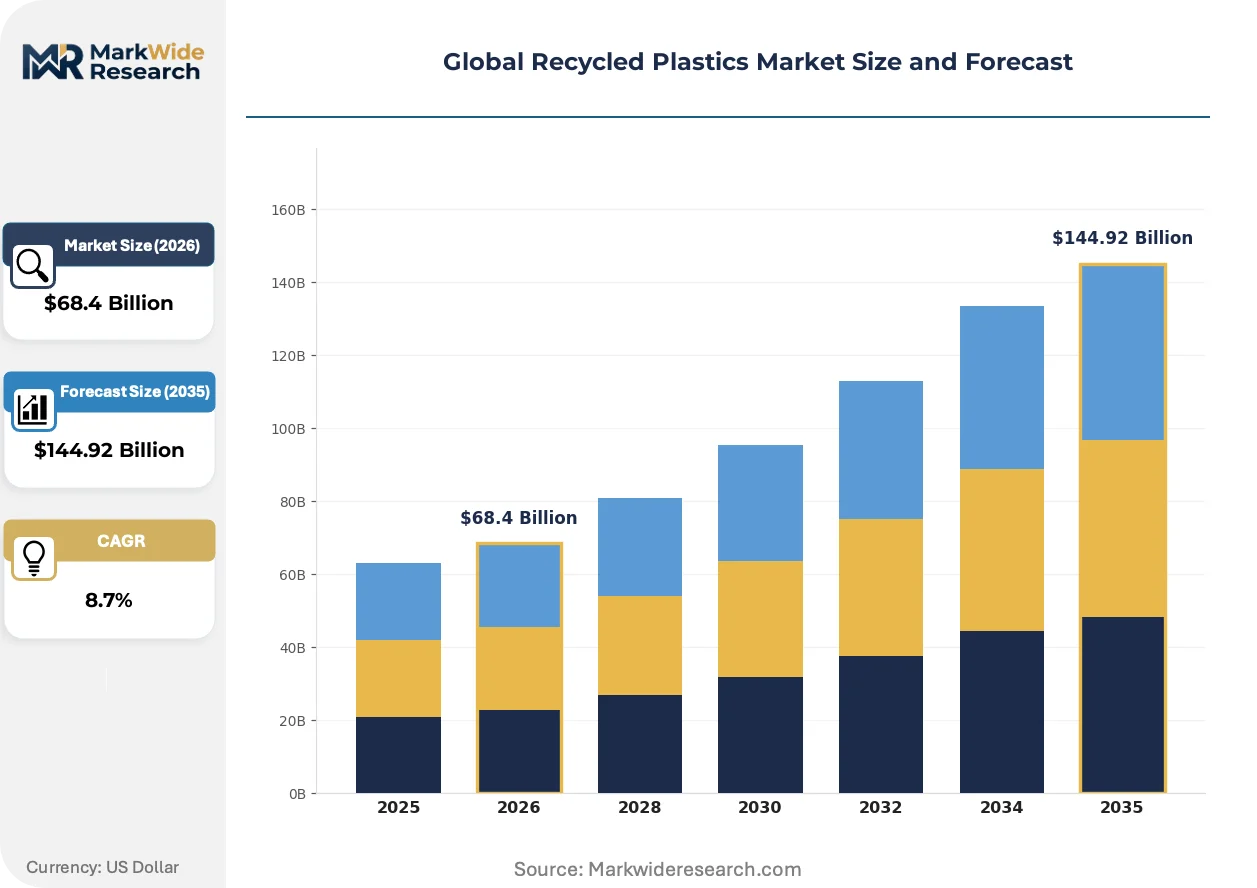
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled PET, Recycled HDPE, Recycled PVC, Recycled LDPE End User: Packaging, Textile, Automotive Components, Construction Application: Containers, Fibers, Sheets, Films Distribution Channel: Direct Sales, Online Sales, Retail, Wholesale |
| Companies Covered | Veolia, Indorama Ventures Public Company Limited, SUEZ, Republic Services, REMONDIS SE & Co. KG, Berry Global Inc., Alpek S.A.B. de C.V., Waste Connections, Clean Harbors, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recycled Plastics Market Strategic Shifts
Digital traceability platforms and advanced sorting technologies are converging to resolve contamination and provenance verification barriers that have historically limited recycled polymer adoption in premium applications.
Artificial intelligence-powered sorting systems are digitizing quality control workflows in mechanical recycling facilities. Brand owners in cosmetics and premium food packaging are requiring batch-level traceability data. This capability is digitizing supplier qualification processes and compressing approval cycles for new feedstock sources.
The EU Green Deal's packaging and packaging waste regulation is tightening recycled content mandates across member states. Extended producer responsibility schemes are shifting collection financing onto brand owners. Food and beverage multinationals are responding by pre-purchasing offtake volumes from certified recyclers to secure supply ahead of compliance deadlines.
Buyer consolidation among packaging converters is concentrating procurement leverage and demanding certificate-backed mass balance accounting. Small and mid-tier recyclers are losing shelf position to integrated waste-to-polymer platforms. This concentration is most visible in Germany and the Netherlands where converter margins are thinnest and sustainability commitments are most advanced.
Global Recycled Plastics Market Segmentation
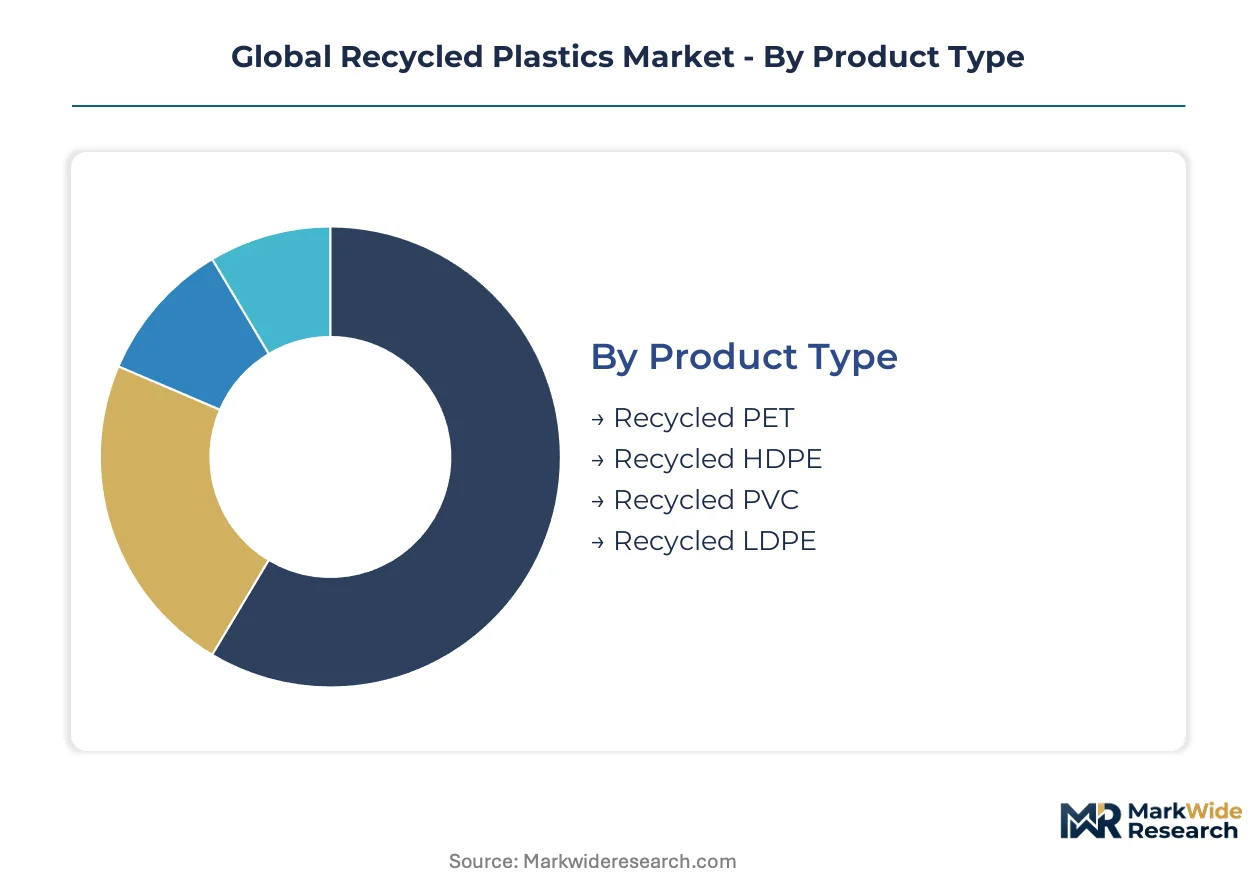
Recycled plastics procurement demands precise polymer-grade matching to virgin resin specifications. Segmentation by product chemistry, end-use durability requirements, and application form factor determines reprocessing economics and margin capture for recyclers.
Product Type:
Mature mechanical recycling infrastructure dominates commodity thermoplastics while emerging chemical recycling platforms target mixed-waste streams previously landfilled.
- Recycled PET:Post-consumer bottle flake undergoes solid-state polymerization to restore intrinsic viscosity for food-contact applications. Demand concentrates in Germany and the Netherlands where EFSA food-grade certifications and EU Green Deal mandates align procurement toward bottle-to-bottle闭环 systems.
- Recycled HDPE:Milk jug and detergent bottle feedstock yields blow-molding grades with melt flow indices of 4-10 g/10 min. Construction pipe manufacturers in the US specify recycled HDPE for drainage applications where ASTM D3350 cell classification permits partial substitution, though virgin resin price volatility compresses recycler margins during crude oil downturns.
- Recycled PVC:Window profile and cable insulation waste streams supply extrusion compounds with controlled thermal stability. Building products OEMs in France leverage REACH-registered stabilizer packages to maintain CE marking compliance.
- Recycled LDPE:Agricultural film and stretch wrap collections deliver film-grade resins for non-food packaging. E-commerce logistics demand in China sustains volume despite lightweighting pressure on film thickness specifications.
Recycled PET handles the majority of throughput; Recycled HDPE is climbing the fastest on share as automotive fuel tank specifications broaden post-consumer content tolerance.
End User:
Application durability standards create divergent procurement patterns across sectors with stringent mechanical property requirements versus those permitting broader specification ranges.
- Packaging:Beverage, food, and personal care brand owners pre-purchase certified rPET offtake volumes ahead of EU mandatory recycled content deadlines. FDA food-contact notification timelines of 18-24 months gate entry for thermoformed deli containers and trays beyond established bottle applications.
- Textile:Polyester staple fiber producers in India integrate informal sector waste picker networks to secure post-consumer PET bottle supply for textile-grade chip production. Garment export contracts to EU buyers require mass balance certification through the International Sustainability and Carbon Certification scheme.
- Automotive Components:Bumper fascias, interior trim, and under-hood applications specify recycled PP and TPO compounds with controlled impact resistance. Tier-1 suppliers negotiate closed-loop collection contracts with REMONDIS and Veolia for end-of-life vehicle dismantling feedstock.
- Construction:Drainage pipes, geomembranes, and decking profiles consume mixed-color recycled PE and PP where aesthetic uniformity is secondary to mechanical performance. German DIN standards for construction plastics permit broader recycled content tolerance than food-contact regulations.
Packaging commands the dominant procurement volume; Automotive Components is gaining share fastest as OEMs redesign specifications around circular material targets.
Application:
Form factor determines contamination sensitivity and reprocessing yield, with closed-loop bottle systems achieving higher recovery rates than diffuse film applications.
- Containers:Bottle-to-bottle recycling achieves closed-loop material flows with established collection infrastructure and food-grade certification pathways. Indorama Ventures operates multi-continent rPET capacity serving Coca-Cola and PepsiCo supply chains.
- Fibers:Textile-grade recycled PET bypasses solid-state polymerization for lower intrinsic viscosity requirements, reducing reprocessing energy intensity by approximately 30% versus bottle-grade production.
- Sheets:Thermoforming applications for deli containers and blister packs require controlled gauge tolerance and optical clarity specifications that challenge mixed-color feedstock utilization.
- Films:Stretch wrap and agricultural film recycling faces contamination from adhesives, labels, and soil loadings that degrade mechanical properties through repeated thermal cycling.
Containers maintain the steepest expansion trajectory; Films confront structural headwinds from lightweighting and collection infrastructure gaps.
Distribution Channel:
Customer scale and specification complexity determine channel selection, with integrated waste-to-polymer platforms displacing fragmented trading relationships.
- Direct Sales:Brand owners and Tier-1 converters negotiate multi-year offtake agreements with certified recyclers for batch-traceable polymer supply. Veolia's integrated platform delivers direct contracts with guaranteed food-grade certification documentation.
- Wholesale:Regional compounders and smaller converters procure mixed-color pellet through distributors when specification tolerance permits broader melt flow index ranges.
- Online Sales:Digital marketplaces for recycled plastics remain nascent, limited by sample qualification requirements and quality consistency verification challenges.
- Retail:Hobbyist and small-batch processors purchase regrind through specialized distributors serving 3D printing filament and craft material segments.
Direct Sales captures the dominant transaction value; Wholesale maintains volume leadership among mid-tier processors lacking dedicated procurement teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports food-grade recycled PET compounds to Dutch and French packaging converters under EU Green Deal compliance contracts. This trade corridor concentrates technical certification capacity and pre-validated supply chains.
Germany
Automotive OEMs in Stuttgart and Munich specify post-consumer PP for bumper-to-bumper recovery programs. The EU Green Deal mandates 25% recycled content in plastic packaging by 2025. The Rhine-Ruhr corridor clusters mechanical recycling infrastructure and pyrolysis pilot plants around Cologne and Düsseldorf.
United States
Beverage brand owners pre-purchase rPET offtake volumes ahead of state-level extended producer responsibility deadlines. FDA food-contact notification requirements gate entry for thermoformed deli containers beyond bottle applications. The Gulf Coast petrochemical corridor hosts chemical recycling scale-up projects targeting mixed-waste feedstocks.
China
E-commerce logistics demand sustains recycled LDPE stretch wrap volumes despite lightweighting pressure. GB standards for plastics recycling quality determine export eligibility for Southeast Asian processors. The Yangtze River Delta concentrates textile-grade rPET chip production for garment export contracts.
India
Polyester staple fiber producers integrate informal sector waste picker networks for post-consumer PET bottle supply. The country's national standards body certifies recycled polymer grades for domestic packaging use. Gujarat hosts mechanical recycling clusters serving export-oriented textile manufacturers.
Netherlands
Packaging converters in Rotterdam and Amsterdam demand mass balance certification through third-party verification schemes. Extended producer responsibility financing shifts collection costs onto brand owners. The Port of Rotterdam serves as a European entry point for chemically recycled polymer imports.
Global Recycled Plastics Market Competitive Environment
Channel-controlling players compete with product-specialist players for procurement relationships with brand owners and Tier-1 converters. The market exhibits tiered consolidation around integrated waste-to-polymer platforms and regional mechanical recycling specialists. Three archetypes dominate: waste management conglomerates with captive polymer assets, petrochemical majors with backward integration into chemical recycling, and independent compounders serving construction and automotive specification markets. Dominant competitive moves include multi-year offtake agreement pre-emption and geographic clustering near feedstock collection density.
Among integrated waste-to-polymer platforms, Veolia represents the channel-controlling archetype through its European sorting and reprocessing asset network. Indorama Ventures Public Company Limited anchors the petrochemical-backward-integration tier with multi-continent rPET capacity. REMONDIS SE & Co. KG exemplifies the closed-loop collection specialist model through automotive and electronics OEM contract structures.
| Leading Market Players |
|---|
| Veolia |
| Indorama Ventures Public Company Limited |
| SUEZ |
| Republic Services |
| REMONDIS SE & Co. KG |
| Berry Global Inc. |
| Alpek S.A.B. de C.V. |
| Waste Connections |
| Clean Harbors, Inc. |
| Others |
Value Chain & Pricing Dynamics
Virgin resin price volatility determines both pricing tier spreads and supply chain shape across recycled plastics procurement. When crude oil benchmarks drop below collection and reprocessing cost thresholds, mechanical recyclers in Germany and the Netherlands face immediate margin compression while chemical recycling projects stall on feedstock economics.
Pricing Analysis
The mechanical-to-chemical recycling pricing gap stratifies procurement across three performance tiers. Food-grade rPET certified under EFSA and FDA notification pathways commands premium positioning over mixed-color mechanical grades for non-food packaging. Cost compression in standard-grade recycled HDPE intensifies as Gulf Coast virgin polyethylene expansions reset benchmark pricing. Brand owners with EU Green Deal compliance deadlines exhibit lowest price sensitivity, while construction pipe converters in the US demonstrate highest elasticity to virgin resin fluctuations.
Supply Chain Analysis
Post-consumer PET bottle collections in Germany, the Netherlands, and the United States anchor upstream feedstock availability for food-grade recycling. Pyrolysis oil and depolymerization monomers draw from mixed-waste streams previously landfilled, resting on chemical recycling scale-up economics. Single-source vulnerability concentrates in Rhine-Ruhr corridor mechanical recycling clusters where technical talent and EFSA certification capacity co-locate. Distribution runs through multi-year offtake agreements between integrated waste-to-polymer platforms and packaging converters, displacing spot-market trading relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Recycled Plastics Market sits at a platform-economics inflection where digital traceability systems and mass balance certification schemes are creating interoperability standards that will determine which recyclers capture brand owner procurement relationships.
For Market Incumbents: Harden defensive positions through backward integration into collection infrastructure and captive chemical recycling capacity additions in the Rhine-Ruhr corridor. Veolia and REMONDIS demonstrate how closed-loop contracts with automotive OEMs create switching costs that emerging entrants cannot replicate. EFSA food-grade certification investments represent the priority lever for premium packaging segment retention against pyrolysis-based competitors. For New Entrants and Emerging Players: India's informal sector waste picker networks represent the most penetrable entry point for post-consumer PET feedstock formalization at scale. Chemical recycling pilot partnerships with Port of Rotterdam import terminals offer second-mover positioning in European food-grade supply chains. Direct-to-brand digital traceability platforms provide the essential go-to-market angle for bypassing incumbent converter relationships. For Investors and Strategic Acquirers: EU Green Deal mandatory recycled content thresholds reshape the acquisition landscape toward integrated waste-to-polymer platforms with pre-validated certification pathways. Five-to-ten year viability favors operators with dual mechanical and chemical recycling technology exposure rather than single-technology pure-plays. The signal to watch is FDA food-contact notification approval velocity for thermoformed packaging applications beyond bottle-grade rPET.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Pyrolysis commercialization unlocks mixed-waste streams for virgin-quality polymer supply. |
| Food-Grade Certification Investment | EFSA and FDA notifications gate premium packaging procurement from Coca-Cola and PepsiCo supply chains. |
| Closed-Loop Collection Contracts | Automotive OEM direct agreements with REMONDIS secure end-of-life vehicle dismantling feedstock. |
| Digital Traceability Platform Deployment | Batch-level provenance verification compresses brand owner supplier qualification cycles. |
| Backward Integration into Sorting Infrastructure | Near-infrared spectroscopy capacity captures feedstock quality premiums in Germany's Rhine-Ruhr corridor. |
Study Parameters
Operator-level perspectives from recycling plant managers, packaging converter procurement leads, automotive Tier-1 supplier sustainability officers, and chemical recycling R&D directors anchored the qualitative base. Secondary validation drew from EU Green Deal regulatory filings, EFSA food-contact notification databases, FDA submission records, and European waste management operator disclosures. Bottom-up feedstock flow modeling and top-down polymer demand projections were triangulated against customs trade data and mechanical recycling facility capacity registers.
Scenario-bracketing framed the analytical approach across the projection horizon, with conservative and aggressive chemical recycling penetration assumptions bounding mechanical recycling market share trajectories. Segmentation dimensions included polymer chemistry grade, end-use durability requirements, application form factor, and regional regulatory cluster. CAGRs were derived from installed capacity expansion schedules, EPR scheme implementation timelines, and virgin resin price elasticity coefficients specific to packaging and automotive procurement patterns.
Practitioners should monitor crude oil benchmark movements, pyrolysis plant commissioning announcements, and EU member state EPR enforcement intensity for early signals requiring forecast revision. Cross-checking against European Plastics Association production statistics and national waste characterization studies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Plastic Compounds Market