
 Solder Resist for Inkjet Printer Market | 2026-2036
Solder Resist for Inkjet Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Solder Resist for Inkjet Printer Market Insights
High-resolution specification tiers is reorganizing procurement priorities among advanced PCB fabricators. TAMURA leverages its photoresist heritage to anchor premium formulation supply for HDI substrate lines. Taiyo Holdings Co sustains broad geographic coverage through integrated resin synthesis and regional compounding assets. Shenzhen RongDa Photosensitive Science & Technology Co competes on domestic scale within China's PCB manufacturing belt.
Solder resist for inkjet printer denotes a photosensitive polymer coating, typically acrylic or epoxy-acrylate hybrid, jet-deposited at 15-25 micron dry-film thickness to insulate copper traces and define solderable pads on printed circuit boards. The material cures under UV-LED exposure with thermal post-bake to achieve IPC-SM-840 Class T adhesion and insulation resistance. UV-curable formulations lead the product type landscape due to instant cure speed matching high-throughput inkjet heads. Water-based chemistries represent the fastest-expanding formulation cluster as VOC emissions rules tighten across manufacturing jurisdictions. Circuit boards dominate application demand, though automotive electronics commands the thickest margin pools owing to AEC-Q100 thermal cycling requirements.
EPA air quality standards and OSHA permissible exposure limits for solvent vapors constrain solvent-based formulation production in US facilities. REACH substance restrictions and RoHS substance bans in Europe eliminate legacy lead-bearing and certain phthalate plasticizer chemistries from import-qualified supply. China's GB standards and MEE environmental enforcement impose comparable VOC caps on domestic inkjet solder resist manufacturing. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation fragmentation that would fragment inventory and compliance costs.
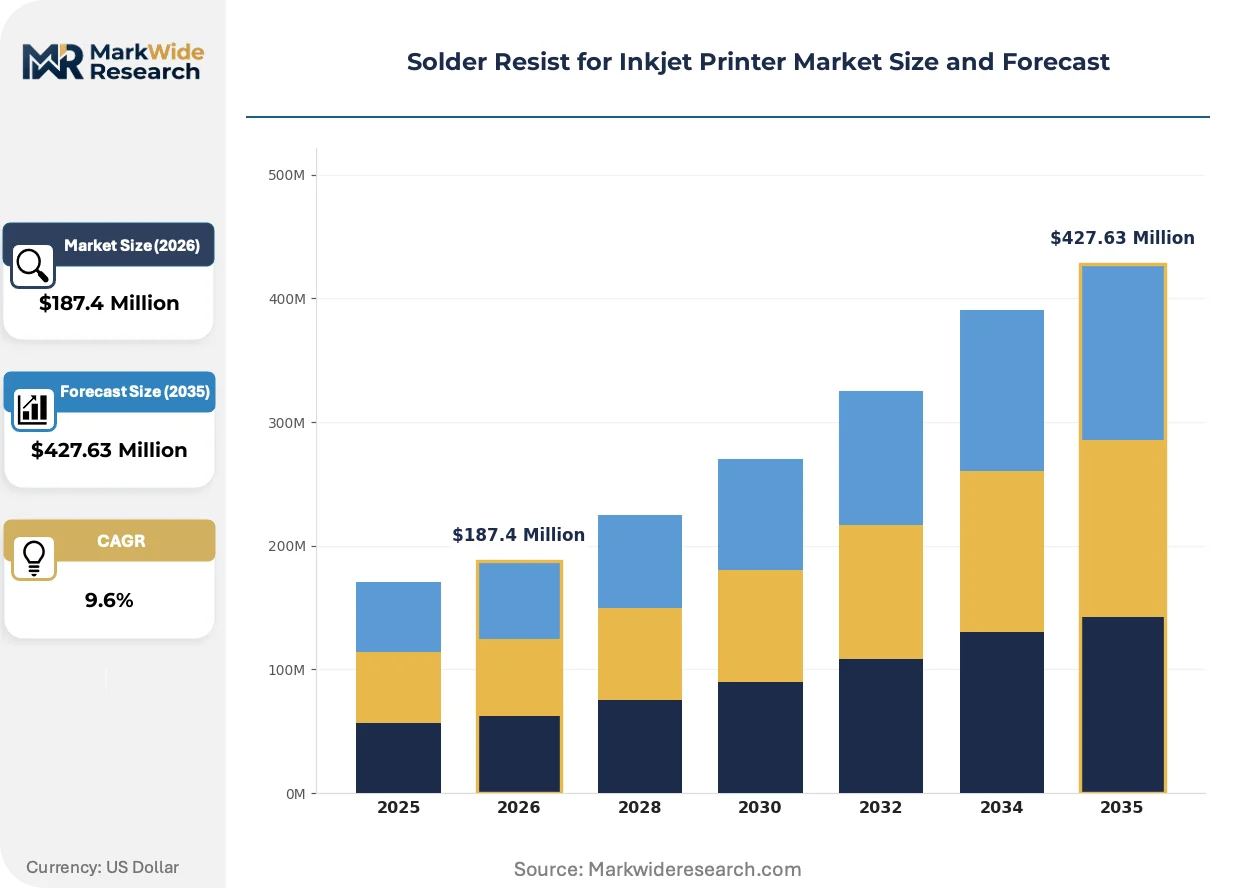
Market Dynamics
Direct imaging inkjet deposition is compressing traditional screen-printing capacity cycles across high-density interconnect fabrication, forcing reformulation pipelines to prioritize sub-20 micron resolution and UV-LED cure compatibility.
Growth Catalysts
- RoHS substance bans:European electronics manufacturers are eliminating legacy lead-bearing solder resists from qualified supplier lists, redirecting procurement toward compliant inkjet formulations.
- Automotive AEC-Q100 thermal cycling requirements:Tier-1 PCB suppliers serving electric vehicle inverters and battery management systems are mandating enhanced adhesion grades that inkjet deposition achieves more consistently than screen printing.
- Taiwan PCB cluster concentration:Fabricators in Hsinchu and Taoyuan are converting sequential lamination lines to inkjet resist systems to accommodate microvia densities exceeding 150 per square centimeter.
Market Restraints
- Acrylate monomer cost volatility:Epoxy-acrylate hybrid formulations depend on specialized oligomer feedstocks whose pricing fluctuates with petrochemical capacity utilization.
- Single-source photoinitiator supply:Japanese and German specialty chemical producers control 80 percent of Type I cleavage photoinitiator output for UV-curable inks.
- Substrate warpage sensitivity:Inkjet solder resist requires planarization precision that thin-core substrate materials below 0.4 millimeter thickness struggle to maintain during thermal post-bake.
Strategic Opportunities
- India PCB fabrication underpenetration:Domestic electronics manufacturing incentives are attracting substrate producers to Gujarat and Tamil Nadu who lack legacy screen-printing infrastructure.
- Water-based formulation regulatory tailwind:China's MEE VOC enforcement is accelerating domestic qualification of aqueous inkjet chemistries that bypass solvent-based emission caps.
- UV-LED and thermal post-bake convergence:Integrated cure systems combining instant UV pinning with precision oven baking are enabling single-pass processing that halves floor space requirements.
Industry Challenges
- IPC-SM-840 Class T certification timelines:New inkjet formulations require 12-18 months of qualification testing across multiple fabricator sites before volume procurement authorization.
- Head maintenance technician scarcity:Piezoelectric inkjet array calibration and nozzle recovery protocols demand specialized training that vocational programs have not yet standardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solder Resist for Inkjet Printer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Free, Green Solder, Epoxy-Based, UV-Curable Formulation: Single Component, Two Component, Water-Based, Solvent-Based Application: Circuit Boards, Electronic Components, Automotive Electronics, Consumer Electronics End User: OEMs, Contract Manufacturers, Repair Service Providers, Hobbyists |
| Companies Covered | TAMURA, Shenzhen RongDa Photosensitive Science & Technology Co, Taiyo Holdings Co, Showa Denko, Jiangsu Kuangshun, Nan Ya Plastics, Ajinomoto Fine-Techno, Peters, Agfa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solder Resist for Inkjet Printer Market Trends and Innovations
Formulation chemistry and deposition hardware are converging to enable feature sizes previously unreachable through analog masking methods, compressing the resolution gap between prototype and volume production.
UV-curable epoxy-acrylate hybrid resists are decomposing the traditional separation between solder mask and permanent legend functions by integrating jettable white and black marking layers within the same deposition sequence. Automotive PCB suppliers in Germany and Japan are adopting these dual-function formulations to consolidate process steps. The structural consequence is decomposing equipment vendor silos as inkjet head manufacturers acquire formulation capabilities.
REACH substance restrictions on certain isocyanate crosslinkers are forcing reformulation toward aliphatic urethane acrylate alternatives with equivalent hardness but modified cure kinetics. European PCB fabricators are absorbing 8-12 month requalification delays as suppliers resubmit IPC-SM-840 test data. High-frequency substrate producers serving 5G base station markets are most affected, as their impedance control requirements tolerate minimal formulation variation.
Consolidated procurement contracts are displacing spot purchasing for inkjet solder resist as tier-1 electronics manufacturing services centralize chemical supply under two-year framework agreements. Foxconn and Jabil procurement teams are mandating regional compounding capacity within 500 kilometers of fabrication sites. This pattern is most visible in East Asia, where logistics cost volatility and customs clearance uncertainty have made just-in-time chemical delivery untenable for high-volume lines.
Solder Resist for Inkjet Printer Market Segmentation
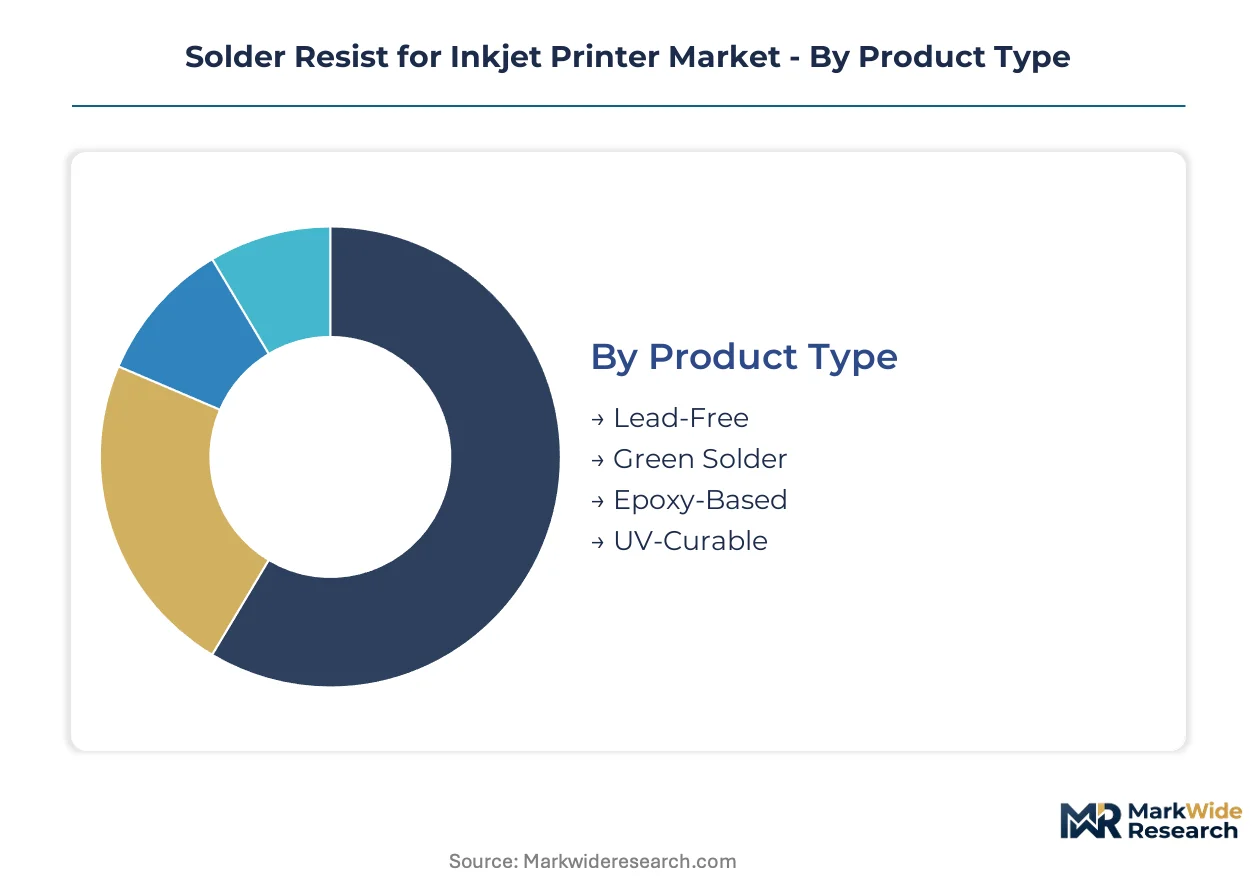
Solder resist segmentation tracks how formulation chemistry, deposition physics, and end-use reliability requirements intersect. Procurement patterns diverge sharply between high-volume consumer electronics and automotive qualification tiers.
Product Type:
Margin pools concentrate in formulations meeting dual RoHS and AEC-Q100 requirements, where certification overhead creates pricing power.
- UV-Curable:Epoxy-acrylate hybrid chemistry cures under UV-LED exposure in sub-5 second pinning cycles, matching piezoelectric inkjet throughput speeds. Taiwan PCB fabricators in Hsinchu and Taoyuan are converting sequential lamination lines to UV-curable systems to accommodate microvia densities exceeding 150 per square centimeter. This segment commands the dominant share due to instant cure speed eliminating thermal post-bake bottlenecks.
- Lead-Free:Formulations eliminate legacy tin-lead catalysts to satisfy REACH substance restrictions and RoHS substance bans across European import-qualified supply. German and Japanese automotive PCB suppliers mandate these grades for electric vehicle inverter and battery management system substrates. Lead-Free is closing the gap fastest as RoHS compliance becomes non-negotiable for tier-1 electronics manufacturing services procurement.
- Epoxy-Based:Traditional bisphenol-A epoxy backbone systems with thermal cure requirements persist in legacy fabrication lines.
- Green Solder:Low-halogen and halogen-free variants targeting JPCA-ES-01-2003 specifications for environmentally conscious electronics brands.
The dominant share belongs to UV-Curable, while Lead-Free is closing the gap fastest.
Formulation:
Water-based chemistries are expanding most quickly as China's MEE VOC enforcement and EPA air quality standards constrain solvent-based production economics.
- Water-Based:Aqueous acrylic dispersions bypass solvent emission caps under China's GB standards and EPA air quality rules, though slower ev动力学 extends drying zones. Domestic Chinese qualification is accelerating as Shenzhen and Dongguan fabricators face MEE environmental enforcement. This segment is climbing the fastest as regulatory tailwinds compound.
- Single Component:Pre-mixed, shelf-stable formulations eliminate on-site mixing errors and reduce technician training burdens for high-mix, low-volume prototype shops. Contract manufacturers in India's Gujarat and Tamil Nadu greenfield sites favor single-component simplicity where legacy screen-printing infrastructure never existed. Single Component holds the volume lead due to operational simplicity.
- Solvent-Based:Rapid-drying formulations face OSHA permissible exposure limit constraints in US facilities and REACH substance restrictions in Europe.
- Two Component:Resin-hardener systems requiring metered mixing achieve superior chemical resistance for aerospace and military IPC-SM-840 Class H grades.
Single Component formulations dominate procurement volumes, yet Water-Based alternatives are gaining share fastest under tightening emission regulations.
Application:
Automotive Electronics generates the thickest margin pools due to AEC-Q100 thermal cycling requirements and 12-18 month qualification timelines that lock out unqualified suppliers.
- Automotive Electronics:Tier-1 PCB suppliers serving electric vehicle powertrains demand enhanced adhesion grades withstanding -40°C to 150°C thermal shock. Inkjet deposition achieves more consistent thickness uniformity than screen printing for battery management system substrates. This segment captures premium pricing due to AEC-Q100 certification barriers.
- Circuit Boards:High-density interconnect fabrication for smartphones, servers, and 5G base stations drives baseline volume demand. Taiwan's Hsinchu Science Park hosts the densest concentration of inkjet resist conversion as microvia densities push beyond analog masking resolution limits. Circuit Boards anchor absolute volume consumption.
- Consumer Electronics:Wearables and hearables with flexible substrate requirements favor inkjet's non-contact deposition over screen-printing squeegee pressure.
- Electronic Components:Discrete passive components and connector housings represent opportunistic demand outside core PCB applications.
Circuit Boards command the dominant share, while Automotive Electronics is expanding most quickly as electrification multiplies PCB content per vehicle.
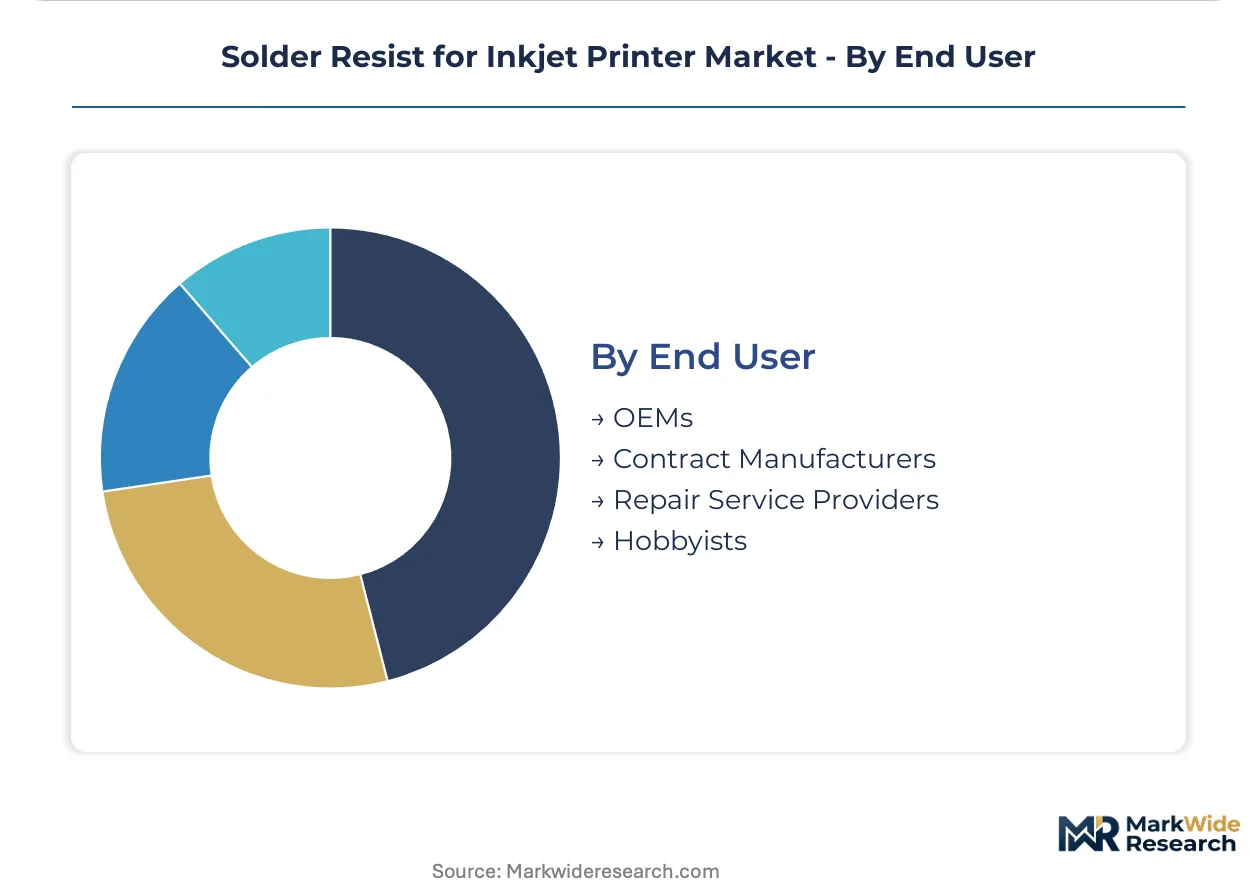
End User:
Contract Manufacturers concentrate procurement leverage through consolidated two-year framework agreements, while OEMs retain formulation specification authority.
- Contract Manufacturers:Foxconn and Jabil procurement teams mandate regional compounding capacity within 500 kilometers of fabrication sites, displacing spot purchasing with consolidated supply. East Asian logistics cost volatility and customs clearance uncertainty have made just-in-time chemical delivery untenable for high-volume lines. This segment dictates volume flows through centralized procurement.
- OEMs:Original equipment manufacturers in automotive and telecommunications specify qualified supplier lists and IPC-SM-840 Class T certification requirements that filter downstream procurement. German automotive OEMs and Japanese electronics brands maintain direct formulation approval authority over contract manufacturing partners. OEMs are tightening specification control fastest as supply chain traceability requirements expand.
- Repair Service Providers:Aftermarket rework and refurbishment operations favor small-format inkjet systems for prototype-scale solder mask repair.
- Hobbyists:Desktop PCB fabrication enthusiasts represent minimal revenue concentration but signal technology democratization trends.
Contract Manufacturers hold the dominant procurement volume, while OEMs are tightening specification control fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and Taiwanese inkjet solder resist suppliers dominate export flows into German automotive PCB fabrication and South Korean consumer electronics manufacturing. Supply corridors trace from East Asian resin synthesis clusters to European REACH-compliant formulation facilities. Cross-border chemical registration requirements are fragmenting inventory management for multinational fabricators.
China
Domestic PCB production in Shenzhen and Dongguan is absorbing water-based inkjet formulations under MEE VOC enforcement pressure. GB standards impose emission caps that solvent-based chemistries increasingly fail. The Pearl River Delta hosts the densest concentration of inkjet conversion lines as fabricators abandon screen-printing for microvia-dense substrates.
Japan
Specialty photoinitiator and oligomer production concentrates under METI industrial chemical oversight. Japanese suppliers control critical feedstock supply for UV-curable epoxy-acrylate hybrids. The Nagoya and Osaka industrial corridors anchor formulation R&D for automotive-grade solder resists meeting AEC-Q100 specifications.
Taiwan
Hsinchu Science Park fabricators are converting sequential lamination lines to inkjet resist systems exceeding 150 microvias per square centimeter. Taiwan PCB clusters lack legacy screen-printing infrastructure flexibility for high-density interconnect evolution. Taoyuan-based substrate producers are mandating regional inkjet chemical compounding within 500 kilometers.
Germany
Automotive PCB suppliers in Bavaria and Baden-Württemberg are qualifying REACH-compliant formulations eliminating isocyanate crosslinkers. KBA vehicle system regulations cascade into substrate material specifications for electric vehicle powertrains. German fabricators absorb 8-12 month requalification delays as suppliers resubmit IPC-SM-840 test data.
South Korea
Seoul Capital Area electronics manufacturing services are consolidating procurement under two-year framework agreements with regional compounding requirements. MFDS chemical substance registration applies to imported solder resist formulations. Busan-Ulsan substrate producers are adopting UV-LED cure systems for smartphone and server board lines.
Solder Resist for Inkjet Printer Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and geographic coverage dimensions. The vendor base separates into photoresist heritage conglomerates, integrated resin-to-ink compounders, and regional scale players. Three archetypes dominate: Japanese chemical conglomerates with upstream oligomer control, Taiwanese-Japanese integrated suppliers with captive resin synthesis, and Chinese domestic specialists leveraging local PCB belt proximity. Competitive moves concentrate on backward integration into photoinitiator supply and regional compounding capacity placement near fabrication clusters.
Among Japanese chemical conglomerates, TAMURA and Taiyo Holdings Co occupy positions anchored by photoresist heritage and integrated resin synthesis assets. Shenzhen RongDa Photosensitive Science & Technology Co exemplifies the Chinese domestic specialist archetype, sitting within the Pearl River Delta manufacturing belt. These three represent the competitive structure: heritage chemical conglomerates with upstream control, integrated transnational suppliers, and regional scale players serving domestic fabrication demand.
| Leading Market Players |
|---|
| TAMURA |
| Shenzhen RongDa Photosensitive Science & Technology Co |
| Taiyo Holdings Co |
| Showa Denko |
| Jiangsu Kuangshun |
| Nan Ya Plastics |
| Ajinomoto Fine-Techno |
| Peters |
| Agfa |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Japanese photoinitiator facilities anchors cost floors for UV-curable formulations, concentrating margin power among oligomer producers who control feedstock access. This scale dynamic compresses pricing flexibility for downstream compounders while amplifying procurement leverage for buyers with consolidated volume commitments.
Pricing Analysis
UV-LED cure-compatible formulations command 15-25% premiums over legacy mercury-arc chemistries, while water-based alternatives trade at modest discounts reflecting slower throughput economics. Three-tier pricing structure across AEC-Q100 automotive grades, IPC-SM-840 Class T industrial tiers, and uncertified economy formulations separates qualified from unqualified supply. Cost compression in standard-grade segments intensifies as Chinese domestic producers expand Pearl River Delta compounding capacity. Contract manufacturers exhibit highest price sensitivity due to framework agreement consolidation, whereas automotive OEMs prioritize certification reliability over unit cost.
Supply Chain Analysis
Just-in-time chemical delivery has become untenable for high-volume East Asian fabrication lines, forcing 6-8 week inventory buffers at regional compounding sites. Critical feedstock concentration rests on Japanese and German specialty chemical producers for Type I cleavage photoinitiators, with epoxy-acrylate oligomer synthesis anchored in Nagoya and Osaka industrial corridors. Single-source photoinitiator vulnerability creates structural risk exposure for UV-curable formulation supply. Distribution runs through centralized procurement contracts mandating 500-kilometer compounding proximity to fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where IPC-SM-840 Class T certification timelines create 12-18 month switching costs that entrench qualified suppliers.
For Market Incumbents: Secure captive photoinitiator supply through backward integration into Japanese or German specialty chemical assets, insulating formulation margins from oligomer cost volatility. Defend against Chinese domestic scale players by accelerating AEC-Q100 qualification pipelines for electric vehicle powertrain substrates, locking tier-1 automotive procurement before regional competitors achieve certification parity. For New Entrants and Emerging Players: Differentiate on water-based formulation regulatory compliance, targeting India's Gujarat and Tamil Nadu greenfield PCB fabrication sites where legacy screen-printing infrastructure never existed. Exploit underpenetration in Indian domestic electronics manufacturing by offering single-component aqueous chemistries that bypass MEE-style VOC enforcement complexity for new market entrants lacking environmental compliance expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated resin-to-ink compounders with regional formulation facilities adjacent to Taiwan and South Korean fabrication clusters. Long-term viability favors acquisition targets possessing captive oligomer synthesis and established IPC-SM-840 test data libraries. Monitor qualification timeline compression as the critical inflection signal—accelerated AEC-Q100 approval cycles would erode certification moats and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Japanese and German specialty chemical producers control 80% of Type I cleavage output, creating single-source vulnerability. |
| Regional Compounding Capacity Expansion | Foxconn and Jabil procurement mandates require formulation facilities within 500 kilometers of fabrication sites. |
| Water-Based Formulation Qualification | China's MEE VOC enforcement accelerates domestic adoption of aqueous chemistries bypassing emission caps. |
| AEC-Q100 Certification Investment | Automotive PCB suppliers demand enhanced adhesion grades withstanding -40°C to 150°C thermal shock cycles. |
| UV-LED Cure System Convergence | Integrated pinning and thermal post-bake systems enable single-pass processing halving floor space requirements. |
Research Methodology
A spread of perspectives from PCB fabrication plant managers, inkjet equipment engineers, specialty chemical procurement leads, and automotive electronics quality directors converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs trade data, IPC technical standards documentation, and REACH substance restriction filings anchored the quantitative framework. Bottom-up segment sizing and top-down macro triangulation cross-checked volume and value estimates.
Segmentation dimensions modeled include formulation chemistry type, cure mechanism technology, end-use reliability tier, and regional regulatory compliance cluster across the projection horizon. CAGRs derived from fitted growth curves incorporating microvia density trajectories, inkjet head throughput evolution, and automotive electrification content-per-vehicle expansion. Forecast inputs specifically tracked UV-LED adoption rates and water-based formulation qualification timelines.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, stable petrochemical feedstock pricing, and continued HDI substrate miniaturization would require recalibration. Forecasts reflect documented assumptions regarding regulatory trajectory and technology substitution patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Food Grade Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Printing Plate Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Global Digital Inks Market
Printing Inks
Commercial Printing Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Specialty Printing Consumables Market
Printing Inks
UV Cured Inks Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Rotogravure Printing Inks Market