
 Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market | 2026-2036
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market Insights
Food-contact-grade specification tiers is collapsing the historical price penalty between virgin and recycled polyolefins across European packaging supply chains. Borealis leverages its Borcycle portfolio to anchor premium resin supply for rigid food containers. LyondellBasell sustains technology leadership through its MoReTec molecular recycling platform, while SABIC competes aggressively in automotive under-the-hood applications with certified circular polypropylene grades.
Advanced-recycled polyolefin resins denote thermoplastic polymers recovered from post-consumer and post-industrial waste streams through mechanical, chemical, or solvent-based processes, achieving melt flow indices between 0.3 and 50 g/10 min and contaminant thresholds below 100 ppm for food-contact approval. These materials primarily substitute virgin polyethylene and polypropylene in applications demanding identical mechanical performance with verified recycled content. Polypropylene commands the deepest margin pool among product types due to automotive and durable goods specifications that tolerate narrower property variance. Packaging Films dominates application volume, though Automotive Components generates superior per-kilogram pricing through OEM certification requirements. Chemical Recycling technology captures investment preference where mechanical routes cannot achieve the purity thresholds mandated by EFSA and FDA for direct food contact.
The EU Green Deal's recycled content targets, enforced through ECHA REACH compliance pathways and the Packaging and Packaging Waste Regulation, compel brand owners to secure certified mass-balance resin allocations. FDA's Letter of No Objection process for chemical recycling technologies governs US market access for food-contact polyolefins, creating a dual-track compliance burden for multinational suppliers. Stakeholders must monitor whether emerging solvent-based purification technologies achieve regulatory equivalence with pyrolysis routes at lower carbon intensity before committing capital to specific technology platforms.
Market Dynamics
Pyrolysis capacity buildout in Germany, the Netherlands, and Spain is compressing the virgin-recycled polyolefin price spread by securing high-purity feedstock streams for food-contact certification. This supply concentration is forcing packaging manufacturers to lock in long-term offtake agreements before 2026 mandates take effect.
Growth Catalysts
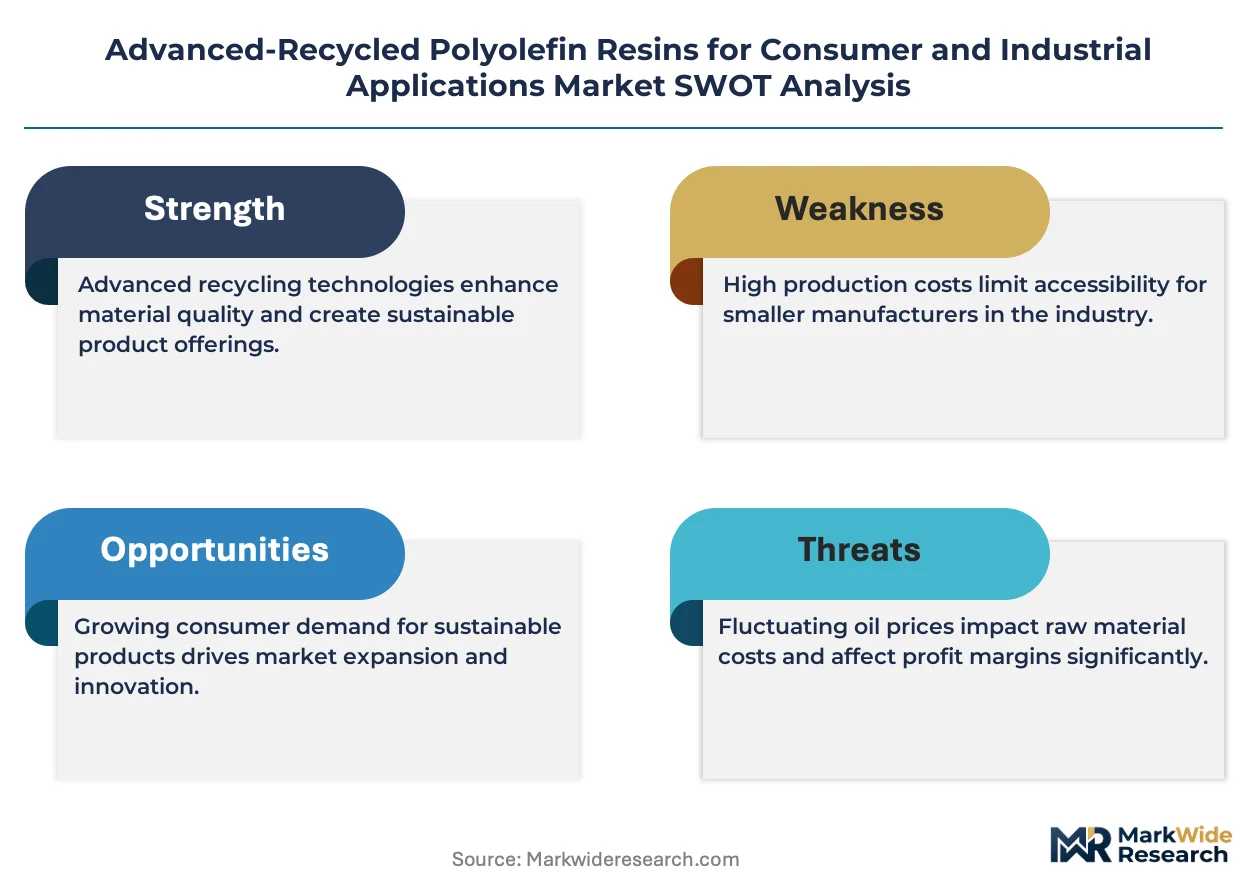
- EU Green Deal recycled content mandates:The Packaging and Packaging Waste Regulation compels brand owners to source certified mass-balance resins, creating guaranteed demand pull for chemical recycling output.
- Automotive lightweighting specifications:Under-the-hood applications tolerate narrower property variance in polypropylene, commanding premium pricing for certified circular grades with verified recycled content.
- Pyrolysis cluster formation:Concentrated chemical recycling infrastructure in Germany, the Netherlands, and Spain aggregates post-consumer waste streams into food-grade polyolefin supply.
Market Restraints
- Naphtha price volatility:Feedstock cost swings for virgin polyethylene and polypropylene production compress margins for mechanical recyclers unable to pass through input fluctuations.
- EFSA purity threshold limitations:Mechanical recycling routes cannot achieve the sub-100 ppm contaminant levels required for direct food contact, restricting addressable market scope.
- Capital intensity of chemical recycling:Pyrolysis and solvent-based purification facilities require $200-500 million per plant, concentrating supply-side ownership among integrated petrochemical majors.
Strategic Opportunities
- Solvent-based purification convergence:Emerging purification technologies paired with mechanical preprocessing promise lower carbon intensity than pyrolysis while achieving equivalent EFSA compliance.
- Automotive closed-loop programs:End-of-life vehicle recycling mandates in Germany create captive feedstock streams for circular polypropylene targeted at bumper and interior applications.
- US FDA Letter of No Objection expansion:Accelerated regulatory approvals for chemical recycling technologies unlock food-contact market access for European resin exporters.
Industry Challenges
- Mass-balance certification complexity:ISCC PLUS and RSB chain-of-custody auditing creates administrative burden for converters lacking traceability infrastructure.
- Polymer chemist scarcity:Formulation expertise for matching melt flow indices across recycled and virgin polyolefin blends concentrates among aging technical workforces in Germany and Belgium.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market |
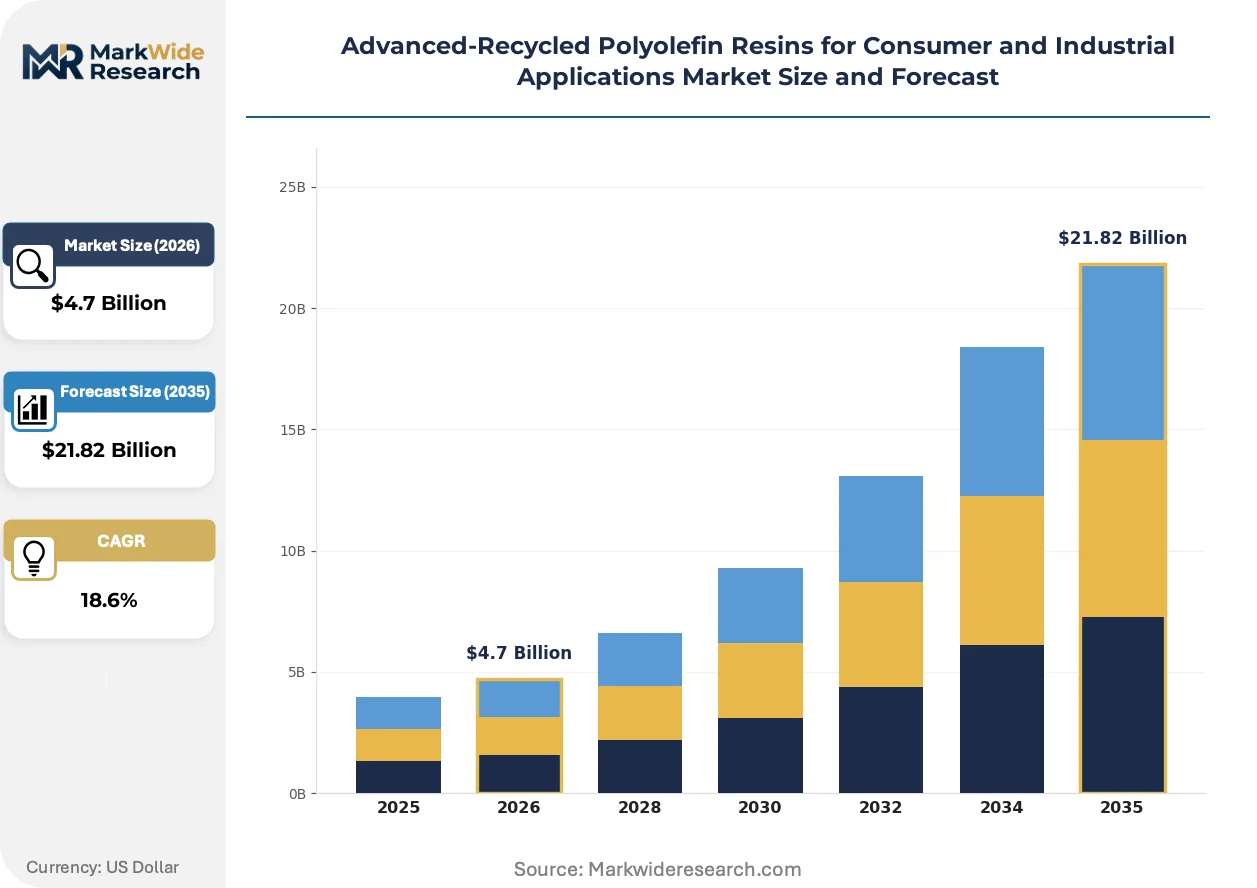
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Polyethylene, Low-Density Polyethylene, Polypropylene, Ethylene-Propylene Copolymer, Linear Low-Density Polyethylene Application: Packaging Films, Automotive Components, Electrical Housings, Construction Materials, Consumer Goods End User: Packaging Manufacturers, Automotive Suppliers, Electrical Equipment Makers, Building Material Companies, Household Product Producers Technology: Mechanical Recycling, Chemical Recycling, Solvent-based Recycling, Advanced Sorting, Compatibilization Techniques |
| Companies Covered | Borealis, LyondellBasell, SABIC, ExxonMobil, Dow, TotalEnergies, INEOS Olefins & Polymers Europe, Plastic Energy, PureCycle Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market Trends and Innovations
Chemical recycling technologies are decomposing the historical purity ceiling that restricted recycled polyolefins to non-food applications. This technological unlock is redrawing competitive boundaries between mechanical and advanced recycling routes.
Pyrolysis oil upgrading with hydrotreatment is decomposing the color and odor defects that previously limited recycled polypropylene to black or gray applications. Automotive tier-one suppliers in Germany and France are qualifying these resins for visible interior components at accelerated pace. The technology is decomposing the virgin resin incumbency in premium automotive specifications by delivering identical mechanical performance with verified circular content.
REACH compliance pathways for recycled content verification are tightening traceability requirements across European packaging supply chains. The ECHA enforcement framework now requires batch-level documentation of post-consumer waste origin for food-contact approvals. Flexible packaging converters in Italy and Spain are restructuring supplier relationships to secure ISCC PLUS certification before 2026 regulatory deadlines.
Brand owner procurement teams are consolidating resin suppliers to secure dedicated mass-balance allocations. Unilever and Nestlé packaging divisions in Germany and Switzerland are signing five-year offtake agreements directly with chemical recycling operators, bypassing traditional distributor channels. This buyer concentration is most visible in rigid food container applications where EFSA compliance creates non-substitutable supply requirements.
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market Segmentation
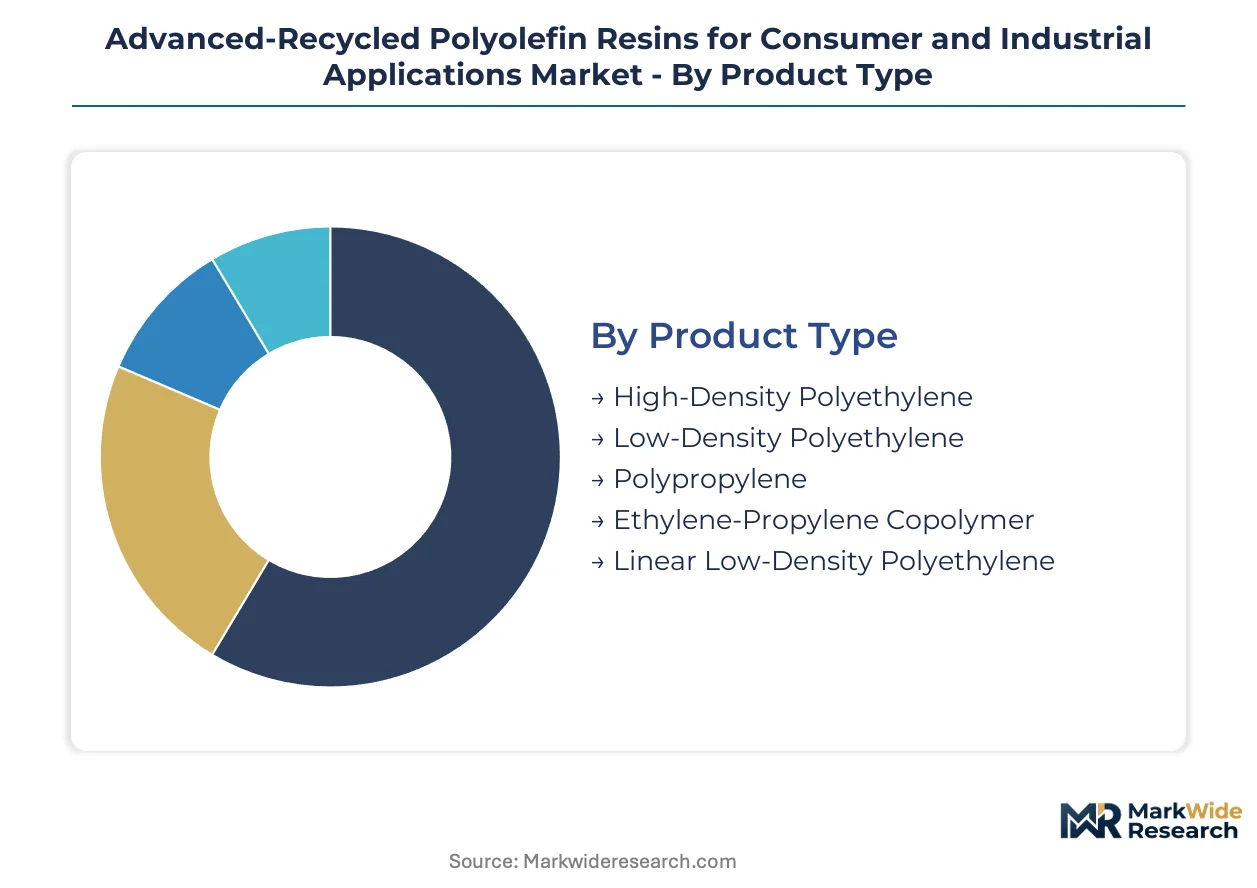
Segmentation in advanced-recycled polyolefin resins reflects divergent purity thresholds across regulatory regimes. EFSA and FDA food-contact specifications fragment product categories by achievable contaminant levels, while automotive OEM certification requirements create parallel specification tiers unrelated to packaging mandates.
Product Type:
Regulatory differentiation separates food-contact-eligible grades from industrial-only streams, with melt flow index ranges and contaminant thresholds determining addressable end-use markets.
- Polypropylene:Narrower property variance tolerance in automotive under-the-hood applications commands premium pricing for certified circular grades. German and French OEMs qualify these resins for visible interior components through pyrolysis oil upgrading with hydrotreatment.
- High-Density Polyethylene:Rigid food container specifications in European packaging supply chains demand sub-100 ppm contaminant thresholds achievable only through chemical recycling routes. Borealis anchors premium resin supply for this segment through mass-balance certified Borcycle grades.
- Low-Density Polyethylene:Flexible packaging converters in Italy and Spain restructure supplier relationships to secure ISCC PLUS certification for film-grade specifications.
- Linear Low-Density Polyethylene:Stretch film and industrial liner applications tolerate broader property variance, expanding mechanical recycling addressability.
- Ethylene-Propylene Copolymer:Automotive bumper and interior applications benefit from closed-loop end-of-life vehicle recycling mandates in Germany.
Polypropylene handles the majority of throughput; High-Density Polyethylene is gaining share fastest on food-contact certification expansion.
Application:
Cost tier differentiation separates premium-certified grades from standard industrial specifications, with per-kilogram pricing spreading widest between automotive OEM-certified and general-purpose packaging streams.
- Packaging Films:Dominates application volume across European flexible and rigid formats. EFSA compliance creates non-substitutable supply requirements, with Unilever and Nestlé packaging divisions in Germany and Switzerland signing five-year offtake agreements directly with chemical recycling operators.
- Automotive Components:Generates superior per-kilogram pricing through OEM certification requirements for under-the-hood and visible interior specifications. Tier-one suppliers in Germany and France accelerate qualification of hydrotreated pyrolysis output for color-critical applications.
- Electrical Housings:Flame-retardant specifications concentrate demand in electrical equipment maker procurement channels.
- Construction Materials:Piping and geomembrane applications tolerate broader recycled content variance, expanding mechanical recycling penetration.
- Consumer Goods:Household product producers source certified mass-balance allocations for sustainability-marketed durable goods.
Packaging Films captures the largest volume base; Automotive Components shows the steepest expansion trajectory on premium pricing and OEM circular content mandates.
End User:
Customer type concentration drives procurement consolidation, with brand owners bypassing traditional distributor channels to secure dedicated mass-balance allocations ahead of regulatory deadlines.
- Packaging Manufacturers:European flexible packaging converters face restructuring pressure as ECHA enforcement requires batch-level documentation of post-consumer waste origin for food-contact approvals. REACH compliance pathways tighten traceability requirements across supply chains.
- Automotive Suppliers:German and French tier-one suppliers qualify recycled polypropylene for visible interior components at accelerated pace, decomposing virgin resin incumbency through identical mechanical performance with verified circular content.
- Electrical Equipment Makers:Flame-retardant housing specifications create specialized demand for compatibilized recycled blends.
- Building Material Companies:Construction sector procurement tolerates broader property variance, expanding addressable supply from mechanical recycling routes.
- Household Product Producers:Sustainability-marketed durable goods drive certified mass-balance demand for non-food contact applications.
Packaging Manufacturers account for the dominant procurement volume; Automotive Suppliers are climbing the fastest on OEM certification acceleration.
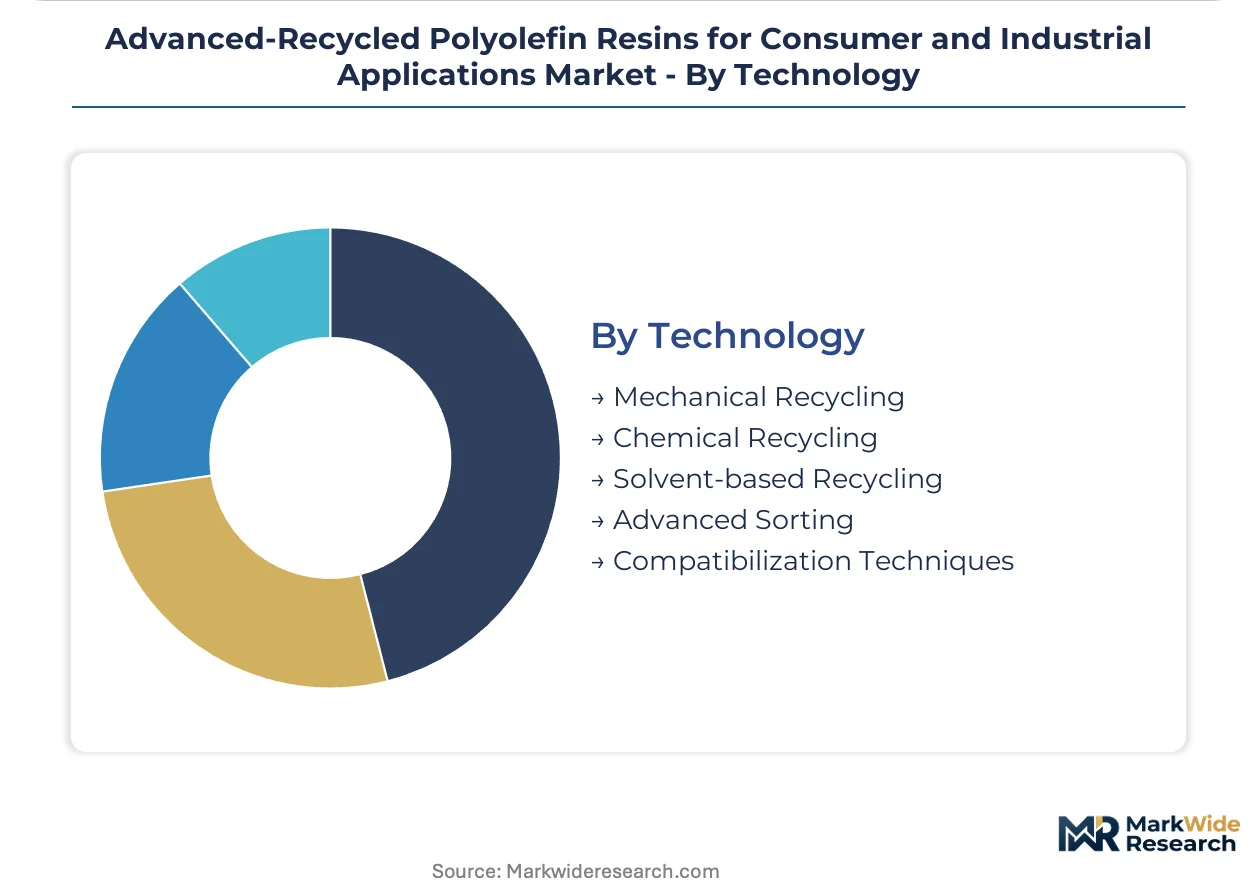
Technology:
Supply concentration in chemical recycling infrastructure determines food-contact market access, with pyrolysis clusters in Germany, the Netherlands, and Spain aggregating post-consumer waste streams into high-purity polyolefin supply.
- Chemical Recycling:Pyrolysis and solvent-based purification achieve sub-100 ppm contaminant thresholds mandated by EFSA and FDA for direct food contact. Capital intensity of $200-500 million per plant concentrates supply-side ownership among integrated petrochemical majors.
- Mechanical Recycling:Restricted to non-food applications by EFSA purity limitations, with margins compressed by naphtha price volatility in virgin polyethylene and polypropylene production.
- Solvent-based Recycling:Emerging purification technologies paired with mechanical preprocessing promise lower carbon intensity than pyrolysis while achieving equivalent EFSA compliance.
- Advanced Sorting:Near-infrared and robotics-based separation upgrades feedstock quality for downstream chemical recycling routes.
- Compatibilization Techniques:Reactive extrusion processes expand property matching between recycled and virgin polyolefin blends for automotive specifications.
Chemical Recycling commands the premium tier; Solvent-based Recycling is expanding most quickly on carbon intensity advantages and capital efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands show the least price elasticity for food-contact certified resins, while Italian and Spanish converters remain more sensitive to virgin-recycled spreads. This demand-elasticity contrast shapes regional investment patterns and offtake contracting behavior.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg drive premium demand for certified circular polypropylene under end-of-life vehicle recycling mandates. The KBA enforces traceability standards that accelerate tier-one supplier qualification of hydrotreated pyrolysis output. Pyrolysis clusters in the Cologne-Leverkusen corridor aggregate post-consumer waste streams into food-grade polyolefin supply for rigid container manufacturers.
Netherlands
Rotterdam's petrochemical infrastructure anchors chemical recycling capacity buildout targeting EFSA-compliant resin output. The country's national environmental regulator enforces REACH compliance pathways that exceed baseline EU requirements for batch-level documentation. Port-centric logistics enable integrated pyrolysis-upgrading operations serving German and Belgian packaging converters.
Spain
Flexible packaging manufacturers in Catalonia and Valencia restructure supplier relationships to secure ISCC PLUS certification ahead of 2026 regulatory deadlines. The Spanish food safety agency enforces ECHA-derived purity thresholds that restrict mechanical recycling to non-food applications. Barcelona-Tarragona chemical complexes concentrate solvent-based purification pilot capacity.
United States
Food-contact market access hinges on FDA Letter of No Objection approvals for chemical recycling technologies, creating a dual-track compliance burden for European resin exporters. Gulf Coast petrochemical corridors leverage existing steam cracker infrastructure for pyrolysis oil co-processing. Texas and Louisiana-based converters evaluate mass-balance certification adoption as brand owner procurement teams consolidate supplier bases.
China
Mechanical recycling dominates current output, with Yangtze River Delta processors expanding sorting and compatibilization capacity for industrial-grade polyolefin streams. The Ministry of Ecology and Environment enforces dual carbon goals that favor lower-carbon-intensity recycling routes over virgin production expansion. Shanghai and Jiangsu province clusters concentrate advanced sorting technology deployment for feedstock quality upgrading.
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in this market. Integrated petrochemical majors control pyrolysis capacity through capital-intensive facility ownership, while specialized technology developers advance solvent-based purification at lower carbon intensity. Three archetypes dominate: mass-balance certified resin suppliers, pyrolysis technology licensors, and mechanical recycling operators with upgrading partnerships. Competitive moves concentrate on long-term offtake contracting and backward integration into waste feedstock aggregation.
Among European integrated petrochemical majors, Borealis, LyondellBasell, and SABIC occupy positions representing distinct strategic emphases. Borealis exemplifies the mass-balance certification anchor through its Borcycle portfolio. LyondellBasell represents technology-forward positioning through molecular recycling platform development. SABIC sits within the automotive-specialist tier, competing aggressively in under-the-hood applications with certified circular polypropylene grades.
| Leading Market Players |
|---|
| Borealis |
| LyondellBasell |
| SABIC |
| ExxonMobil |
| Dow |
| TotalEnergies |
| INEOS Olefins & Polymers Europe |
| Plastic Energy |
| PureCycle Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements lock in both supply access and price visibility for European packaging manufacturers racing to secure EFSA-compliant resin allocations before EU Green Deal mandates activate. These contracts compress virgin-recycled price spreads by removing spot-market volatility for food-contact certified grades.
Pricing Analysis
EU Green Deal recycled content mandates dictate the pricing tier structure across European polyolefin supply chains. Three-tier pricing structure across premium, standard, and economy levels separates mass-balance certified food-contact grades from industrial-only mechanical recycling streams. Cost compression in standard-tier mechanical recycling is intensifying because naphtha price volatility in virgin production limits margin pass-through. Packaging manufacturers in Italy and Spain show highest price sensitivity, while German automotive OEMs accept premium pricing for certified circular polypropylene with verified property variance tolerance.
Supply Chain Analysis
Inventory lead times stretch longest for hydrotreated pyrolysis output destined for visible automotive interior applications. Supply concentrates in Germany, the Netherlands, and Spain where pyrolysis clusters aggregate post-consumer waste into food-grade polyolefin streams. Feedstock draws from mixed plastic waste bales, pyrolysis oil intermediates, and solvent-purified polymer streams. Single-source vulnerability runs through Rotterdam's port-centric logistics hub serving German and Belgian converters. Distribution runs through direct manufacturer-to-brand owner channels, bypassing traditional resin distributors as Unilever and Nestlé procurement teams consolidate supplier bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against virgin polyolefin incumbency reinforced by petrochemical majors with integrated cracker infrastructure. Incumbents must navigate the threat of solvent-based purification technologies achieving EFSA equivalence at lower carbon intensity than pyrolysis.
For Market Incumbents: Shield mass-balance certification premiums by accelerating backward integration into waste feedstock aggregation before solvent-based competitors achieve scale. Secure long-term pyrolysis capacity reservations in the Cologne-Leverkusen corridor. Invest in hydrotreatment upgrading to defend against color-critical automotive specifications shifting toward lower-carbon alternatives. For New Entrants and Emerging Players: Differentiate on carbon intensity metrics by pairing mechanical preprocessing with emerging solvent purification routes targeting Italian and Spanish flexible packaging converters. Target the solvent-based recycling segment where capital efficiency advantages promise faster payback than pyrolysis. Pursue ISCC PLUS certification partnerships with established mechanical recyclers lacking food-contact upgrade pathways. For Investors and Strategic Acquirers: Capital is best deployed toward technology licensors with proven solvent-based purification pilots rather than capital-intensive pyrolysis operators. The five-to-ten year viability window favors platforms achieving regulatory equivalence with lower carbon footprints. Watch for FDA Letter of No Objection expansions as the inflection signal unlocking US market access for European technology exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waste Aggregation | Secures captive feedstock streams for chemical recycling operators facing post-consumer plastic bale competition. |
| Hydrotreatment Capacity Expansion | Enables color-critical automotive interior qualifications that decompose virgin polypropylene incumbency. |
| ISCC PLUS Certification Investment | Unlocks brand owner procurement channels requiring batch-level traceability documentation under ECHA enforcement. |
| Solvent-Based Purification Pilot Scale-Up | Positions emerging technology developers to capture carbon-conscious packaging manufacturers in Southern Europe. |
| Long-Term Offtake Agreement Structuring | Locks in volume commitments from Nestlé and Unilever packaging divisions ahead of 2026 regulatory deadlines. |
Research Methodology
The analysis maps chemical recycling, mechanical recycling, solvent-based purification, and advanced sorting sub-sectors, each validated through primary interviews with plant operations directors, procurement leads at automotive tier-one suppliers, flexible packaging converters, and ECHA regulatory affairs specialists. Secondary sources include customs and trade data on polyolefin resin flows, Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and ISCC PLUS certification registries. Bottom-up capacity buildout tracking triangulates against top-down demand modeling from packaging and automotive end-use sectors.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework models segmentation by product type, application, end user, and technology platform, with additional dimensioning by regional regulatory cluster. CAGRs derive from capacity expansion timelines, regulatory mandate phase-in schedules, and substitution elasticity estimates for virgin resin displacement. Forecast inputs incorporate pyrolysis oil upgrading yield rates and EFSA contaminant threshold compliance probabilities.
Forecasts assume regulatory continuity in EU REACH, EFSA food-contact, and FDA Letter of No Objection regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market