
 Global Recycled PET (R-PET) Bottles Market | 2026-2036
Global Recycled PET (R-PET) Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recycled PET (R-PET) Bottles Market Foresight
Food-grade pellet specification is unwinding competitive dynamics across the R-PET bottles landscape. Indorama Ventures Public Company Limited leverages its integrated PET resin and recycling footprint to secure virgin-quality flake supply. Plastipak Holdings anchors North American beverage contracts through proprietary bottle-to-bottle processing technology. ALPLA Werke Alwin Lehner GmbH & Co KG dominates European pharmaceutical and cosmetic packaging with multi-site extrusion blow molding capability.
Recycled PET (R-PET) bottles are manufactured from post-consumer polyethylene terephthalate flake that undergoes hot caustic washing, optical sorting, and solid-state polymerization to achieve intrinsic viscosity above 0.80 dL/g for carbonated beverage pressure retention. The primary commercial purpose is to replace virgin PET in closed-loop packaging while meeting FDA and EFSA food-contact safety thresholds. Food-grade R-PET commands the deepest margin pool as beverage manufacturers face binding recycled content mandates, while textile-grade supply competes with fiber producers for flake feedstock. Bottles remain the dominant product form, though sheet and thermoformed container segments absorb lower-intrinsic-viscosity output from mixed-color collection streams.
The EU F-Gas Regulation and REACH compliance frameworks constrain mechanical recycling additives, while FDA letters of no objection govern food-contact R-PET legitimacy in the United States. China's SAMR enforces GB standards for recycled plastics in domestic packaging, creating divergent certification burdens for multinational converters. Stakeholders must monitor how chemical recycling scale-up alters mechanical recyclers' feedstock access and pricing power in tight food-grade markets.
Market Dynamics
The EU Single-Use Plastics Directive's recycled content mandates are compressing food-grade R-PET availability, forcing beverage converters to secure multi-year flake supply contracts ahead of mechanical recycling capacity expansion.
Growth Catalysts
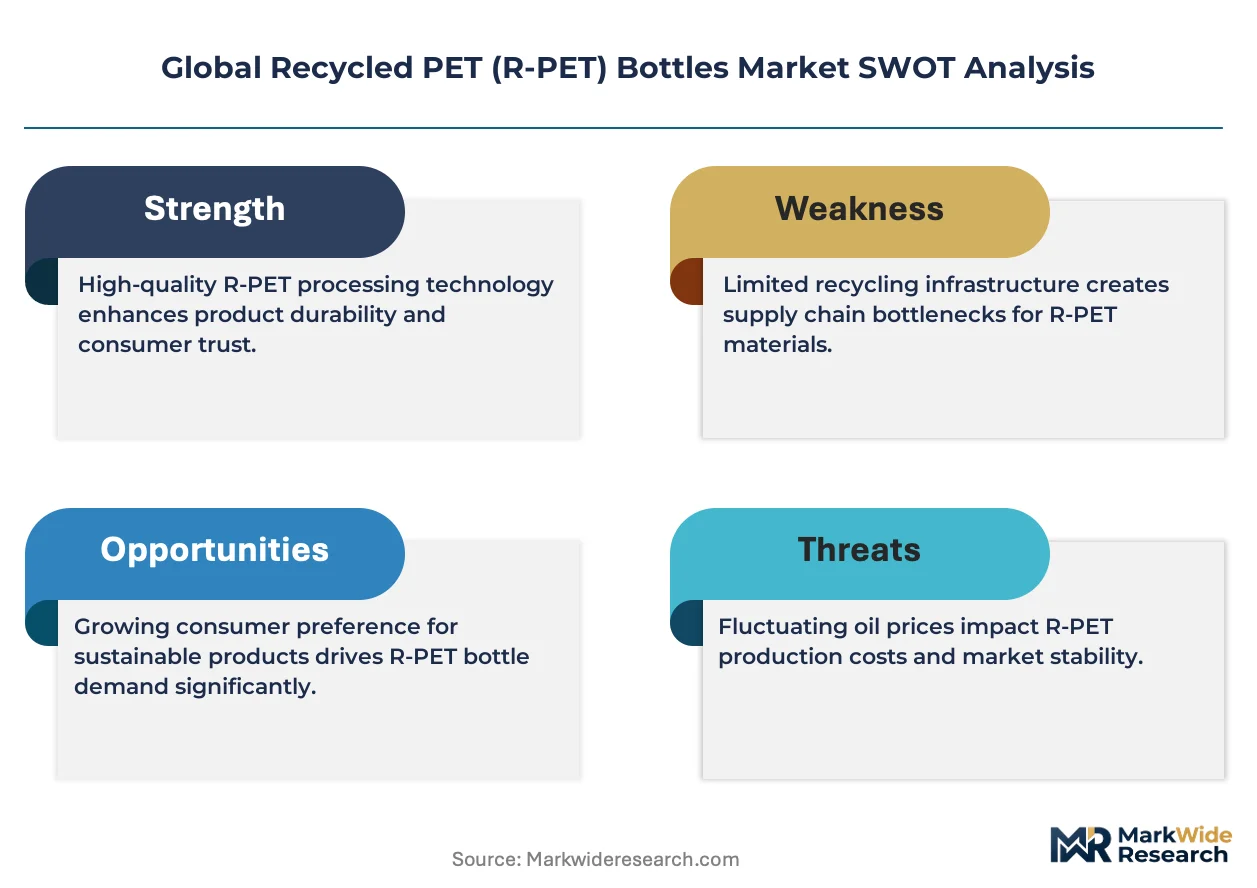
- Binding recycled content thresholds:The EU Single-Use Plastics Directive mandates minimum recycled plastic in beverage bottles, creating guaranteed offtake for food-grade R-PET processors.
- Reverse vending infrastructure:Germany's deposit-return system captures over 90% of PET bottles, generating the continent's highest-quality post-consumer feedstock stream for bottle-to-bottle recycling.
- Hot caustic washing advancement:Improved decontamination protocols now achieve FDA and EFSA food-contact safety thresholds without solid-state polymerization, lowering capital barriers for mechanical recyclers.
Market Restraints
- Flake feedstock cost volatility:Post-consumer PET bale prices swing with virgin PET resin naphtha spreads, squeezing mechanical recycler margins when oil prices collapse.
- German supply concentration:Europe's tightest food-grade R-PET market concentrates premium flake output in Bavarian and Rhineland-Palatinate collection zones, creating geographic single-source risk.
- Chemical recycling feedstock competition:Pyrolysis and glycolysis operators now bid for the same clear/blue bale streams, diverting material from established mechanical processors.
Strategic Opportunities
- Underpenetrated US Gulf Coast:Texas and Louisiana lack bottle-to-bottle recycling infrastructure despite massive beverage production, creating greenfield project potential.
- Cosmetic and pharmaceutical packaging:EFSA-compliant R-PET commands premium pricing in personal care segments not yet bound by beverage-sector mandates.
- China's GB standards evolution:SAMR's tightening domestic recycled plastics regulations may open food-grade R-PET import windows as local mechanical recyclers struggle with contamination control.
Industry Challenges
- Optical sorting technician scarcity:Near-infrared spectroscopy calibration requires specialized skills rarely taught in polymer engineering programs, slowing plant commissioning.
- Solid-state polymerization capex intensity:Achieving 0.80 dL/g intrinsic viscosity for carbonated beverage bottles requires energy-intensive SSP reactors with 5-7 year payback periods.
- FDA letter of no objection timelines:US food-contact notifications for novel decontamination technologies face 12-18 month review queues, delaying commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recycled PET (R-PET) Bottles Market |
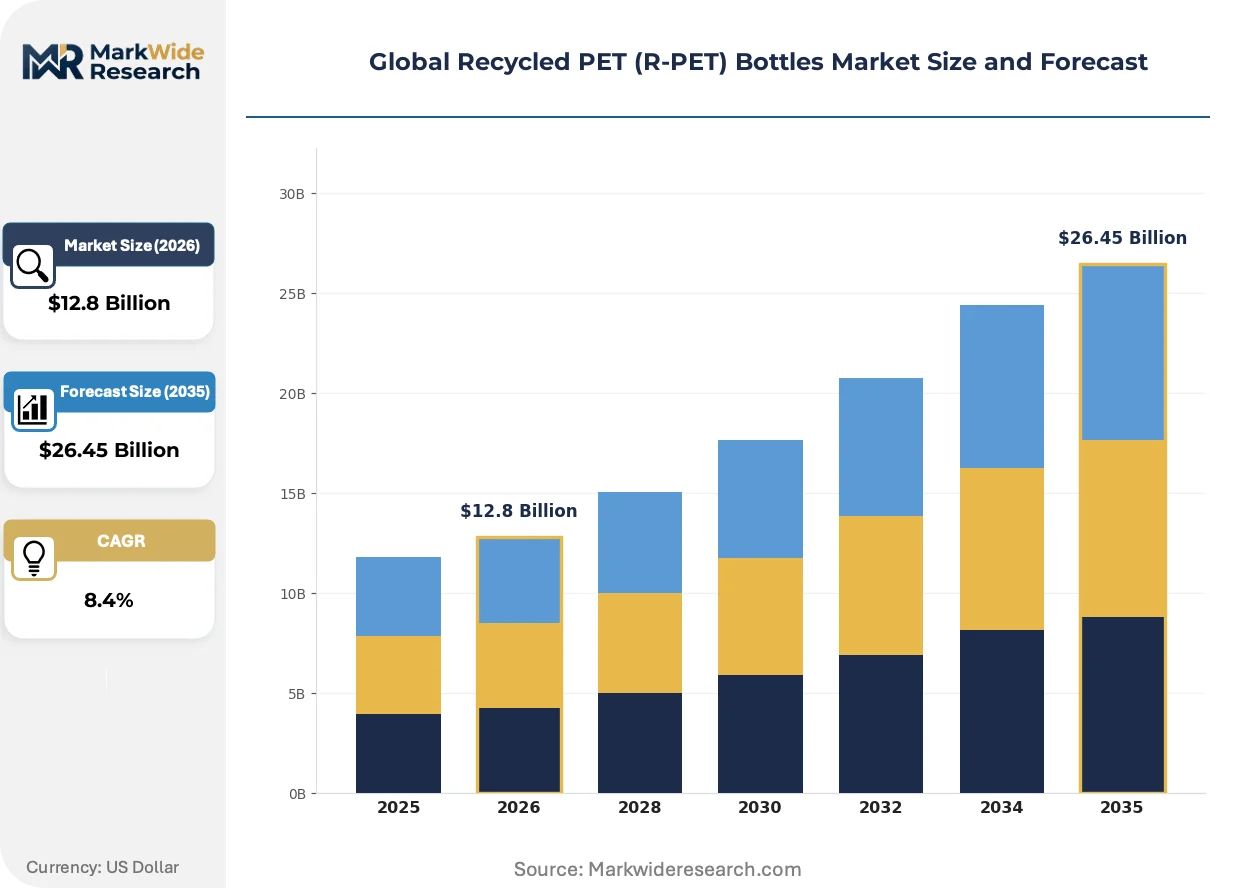
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Films, Sheets Grade: Food Grade, Textile Grade, Cosmetic Grade, Pharmaceutical Grade Application: Beverages, Personal Care, Household Cleaners, Food Packaging, Industrial Chemicals End User: Beverage Manufacturers, Cosmetic Brands, Textile Companies, Chemical Producers, Food Processors |
| Companies Covered | Indorama Ventures Public Company Limited, Plastipak Holdings, CarbonLITE Industries, ALPLA Werke Alwin Lehner GmbH & Co KG, Phoenix Technologies International, Evergreen Plastics, Vanden Global, UltrePET, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recycled PET (R-PET) Bottles Market Shifts & Advancements
Advanced decontamination technologies and regulatory tightening are reshaping competitive advantage toward integrated resin-recycling operations with captive bottle-to-bottle supply chains.
Advanced glycolysis depolymerization is displacing conventional mechanical recycling for colored and contaminated feedstocks previously relegated to fiber applications. Beverage brand sustainability officers are fast-tracking chemical recycling offtake agreements to meet 2030 recycled content pledges without sacrificing bottle clarity. This technology is displacing lower-margin sheet and strapping applications as the preferred sink for mixed-color PET bales.
REACH compliance frameworks now restrict mechanical recycling additives used for odor and color control, forcing converters to reformulate washing protocols. The ECHA restriction on certain stabilizers has triggered capital upgrades across European mechanical recycling plants. Food-grade bottle processors in Germany and France are responding by installing additional hot caustic washing stages to achieve purity without prohibited chemical aids.
Brand-led bottle-to-bottle procurement mandates are consolidating converter relationships around multi-year supply agreements with fixed flake price collars. Major beverage bottlers are bypassing spot markets to lock in decade-long food-grade R-PET volumes directly with integrated resin producers. This pattern is most visible in North America, where Coca-Cola and PepsiCo sustainability targets have compressed the supplier base to vertically integrated processors with proprietary collection infrastructure.
Global Recycled PET (R-PET) Bottles Market Segmentation
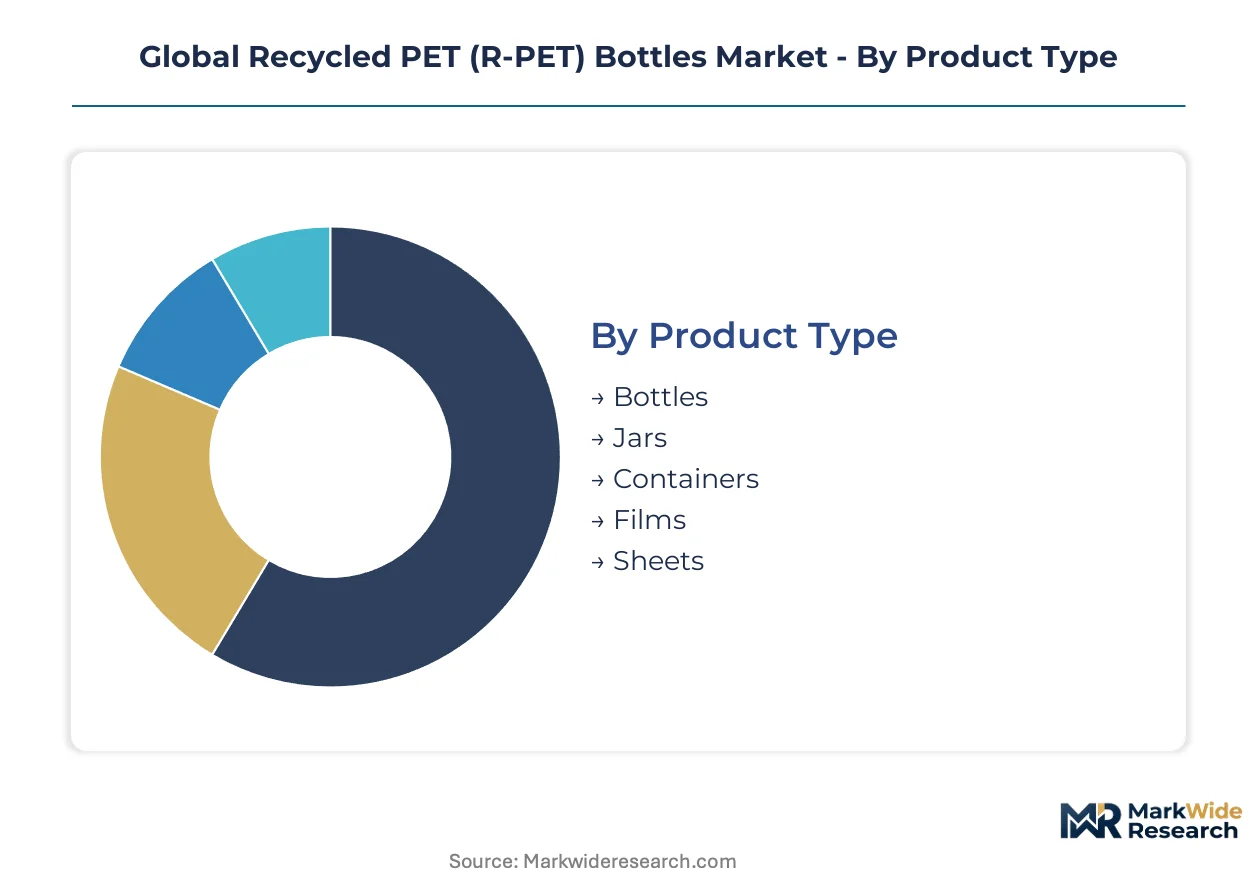
Segmentation in the R-PET bottles market reveals how regulatory mandates and end-use specifications fragment supply chains. Food-grade certification requirements create distinct margin tiers that mechanical recyclers must navigate to secure premium offtake agreements.
Product Type:
Geographic demand patterns diverge sharply: bottles dominate domestic European consumption under deposit-return systems, while films and sheets serve export-oriented packaging converters in Asia-Pacific.
- Bottles:Carbonated beverage containers require intrinsic viscosity above 0.80 dL/g through solid-state polymerization. German deposit-return infrastructure generates the purest post-consumer feedstock stream for this segment, though chemical recyclers now compete for the same clear/blue bales.
- Films:Lower viscosity specifications accept mixed-color flake without SSP processing. Demand concentrates in Chinese thermoforming operations serving export markets, where SAMR's evolving GB standards create compliance uncertainty for imported R-PET.
- Jars:Wide-mouth containers for spreads and condiments use intermediate viscosity grades with modified preform designs.
- Containers:Non-bottle rigid packaging absorbs lower-purity flake streams rejected by beverage-grade processors.
- Sheets:Thermoformed trays and blister packs tolerate broader color variation, sourcing from post-industrial scrap rather than post-consumer collection.
Bottles holds the largest share; momentum sits with films as chemical recycling diverts mixed-color feedstock from fiber applications.
Grade:
Cost tier stratification separates capital-intensive food-grade operations from commodity textile-grade competitors bidding on identical bale streams.
- Food Grade:FDA letters of no objection and EFSA compliance govern hot caustic washing protocols and contaminant thresholds. Beverage manufacturers in Germany and France lock in multi-year supply contracts at fixed price collars to secure volumes ahead of EU mandate deadlines.
- Textile Grade:Fiber applications accept broader contamination windows without solid-state polymerization. Chinese and Indian polyester staple fiber producers dominate offtake, though chemical recycling now diverts previously mechanical-grade feedstock.
- Cosmetic Grade:EFSA-compliant R-PET commands premium pricing in European personal care packaging not yet bound by beverage-sector recycled content mandates.
- Pharmaceutical Grade:Stringent extractables and leachables testing limits viable suppliers to integrated resin producers with captive collection infrastructure.
Food Grade commands the deepest margin pool; Cosmetic Grade is climbing the fastest as brand sustainability pledges extend beyond beverage sectors.
Application:
Customer type concentration drives procurement patterns: multinational beverage bottlers impose bottle-to-bottle mandates, while smaller food processors accept lower-grade alternatives.
- Beverages:Carbonated soft drinks and bottled water represent the most demanding application, requiring clarity retention and pressure resistance. Coca-Cola and PepsiCo sustainability targets in North America have compressed supplier bases to vertically integrated processors.
- Personal Care:Shampoo and lotion bottles tolerate slight color variation, opening procurement to emerging mechanical recyclers without full food-grade certification.
- Household Cleaners:Non-food-contact applications accept broader contamination spectra, sourcing from lower-cost mixed-color flake streams.
- Food Packaging:Trays and clamshells for fresh produce operate under intermediate regulatory scrutiny between beverage and non-food grades.
- Industrial Chemicals:Drum and pail applications prioritize structural integrity over optical purity, utilizing post-industrial regrind.
Beverages anchors volume demand; Personal Care is expanding most quickly as cosmetic brands adopt R-PET ahead of binding mandates.
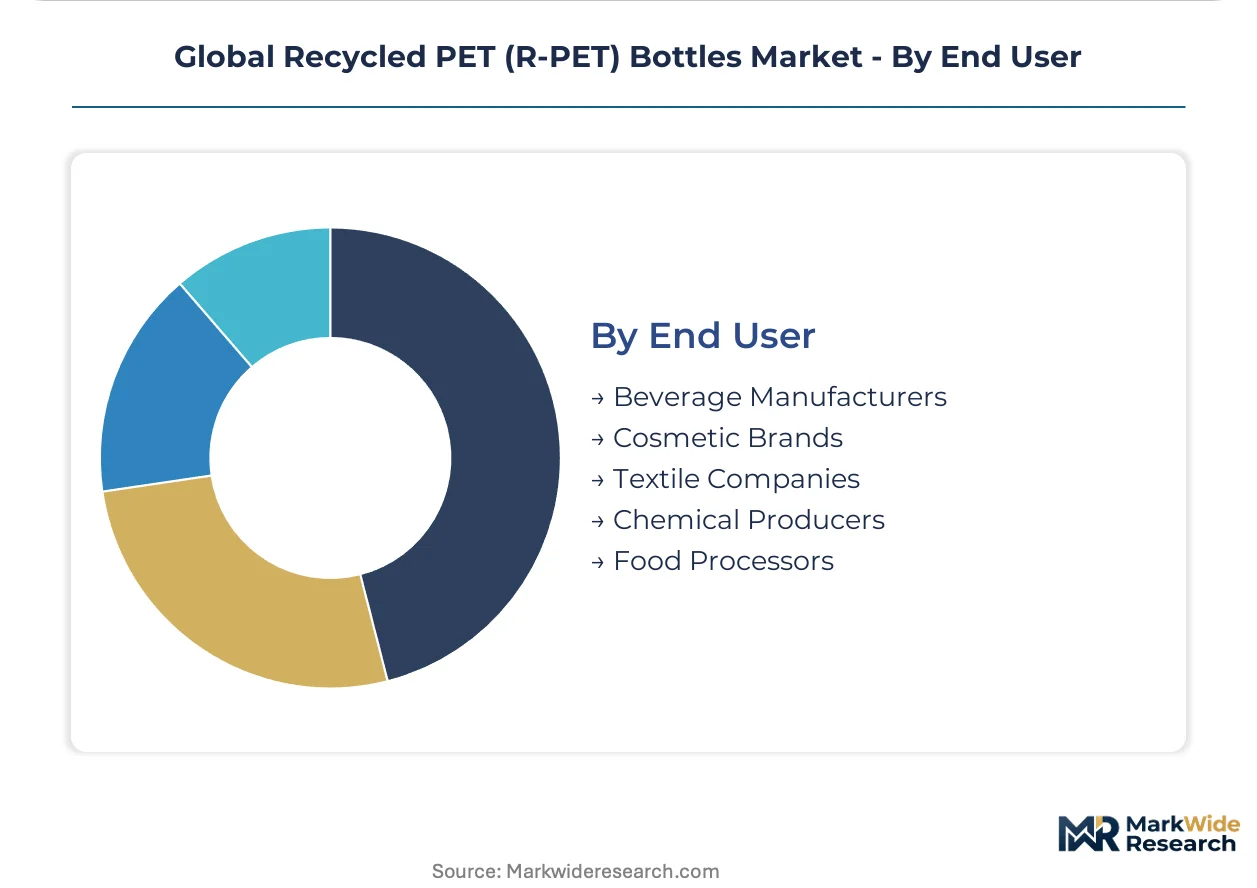
End User:
Supply concentration aligns with converter scale: beverage manufacturers consolidate procurement around multi-year agreements, while textile companies fragment across spot markets.
- Beverage Manufacturers:Binding recycled content mandates force direct contracting with integrated resin-recycling operations. North American bottlers bypass distributors to secure decade-long flake volumes with proprietary collection infrastructure.
- Cosmetic Brands:Premium positioning drives voluntary adoption of EFSA-compliant R-PET ahead of regulatory requirements, particularly in German and French markets.
- Textile Companies:Polyester staple fiber producers in China and India compete with chemical recyclers for mixed-color bale streams, pressuring mechanical recycler margins.
- Chemical Producers:Industrial packaging users prioritize supply security over certification grade, accepting post-industrial scrap when post-consumer flake tightens.
- Food Processors:Smaller converters lack procurement leverage for long-term contracts, exposing operations to spot market volatility in German supply zones.
Beverage Manufacturers dominate procurement scale; Cosmetic Brands are gaining share fastest as sustainability premiums expand beyond regulated sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in food-grade flake concentrate in Germany and the United States, while Asian converters remain net importers of post-consumer bale supply. European mechanical recyclers face feedstock competition from emerging chemical recycling capacity. Chinese sheet processors absorb lower-grade mixed-color streams rejected by beverage-grade bottlers.
Germany
Reverse vending infrastructure captures over 90% of post-consumer PET bottles, generating Europe's purest clear/blue bale stream for bottle-to-bottle recycling. The EU Single-Use Plastics Directive mandates minimum recycled content thresholds, binding beverage manufacturers to multi-year flake supply contracts. Bavarian and Rhineland-Palatinate collection zones concentrate premium food-grade output, creating geographic single-source risk for converters.
United States
Coca-Cola and PepsiCo sustainability targets compress supplier bases to vertically integrated processors with proprietary collection infrastructure. FDA letters of no objection govern food-contact R-PET legitimacy, with 12-18 month review queues delaying novel decontamination deployment. The US Gulf Coast from Texas to Louisiana lacks bottle-to-bottle recycling infrastructure despite massive beverage production, creating greenfield project potential.
China
SAMR enforces GB standards for recycled plastics in domestic packaging, creating divergent certification burdens for multinational converters. Yangtze River Delta thermoforming operations serve export markets, absorbing lower-intrinsic-viscosity output from mixed-color collection streams. Local mechanical recyclers struggle with contamination control, potentially opening food-grade R-PET import windows as regulations tighten.
France
Beverage-grade processors respond to ECHA restrictions on mechanical recycling additives by installing additional hot caustic washing stages. EFSA compliance frameworks constrain odor and color control formulations, forcing capital upgrades across mechanical recycling plants. Île-de-France cosmetic brands drive voluntary adoption of EFSA-compliant R-PET ahead of regulatory requirements, commanding premium pricing.
India
Polyester staple fiber producers compete with emerging chemical recyclers for mixed-color bale streams, pressuring mechanical recycler margins. BIS standards for recycled plastics create compliance uncertainty for imported flake supply. Gujarat and Maharashtra textile clusters absorb lower-grade mechanical output previously destined for fiber applications, though food-grade certification remains limited.
Global Recycled PET (R-PET) Bottles Market Competitive Landscape
Concentration sits with integrated resin-recycling operations that control captive bottle-to-bottle supply chains. The supplier base compresses around vertically positioned players with proprietary collection infrastructure and multi-year beverage contracts. Three archetypes dominate: integrated petrochemical conglomerates with backward recycling capacity, specialized mechanical recyclers with FDA/EFSA food-grade certification, and equipment-technology providers licensing decontamination systems. Competitive moves center on capacity expansion in underpenetrated geographies and strategic partnerships securing long-term flake offtake.
Among Thailand-based integrated operators, Indorama Ventures Public Company Limited exemplifies the petrochemical-recycling convergence archetype with its combined resin and recycling footprint. Plastipak Holdings anchors North American positioning through its proprietary processing technology and beverage contract concentration. ALPLA Werke Alwin Lehner GmbH & Co KG occupies the European specialist tier, leveraging multi-site extrusion blow molding capability across pharmaceutical and cosmetic packaging segments. These three represent distinct competitive vectors: Asian integrated scale, North American technology-contract lock-in, and European premium-grade specialization.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Plastipak Holdings |
| CarbonLITE Industries |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Phoenix Technologies International |
| Evergreen Plastics |
| Vanden Global |
| UltrePET |
| Krones AG |
| Others |
Supply & Pricing Matrix
Multi-year offtake agreements with fixed price collars lock in food-grade R-PET supply access for beverage manufacturers while compressing spot market liquidity. German converters under EU Single-Use Plastics Directive mandates secure Bavarian flake volumes years ahead of mechanical recycling capacity expansion, binding price visibility to collection infrastructure performance.
Pricing Analysis
Beverage manufacturers anchor contract-based long-term offtake structures that stratify across food-grade certification tiers and volume scale commitments. Price differentiation separates FDA letter-of-no-objection holders from textile-grade competitors bidding on identical clear/blue bale streams. Pricing pressure stems from chemical recyclers now competing for premium feedstock, diverting material from established mechanical processors. Smaller food processors exhibit highest price sensitivity, lacking procurement leverage against spot market volatility in German supply zones.
Supply Chain Analysis
Germany and the United States anchor food-grade flake production through reverse vending infrastructure and vertically integrated resin-recycling operations. Mechanical recyclers draw from post-consumer PET bale streams, virgin PET resin naphtha spreads, and solid-state polymerization energy inputs. Single-source vulnerability concentrates in Bavarian and Rhineland-Palatinate collection zones. Distribution runs through direct converter relationships and multi-year supply agreements, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where bottle-to-bottle closed-loop ecosystems interoperate with chemical recycling scale-up, reshaping feedstock allocation and procurement lock-in dynamics.
For Market Incumbents: Fortify captive collection infrastructure in underpenetrated geographies against chemical recycling feedstock competition. Expand solid-state polymerization capacity ahead of EU mandate deadlines to defend margin position from novel decontamination technologies achieving food-contact thresholds without energy-intensive SSP processing. For New Entrants and Emerging Players: Cosmetic and pharmaceutical packaging service-layer gaps offer white-space entry where EFSA-compliant R-PET commands premium pricing without beverage-sector mandate saturation. Target Texas and Louisiana greenfield opportunities where massive beverage production lacks local bottle-to-bottle recycling infrastructure. Pursue technology licensing partnerships with established decontamination system providers to accelerate FDA letter of no objection acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated resin-recycling operations with proprietary collection infrastructure and multi-year beverage contracts. Long-term viability centers on backward integration into flake supply and captive SSP capacity. Monitor chemical recycling offtake agreement velocity as inflection indicator for mechanical recycler feedstock access erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | German reverse vending operators secure 90%+ capture rates, generating Europe's purest clear/blue bale streams for bottle-to-bottle recycling. |
| Solid-State Polymerization Capacity Expansion | Achieving 0.80 dL/g intrinsic viscosity for carbonated beverage pressure retention requires energy-intensive SSP reactors with extended payback periods. |
| Long-term Supply Agreement with Fixed Price Collars | Coca-Cola and PepsiCo sustainability targets compress North American supplier bases to vertically integrated processors with decade-long flake volumes. |
| Hot Caustic Washing Technology Licensing | Improved decontamination protocols achieve FDA and EFSA food-contact safety thresholds, lowering capital barriers for mechanical recyclers. |
| Geographic Expansion to US Gulf Coast | Texas and Louisiana lack bottle-to-bottle recycling infrastructure despite massive beverage production, creating greenfield project potential. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across beverage procurement directors, mechanical recycling plant managers, PET resin technical R&D leads, and EFSA regulatory compliance officers. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, FDA food-contact notification databases, German reverse vending system performance data, and SEC filings of integrated petrochemical conglomerates. Bottom-up capacity modeling and top-down demand projection triangulation anchored volume estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from installed capacity trajectories, mandate compliance deadlines, and feedstock availability curves. Industry-specific inputs included post-consumer PET bale price volatility against naphtha spreads and chemical recycling capacity announcement pipelines.
Material uncertainties — feedstock diversion to pyrolysis and glycolysis operators, REACH additive restriction expansions, and SAMR GB standards evolution — sit outside the modeled envelope. Forecasts reflect assumptions around mechanical recycling decontamination technology advancement and deposit-return system capture rate maintenance. Recalibration cycles align with material shifts in EU mandate enforcement timelines and chemical recycling commercial scale-up velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market