
 Gluten Free Food Market | 2026-2036
Gluten Free Food Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Free Food Market Analysis
Certified Gluten-Free accreditation from the Gluten Intolerance Group is unwinding competitive access for smaller brands that lack testing infrastructure. General Mills, Inc. leverages its supply chain scale to secure certified oat streams at volume. Bob's Red Mill Natural Foods, Inc. anchors its position through dedicated gluten-free milling facilities in Oregon. Barilla Group competes by extending its pasta expertise into quinoa and corn formulations with European market dominance.
Gluten free food comprises products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting rice flour, tapioca starch, or xanthan gum to achieve comparable texture and shelf stability. Bakery Products command the largest revenue pool due to bread and cake replacement demand, though Snacks generate faster velocity through impulse purchase channels. Rice dominates ingredient sourcing by tonnage, while Quinoa formulations capture premium positioning in North American natural retail.
FDA enforces the gluten-free labeling rule requiring sub-20 ppm gluten content, while EFSA and EMA coordinate allergen threshold science that informs EU member state enforcement. Health Canada maintains parallel standards through its gluten-free claims guidance, creating a multi-jurisdictional compliance burden for exporters. Stakeholders must monitor evolving Codex Alimentarius revisions and emerging rapid-detection technologies that could reshape certification economics.
Market Dynamics
Certification infrastructure concentration is restructuring competitive access, as accredited testing capacity becomes the gating factor for shelf placement in major retail channels. Brands without captive laboratory relationships face escalating compliance costs and extended time-to-market cycles.
Growth Catalysts
- FDA Gluten-Free Labeling Rule:The sub-20 ppm enforcement threshold creates uniform compliance baselines that reduce consumer trust friction and expand addressable demand among diagnosed celiac populations in the United States.
- EU Commission Implementing Regulation 828/2014:Harmonized cross-border labeling standards enable economies of scale in formulation and packaging across member states, accelerating private-label expansion.
- Rapid-detection technologies:Lateral flow immunoassays and PCR-based screening are compressing batch-release timelines from days to hours, enabling just-in-time manufacturing for perishable gluten-free bakery lines.
Market Restraints
- Certified oat supply concentration:Purity protocol oat streams are geographically concentrated in North American and Scandinavian growing regions, exposing formulators to harvest-quality volatility and single-source dependency.
- Xanthan gum price instability:Fermentation-derived hydrocolloids face feedstock cost pressure from corn and sugar substrate markets, compressing margin structures in texture-critical applications.
- Cross-contamination liability thresholds:The 20 ppm regulatory ceiling leaves minimal buffer for manufacturing variance, forcing redundant production line segregation that elevates capital intensity.
Strategic Opportunities
- Australia diagnostic gap closure:Underpenetrated screening rates relative to celiac disease prevalence create latent demand pools as gastroenterology access expands through public health initiatives.
- Direct-to-subscription channels:Recurring delivery models bypass conventional slotting fee structures and capture full-margin relationships with lifestyle-driven gluten-free adopters.
- Sorghum and teff ingredient innovation:Ancient grain diversification beyond rice and corn matrices enables glycemic positioning and novel texture profiles in premium bakery segments.
Industry Challenges
- Allergen analytical chemistry talent scarcity:Validated ELISA and mass spectrometry operators command premium compensation in food safety labor markets, constraining quality team scaling.
- Dual-facility capital requirements:Dedicated gluten-free milling and processing infrastructure demands parallel equipment investments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Free Food Market |
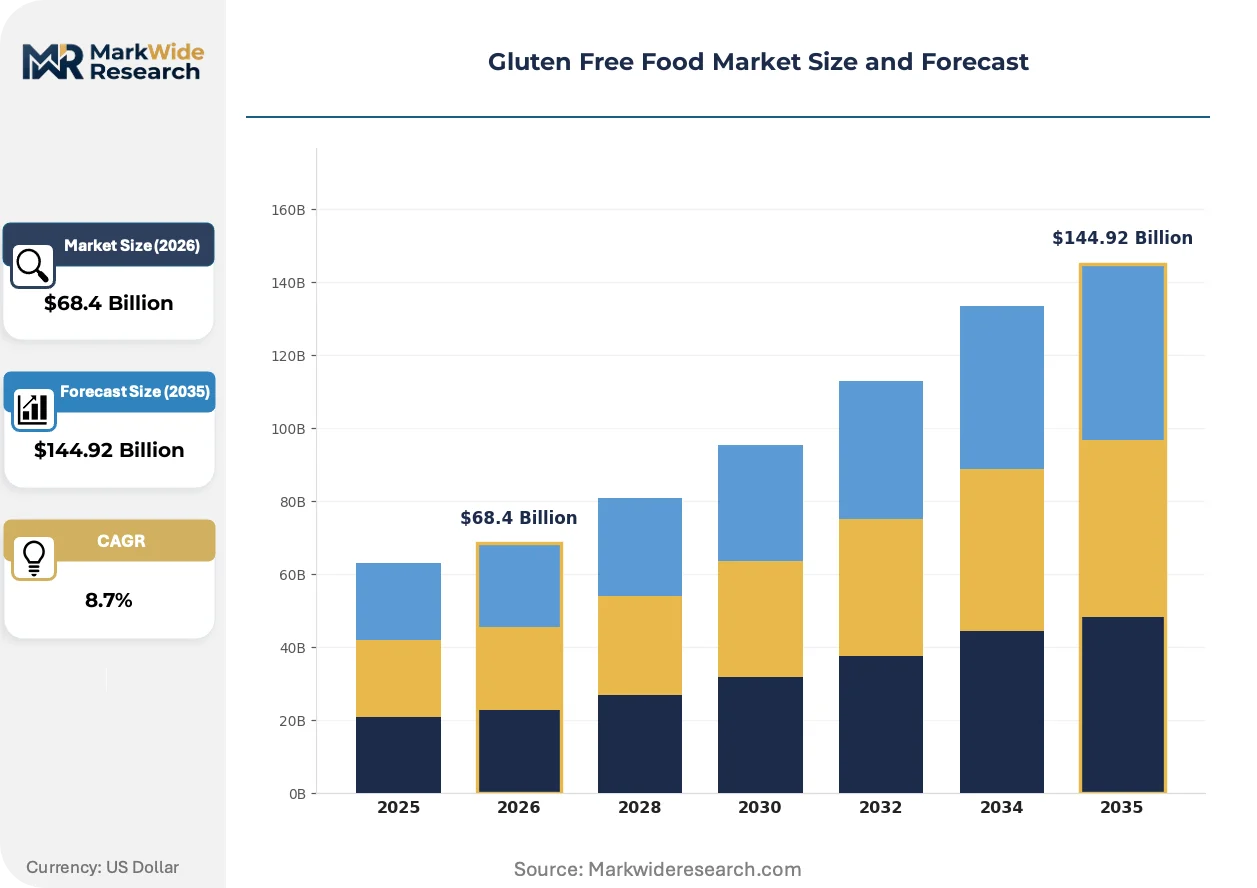
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bakery Products, Snacks, Pasta, Dairy Alternatives Ingredient Source: Rice, Corn, Quinoa, Oats End User: Retail Consumers, Food Service, Health Institutions, Catering Services Packaging Type: Bags, Boxes, Tubs, Pouches |
| Companies Covered | General Mills, Inc., The Kraft Heinz Company, Conagra Brands, Inc., Kellanov, Mondelez International, Inc., The Hain Celestial Group, Inc., Barilla Group, Bob's Red Mill Natural Foods, Inc., PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Free Food Market Emerging Trajectories
Reformulation science is compressing the sensory gap between gluten-free and conventional products, while detection technology and procurement logic are simultaneously transforming how value is captured across the value chain.
Enzymatic gluten degradation is miniaturizing. Transglutaminase and prolyl endopeptidase applications are migrating from industrial-scale brewing into finished food matrices, enabling sourdough-style fermentation in gluten-free bread without structural collapse. Artisan bakeries in Germany and the United States are piloting these systems for crust elasticity replication. The technology is miniaturizing quality thresholds previously achievable only through hydrocolloid-heavy formulations.
REACH and RoHS compliance pressures are reshaping packaging material selection for European exports. Recyclable mono-material films are displacing multi-layer laminates that previously protected oxygen-sensitive ancient grain formulations. Italian pasta manufacturers report reformulation cycles to accommodate barrier-property shifts without shelf-life degradation.
Subscription-based replenishment is capturing pantry-stocking occasions previously dominated by conventional retail. Direct-to-consumer platforms in the United States and United Kingdom are bundling certified bakery and snack assortments with diagnostic test kits, creating stickier household relationships than impulse-aisle competition permits.
Gluten Free Food Market Segmentation
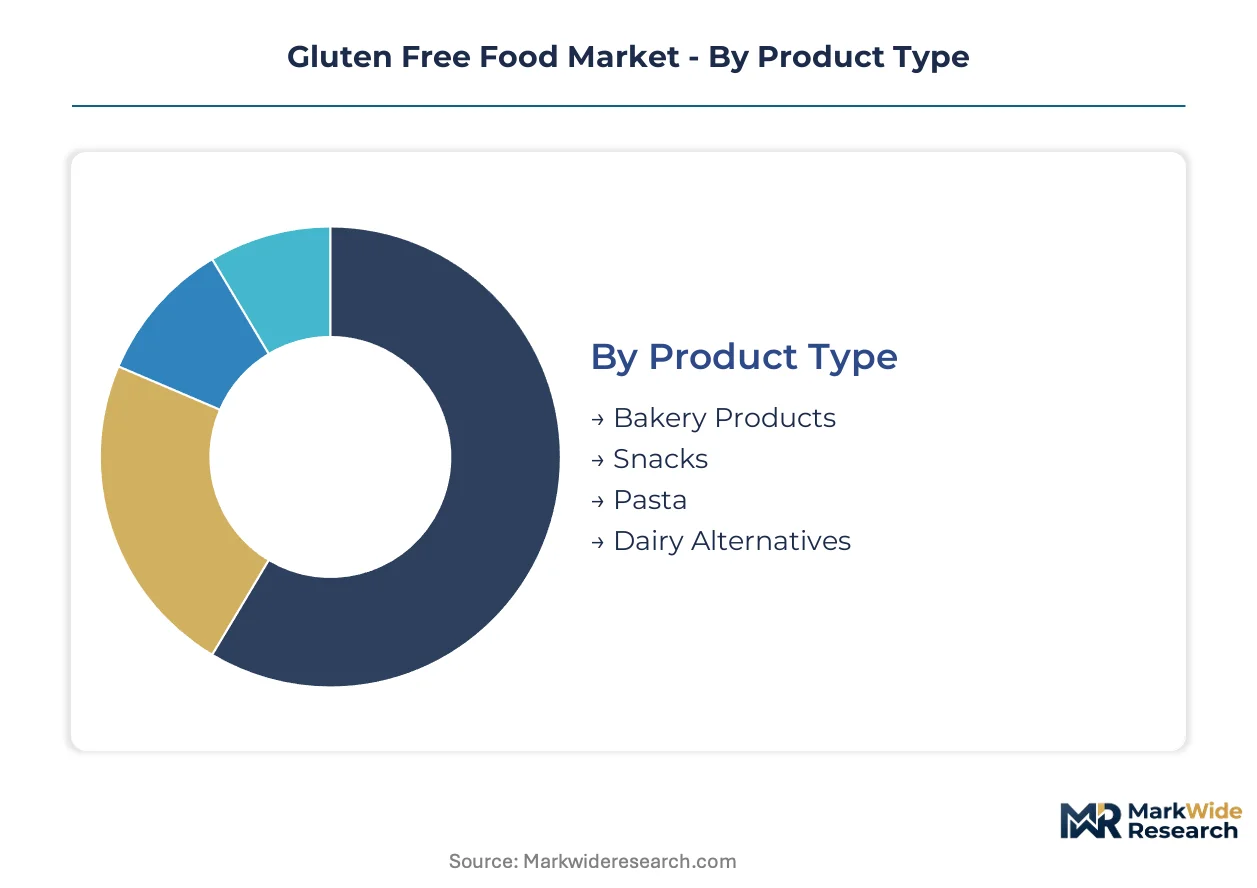
Gluten-free food segmentation reflects divergent compliance burdens across product categories, with FDA and EU Commission thresholds reshaping which segments justify dedicated production infrastructure. Understanding these divides clarifies where capital deployment yields protected margin positions versus commoditized competition.
Product Type:
FDA's sub-20 ppm enforcement and EU Commission Implementing Regulation 828/2014 create tiered compliance exposure across finished goods categories, with perishability and cross-contamination risk determining which segments warrant captive facility investment.
- Bakery Products:Bread, cake, and pastry formulations rely on rice flour, tapioca starch, and xanthan gum to replicate gluten's viscoelastic structure. Demand concentrates in the United States and Germany where celiac diagnostic rates and retail shelf space for certified lines continue expanding, though dual-facility capital requirements strain mid-tier manufacturers.
- Snacks:Crackers, chips, and energy bars achieve faster velocity through impulse purchase channels with simpler formulation matrices. Australia shows particular strength in this segment as underpenetrated screening rates relative to disease prevalence create latent demand pools through expanding gastroenterology access.
- Pasta:Quinoa and corn formulations dominate premium positioning in North American natural retail, with Italian manufacturers adapting to REACH and RoHS packaging compliance pressures.
- Dairy Alternatives:Gluten-free labeled milk substitutes and plant-based yogurts serve cross-category allergen avoidance consumers in Health Canada-regulated markets.
Bakery Products handles the majority of throughput; Snacks is the fastest mover on share.
Ingredient Source:
Cost tier differentiation separates commodity grain streams from premium ancient grain positioning, with purity protocol requirements adding certification overhead that reshapes procurement economics.
- Rice:Dominates tonnage sourcing across all product categories, with white and brown rice flours providing neutral flavor bases and established supply chains in Asian and North American growing regions.
- Corn:Maize-derived ingredients offer cost advantages in mass-market formulations, though non-GMO and organic certifications command premium positioning in United States natural retail channels.
- Quinoa:Andean-sourced grain delivers complete protein positioning and low glycemic index claims that capture premium pricing in North American and European health food segments, with supply concentration in Peru and Bolivia creating single-source dependency risks.
- Oats:Purity protocol oat streams from North American and Scandinavian growing regions face harvest-quality volatility, with certified gluten-free oat supply concentration exposing formulators to price instability and extended lead times.
Rice anchors volume throughput; Quinoa climbs the fastest on value per kilogram.
End User:
Customer type determines margin capture potential, with institutional procurement favoring volume contracts and direct-to-consumer channels preserving full pricing power.
- Retail Consumers:Supermarket and specialty store purchases dominate revenue generation, with subscription-based replenishment models in the United States and United Kingdom bypassing conventional slotting fee structures.
- Food Service:Restaurant and cafe procurement demands bulk formats with consistent supply assurance, creating preference for established brands with dedicated gluten-free milling infrastructure.
- Health Institutions:Hospital and clinical nutrition programs require documented certification chains and batch-level testing records that favor suppliers with captive laboratory relationships.
- Catering Services:Event and corporate dining providers seek versatile ingredient formats that simplify cross-contamination protocol compliance in shared kitchen environments.
Retail Consumers commands the revenue base; Food Service is expanding most quickly as away-from-home gluten-free options proliferate.
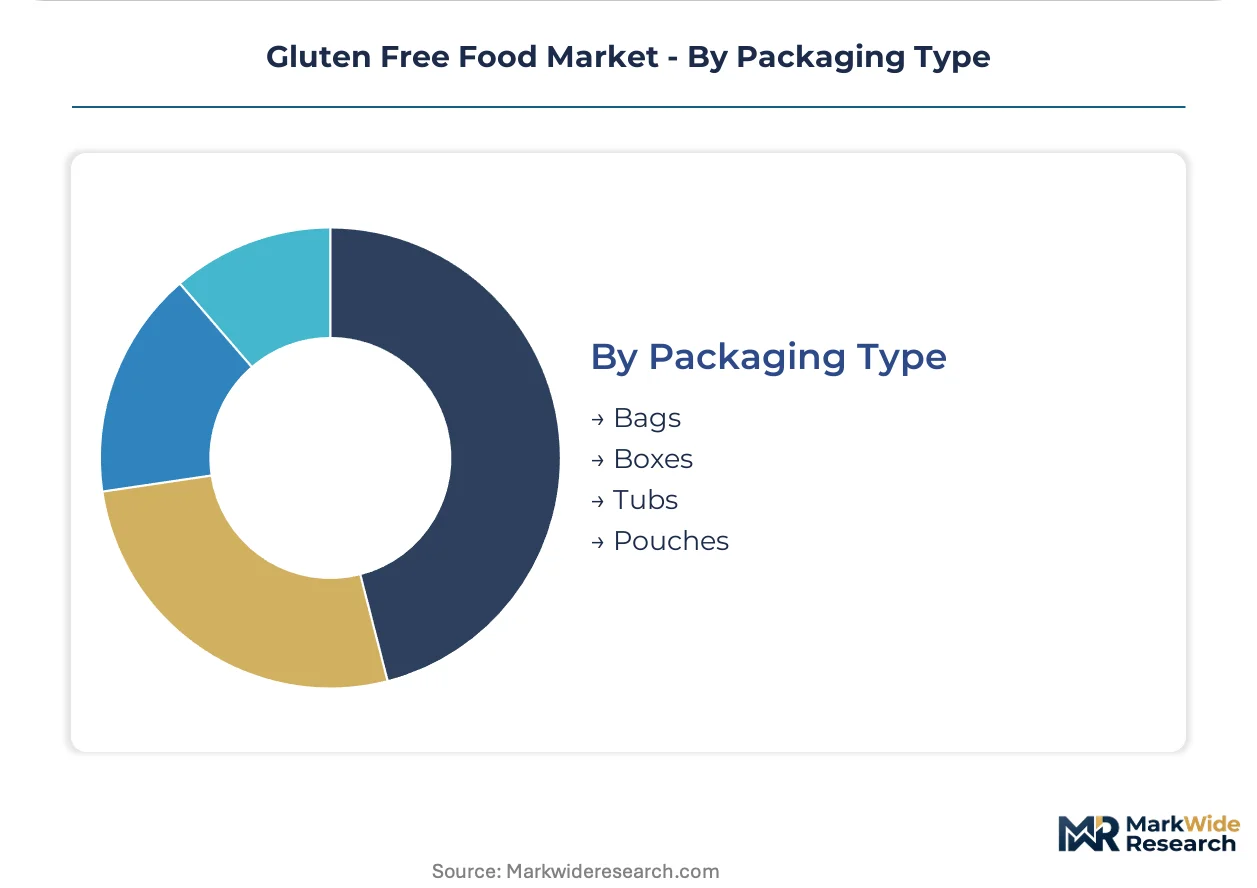
Packaging Type:
Packaging material selection increasingly reflects regulatory pressure on recyclability, with oxygen barrier requirements for ancient grain formulations complicating mono-material transitions.
- Bags:Flexible packaging dominates dry goods categories with cost efficiency and shelf presence advantages, though multi-layer laminates face displacement by REACH-compliant recyclable alternatives.
- Boxes:Corrugated and folding carton formats serve premium bakery and pasta positioning with stackability and print surface benefits for certification mark visibility.
- Tubs:Rigid plastic and fiber-based containers protect refrigerated dairy alternatives and fresh bakery items with resealability features that extend consumption windows.
- Pouches:Stand-up and flat pouch formats gain traction in snack and single-serve segments with material efficiency and e-commerce shipping advantages.
Bags maintains volume leadership; Pouches shows the steepest expansion trajectory as direct-to-consumer channels scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail consumers with celiac disease and gluten sensitivity concentrate in markets with established diagnostic infrastructure and certified product availability. The United States, Germany, and Australia anchor demand through distinct regulatory and distribution pathways.
United States
Supermarket shelf space for certified bakery and snack lines continues expanding as celiac diagnostic rates climb. FDA enforces the sub-20 ppm gluten-free labeling rule, creating uniform compliance baselines that reduce consumer trust friction. Portland, Oregon hosts dedicated gluten-free milling infrastructure that supplies national distribution networks.
Germany
Artisan bakeries pilot enzymatic gluten degradation systems for sourdough-style bread with crust elasticity replication. EU Commission Implementing Regulation 828/2014 harmonizes cross-border labeling standards, enabling economies of scale in formulation and packaging. Munich and Berlin clusters drive premium ancient grain pasta innovation for export markets.
Australia
Underpenetrated screening rates relative to celiac disease prevalence create latent demand pools as gastroenterology access expands through public health initiatives. TGA coordinates allergen threshold science that informs domestic enforcement and import standards. Melbourne and Sydney concentrate specialty retail and direct-to-subscription platform headquarters.
Canada
Health Canada maintains parallel gluten-free claims guidance, creating multi-jurisdictional compliance burden for exporters serving North American markets. Cross-border supply chains integrate certified oat streams from North American growing regions. Toronto and Vancouver anchor food service procurement networks demanding bulk formats with consistent supply assurance.
Italy
Pasta manufacturers adapt to REACH and RoHS packaging compliance pressures, reformulating to accommodate recyclable mono-material barrier-property shifts. Corn and quinoa formulations dominate premium positioning in domestic and export channels. Emilia-Romagna and Lombardy industrial clusters concentrate production infrastructure for European market dominance.
Gluten Free Food Market Vendor Landscape
Player mix skews toward diversified food conglomerates with captive supply chain infrastructure and dedicated gluten-free specialists with accredited testing relationships. Market structure exhibits tiered concentration, with scale-driven multinational portfolios occupying mass retail channels while regional specialists capture premium natural retail positioning. Three archetypes dominate: vertically integrated grain processors with purity protocol oat streams, legacy pasta and bakery houses extending expertise into alternative formulations, and direct-to-consumer subscription platforms bypassing conventional slotting fees. Competitive moves concentrate on dedicated facility investments and rapid-detection technology partnerships that compress batch-release timelines.
Within the diversified conglomerate tier, General Mills, Inc. and The Kraft Heinz Company represent scale-driven positions anchored by supply chain breadth and retail distribution density. Among dedicated specialists, Bob's Red Mill Natural Foods, Inc. occupies a position exemplifying accredited facility investment, while Barilla Group exemplifies category extension from conventional pasta expertise into quinoa and corn formulations. These three companies illustrate how certification infrastructure concentration is restructuring competitive access across the value chain.
| Leading Market Players |
|---|
| General Mills, Inc. |
| The Kraft Heinz Company |
| Conagra Brands, Inc. |
| Kellanov |
| Mondelez International, Inc. |
| The Hain Celestial Group, Inc. |
| Barilla Group |
| Bob's Red Mill Natural Foods, Inc. |
| PepsiCo, Inc. |
| Others |
Supply Flow & Price Mechanics
FDA's sub-20 ppm gluten-free labeling rule and EU Commission Implementing Regulation 828/2014 gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb certification overhead that stratifies pricing tiers by compliance tier rather than ingredient cost alone.
Pricing Analysis
Cost-plus contracts with xanthan gum and purity protocol oat indexation dominate procurement agreements between manufacturers and ingredient suppliers. Three-tier pricing structure across certified premium, standard gluten-free, and economy private-label levels separates buyers by diagnostic necessity versus lifestyle preference. Pricing pressure stems from fermentation feedstock volatility in hydrocolloid markets, compressing margins in texture-critical bakery applications. Celiac-diagnosed retail consumers show lowest price sensitivity due to medical necessity, while lifestyle adopters drive volume but resist premium positioning.
Supply Chain Analysis
Inventory lead times for certified oat streams extend substantially beyond conventional grain procurement cycles due to purity protocol growing restrictions. Geographic supply concentrates in the United States, Canada, and Scandinavia for gluten-free oat cultivation, with quinoa sourcing anchored in Peru and Bolivia. Raw material dependencies center on rice flour, tapioca starch, and xanthan gum as structural substitutes for gluten's viscoelastic properties. Single-source vulnerability in Andean quinoa supply creates concentration risk during harvest volatility. Distribution runs through mass retail supermarket channels, with direct-to-subscription platforms capturing pantry-stocking occasions at full margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against enzymatic gluten degradation technologies that could collapse the sensory gap between gluten-free and conventional products, threatening the category's premium positioning.
For Market Incumbents: Secure captive purity protocol oat supply through backward integration into North American growing regions before harvest-quality volatility escalates. Anchor certification infrastructure through accredited laboratory partnerships that compress batch-release timelines from days to hours, defending shelf placement against private-label encroachment.
For New Entrants and Emerging Players: Anchor in Australia's underpenetrated diagnostic gap where expanding gastroenterology access creates latent demand pools ahead of incumbent distribution buildout. Target direct-to-subscription channels with bundled diagnostic test kits and certified bakery assortments, bypassing conventional slotting fee structures that favor scale players.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underutilized gluten-free facility assets and stranded certification relationships. Long-term viability hinges on diagnostic rate expansion outpacing enzymatic conventional-product substitution. Watch rapid-detection technology adoption curves as inflection indicator for certification economics restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | Accredited testing capacity gates shelf placement in FDA-regulated United States retail channels. |
| Purity Protocol Oat Supply Integration | Backward integration into North American growing regions secures volume against harvest volatility. |
| Direct-to-Consumer Channel Launch | Subscription models capture full-margin pantry-stocking occasions from lifestyle-driven adopters. |
| Enzymatic Formulation Partnership | Transglutaminase applications replicate crust elasticity without hydrocolloid-heavy cost structures. |
| REACH-Compliant Packaging Transition | Mono-material films satisfy EU regulatory pressure without ancient grain shelf-life degradation. |
Methodological Framework
Cross-validation between primary interviews with certified food production managers, retail category buyers, regulatory compliance officers, and diagnostic laboratory directors anchors the qualitative findings against secondary validation from FDA labeling guidance documents, EU Commission implementing regulations, Health Canada claims guidance, and Codex Alimentarius draft revisions. Customs records and certified product registration databases provide trade flow triangulation. Bottom-up facility capacity assessments and top-down retail audit data converge on volume estimates.
Sensitivity analysis across ingredient price scenarios and diagnostic rate assumptions tests forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, ingredient source, end user archetype, and packaging format, with regulatory jurisdiction as cross-cutting overlay. CAGRs derive from compound growth trajectory fitting against historical certified product launch velocity and shelf space expansion patterns. Purity protocol oat supply constraints and rapid-detection technology adoption curves serve as industry-specific forecast inputs.
Material uncertainties — regulatory threshold revisions, enzymatic substitution technology maturation, and diagnostic rate acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification infrastructure scaling and retail channel access evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Malt Extracts Market