
 Japan Dairy Market | 2026-2036
Japan Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Dairy Market Insights
Precision fermentation and enzymatic processing is reconfiguring how functional dairy ingredients are manufactured and scaled in Japan. Meiji Co. Ltd leverages its captive R&D pipeline to sustain leadership in probiotic strain development. Morinaga Milk Industry Co. Ltd anchors its position through specialized infant and medical nutrition formulations. Yakult Honsha Co. Ltd dominates the ambient probiotic drink channel with unmatched distribution density into convenience retail.
Japan dairy encompasses fluid milk, fermented products, cheese, and butter derived from bovine milk through pasteurization, homogenization, and controlled fermentation at specified fat solids and microbial thresholds, serving nutritional intake, food manufacturing input, and food service preparation needs. Milk retains the largest volume footprint but operates on thin margins due to raw milk price controls under the producer stabilization mechanism. Yogurt commands disproportionate value contribution as functional claims around Lactobacillus strains justify shelf price premiums in supermarkets and convenience stores.
METI administers Japan's food industry policy including dairy supply stabilization, while the Consumer Affairs Agency enforces Food Labeling Standards Act compliance on nutrient function claims and allergen disclosure. MHLW's Food Sanitation Act sets residual antibiotic limits and raw milk cooling standards that shape farm-to-processor logistics investment. Stakeholders must monitor how evolving PLI-style domestic production incentives and carbon footprint disclosure requirements under the GX initiative will reshape sourcing economics and packaging format decisions.
Market Dynamics
Japan's dairy sector is contending with a structural squeeze between METI-administered raw milk price stabilization and the Consumer Affairs Agency's tightening of Food Labeling Standards Act claims, which together force simultaneous cost discipline and premium-positioning investment.
Growth Catalysts
- Functional claim premiumization:Probiotic strain-specific positioning under revised labeling rules allows yogurt and fermented milk to command shelf price premiums in convenience retail and supermarket channels.
- Precision fermentation scale-up:Enzymatic processing technologies are reducing ingredient production costs for protein-fortified formats targeting aging consumers in the Greater Tokyo corridor.
- GX initiative carbon accounting:Packaging format innovation driven by disclosure requirements is opening premium positioning for low-carbon footprint chilled distribution networks.
Market Restraints
- Raw milk price control rigidity:The producer stabilization mechanism caps fluid milk margins and limits processor flexibility to absorb feed cost volatility from Hokkaido dairy cooperatives.
- Antibiotic residue compliance costs:MHLW Food Sanitation Act cooling standards and residual limit testing impose farm-to-processor logistics investments that squeeze small-scale operations.
- Plant-based dairy substitution:Oat and almond milk alternatives are capturing lactose-intolerant and flexitarian consumers in urban convenience retail, compressing fluid milk volume.
Strategic Opportunities
- Medical nutrition specialization:Infant and senior-specific formulations under PMDA oversight offer white space for high-margin products beyond commodity yogurt and fluid milk.
- Kansai underpenetration:Premium chilled distribution density lags Osaka-Kyoto corridors versus Tokyo, creating expansion runway for functional dairy formats.
- PLI-style domestic production incentives:Emerging METI production-linked incentive structures may reshape sourcing economics toward domestic ingredient security.
Industry Challenges
- Microbiome strain IP complexity:Proprietary Lactobacillus development requires multi-year R&D cycles with uncertain patent protection timelines against competitor reverse engineering.
- Cold chain capex intensity:Premium chilled distribution expansion demands refrigeration infrastructure investment that strains mid-tier processor balance sheets.
- Allergen labeling compliance velocity:Consumer Affairs Agency disclosure requirement updates outpace reformulation cycles, forcing reactive packaging redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Dairy Market |
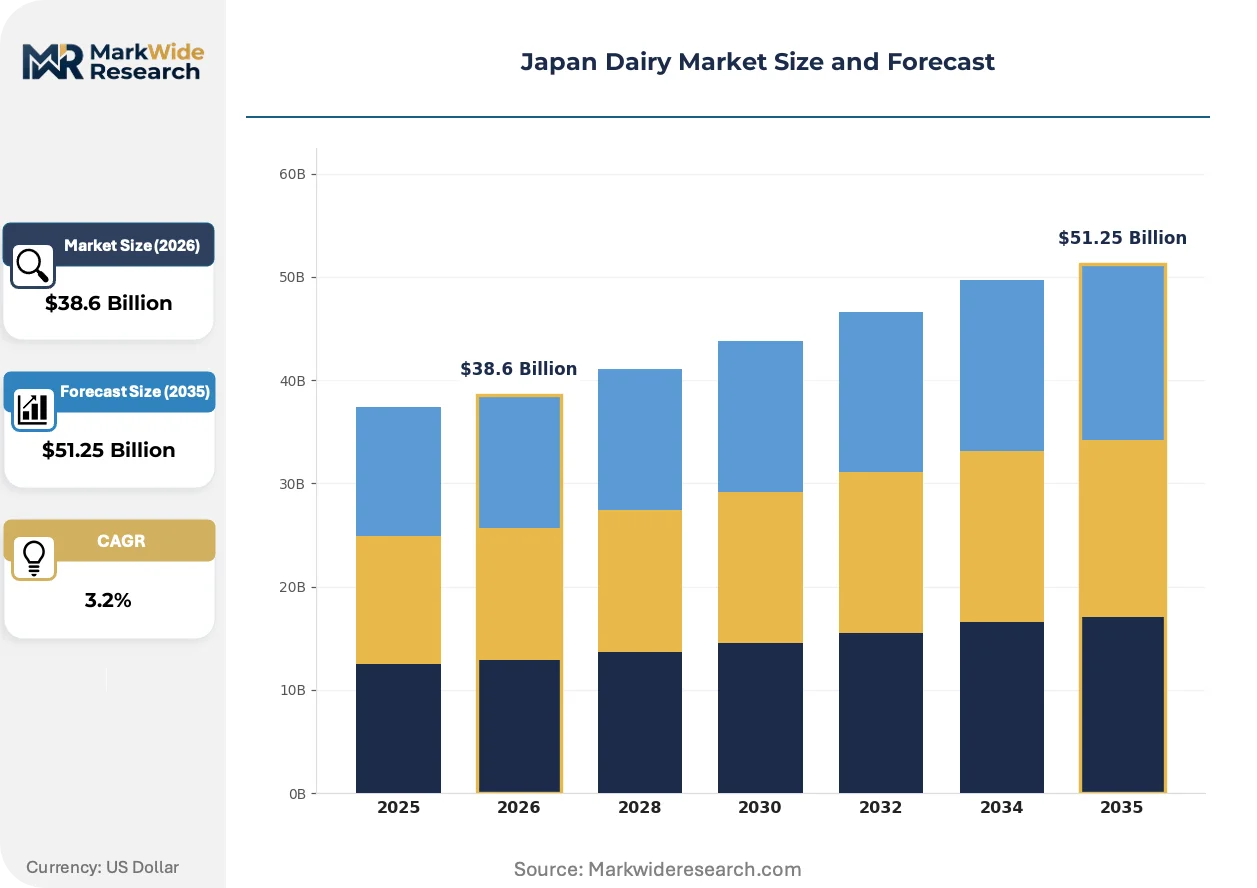
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter End User: Retail Consumers, Food Service, Manufacturers, Institutions Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Direct Sales Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Meiji Co. Ltd, Megmilk Snow Brand Co. Ltd, Morinaga Milk Industry Co. Ltd, Yakult Honsha Co. Ltd, Yotsuba Milk Products Co. Ltd, Takanashi Dairy Co. Ltd, NH Foods Ltd, Rokko Butter Co. Ltd, Bel Japon KK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Dairy Market Trends and Innovations
Japan's dairy landscape is being reconfigured by bioprocessing advances, regulatory claim tightening, and channel-specific demand fragmentation that rewards precision over scale.
Precision fermentation infrastructure is digitizing how functional ingredients—specifically bioactive peptides and specialized proteins—are manufactured at commercial scale. Mid-tier processors in the Kanto region are adopting these platforms to bypass traditional dairy cooperative supply structures. The technology is digitizing strain development timelines and compressing the gap between laboratory validation and supermarket shelf placement.
Revisions to the Food Labeling Standards Act are tightening substantiation requirements for nutrient function claims on probiotic and protein-fortified products. Processors must now submit clinical evidence packages to the Consumer Affairs Agency before deploying gut health or immune support messaging. Yogurt and fermented milk segments are responding by consolidating claims around fewer, better-documented strains rather than proliferating speculative benefits.
Convenience store chains are consolidating dairy procurement around fewer, larger suppliers with dedicated chilled logistics capabilities. Independent processors face exclusion from 7-Eleven and Lawson shelf resets unless they integrate with these distribution networks. This concentration is most visible in Tokyo's 23 wards, where ambient probiotic drinks retain placement while chilled premium formats face space compression.
Japan Dairy Market Segmentation
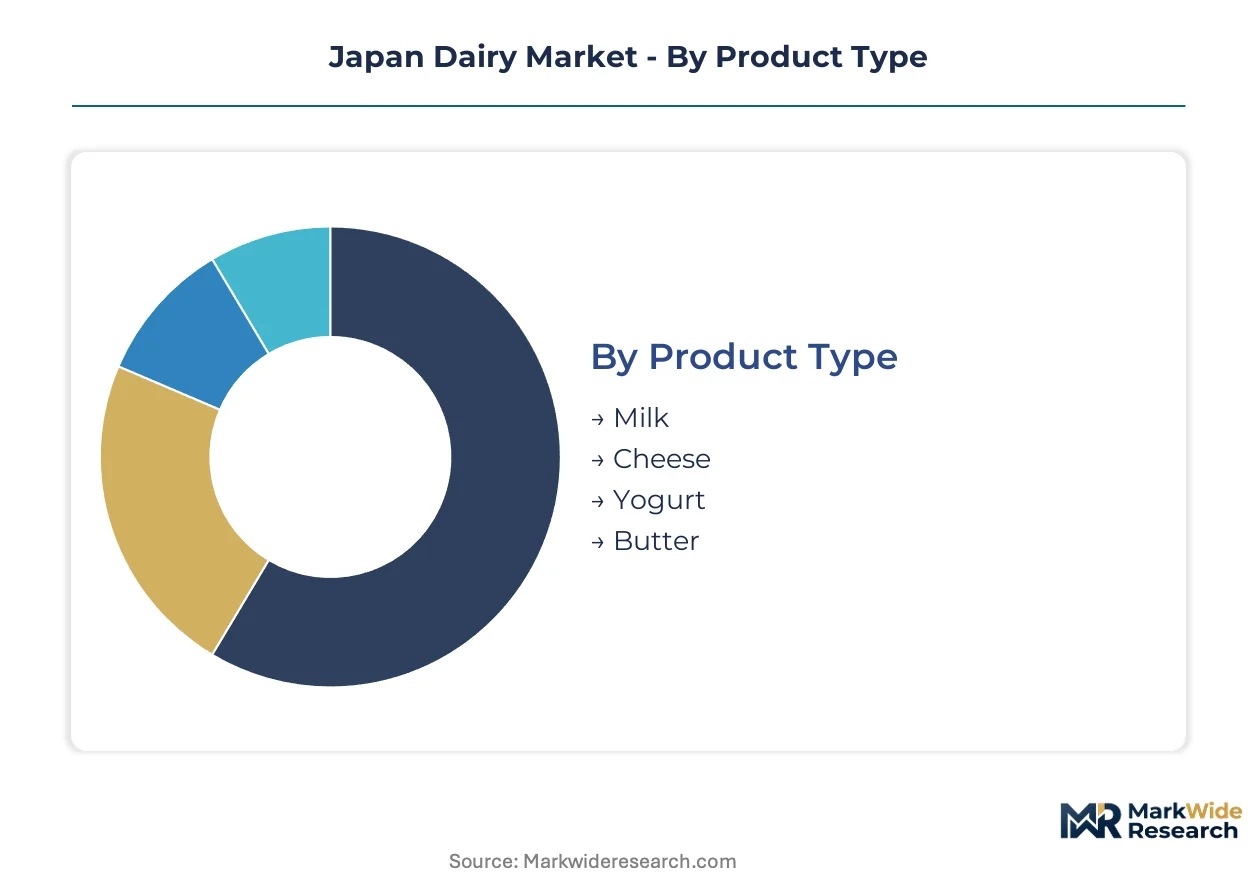
Segmentation in Japan's dairy sector reveals how METI-administered pricing structures and Consumer Affairs Agency labeling rules differentially impact product economics across channels. Each dimension exposes distinct margin pressures and premium capture opportunities that processors must navigate.
Product Type:
After-sales service intensity varies sharply across dairy formats, with functional yogurt demanding ongoing consumer education on strain-specific benefits while fluid milk requires minimal post-purchase engagement.
- Yogurt:Fermented products carry specified Lactobacillus counts and fat solids percentages that must maintain viability through chilled distribution. Demand concentrates in Greater Tokyo convenience retail where functional claims justify shelf price premiums under revised Food Labeling Standards Act rules.
- Milk:Pasteurized and homogenized bovine milk operates under raw milk price controls that cap processor margins regardless of feed cost volatility from Hokkaido cooperatives. Volume concentrates in supermarket channels serving household nutritional intake needs.
- Cheese:Natural and processed cheese formats serve food manufacturing input requirements with varying moisture and fat content specifications.
- Butter:Fat-derived spreads support food service preparation and baking applications with standardized churn specifications.
Yogurt holds the largest share; momentum sits with functional formats climbing the fastest as aging consumers seek probiotic and protein-fortified options.
End User:
Cost tier stratification separates commodity bulk purchasers from premium-positioned direct consumers, with institutional buyers driving volume and retail consumers driving margin.
- Retail Consumers:Individual households purchasing through supermarket and convenience channels for direct nutritional intake. Demand fragments across aging demographics seeking medical-adjacent benefits and younger flexitarians exploring plant alternatives.
- Food Service:Restaurants, cafes, and hospitality operators procuring butter and cheese for preparation inputs. Specifications center on consistency and volume pricing for operational efficiency.
- Manufacturers:Food processors integrating dairy ingredients into packaged goods, requiring standardized fat solids and microbial thresholds for production line compatibility.
- Institutions:Schools, hospitals, and corporate cafeterias sourcing fluid milk under nutritional program mandates with price-sensitive procurement protocols.
Retail consumers command the value pool; institutional contracts deliver volume stability with constrained margin expansion.
Distribution Channel:
Geographic concentration in the Greater Tokyo corridor creates channel-specific infrastructure requirements that advantage processors with captive chilled logistics networks.
- Convenience Stores:7-Eleven and Lawson chains consolidate procurement around suppliers with dedicated ambient and chilled distribution capabilities, excluding independent processors lacking integrated logistics.
- Supermarkets:Aeon and Ito-Yokado banners demand premium positioning for functional yogurt alongside economy-tier fluid milk, requiring segmented SKU strategies.
- Online Retail:E-commerce platforms enable subscription-based fresh dairy delivery with cold chain guarantees, capturing urban consumers prioritizing convenience over immediate availability.
- Direct Sales:Farm-gate and cooperative channels bypass retail markups for Hokkaido-sourced products, serving quality-focused buyers seeking provenance transparency.
Convenience stores dominate premium placement; online retail exhibits steepest expansion trajectory as chilled logistics digitization accelerates.
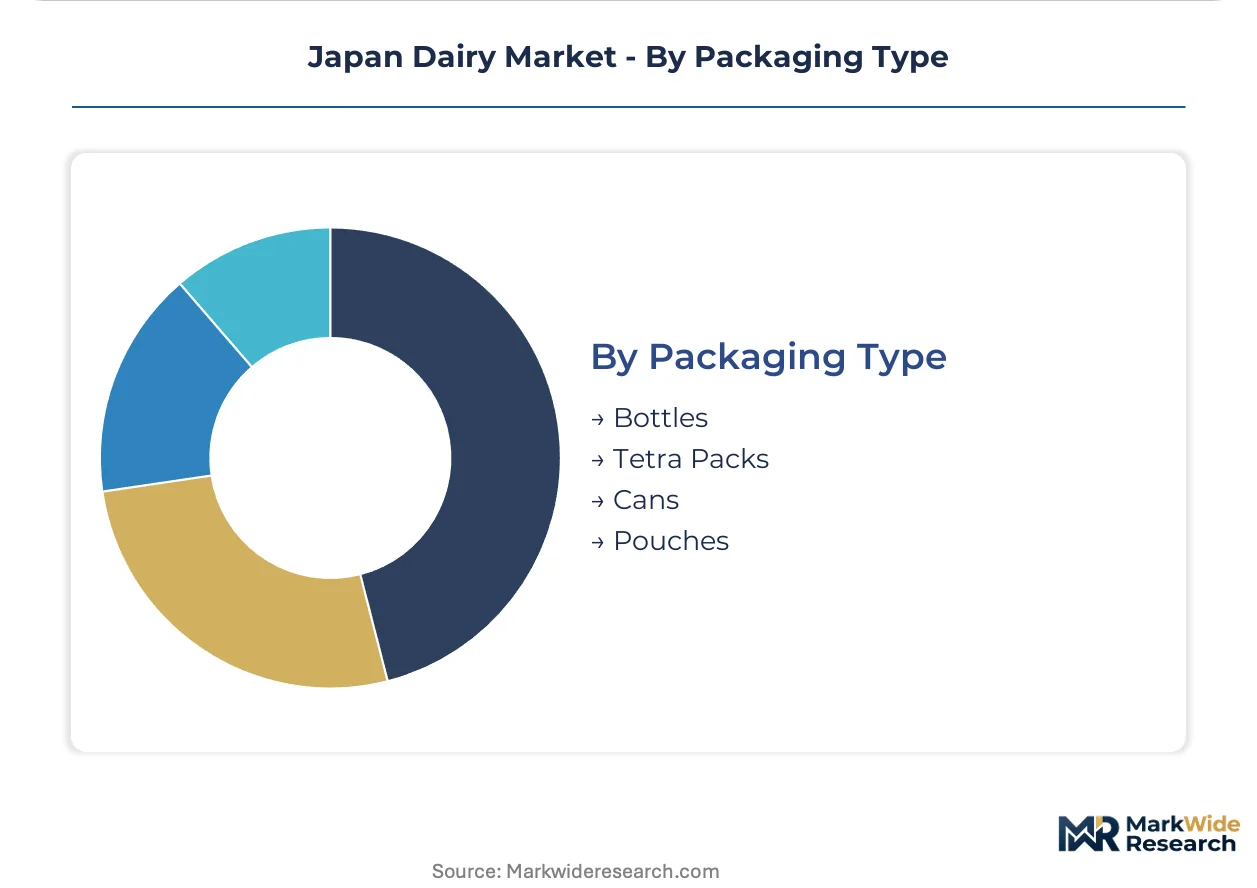
Packaging Type:
GX initiative carbon accounting requirements are reshaping format selection, with disclosure obligations favoring lightweight and recyclable structures in premium positioning.
- Tetra Packs:Aseptic carton formats dominate ambient probiotic drinks and UHT milk, offering extended shelf life without refrigeration and supporting Yakult Honsha's unmatched distribution density.
- Bottles:HDPE and PET containers serve fresh fluid milk and drinking yogurt requiring chilled distribution, with recycled content ratios increasingly specified by major retailers.
- Pouches:Flexible formats reduce material intensity for portion-controlled products, aligning with single-serve consumption patterns in urban convenience retail.
- Cans:Metal packaging retains niche application for specialized cream and evaporated milk products targeting food service manufacturing inputs.
Tetra packs anchor ambient volume; pouches gain share fastest as processors respond to packaging format innovation pressures under carbon footprint disclosure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's dairy exports flow disproportionately into Japanese import channels, with trade volumes concentrated in whey protein and bulk butterfat for food manufacturing applications. This trade corridor shapes competitive dynamics for domestic processors seeking import substitution opportunities.
Kanto/Tokyo
Greater Tokyo's 23 wards concentrate premium chilled distribution infrastructure for functional yogurt and probiotic formats. METI's producer stabilization mechanism intersects with Consumer Affairs Agency labeling enforcement here, forcing simultaneous cost discipline and premium positioning. Convenience store chains in Shibuya and Shinjuku districts consolidate procurement around suppliers with captive ambient and chilled logistics networks.
Kansai/Osaka
Osaka-Kyoto corridors exhibit underpenetration in premium chilled distribution density versus Tokyo, creating expansion runway for functional dairy formats. Aging demographics in this corridor seek protein-fortified and medical-adjacent nutrition products. Kobe and Kyoto industrial zones host mid-tier processors adopting precision fermentation platforms to bypass traditional cooperative supply structures.
Hokkaido
Hokkaido dairy cooperatives supply raw milk under price control mechanisms that cap fluid milk margins regardless of feed cost volatility. Farm-gate and cooperative channels here serve quality-focused buyers seeking provenance transparency. Sapporo and Asahikawa clusters concentrate cooling infrastructure investments required under MHLW Food Sanitation Act standards.
Chubu/Nagoya
Nagoya's manufacturing base drives food service procurement of standardized butter and cheese for operational efficiency. Institutional buyers including Toyota group cafeterias source fluid milk under price-sensitive nutritional program mandates. Aichi prefecture's logistics hubs connect Hokkaido supply to central Japan distribution networks.
Kyushu
Fukuoka's urban corridor captures lactose-intolerant and flexitarian consumers exploring plant-based alternatives in convenience retail. Regional processors face cold chain capex intensity challenges when expanding premium chilled distribution beyond major metros. Kumamoto and Kagoshima agricultural zones supply raw milk with lower transport costs to local processors.
Japan Dairy Market Competitive Landscape
On the supply side, the industry is consolidated around three dominant domestic processors with captive R&D pipelines and specialized distribution networks. Mid-tier regional cooperatives occupy fragmented positions in fluid milk and commodity cheese. The competitive landscape stratifies into functional innovation leaders, scale-driven commodity processors, and niche medical nutrition specialists. Dominant competitive moves include M&A activity targeting chilled logistics capabilities and strategic partnerships with convenience retail chains for shelf placement.
Within the functional innovation tier, Meiji Co. Ltd and Morinaga Milk Industry Co. Ltd exemplify divergent specialization strategies. Meiji occupies a position anchored in probiotic strain development and broad retail distribution. Morinaga represents the medical nutrition specialization archetype, with positioning concentrated in infant and senior-specific formulations. Yakult Honsha Co. Ltd sits within the ambient distribution dominance archetype, leveraging unmatched convenience store channel density for probiotic drink formats.
| Leading Market Players |
|---|
| Meiji Co. Ltd |
| Megmilk Snow Brand Co. Ltd |
| Morinaga Milk Industry Co. Ltd |
| Yakult Honsha Co. Ltd |
| Yotsuba Milk Products Co. Ltd |
| Takanashi Dairy Co. Ltd |
| NH Foods Ltd |
| Rokko Butter Co. Ltd |
| Bel Japon KK |
| Others |
Pricing and Supply Chain Analysis
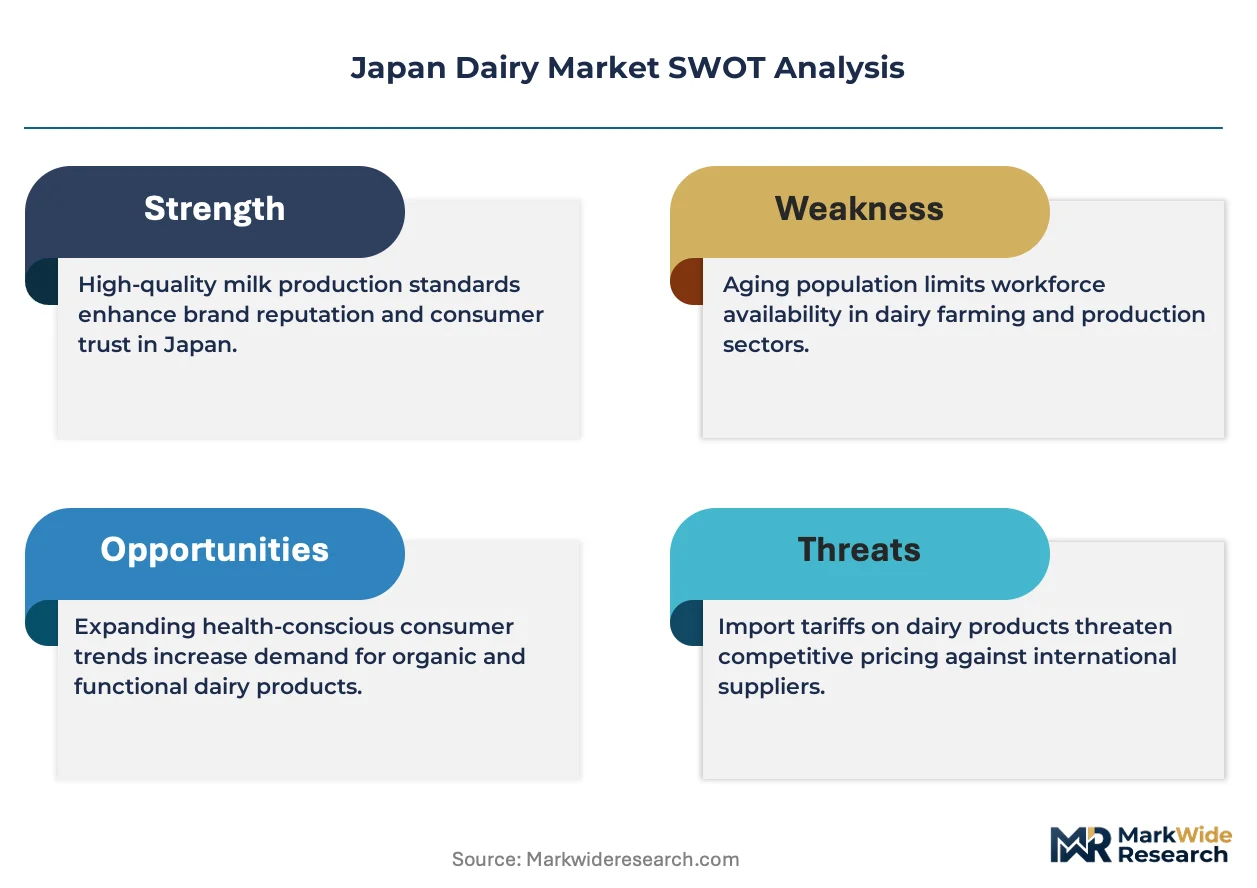
Hokkaido dairy cooperatives anchor Japan's raw milk supply, and their capacity constraints under METI-administered price controls directly compress downstream processor margins while limiting pricing flexibility for fluid milk formats. The geographic concentration of cooling infrastructure investments around Sapporo and Asahikawa clusters creates a supply bottleneck that transmits cost rigidities through to Tokyo metropolitan retail channels.
Pricing Analysis
Precision fermentation technology-generation pricing gaps separate incumbent probiotic strain developers from mid-tier processors adopting enzymatic platforms. Three-tier pricing structure across premium functional yogurt, standard fluid milk, and economy-tier institutional contracts dominates, with differentiation driven by Lactobacillus strain certification levels and chilled distribution density. Cost compression in fluid milk intensifies because raw milk price stabilization caps pass-through of Hokkaido feed cost volatility. Institutional buyers under school nutrition mandates exhibit highest price sensitivity; convenience retail channels seeking functional claim premiums show lowest.
Supply Chain Analysis
Japan's Food Sanitation Act residue controls and cooling standards function as de facto export restrictions on raw milk logistics technology, limiting cross-border processor equipment sourcing. Domestic supply concentrates in Hokkaido cooperatives and Kanto precision fermentation clusters, with critical dependencies on imported whey protein from New Zealand, specialized fermentation enzymes, and pharmaceutical-grade packaging films. Single-source vulnerability runs through Hokkaido cooperative supply structures. Distribution runs through captive chilled networks serving 7-Eleven and Lawson convenience chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's dairy sector sits in early-cycle functional expansion, with precision fermentation adoption and probiotic claim substantiation creating runway for premium format penetration beyond legacy fluid milk commoditization.
For Market Incumbents: Insulate proprietary Lactobacillus strain portfolios through accelerated PMDA medical nutrition pathway filings before competitor reverse engineering erodes differentiation. Deepen backward integration into Hokkaido cooperative supply structures to secure raw milk allocation priority under METI stabilization mechanisms. Lock in exclusive chilled logistics partnerships with Lawson and 7-Eleven to exclude mid-tier processors from premium convenience shelf resets. For New Entrants and Emerging Players: Build out precision fermentation platforms in Kansai's underpenetrated Osaka-Kyoto corridor, where aging demographics seek protein-fortified formats but chilled distribution density lags Tokyo. Target medical nutrition white space under PMDA oversight for infant and senior-specific formulations. Pursue direct-to-institutional subscription models bypassing retail markup concentration. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because convenience retail procurement consolidation around fewer suppliers with integrated chilled networks will compress independent processor valuations and create acquisition opportunities. Monitor METI PLI-style domestic production incentive announcements as inflection signal for sourcing economics reshuffling.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enzymatic processing platforms reduce bioactive peptide production costs for Kanto mid-tier processors. |
| Medical Nutrition Specialization | PMDA pathway filings for infant and senior formulations capture margins beyond commodity yogurt segments. |
| Chilled Distribution Expansion | Captive logistics networks secure placement in 7-Eleven and Lawson shelf resets excluding independents. |
| GX Initiative Compliance | Carbon footprint disclosure investments open premium positioning for low-packaging-intensity formats. |
| Strategic Cooperative Integration | Backward integration into Hokkaido supply structures secures raw milk allocation under price controls. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy processing executives, chilled logistics network managers, convenience retail category buyers, and PMDA regulatory affairs specialists. Secondary validation drew from METI production statistics, Consumer Affairs Agency labeling enforcement records, MHLW Food Sanitation Act compliance filings, and Hokkaido cooperative supply reports. Bottom-up volume modeling triangulated against top-down value estimates across product type, end user, distribution channel, and packaging format segmentation.
Calibration anchored historical consumption patterns against functional claim adoption curves and precision fermentation capacity buildouts across the projection horizon. Segmentation dimensions modeled included product format, distribution channel density, GX initiative compliance tier, and regional consumption cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating aging demographic shifts and plant-based substitution rates.
Stress conditions across raw milk price control rigidity, probiotic claim substantiation timelines, and chilled logistics capex intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on METI policy continuity and Consumer Affairs Agency enforcement velocity. Material shifts in PLI incentive structures or Food Labeling Standards Act revision scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Canada Dairy Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Dairy Protein Market
Dairy Products
Japan Casein Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Cream Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Fluid Milk Market
Dairy Products
A2 Milk Market
Dairy Products
Citrus Yogurt Market