
 Gluten-Free Soup Market | 2026-2036
Gluten-Free Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Soup Market Foresight
A wide capital-intensity divergence between players is rotating competitive advantage toward manufacturers with dedicated allergen-free facilities versus shared-line operators. Campbell Soup Company leverages its North American distribution infrastructure to sustain retail penetration across conventional and natural channels. Amy's Kitchen differentiates through organic-ingredient positioning and controls a premium price tier in frozen formats. General Mills anchors volume through scale economics in dry soup mix production.
Gluten-free soup comprises prepared food products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting starches from rice, corn, or legumes to achieve comparable viscosity and mouthfeel. Manufacturers employ enzymatic testing and segregated production zones to maintain gluten levels below regulatory thresholds, primarily serving consumers with celiac disease, gluten sensitivity, or elective dietary avoidance. Canned soup leads absolute revenue due to pantry-stocking behavior and extended shelf stability, while liquid soup in refrigerated formats captures faster growth as meal-kit services and direct-to-home delivery expand. Grain-based ingredient formulations occupy the deepest margin pools where ancient grains command premium positioning, though legume-based recipes gain traction among protein-seeking consumers.
The FDA enforces gluten-free labeling standards at 20 parts per million, while EFSA coordinates harmonized thresholds across EU member states through implementing regulation 828/2014; both frameworks compel ingredient traceability and facility segregation investments. The USDA Organic seal intersects with gluten-free claims in dual-certified products, adding audit complexity but unlocking shelf placement in natural retailers. Stakeholders must monitor evolving FODMAP and low-histamine dietary trends that could fragment the free-from category further.
Market Dynamics
Dedicated allergen-free production lines are becoming the decisive competitive moat as FDA and EFSA cross-contamination thresholds tighten below 20 parts per million, forcing capital reallocation away from shared-facility operators.
Growth Catalysts
- Celiac disease prevalence:Diagnosed cases in the United States and Western Europe expand the clinical consumer base requiring certified gluten-free formulations.
- Implementing Regulation 828/2014:EFSA harmonization across EU member states reduces regulatory fragmentation, simplifying pan-European product launches for compliant manufacturers.
- Meal-kit delivery channels:Refrigerated liquid soup formats gain velocity through direct-to-home subscription services targeting convenience-seeking households.
Market Restraints
- Input cost volatility:Ancient grain starches from quinoa and amaranth face price instability tied to South American harvest cycles and climate variability.
- Facility segregation requirements:Dedicated production zones demand capital outlays that disadvantage smaller shared-line operators competing on thin margins.
- Substitution threat:Low-FODMAP and low-histamine dietary protocols fragment the free-from category, diverting consumer attention from gluten-specific claims.
Strategic Opportunities
- Underpenetrated India:Rising diagnosed celiac cases and urban health consciousness create first-mover potential for certified imports in metropolitan retail.
- Protein-forward legume formulations:Lentil and chickpea bases attract fitness-oriented consumers seeking macronutrient density beyond allergen avoidance.
- USDA Organic intersection:Dual-certified gluten-free and organic products unlock premium shelf placement in natural retail channels with margin expansion.
Industry Challenges
- Enzymatic testing talent scarcity:Laboratory technicians skilled in gluten quantification below 20 ppm thresholds command premium wages, constraining quality control scaling.
- Legacy ERP integration:Ingredient traceability systems required for FDA compliance clash with dated inventory management platforms, delaying lot-tracking implementation.
- Certification timeline compression:Third-party gluten-free audits face backlogs, extending product launch windows and freezing working capital in pipeline inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Soup Market |
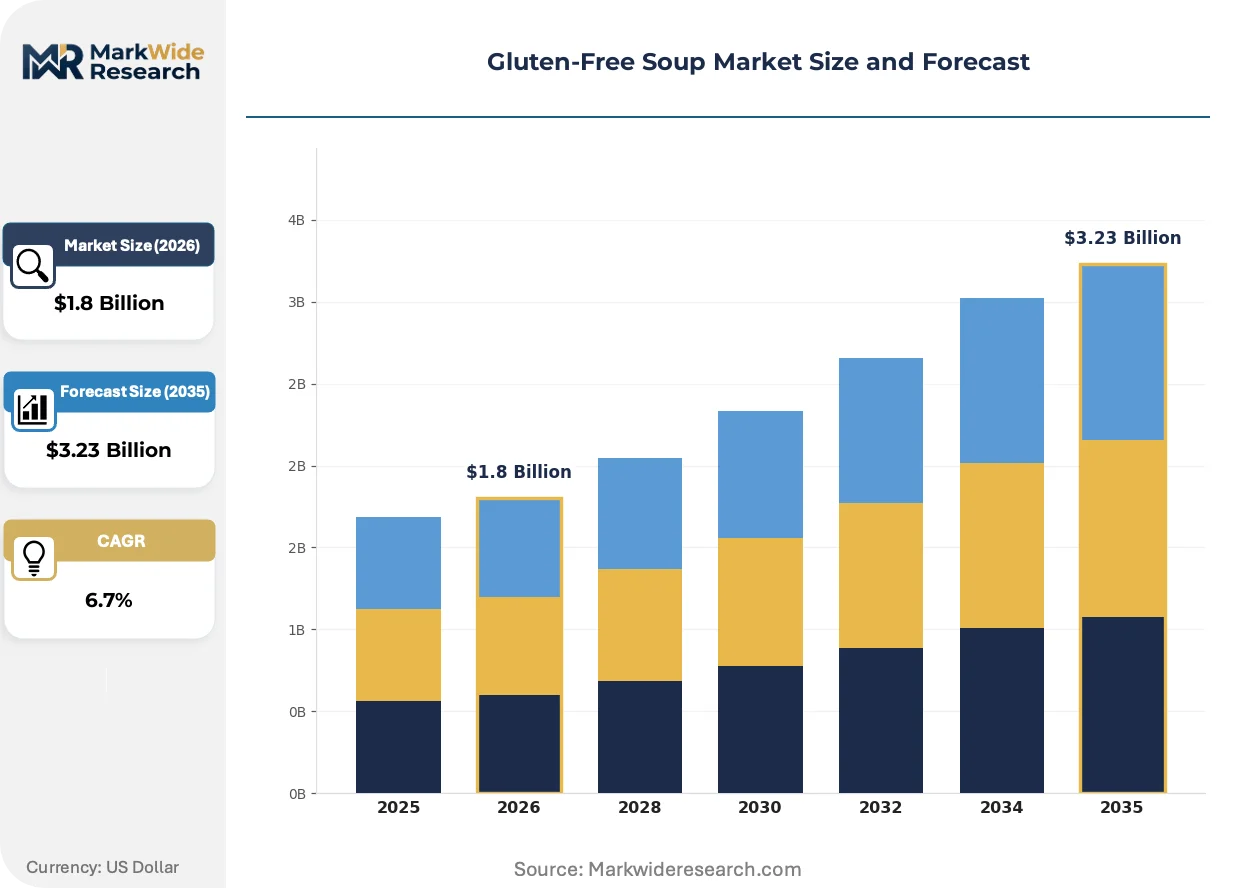
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soup, Dry Soup Mix, Frozen Soup, Liquid Soup Ingredient Type: Vegetable-Based, Legume-Based, Grain-Based, Seafood-Based Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops End User: Households, Restaurants, Cafes, Meal Kit Services |
| Companies Covered | Campbell Soup Company, General Mills, Amy's Kitchen, Pacific Foods, Conagra Brands, Kraft Heinz Company, Kikkoman Corporation, The Hain Celestial Group, Barilla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Soup Market Shifts & Advancements
Production technology and distribution architecture are undergoing parallel transformation as enzymatic detection advances collide with direct-to-consumer channel maturation.
Enzymatic testing protocols for gluten quantification are bifurcating manufacturing investment between mass-market dry mix producers and premium refrigerated specialists. Large-scale Campbell Soup Company facilities deploy high-throughput lateral flow devices for rapid batch release, while Amy's Kitchen and organic-positioned competitors adopt ELISA-based laboratory verification for dual-certified organic claims. This technological split is compressing mid-tier shared-line operators who lack capital for either automation tier.
EFSA implementing regulation 828/2014 tightens gluten-free labeling enforcement across EU member states, compelling manufacturers to document supply chain segregation from farm to finished good. Industrial consequence includes mandatory third-party audit cycles and ingredient traceability investments that favor vertically integrated starch suppliers. Southern European markets with higher celiac diagnosis rates show fastest compliance adoption, pressuring importers from non-harmonized jurisdictions.
Direct-to-home refrigerated soup subscriptions displace conventional pantry-stocking behavior among urban millennials and Gen Z households. Meal-kit services and specialty e-commerce platforms capture volume previously routed through brick-and-mortar grocery, compressing traditional retail slotting fee economics. This channel rotation concentrates in United States coastal metropolitan areas where cold-chain logistics density supports last-mile freshness guarantees.
Gluten-Free Soup Market Segmentation
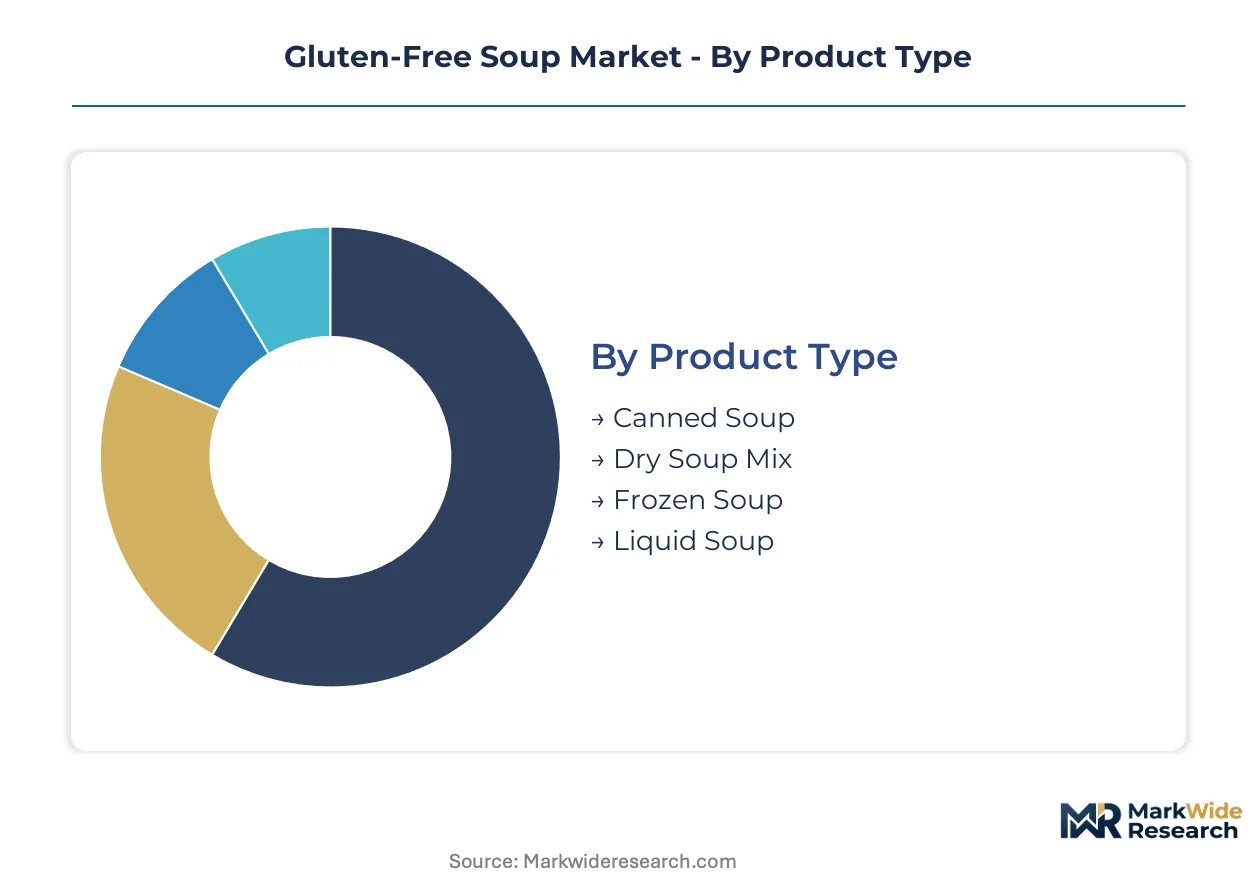
Segmentation in gluten-free soup reveals how manufacturing capabilities, ingredient sourcing, and channel economics create distinct competitive battlegrounds. Margin pools concentrate where certification complexity intersects with format-specific production investments.
Product Type:
Premium margin capture diverges sharply between shelf-stable formats requiring capital-intensive retort infrastructure and refrigerated products demanding cold-chain density.
- Canned Soup:Retort-sterilized aluminum or steel packaging delivers 24-36 month shelf stability through thermal processing. Pantry-stocking behavior in United States suburban households sustains volume, though slotting fees at Kroger and Albertsons compress net margins for mid-tier entrants.
- Liquid Soup:Refrigerated aseptic cartons and modified-atmosphere packaging preserve fresh flavor profiles for 30-60 days. Direct-to-home subscription velocity in coastal metropolitan areas—particularly Seattle and San Francisco—drives fastest expansion as meal-kit services displace conventional grocery trips.
- Dry Soup Mix:Dehydrated vegetable and starch blends packaged in laminated pouches offer lightweight logistics and extended ambient storage. Manufacturing concentrates in Midwest grain-processing corridors where rice and corn starch supply chains achieve scale.
- Frozen Soup:Blast-frozen formulations in microwaveable tubs target convenience-oriented households with premium positioning. Cold-storage slotting at Whole Foods and Sprouts unlocks dual-certified organic placement.
The dominant share belongs to Canned Soup, while Liquid Soup is closing the gap fastest.
Ingredient Type:
Input cost structures and protein positioning separate commodity-driven formulations from premium ancient-grain and legume alternatives.
- Grain-Based:Rice, corn, quinoa, and amaranth starches replicate wheat-derived viscosity through modified starch chemistry. Quinoa and amaranth sourcing from Peruvian and Bolivian highlands introduces harvest-cycle price volatility that favors vertically integrated processors with forward-contracting capabilities.
- Legume-Based:Lentil, chickpea, and white bean bases deliver 8-12 grams protein per serving, attracting fitness-oriented consumers beyond strict gluten-avoidance. Amy's Kitchen and Pacific Foods anchor this segment with organic supply chain investments.
- Vegetable-Based:Tomato, squash, and root-vegetable purees with minimal starch addition serve calorie-conscious and low-carb dietary protocols. Clean-label positioning avoids modified food starch declarations that trigger consumer skepticism.
- Seafood-Based:Clam chowder, lobster bisque, and fish-stock formulations target coastal demographics with premium price acceptance. Supply chain complexity from marine-sourced inputs limits national distribution reach.
Grain-Based formulations command the deepest margin pools, though Legume-Based alternatives are expanding most quickly.
Distribution Channel:
Channel economics stratify between high-volume conventional retail and relationship-driven specialty placement with divergent working capital requirements.
- Supermarkets:Kroger, Safeway, and Publix shelf sets drive mass-market penetration through end-cap promotions and seasonal displays. Planogram compliance demands case-volume minimums that exclude micro-producers lacking co-packer relationships.
- Online Retail:Amazon Fresh, Thrive Market, and brand-direct storefronts capture subscription-driven replenishment with customer data feedback loops. Last-mile cold-chain investment requirements filter out ambient-only product lines.
- Health Food Stores:Whole Foods, Sprouts, and independent natural retailers enforce dual-certified organic and gluten-free standards with margin premiums. Local-for-local procurement preferences favor regional manufacturers within 200-mile radius.
- Specialty Shops:European import grocers, celiac-specific boutiques, and hospital retail pharmacies serve diagnosed consumers with prescription-adjacent positioning. Limited SKU breadth concentrates on medical-necessity messaging over lifestyle marketing.
Supermarkets maintain volume leadership, while Online Retail is gaining share fastest.
End User:
Demand concentration patterns separate institutional foodservice procurement from household replenishment behaviors with distinct price elasticity profiles.
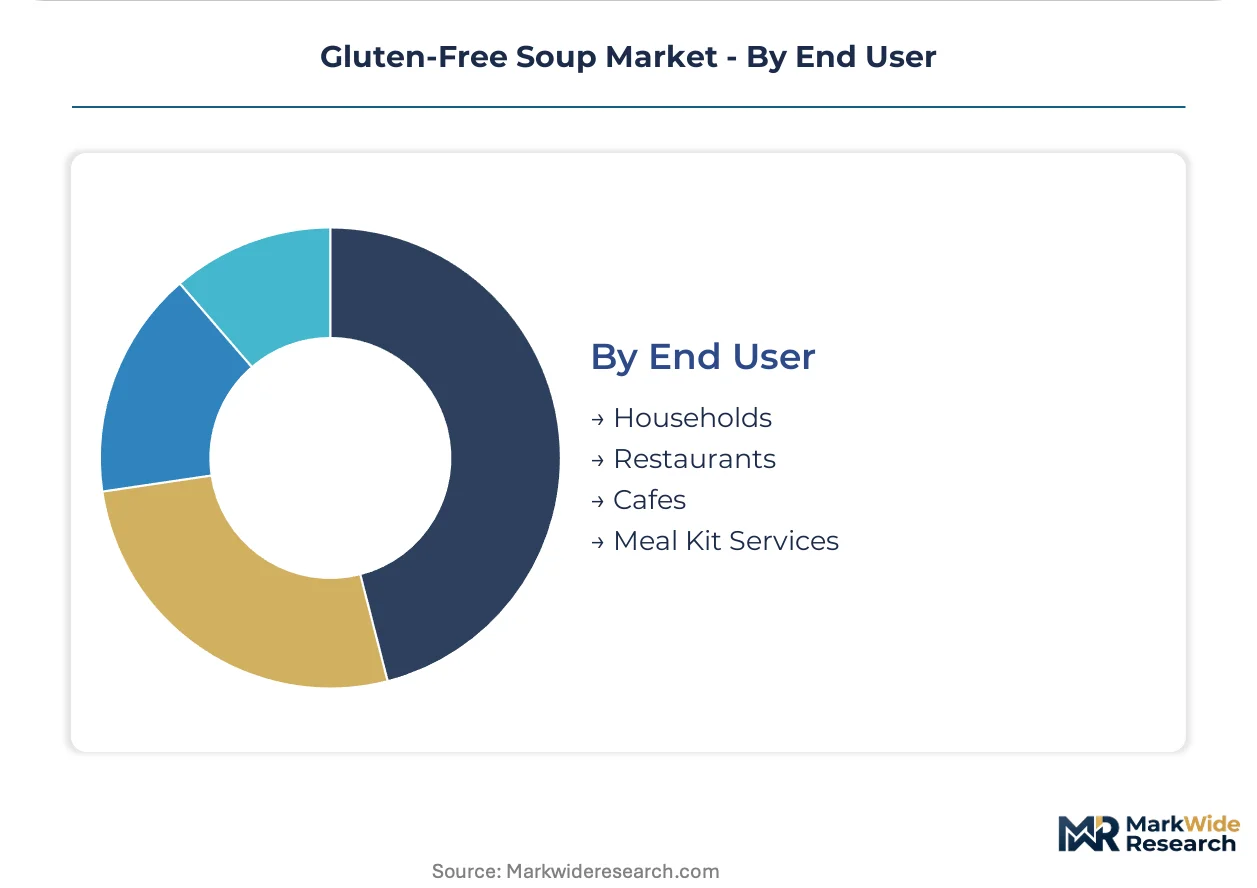
- Households:Individual and family units purchasing for home consumption drive pantry-stocking velocity in canned and dry formats. Celiac diagnosis rates in United States pediatric populations expand the clinical necessity segment beyond elective dietary trends.
- Meal Kit Services:Blue Apron, Sunbasket, and regional subscription platforms specify refrigerated liquid soups as center-plate components. Contract manufacturing relationships with dedicated allergen-free facilities create supply exclusivity.
- Restaurants:Casual dining and fast-casual chains with gluten-free menu protocols source frozen soup in foodservice packs. Cross-contamination liability concerns push procurement toward certified suppliers with third-party audit documentation.
- Cafes:Independent coffee shops and bakery-cafes offer single-serve cups and grab-and-go containers for lunch occasion capture. Limited cold-storage footprint favors shelf-stable ambient formats over frozen or refrigerated alternatives.
Households anchor absolute demand, while Meal Kit Services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households in suburban United States markets show the highest price elasticity, accepting premium positioning for certified gluten-free claims, while price-sensitive buyers in emerging Asian markets prioritize basic allergen avoidance without certification premiums.
United States
Diagnosed celiac disease prevalence among pediatric populations and elective gluten-free adherence among fitness-oriented millennials drive dual demand streams. The FDA enforces the 20 parts per million labeling threshold through its Food Safety Modernization Act traceability mandates. Chicago and Minneapolis anchor Midwest dry soup mix production corridors where rice and corn starch supply chains achieve manufacturing scale.
Germany
Western Europe's highest diagnosed celiac rate per capita underpins clinical-necessity demand distinct from lifestyle-driven purchasing elsewhere. EFSA implementing regulation 828/2014 harmonizes gluten-free standards across EU member states, reducing cross-border compliance friction. Bavaria hosts dedicated allergen-free manufacturing clusters where third-party audit documentation supports pan-European distribution.
United Kingdom
Free-from aisle expansion at Tesco and Sainsbury's signals retailer commitment to allergen-free prepared foods beyond niche positioning. The Food Standards Agency enforces gluten labeling through retained EU law post-Brexit, maintaining alignment with EFSA thresholds. Greater Manchester and West Yorkshire concentrate co-packing capacity serving both domestic retail and Irish export channels.
Canada
Cross-border supply chain integration with United States manufacturers creates pricing pressure on domestic producers lacking scale economies. Health Canada maintains gluten-free labeling guidance consistent with FDA 20 ppm standards, facilitating import recognition. Toronto and Vancouver metropolitan areas drive refrigerated liquid soup velocity through meal-kit subscription penetration in urban households.
Australia
High per-capita celiac diagnosis rates and strong health-food retail culture support premium positioning for certified organic-gluten-free intersection products. Food Standards Australia New Zealand mandates gluten-free claims through Standard 1.2.8, with enforcement through state-based health departments. Melbourne and Sydney anchor natural retailer concentration where dual-certified products command shelf placement premiums.
Gluten-Free Soup Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Gluten-Free Soup Market, with capital-intensity divergence rotating advantage toward dedicated facility operators. Mass-market dry mix producers leverage Midwest grain-processing corridors for input cost control, while refrigerated specialists concentrate in coastal metropolitan logistics hubs. Three archetypes define competitive positioning: diversified food conglomerates with allergen-free line extensions, organic-certified specialists with dual-label premiums, and contract manufacturers serving meal-kit subscription channels. Capacity expansion into dedicated production zones and backward integration into certified starch supply chains constitute the dominant competitive moves reshaping manufacturer economics.
Within the diversified conglomerate tier, Campbell Soup Company and General Mills occupy positions anchored by North American distribution infrastructure and scale economics in shelf-stable formats. Amy's Kitchen exemplifies the organic-specialist archetype, with its company name signaling kitchen-positioned branding that supports premium tier placement in natural retail channels. Pacific Foods represents refrigerated format specialists where cold-chain density and direct-to-home subscription relationships create competitive differentiation.
| Leading Market Players |
|---|
| Campbell Soup Company |
| General Mills |
| Amy's Kitchen |
| Pacific Foods |
| Conagra Brands |
| Kraft Heinz Company |
| Kikkoman Corporation |
| The Hain Celestial Group |
| Barilla |
| Others |
Supply & Pricing Matrix
FDA gluten-free labeling thresholds at 20 parts per million simultaneously gate supply qualification and stratify price tiers, forcing manufacturers to absorb certification costs into premium positioning while shared-line operators face margin compression from compliance investments.
Pricing Analysis
After-sales revenue from subscription replenishment and direct-to-home delivery contracts drives lifetime value differentiation in this market. Three-tier pricing structure across premium, standard, and economy levels separates dual-certified organic products from conventional gluten-free claims and private-label alternatives. Price differentiation stems from certification grade and volume scale, with USDA Organic intersection commanding shelf placement premiums. Cost compression in the mid-tier is intensifying because enzymatic testing talent scarcity raises quality control overhead. Households with diagnosed celiac members show lowest price sensitivity, while elective dietary adherents in mass retail channels drive promotional velocity.
Supply Chain Analysis
Strategic stockpiling of ancient grain starches dominates inventory strategy as South American harvest cycles introduce input volatility that justifies forward-contracting positions. Supply concentrates in Peru and Bolivia for quinoa and amaranth sourcing, while Midwest United States anchors rice and corn starch processing. Raw material dependencies include modified starch chemistry inputs, legume protein isolates, and aseptic packaging substrates. Single-source vulnerability from Andean highland agriculture exposes margin stability to climate-induced yield variation. Distribution runs through refrigerated cold-chain hubs in coastal metropolitan areas for liquid formats, with ambient dry goods flowing through conventional grocery distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as tightening regulatory thresholds force capital reallocation waves that favor prepared manufacturers with dedicated facilities during compliance upgrade cycles.
For Market Incumbents: Compound defensive positioning through backward integration into certified starch supply chains and capacity expansion in dedicated allergen-free production zones. Amy's Kitchen and Pacific Foods demonstrate how organic supply chain control neutralizes input volatility threats. Certification investment in dual USDA Organic and gluten-free claims secures natural retail channel leverage against private-label encroachment. For New Entrants and Emerging Players: Lead with refrigerated liquid soup formats targeting meal-kit subscription channels where contract manufacturing relationships create supply exclusivity. Underpenetrated metropolitan India offers first-mover potential for certified imports as diagnosed celiac cases rise. Direct-to-home positioning with protein-forward legume formulations captures fitness-oriented consumers beyond strict allergen avoidance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across refrigerated format specialists as cold-chain density requirements escalate. Long-term viability favors manufacturers with captive supply of certified ancient grains and established third-party audit documentation. The signal to monitor is EFSA enforcement harmonization progress, which will accelerate consolidation pressure on non-compliant importers.| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Allergen-Free Facility Investment | Campbell Soup Company leverages this to sustain retail penetration across conventional and natural channels with compliance certainty. |
| Backward Integration into Certified Starch Supply | Vertical control over quinoa and amaranth sourcing neutralizes Peruvian harvest cycle volatility for premium positioning. |
| Meal-Kit Subscription Channel Partnership | Blue Apron and Sunbasket specifications for refrigerated liquid soups displace conventional pantry-stocking economics. |
| Dual USDA Organic Certification Pursuit | Whole Foods and Sprouts enforce this standard for shelf placement premiums in natural retail channels. |
| ELISA-Based Laboratory Verification Upgrade | Amy's Kitchen deploys this for organic-positioned competitors seeking precision below FDA 20 ppm thresholds. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at Kroger and Whole Foods, supply planners, and regulatory affairs leads anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from FDA gluten-free labeling guidance, EFSA implementing regulation 828/2014 documentation, Nielsen retail audit data, and SEC filings from diversified food conglomerates. Bottom-up and top-down triangulation cross-checked volume estimates against production capacity disclosures and import trade records.
Sensitivity analysis across multiple scenario assumptions tested forecast robustness throughout the projection horizon. The analytical framework modeled segmentation dimensions including product format, ingredient base, distribution channel, and end-user procurement pattern. CAGRs were derived from regression analysis of historical volume trends and elasticity-adjusted demand projections. Industry-specific forecast inputs included celiac diagnosis rate trajectories and cold-chain logistics density metrics for refrigerated format penetration.
Underlying assumptions cover sustained FDA and EFSA enforcement intensity, with deviation risk concentrated in regulatory threshold modifications or accelerated substitution by low-FODMAP dietary protocols. Forecasts reflect these documented assumptions with explicit scenario weighting. Revision becomes warranted when EFSA harmonization adoption rates across Southern European markets cross acceleration thresholds that alter pan-European competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market