
 IP Geo-Location Services Market | 2026-2036
IP Geo-Location Services Market Size, Share, and Industry Trends Forecast 2026-2036
IP Geo-Location Services Market Foresight
Modular API packaging is recalibrating buyer choice across the IP geo-location landscape, as enterprises shift from monolithic platforms to discrete, purpose-built service modules. Akamai Technologies, Inc. leverages its edge network density to embed location intelligence directly into content delivery workflows. MaxMind, Inc. specializes in high-precision IP databases that anchor fraud detection stacks for financial institutions. Digital Element, Inc. competes through real-time mobile geolocation granularity that supports streaming and advertising use cases.
IP geo-location services map internet protocol addresses to physical coordinates using proprietary database algorithms, BGP routing analysis, and Wi-Fi positioning triangulation, typically resolving location to city-level precision with latency under 100 milliseconds for real-time applications. The primary commercial purpose spans content localization, transaction security verification, and regulatory compliance for cross-border data handling. Geolocation API deployments dominate transaction volumes due to their integration simplicity, while fraud detection applications command premium pricing because of the direct cost-avoidance value they deliver to financial services and e-commerce end users. Cloud-based deployment models absorb the majority of new capacity, though hybrid configurations persist among telecommunications carriers managing sovereign data requirements.
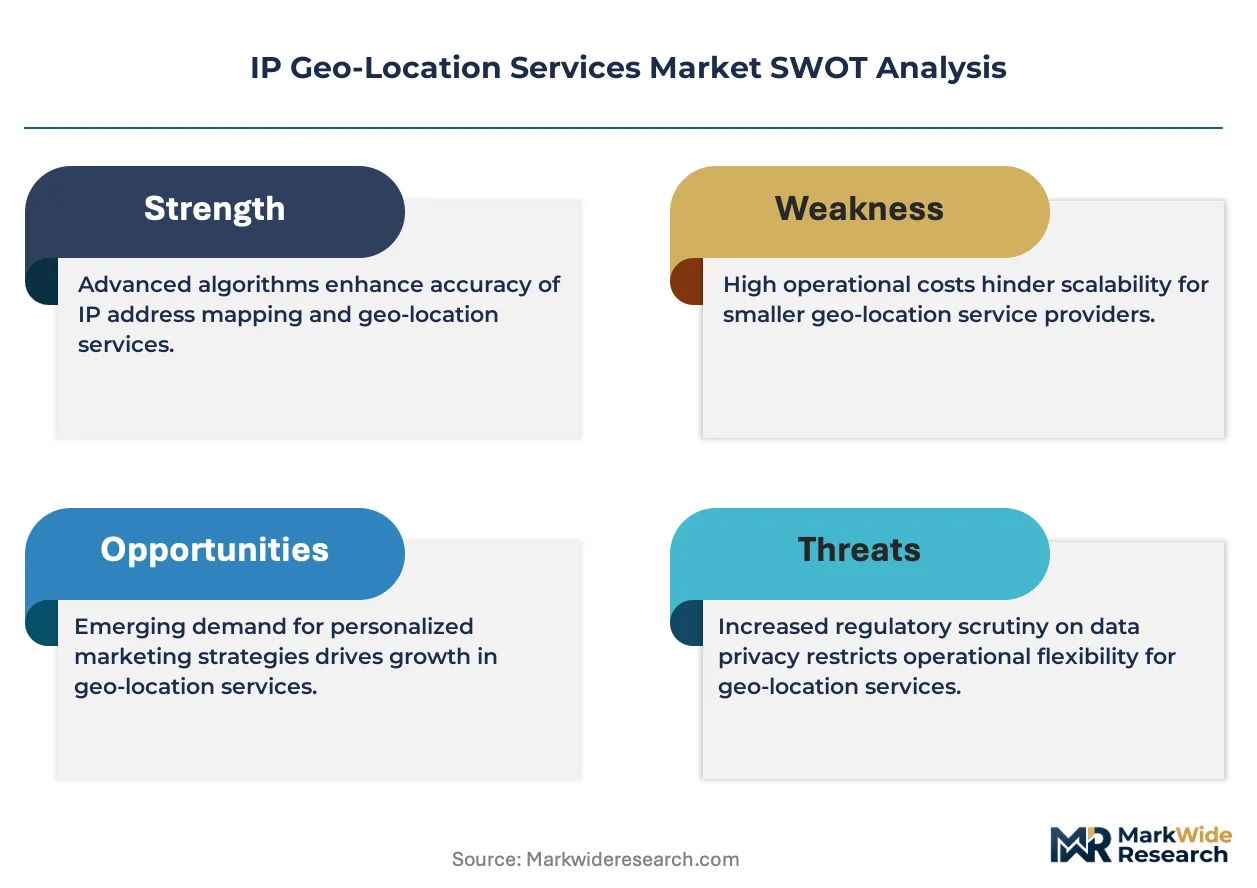
FCC guidelines on emergency service location accuracy, EU GDPR data localization mandates, and the California Consumer Privacy Act collectively shape product architecture and market access requirements for providers serving North American and European buyers. These frameworks demand audit-ready data provenance, forcing vendors to maintain transparent sourcing for IP registry and carrier-derived location signals. Stakeholders must monitor evolving national data sovereignty laws to determine whether in-region database hosting becomes a competitive prerequisite rather than a premium option.
Market Dynamics
Modular API packaging is fragmenting buyer procurement patterns across the IP geo-location landscape, as enterprises dismantle monolithic platform contracts in favor of discrete, purpose-built service modules that integrate directly into existing security and content delivery stacks.
Growth Catalysts
- Fraud Prevention Mandates:Financial services firms deploy IP geo-location for real-time transaction verification, driven by regulatory pressure from the EU's Digital Services Act and GDPR location transparency requirements.
- Edge Network Density:Cloud infrastructure providers embed location intelligence into content delivery workflows, reducing latency below 100 milliseconds for streaming and advertising use cases.
- Wi-Fi Positioning Triangulation:Mobile operators leverage carrier-derived signals to enhance real-time geolocation granularity, supporting emergency service accuracy guidelines from the FCC.
Market Restraints
- Data Provenance Auditing:Vendors must maintain transparent sourcing for IP registry and carrier-derived signals, increasing compliance overhead under GDPR data localization mandates.
- BGP Routing Volatility:Border Gateway Protocol analysis depends on registry data quality that degrades in emerging markets with fragmented internet exchange infrastructure.
- Carrier Concentration Risk:Location signal accuracy concentrates among tier-one telecommunications operators in the United States and Western Europe, limiting precision in secondary markets.
Strategic Opportunities
- India Digital Infrastructure:TRAI mandates for telecom service quality create demand for domestic IP geo-location hosting as data sovereignty requirements harden.
- AI-Driven Anomaly Detection:Machine learning convergence with geolocation databases enables predictive fraud scoring that compresses false-positive rates for payment processors.
- API Marketplace Distribution:Cloud provider marketplaces offer new channel access for specialized geolocation modules, bypassing traditional enterprise sales cycles.
Industry Challenges
- Legacy System Integration:Financial institutions face friction embedding real-time geolocation APIs into core banking platforms built on decades-old transaction processing architectures.
- Cross-Border Compliance Timeline:Vendors must navigate divergent data localization requirements across the EU, India, and China, extending product certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IP Geo-Location Services Market |
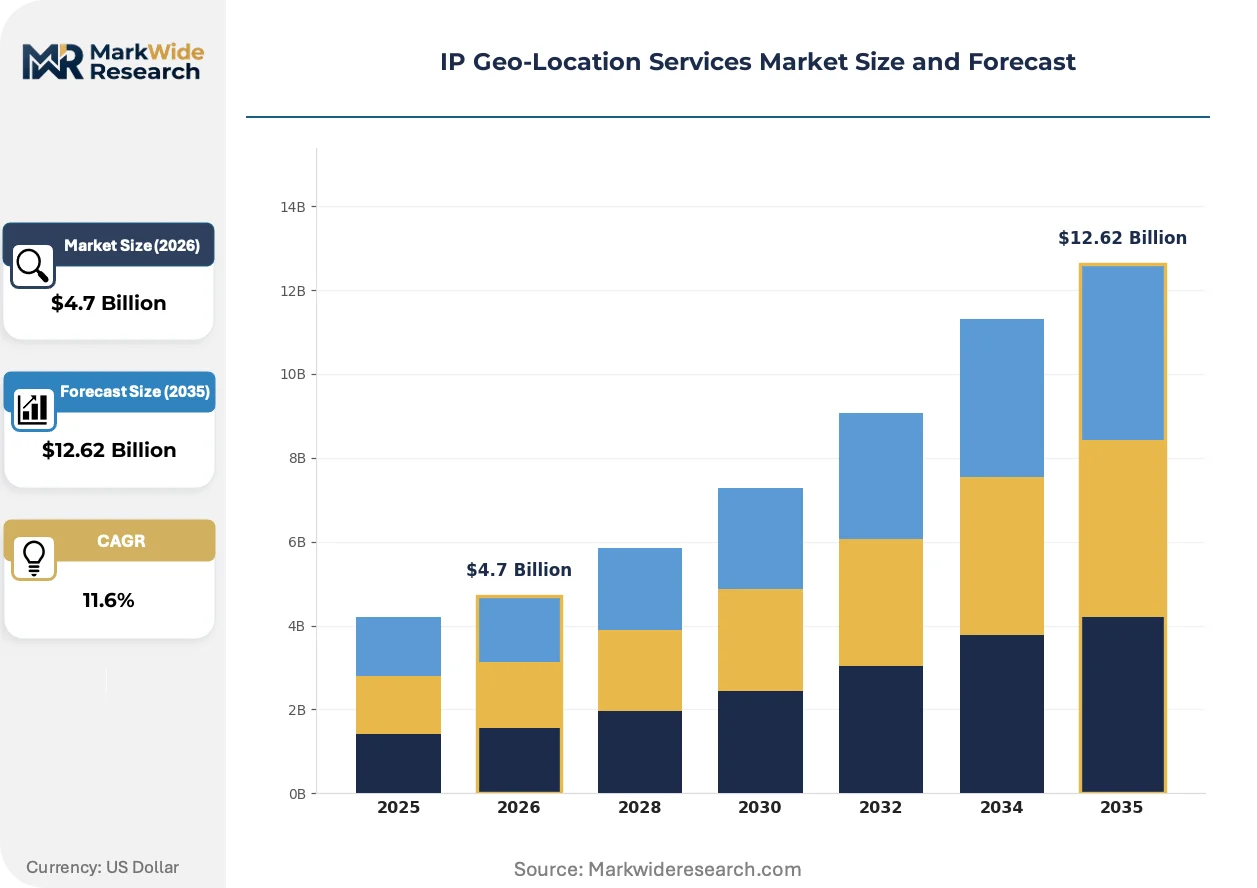
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data API, Geolocation API, Mobile Geolocation, IP Address Verification Application: Content Delivery, Fraud Detection, Marketing Personalization, Traffic Monitoring End User: E-commerce, Telecommunications, Financial Services, Cybersecurity Deployment: Cloud-Based, On-Premises, Hybrid, SaaS |
| Companies Covered | MaxMind, Inc., Neustar, Inc., Google Cloud, Akamai Technologies, Inc., Pitney Bowes Inc., IP2Location, Ipstack, Digital Element, Inc., BigDataCloud Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IP Geo-Location Services Market Shifts & Advancements
Edge computing architectures and privacy-preserving signal processing are compressing the latency-accuracy trade-off that historically constrained real-time geolocation deployments. Three developments merit particular attention.
Containerized microservices architectures for geolocation databases are modularizing how enterprises consume location intelligence. Fraud detection teams at payment processors now deploy discrete IP reputation modules alongside city-level precision APIs, mixing accuracy tiers within single transaction flows. This decomposition is compressing average contract values while expanding total addressable touchpoints per customer.
The EU AI Act's risk classification framework for automated decision-making systems is forcing geolocation vendors to document algorithmic provenance for fraud scoring applications. Providers serving European financial institutions must now maintain audit trails linking IP address inputs to physical coordinate outputs. German and French regulators are conducting the first enforcement actions against opaque location inference methods.
Self-service API portals with usage-based metering are displacing annual enterprise licenses for mid-market e-commerce platforms. Merchants in Southeast Asia and Latin America now onboard geolocation services through cloud marketplaces without direct vendor negotiation. This channel shift is visible most acutely among direct-to-consumer brands seeking rapid international expansion without dedicated procurement functions.
IP Geo-Location Services Market Segmentation
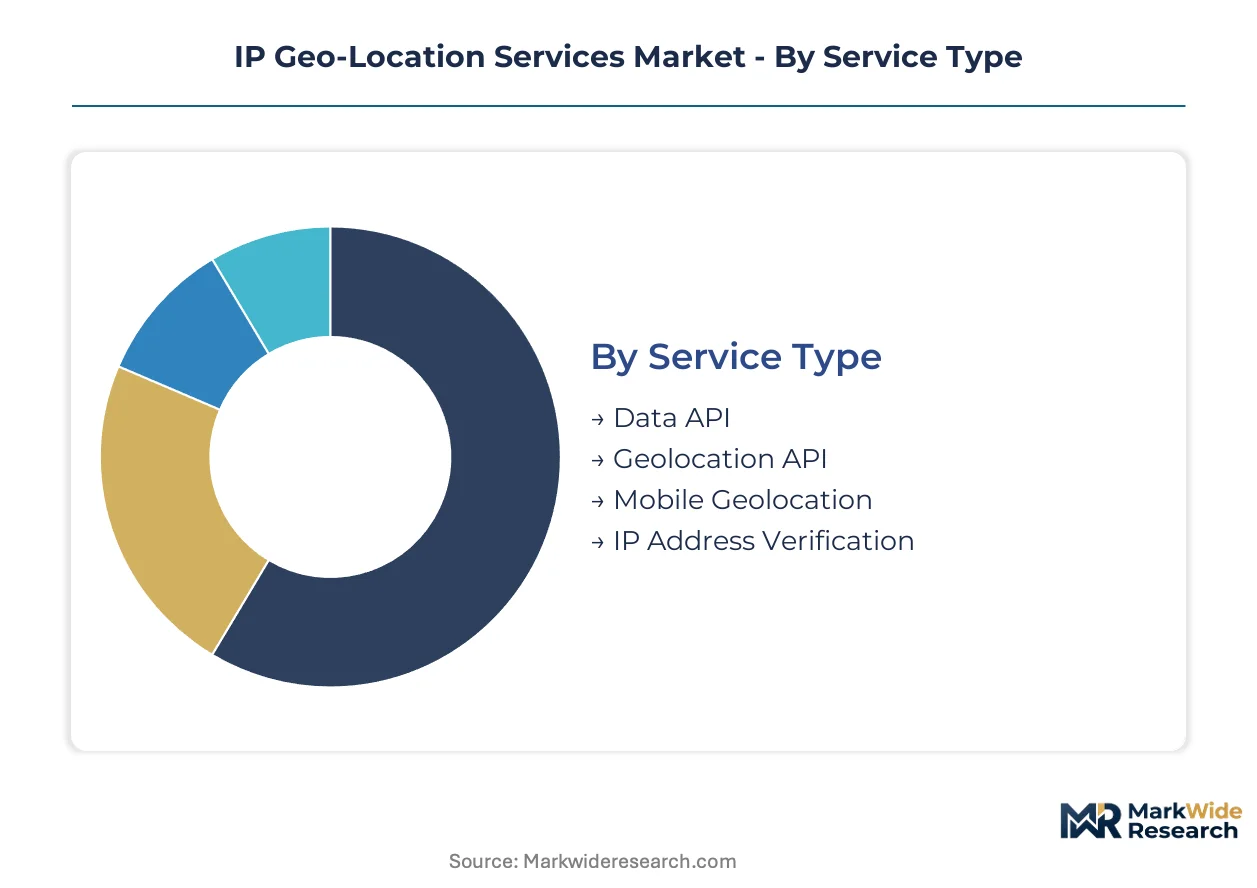
IP geo-location services fragment across four distinct dimensions that shape procurement complexity and integration requirements. Each segmentation axis carries unique certification burdens and pricing architectures that vendors must navigate to capture enterprise contracts.
Service Type:
GDPR audit trails and FCC emergency accuracy mandates impose divergent compliance obligations across service modalities, with real-time APIs facing stricter latency-documentation requirements than batch-processing alternatives.
- Geolocation API:Real-time RESTful endpoints resolve IP addresses to city-level coordinates within sub-100 millisecond response windows. Financial services firms in Germany and France concentrate demand here, driven by EU AI Act documentation requirements for automated fraud scoring.
- Data API:Bulk database access enables offline IP-to-location mapping for analytics workloads and historical pattern analysis. Cybersecurity vendors in the United States embed these feeds into SIEM platforms, prioritizing coverage breadth over query speed.
- Mobile Geolocation:Carrier-derived signal triangulation enhances precision for device-based positioning.
- IP Address Verification:Validation services confirm address authenticity and registry provenance.
Geolocation API sits at the top of the volume ranking, with Mobile Geolocation climbing the fastest.
Application:
Margin structures diverge sharply by use case, with fraud detection commanding premium per-transaction pricing while content delivery scales on commodity API call volumes.
- Fraud Detection:Real-time risk scoring during payment authorization demands sub-50 millisecond location verification with carrier-grade signal provenance. E-commerce platforms in Southeast Asia drive expansion here, integrating geolocation into 3D Secure authentication flows.
- Content Delivery:Edge server selection and language localization rely on coarse-grained country-level precision. Streaming services optimize caching decisions through lightweight API calls that prioritize cost efficiency over coordinate accuracy.
- Marketing Personalization:Audience segmentation and localized offer targeting.
- Traffic Monitoring:Geographic distribution analysis for network security and capacity planning.
Fraud Detection captures the highest margin tier, with Content Delivery expanding most quickly across mid-market SaaS platforms.
End User:
Procurement sophistication varies dramatically by sector, with financial institutions demanding SOC 2 Type II attestations while telecommunications carriers negotiate sovereign hosting clauses.
- Financial Services:Payment processors and digital banks deploy geolocation for transaction anomaly detection and regulatory reporting. EU GDPR location transparency mandates and the Digital Services Act create binding compliance obligations that elevate vendor selection criteria.
- Cybersecurity:Threat intelligence platforms correlate IP geolocation with attack attribution and botnet tracking. Managed security service providers in the United States integrate these feeds into automated incident response workflows.
- E-commerce:Merchant platforms use location data for shipping validation and regional pricing.
- Telecommunications:Mobile operators leverage internal signal databases for subscriber services.
Financial Services anchors revenue concentration, with Cybersecurity gaining share fastest among cloud-native security vendors.
Deployment:
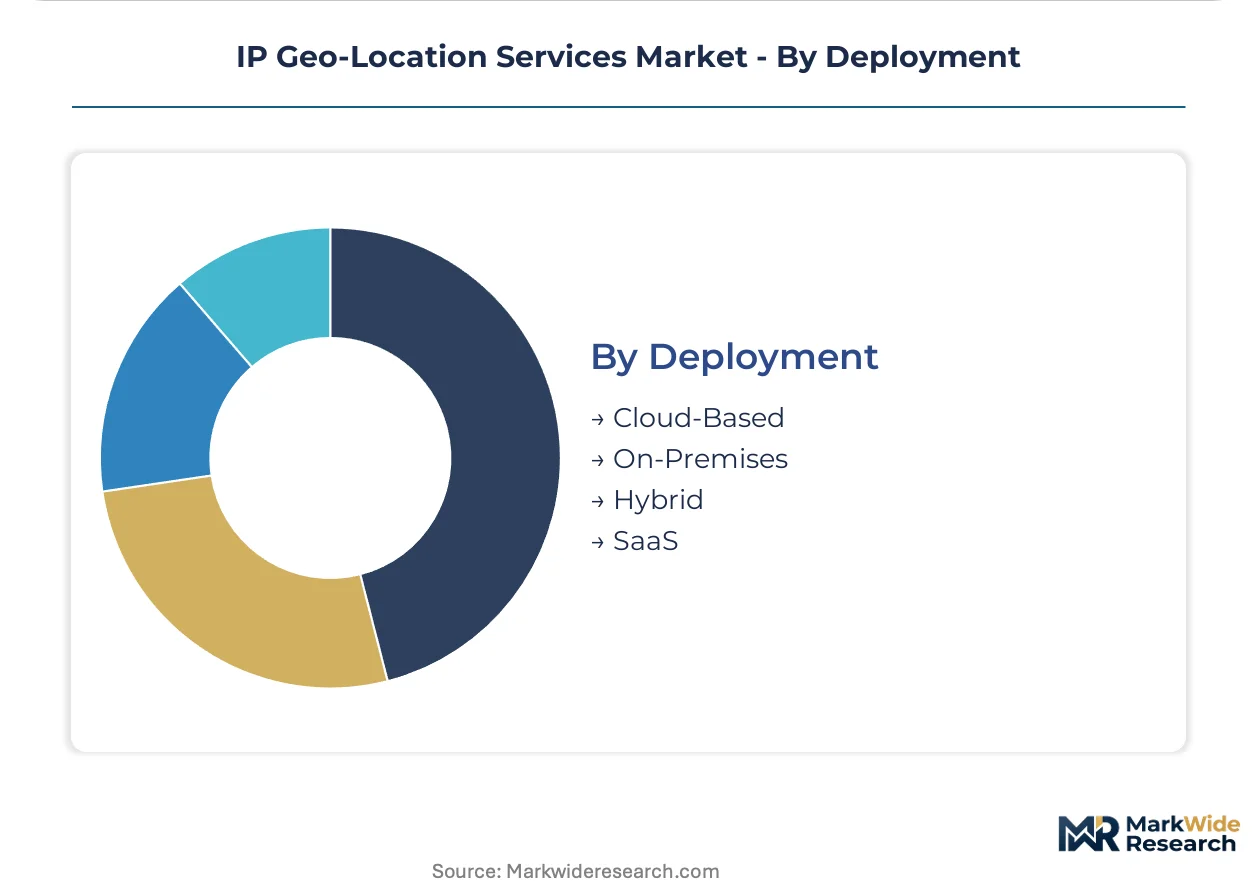
Data sovereignty requirements and latency constraints push enterprises toward hybrid architectures that balance cloud elasticity with on-premises control.
- Cloud-Based:Fully managed API endpoints eliminate infrastructure overhead while enabling elastic scaling during traffic spikes. Direct-to-consumer brands in Latin America favor this model for rapid international expansion without dedicated DevOps resources.
- Hybrid:Split architectures process sensitive queries through on-premises databases while routing standard requests to cloud endpoints. Indian telecommunications firms adopt this pattern to satisfy TRAI data localization mandates without sacrificing global coverage.
- On-Premises:Self-hosted database deployments for classified environments.
- SaaS:Pre-integrated platform subscriptions with usage-based metering.
Cloud-Based deployment holds the volume lead, with Hybrid configurations steepest expansion trajectory among regulated industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IP geo-location services industry traces its commercial roots to early 2000s database licensing operations in the United States, where internet infrastructure providers first systematized IP-to-location mapping for content delivery optimization.
United States
Cloud infrastructure providers and cybersecurity vendors drive API consumption volumes across financial services and streaming platforms. FCC emergency service location accuracy guidelines mandate sub-50-meter precision for VoIP and mobile calls, forcing carriers to upgrade signal triangulation capabilities. Seattle and San Francisco Bay Area clusters host the densest concentration of edge computing deployments embedding real-time geolocation into content delivery workflows.
Germany
Financial institutions in Frankfurt and Munich deploy IP geo-location for transaction verification under strict EU GDPR location transparency requirements. The EU AI Act's risk classification framework demands algorithmic provenance documentation for automated fraud scoring systems. Berlin-based fintech startups integrate modular geolocation APIs into open banking platforms, accelerating mid-market adoption.
India
TRAI mandates for telecom service quality create demand for domestic IP geo-location hosting as data sovereignty requirements harden across payment processing and e-commerce. The central bank's digital payment security guidelines push banks toward real-time location verification for UPI transactions. Mumbai and Bangalore clusters concentrate cloud-native security vendors building India-hosted geolocation databases.
United Kingdom
Post-Brexit regulatory divergence complicates cross-border data handling for financial services firms maintaining EU market access. The Financial Conduct Authority's operational resilience requirements elevate vendor selection criteria for geolocation-dependent fraud detection. London's fintech corridor drives demand for hybrid deployment models balancing cloud elasticity with sovereign data controls.
Japan
Mobile operators leverage carrier-derived signal databases for subscriber services under METI guidelines for telecommunications infrastructure security. The country's aging population drives demand for location-aware emergency response systems requiring sub-100-millisecond API latency. Tokyo and Osaka metropolitan areas concentrate streaming services optimizing content delivery through edge-embedded geolocation intelligence.
IP Geo-Location Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision tiers and compliance certification depth, with fraud detection specialists commanding per-transaction pricing multiples above content delivery generalists. The vendor base organizes into three strategic archetypes: edge network operators bundling location intelligence into infrastructure services, database specialists licensing high-precision IP mappings, and API-first platforms serving mid-market SaaS integrations. Dominant competitive moves include modular API decomposition to capture discrete use-case budgets and sovereign hosting partnerships to satisfy data localization mandates.
Within the infrastructure-integrated tier, Akamai Technologies, Inc. and Google Cloud exemplify edge network operators embedding geolocation directly into content delivery workflows. MaxMind, Inc. and Digital Element, Inc. occupy positions among database specialists prioritizing precision granularity for fraud detection and advertising use cases. Neustar, Inc. and Pitney Bowes Inc. represent legacy data services providers extending IP location capabilities through enterprise sales channels. These six entities collectively illustrate the competitive spectrum from infrastructure-scale bundling to specialized precision licensing.
| Leading Market Players |
|---|
| MaxMind, Inc. |
| Neustar, Inc. |
| Google Cloud |
| Akamai Technologies, Inc. |
| Pitney Bowes Inc. |
| IP2Location |
| Ipstack |
| Digital Element, Inc. |
| BigDataCloud Pty Ltd. |
| Others |
Supply & Pricing Matrix
Captive edge-network integration anchors both supply positioning and pricing power for infrastructure-tier providers, who embed geolocation intelligence directly into content delivery workflows rather than licensing discrete databases. This vertical control over signal origination and API delivery creates margin insulation against commodity pricing pressure from pure-play data vendors.
Pricing Analysis
Usage-based SaaS metering with tiered volume discounts dominates commercial contracts, with fraud detection applications commanding premium per-transaction rates against commodity content delivery API calls. Price differentiation hinges on carrier-grade signal provenance and GDPR audit trail certification, with certified precision tiers extracting multiples above uncertified alternatives. Pricing pressure stems from self-service cloud marketplace channels compressing enterprise negotiation leverage. Mid-market e-commerce platforms exhibit highest price sensitivity, while financial institutions prioritize compliance certification over cost.
Supply Chain Analysis
Freight-equivalent data transmission costs concentrate supply advantage among United States, Germany, and India hosting clusters, where fiber density and exchange point proximity minimize latency to major demand centers. Raw inputs draw from Regional Internet Registry allocations, BGP routing table feeds, and carrier-derived mobile signal databases. Single-source vulnerability concentrates in tier-one telecommunications operators controlling last-mile signal accuracy. Distribution runs through cloud provider marketplaces and direct enterprise API integration, with hybrid deployment models requiring sovereign hosting partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compliance costs and Indian data sovereignty infrastructure buildout, where divergent localization mandates create divergent margin structures for equivalent technical capabilities.
For Market Incumbents: Deepen carrier partnership exclusivity in India and Germany to lock in signal provenance advantages before TRAI and EU AI Act enforcement hardens. Invest in containerized microservices architectures that decompose legacy platform contracts into discrete, defensible modules. Threat substitution from privacy-preserving browser APIs demands preemptive positioning in on-premises deployment channels. For New Entrants and Emerging Players: AI-driven anomaly detection modules offer a technology-first wedge into payment processor fraud stacks, where incumbent precision gaps create white-space for predictive scoring differentiation. Target Southeast Asian e-commerce platforms seeking rapid international expansion without dedicated procurement functions. Go-to-market leverage rests on cloud marketplace distribution bypassing traditional enterprise sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for specialized API-first platforms because buyer procurement fragmentation dismantles monolithic contracts into discrete module budgets. Long-term viability centers on compliance certification depth as EU AI Act enforcement escalates. Watch German and French regulatory action against opaque location inference methods as inflection signal for algorithmic provenance valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Hosting Partnership | TRAI mandates in India and GDPR localization requirements create mandatory in-region infrastructure. |
| Modular API Decomposition | Fraud detection teams now mix accuracy tiers within single transaction flows, expanding touchpoints. |
| Algorithmic Provenance Documentation | EU AI Act enforcement in Germany and France demands audit trails linking IP inputs to coordinate outputs. |
| Cloud Marketplace Distribution | Self-service portals with usage-based metering displace annual licenses for mid-market SaaS platforms. |
| Carrier Signal Exclusivity | Tier-one telecommunications operators in United States and Western Europe control precision accuracy. |
Research Methodology
Coverage spans United States, Germany, India, United Kingdom, and Japan, with primary inputs from each market informing regional variation in regulatory enforcement and procurement sophistication. Primary interviews with fraud detection engineers at payment processors, API product managers at cloud infrastructure providers, regulatory compliance officers at financial institutions, and carrier network operations specialists combined with secondary validation from SEC filings, TRAI enforcement notices, EU AI Act implementation guidance, and BGP routing registry databases. Bottom-up deployment volume estimates triangulated against top-down enterprise IT spending allocations across the analysis window.
Granularity-level modeling operated at service type, application, end user, and deployment mode dimensions, with additional precision tiers for carrier-derived versus registry-derived signal sourcing. CAGRs derived from segment-specific adoption curves weighted by regulatory mandate timelines and cloud infrastructure capex trajectories. Forecast inputs incorporated FCC emergency accuracy guideline evolution, EU Digital Services Act implementation phases, and UPI transaction volume growth patterns.
The model holds under stable regulatory enforcement timelines; deviation in data sovereignty law acceleration or privacy-preserving browser API adoption would shift deployment mode mix and pricing power distribution. Forecasts reflect documented assumptions about carrier signal licensing continuity and cloud marketplace channel maturation. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Geomarketing Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
South Korea Geospatial Analytics Market
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market