
 China Geospatial Analytics Market | 2026-2036
China Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
China Geospatial Analytics Market Insights
Subscription-based software-defined feature layers is shifting how geospatial value gets packaged in China. Mapuni leverages cloud-native deployment to anchor its position among municipal government clients. Qianxun Spatial Intelligence differentiates through BeiDou-integrated positioning services for autonomous vehicle testing corridors. Zhejiang Zhenshan Technology Co., Ltd. dominates hardware-software bundled offerings in provincial surveying bureaus.
Geospatial analytics encompasses the computational processing, visualization, and predictive modeling of location-tagged data derived from satellite remote sensing, aerial photogrammetry, LiDAR point clouds, and ground-based sensor networks, typically requiring sub-meter positional accuracy and real-time stream processing architectures to support decision systems in urban planning and resource management. GIS technology leads current deployment volumes across Chinese government accounts, while LiDAR adoption accelerates fastest in transportation corridor mapping and precision agriculture. Service type revenue pools concentrate in data analysis and software development, where recurring platform fees now exceed one-time consulting engagements in contracted value.
MIIT's geographic information interoperability standards, GB national standards for spatial data quality, and the Ministry of Natural Resources' surveying资质 licensing framework collectively shape product certification requirements and vendor qualification pathways. These regulations restrict market access for uncertified foreign platforms while channeling procurement toward domestically compliant solution stacks. Stakeholders must monitor evolving credential requirements and dual carbon data disclosure rules to anticipate compliance-driven procurement shifts.
Market Dynamics
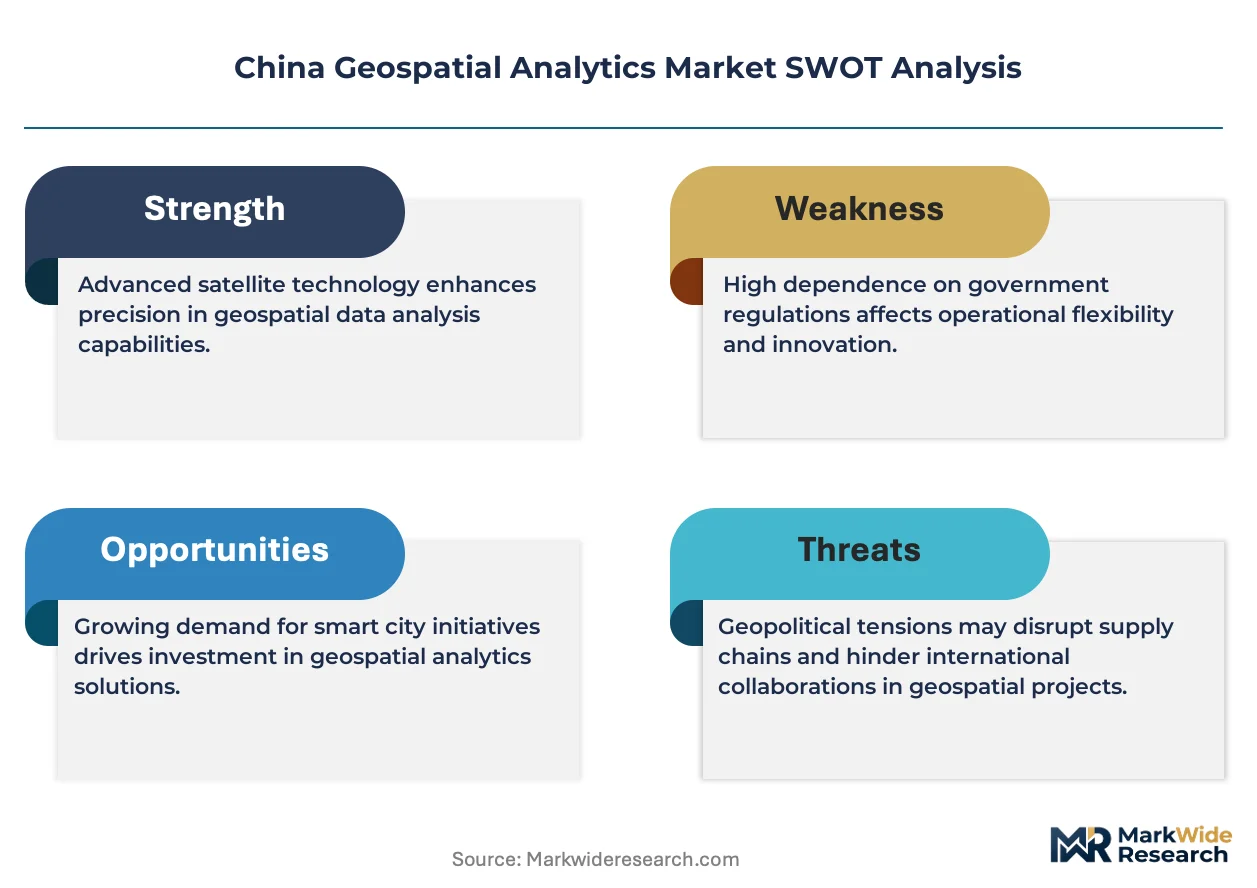
MIIT's geographic information interoperability standards are compressing vendor margins while accelerating platform consolidation among domestic solution providers competing for municipal procurement contracts.
Growth Catalysts
- Dual carbon data disclosure mandates:MEE requirements for emissions tracking are forcing industrial operators to deploy spatial intelligence layers for facility-level carbon accounting.
- BeiDou-3 constellation completion:Sub-meter positioning availability is unlocking autonomous vehicle testing corridors in Chongqing and Wuhan.
- Yangtze River Delta port automation:Real-time berth allocation systems using satellite-derived vessel tracking are cutting container dwell times at Ningbo-Zhoushan terminals.
Market Restraints
- Surveying资质 licensing bottlenecks:Ministry of Natural Resources credential requirements restrict uncertified foreign platforms from bidding on provincial government contracts.
- High-resolution satellite imagery import dependencies:Domestic commercial constellations lack the revisit frequency of foreign providers, constraining time-sensitive applications.
- LiDAR sensor cost structures:Solid-state unit prices remain elevated for precision agriculture deployment at scale across smallholder plots.
Strategic Opportunities
- Central China smart city buildouts:Chengdu and Xi'an municipal governments are expanding procurement for infrastructure digital twin platforms with integrated geospatial engines.
- GB standards harmonization:Unified spatial data quality frameworks are reducing integration friction between provincial surveying bureaus and private platform vendors.
- Edge-AI convergence:On-device inference for real-time feature extraction is opening unmanned aerial survey missions in remote western provinces with limited connectivity.
Industry Challenges
- Interoperability engineering talent scarcity:Platform vendors struggle to recruit specialists fluent in both GB standards and cloud-native microservices architecture.
- Legacy GIS system integration complexity:Municipal clients demand backward compatibility with decade-old ESRI deployments, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Geospatial Analytics Market |
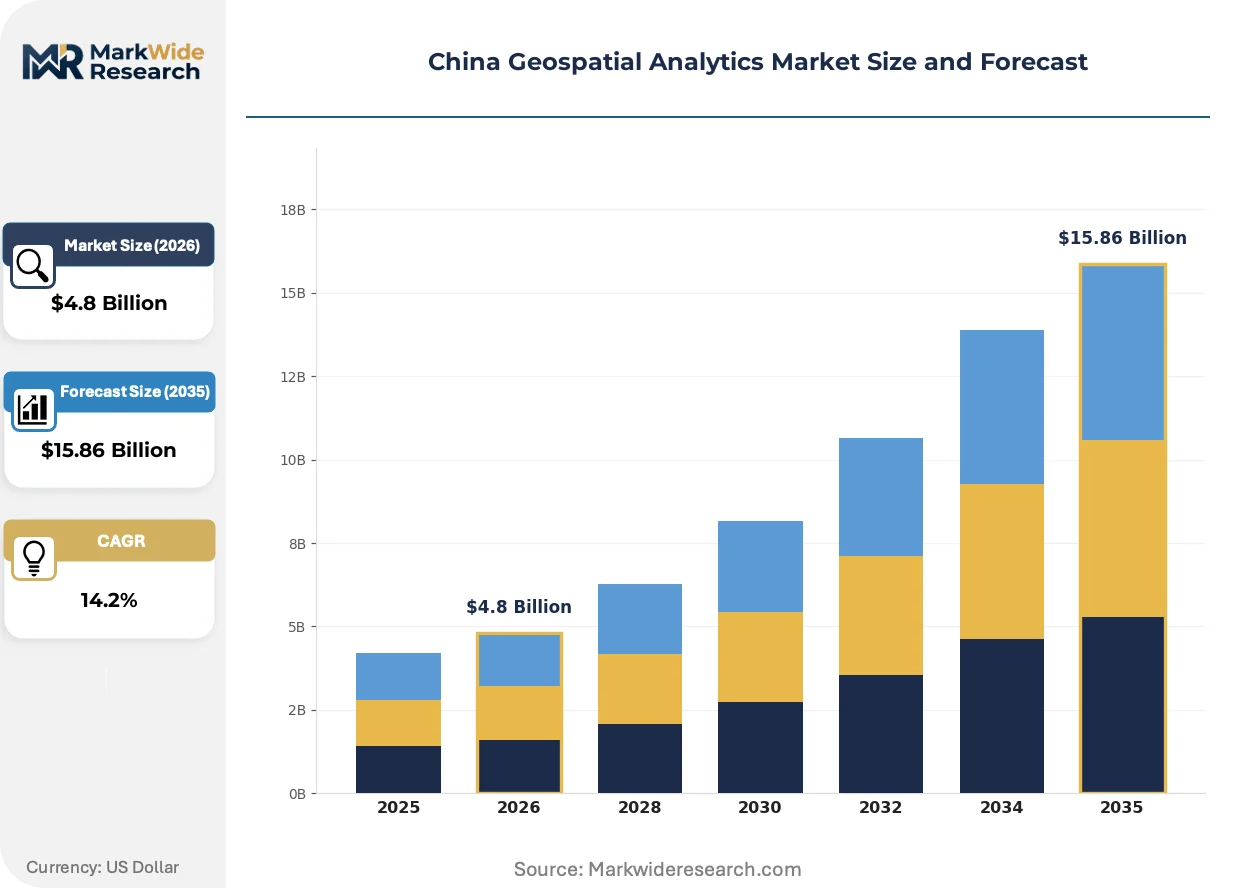
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GIS, Remote Sensing, LiDAR, Photogrammetry End User: Government, Transportation, Agriculture, Environmental Management Application: Urban Planning, Disaster Management, Natural Resource Management, Asset Tracking Service Type: Consulting, Software Development, Training, Data Analysis |
| Companies Covered | Zhejiang Zhenshan Technology Co., Ltd., Mapuni, Qianxun Spatial Intelligence, China Geo-Engineering Corporation, GeoQ, SZ Soarability Technology LLC, Weihai Wuzhou Navi-Tech, SinoMap, Jiangsu Xingyue Surveying and Mapping Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Geospatial Analytics Market Trends and Innovations
Cloud-native geospatial engines are compressing deployment cycles from months to weeks, while regulatory pressure on data sovereignty is redirecting R&D investment toward domestically controlled processing stacks.
AI-powered feature extraction from satellite imagery is overtaking manual photogrammetry workflows in infrastructure monitoring applications. Provincial transportation bureaus in Jiangsu and Guangdong are adopting automated crack detection and vegetation encroachment alerts for highway corridor maintenance. This capability compression is collapsing traditional surveying service contracts into software subscription tiers.
MIIT's GB/T standards for geographic information interoperability are mandating open API specifications across government procurement. Platform vendors must now expose core geoprocessing functions to third-party developers, eroding proprietary data moats. Municipal IT departments in tier-one cities are prioritizing vendors with certified compliance over feature depth.
Subscription-based software-defined feature layers are displacing perpetual license models in municipal accounts. Procurement officers in Shanghai and Shenzhen now contract for metered consumption of satellite imagery analytics rather than owning raw data assets. This shift concentrates vendor relationships around platform stickiness rather than data resale margins.
China Geospatial Analytics Market Segmentation
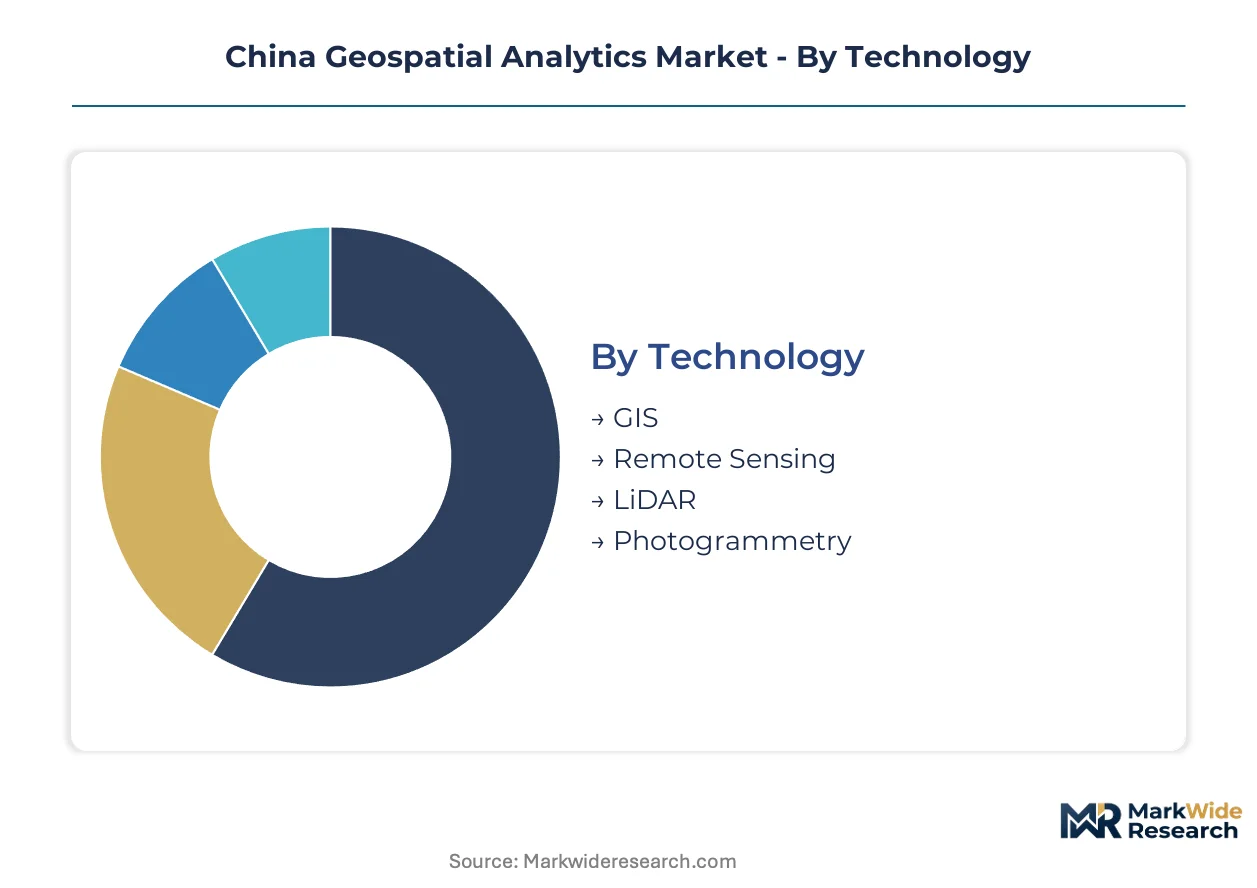
Segmentation reveals how procurement priorities diverge across technology maturity tiers and compliance requirements in China's geospatial market. MIIT certification pathways and BeiDou integration mandates reshape which solution types capture municipal budgets versus industrial accounts.
Technology:
Upgrade cycles accelerate where legacy deployments face interoperability mandates from national standards bodies.
- GIS:Dominant deployment volume across provincial surveying bureaus and municipal planning departments. Shanghai and Shenzhen smart city administrations anchor demand as cloud-native engines displace decade-old ESRI installations.
- Remote Sensing:Satellite imagery analytics processing sub-meter resolution data for infrastructure monitoring. Yangtze River Delta port operators deploy real-time vessel tracking layers to compress container dwell times at Ningbo-Zhoushan terminals.
- LiDAR:Solid-state sensor costs constrain precision agriculture adoption across smallholder plots.
- Photogrammetry:Manual workflows contract as AI-powered feature extraction automates highway corridor maintenance alerts.
Volume placements concentrate in GIS; the faster expansion belongs to Remote Sensing.
End User:
Customer-type stratification follows funding authority levels from central ministries to county-level operators.
- Government:Provincial surveying bureaus and municipal IT departments drive procurement through MIIT-certified platform tenders. Backward compatibility requirements with legacy systems extend implementation timelines.
- Transportation:Jiangsu and Guangdong transportation bureaus adopt automated crack detection for highway maintenance. Chongqing and Wuhan autonomous vehicle testing corridors demand BeiDou-integrated positioning services.
- Agriculture:Precision agriculture operators in the Yangtze River Delta deploy spatial intelligence layers for crop monitoring.
- Environmental Management:MEE dual carbon disclosure mandates force facility-level emissions tracking using spatial data.
Government accounts dominate current contract value; Environmental Management climbs the fastest on regulatory compulsion.
Application:
Use-case prioritization reflects infrastructure investment waves and climate adaptation spending.
- Urban Planning:Chengdu and Xi'an municipal governments expand procurement for infrastructure digital twin platforms.
- Disaster Management:Real-time stream processing architectures support emergency response systems in flood-prone provinces.
- Natural Resource Management:Forest and water resource bureaus integrate satellite-derived change detection for compliance monitoring.
- Asset Tracking:Port logistics operators deploy berth allocation systems using satellite-derived vessel positioning.
Urban Planning holds the largest installed base; Asset Tracking gains share fastest on port automation investments.
Service Type:
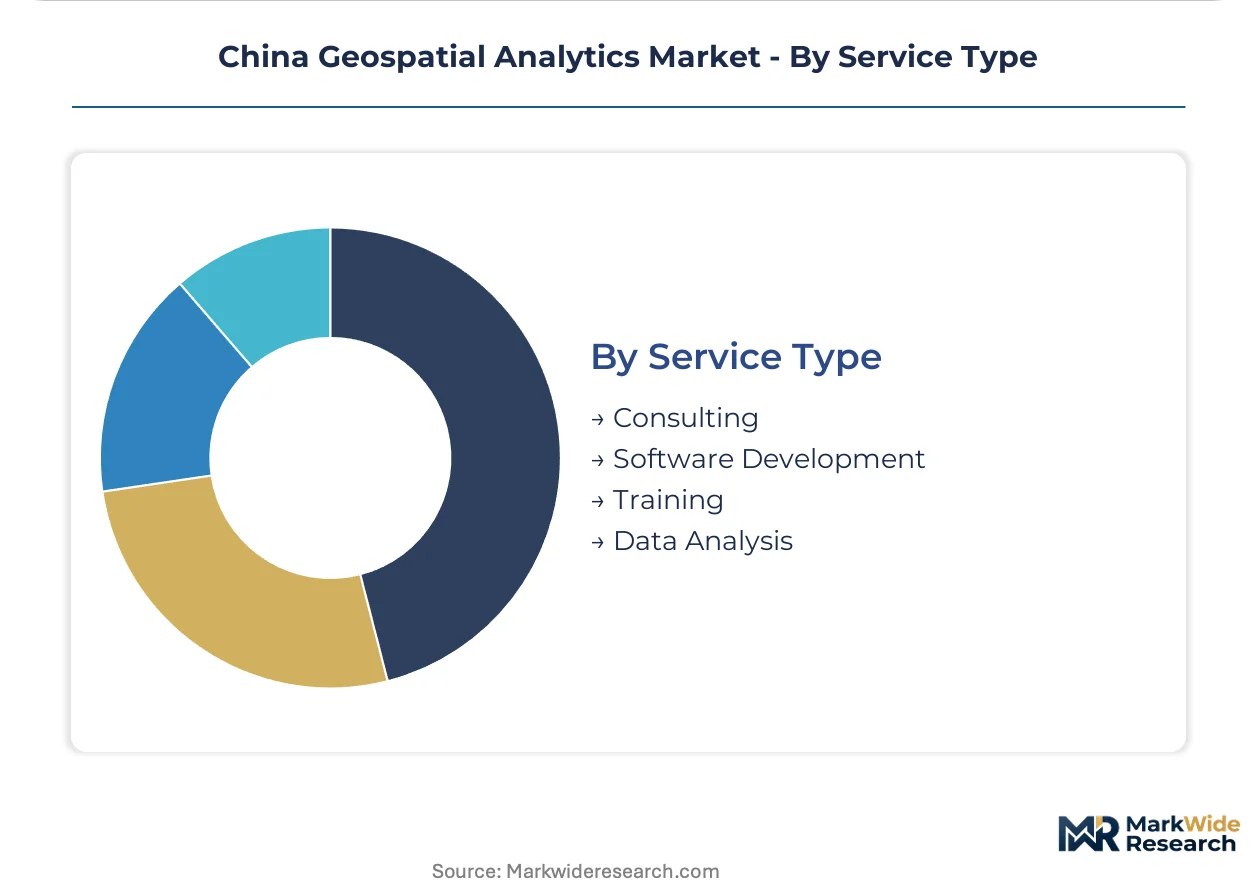
Revenue model evolution shifts from perpetual licenses toward recurring platform fees.
- Consulting:One-time implementation support contracts shrink as vendors push subscription-based software-defined feature layers.
- Software Development:Cloud-native geoprocessing functions exposed through open APIs per MIIT GB/T mandates. Recurring platform fees now exceed one-time consulting engagements in contracted value.
- Training:Certification programs for GB standards fluency address interoperability engineering talent scarcity.
- Data Analysis:Metered consumption of satellite imagery analytics displaces raw data asset ownership in Shanghai and Shenzhen municipal accounts.
Software Development captures the deepest revenue pools; Data Analysis shows the steepest expansion trajectory on subscription adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors procurement intensity for China's geospatial analytics sector, with Shanghai municipal authorities driving cloud-native platform adoption across smart city infrastructure layers.
Yangtze River Delta
Port logistics operators at Ningbo-Zhoushan terminals deploy real-time berth allocation systems using satellite-derived vessel tracking to compress container dwell times. MIIT's GB/T interoperability standards mandate open API specifications for government procurement in this corridor. Precision agriculture operators across Jiangsu and Zhejiang provinces layer spatial intelligence for crop monitoring at sub-meter resolution.
Pearl River Delta
Shenzhen smart city administrations anchor demand for infrastructure digital twin platforms with integrated geoprocessing engines. The Ministry of Natural Resources' surveying资质 licensing framework restricts uncertified platforms from municipal tenders in Guangdong province. Autonomous vehicle testing corridors in Guangzhou integrate BeiDou-3 positioning services for sub-meter navigation accuracy.
Beijing-Tianjin-Hebei
Environmental Management applications concentrate here as MEE dual carbon disclosure mandates force facility-level emissions tracking using spatial data layers. GB national standards for spatial data quality shape product certification requirements for vendors bidding on central government contracts. Municipal IT departments in Beijing prioritize MIIT-certified compliance over feature depth in platform selection.
Sichuan-Chongqing
Chongqing's autonomous vehicle testing corridors demand BeiDou-integrated positioning services for navigation validation at scale. The region's mountainous terrain drives adoption of edge-AI convergence for unmanned aerial survey missions with limited connectivity. Chengdu municipal government expands procurement for infrastructure monitoring using AI-powered feature extraction from satellite imagery.
Shandong Peninsula
Provincial surveying bureaus in Jinan and Qingdao drive hardware-software bundled procurement for traditional GIS upgrade cycles. MIIT standards accelerate platform consolidation among domestic vendors competing for municipal contracts in this manufacturing-heavy corridor. Port operators at Qingdao container terminals pilot real-time spatial intelligence for automated cargo handling workflows.
China Geospatial Analytics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's geospatial analytics sector, with hardware-software bundled vendors facing margin compression from cloud-native platform specialists. The vendor base clusters around three strategic archetypes: municipal-focused platform consolidators, BeiDou-integrated positioning service providers, and provincial surveying bureau hardware bundlers. Competitive moves concentrate on MIIT certification acquisition and cloud-native microservices architecture development.
Within the municipal platform tier, Mapuni occupies a position among cloud-native deployment specialists serving government accounts. Qianxun Spatial Intelligence exemplifies the BeiDou-integration archetype for autonomous vehicle corridor applications. Zhejiang Zhenshan Technology Co., Ltd. anchors the hardware-software bundled tier for provincial surveying bureau procurement.
| Leading Market Players |
|---|
| Zhejiang Zhenshan Technology Co., Ltd. |
| Mapuni |
| Qianxun Spatial Intelligence |
| China Geo-Engineering Corporation |
| GeoQ |
| SZ Soarability Technology LLC |
| Weihai Wuzhou Navi-Tech |
| SinoMap |
| Jiangsu Xingyue Surveying and Mapping Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
MIIT certification tiers bifurcate vendor pricing power and procurement access, with certified domestic platforms commanding municipal premiums while uncertified foreign competitors face exclusion from provincial government contracts. This tiered access structure concentrates supply relationships around Beijing, Shanghai, and Shenzhen technology clusters where compliance engineering capabilities anchor vendor qualification pathways.
Pricing Analysis
Margin tightening in hardware-software bundled tiers reflects cloud-native platform displacement of perpetual license models. Three-tier pricing structure across MIIT-certified premium, provincial-standard, and county-economy levels differentiates vendors by interoperability compliance depth. Cost compression accelerates as municipal procurement officers shift from raw data asset ownership toward metered consumption of satellite imagery analytics. Government accounts show lowest price sensitivity given regulatory compliance mandates; precision agriculture operators exhibit highest sensitivity due to smallholder plot fragmentation.
Supply Chain Analysis
Direct-to-municipal-IT channels handle government procurement demand while hardware bundlers serve provincial surveying bureaus through authorized distributor networks. Component manufacturing concentrates in China, Taiwan, and South Korea for solid-state LiDAR sensors and BeiDou-3 positioning chipsets. Raw material dependencies span gallium arsenide substrates, precision optical glass, and high-purity rare earth elements for sensor fabrication. Single-source vulnerability around foreign high-resolution satellite imagery imports constrains time-sensitive applications. Distribution runs through MIIT-certified system integrators for government accounts and agricultural equipment dealers for precision farming deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation accelerates as interoperability engineering talent scarcity and certification bottlenecks force sub-scale vendors toward acquisition or exit. MIIT's GB/T mandate compression favors capitalized players with compliant cloud-native stacks.
For Market Incumbents: Extend cloud-native microservices architecture into tier-two municipal markets before provincial surveying bureaus complete legacy GIS upgrade cycles. Acquire BeiDou-integration specialists to defend positioning against Qianxun Spatial Intelligence's autonomous vehicle corridor dominance. Deepen backward integration into domestic satellite imagery processing to reduce foreign constellation dependency exposure.
For New Entrants and Emerging Players: Enter via edge-AI convergence for unmanned aerial surveys in Sichuan-Chongqing's connectivity-limited western provinces. Target environmental management applications where MEE dual carbon disclosure mandates force facility-level spatial intelligence procurement without entrenched vendor relationships. Lead with open API compliance per MIIT standards to bypass certification timeline disadvantages.
For Investors and Strategic Acquirers: Re-rating potential sits with municipal-focused platform consolidators given GB standards harmonization reducing integration friction across provincial accounts. Long-term viability favors vendors with recurring platform fee models exceeding one-time consulting engagement value. Watch MIIT credential requirement expansion into county-level procurement as inflection signal for compliance-driven vendor shakeout acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | Unlocks municipal procurement access under GB/T interoperability mandates in Shanghai and Shenzhen. |
| BeiDou-3 Integration Partnership | Captures autonomous vehicle testing corridor demand in Chongqing and Wuhan positioning services. |
| Cloud-Native Platform Migration | Compresses deployment cycles from months to weeks for smart city infrastructure digital twins. |
| Edge-AI Capability Buildout | Enables unmanned aerial survey missions in western provinces with limited connectivity infrastructure. |
| Backward Integration into Domestic Imagery | Reduces dependency on foreign satellite constellation revisit frequency constraints. |
Research Methodology
Multi-period observation of municipal procurement contract flows, MIIT certification timelines, and BeiDou integration deployment rates anchored the trend analysis, supplemented by interviews with smart city IT directors, provincial surveying bureau chiefs, autonomous vehicle testing corridor operators, precision agriculture platform engineers, and environmental management compliance officers. Secondary validation drew from MIIT GB standards documentation, Ministry of Natural Resources licensing registries, Yangtze River Delta port authority procurement disclosures, and municipal government budget expenditure reports. Bottom-up vendor revenue triangulation against top-down addressable market sizing ensured analytical consistency.
Segment-weighting across technology type, end-user funding authority level, application use-case maturity, and service model revenue structure informed the analytical framework throughout the projection horizon. Deployment volume trajectories for GIS, remote sensing, LiDAR, and photogrammetry technologies combined with subscription adoption curves and certification pipeline velocities to derive expansion rates across the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT regulatory acceleration or satellite imagery import restriction scenarios. Periodic stress-testing of base assumptions around dual carbon mandate enforcement intensity and BeiDou-3 constellation service reliability is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market