
 China Location-Based Services Market | 2026-2036
China Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
China Location-Based Services Market Insights
Platform bundling with cloud infrastructure and payment ecosystems is repositioning buyer procurement logic in China's location services sector. Alibaba Cloud leverages its Amap navigation layer and merchant data flywheel to dominate local discovery and logistics routing. Baidu sustains mapping R&D intensity through its Apollo autonomous driving program and AI-powered geospatial engine. Tencent competes by embedding location intelligence into WeChat's super-app architecture, controlling the channel through which most Chinese consumers access point-of-interest data.
Location-based services encompass geospatial data collection, real-time positioning algorithms, and contextual service delivery through GNSS, cellular triangulation, and short-range wireless protocols with sub-10 meter accuracy thresholds for consumer-grade applications. Their primary commercial purpose spans fleet coordination, proximity marketing, asset monitoring, and indoor wayfinding across physical-digital hybrid environments. Navigation and tracking services lead the service type dimension, though geofencing is accelerating fastest as industrial users deploy perimeter-based automation for warehouse and manufacturing workflows. GPS and BeiDou dual-constellation reception anchors the technology stack, while Bluetooth beacons represent the fastest-expanding layer for indoor positioning where satellite signals degrade.
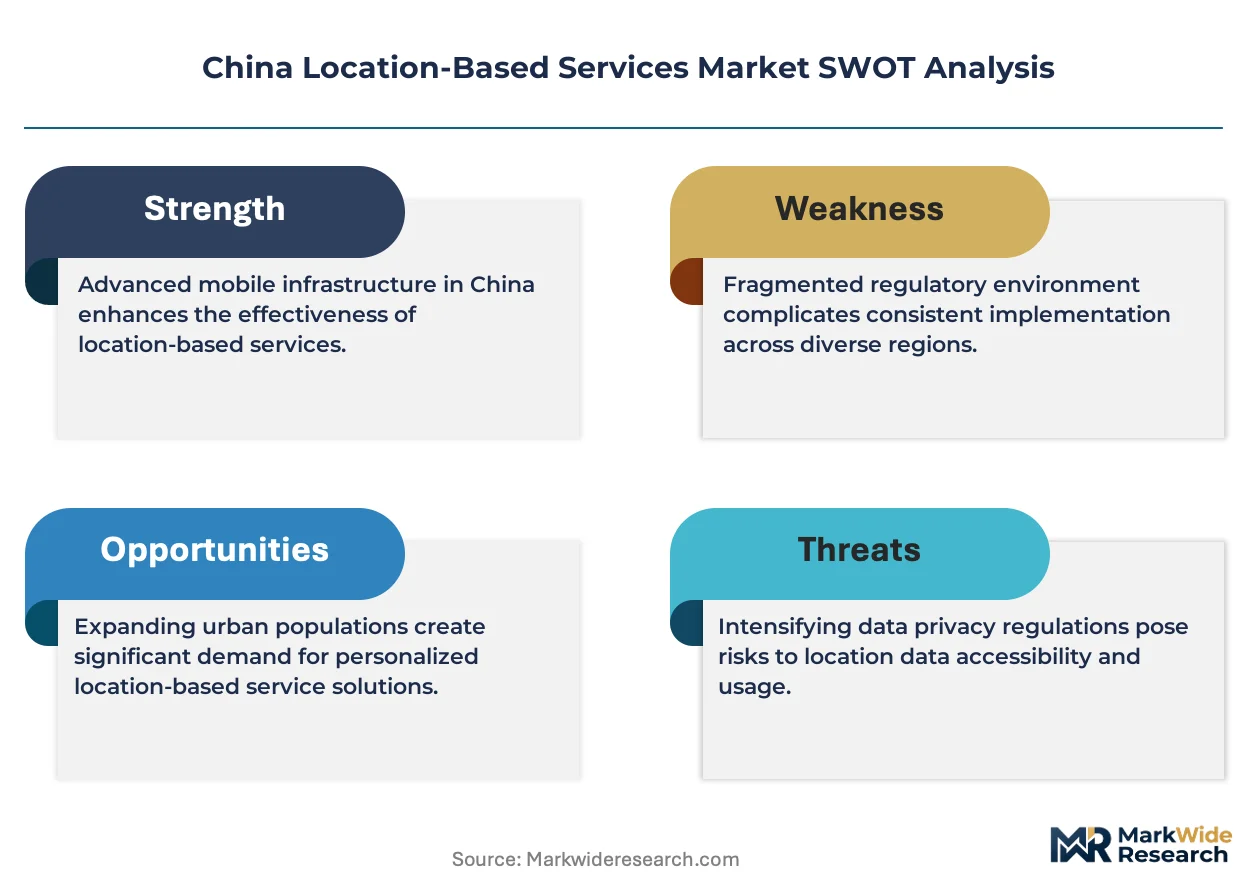
MIIT enforces data localization and cybersecurity review standards for geospatial information collection, restricting cross-border data flows and mandating domestic server storage for critical infrastructure operators. SAMR oversees anti-competitive practices in platform-based location data aggregation, while GB standards prescribe BeiDou interoperability requirements for state-contracted navigation systems. Stakeholders must monitor evolving encryption mandates for raw positioning data and assess whether their architecture can satisfy simultaneous compliance with national security classifications and commercial scalability targets.
Market Dynamics
BeiDou-3 constellation completion and MIIT's data localization mandates are restructuring vendor compliance architectures and procurement criteria across China's location services ecosystem. Platform operators must now engineer dual-constellation positioning stacks while maintaining domestic data sovereignty, reshaping R&D roadmaps and partnership strategies.
Growth Catalysts
- Smart city infrastructure mandates:Guangdong Province's digital twin deployments for urban traffic management are generating fleet-scale contracts for real-time positioning platforms. Municipal procurement specifications now require sub-meter accuracy thresholds.
- Logistics digitization workflows:E-commerce fulfillment networks are deploying geofencing automation for warehouse perimeter security and last-mile route optimization. Industrial users demand API-native integration with existing ERP systems.
- MIIT cybersecurity review frameworks:Mandatory security assessments for geospatial data collection are accelerating domestic vendor consolidation. Foreign platform operators face localization requirements that favor indigenous technology stacks.
Market Restraints
- Semiconductor input volatility:GNSS receiver chip supply concentrates among a limited fabrication base, exposing positioning hardware costs to foundry capacity constraints and export control friction.
- Indoor positioning technical limitations:Bluetooth beacon density requirements and multipath interference in dense urban environments degrade accuracy below commercial viability thresholds for certain asset-tracking applications.
- Cross-border data flow restrictions:MIIT's geospatial information regulations block multinational enterprises from integrating China-based positioning data with global analytics platforms, fragmenting operational visibility.
Strategic Opportunities
- Autonomous vehicle mapping layers:High-definition lane-level positioning for robotaxi and trucking corridors represents uncontracted white space. Apollo and similar programs are sourcing centimeter-accuracy road network data.
- BeiDou-AI convergence:Fused positioning-intelligence engines combining satellite navigation with computer vision are enabling predictive traffic routing. Technology convergence opens new service tier pricing.
- Rural county penetration gaps:Tier-3 and Tier-4 urban clusters lack dense POI databases and real-time transit integration. Local government digital service contracts remain undersupplied relative to provincial capitals.
Industry Challenges
- Geospatial AI engineering scarcity:Talent pools combining satellite navigation expertise with machine learning deployment skills remain shallow. Recruitment competition intensifies between mapping platforms and autonomous driving programs.
- Legacy fleet management integration:State-owned logistics enterprises operate heterogeneous telematics infrastructures. API standardization delays prolong sales cycles and inflate customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Location-Based Services Market |
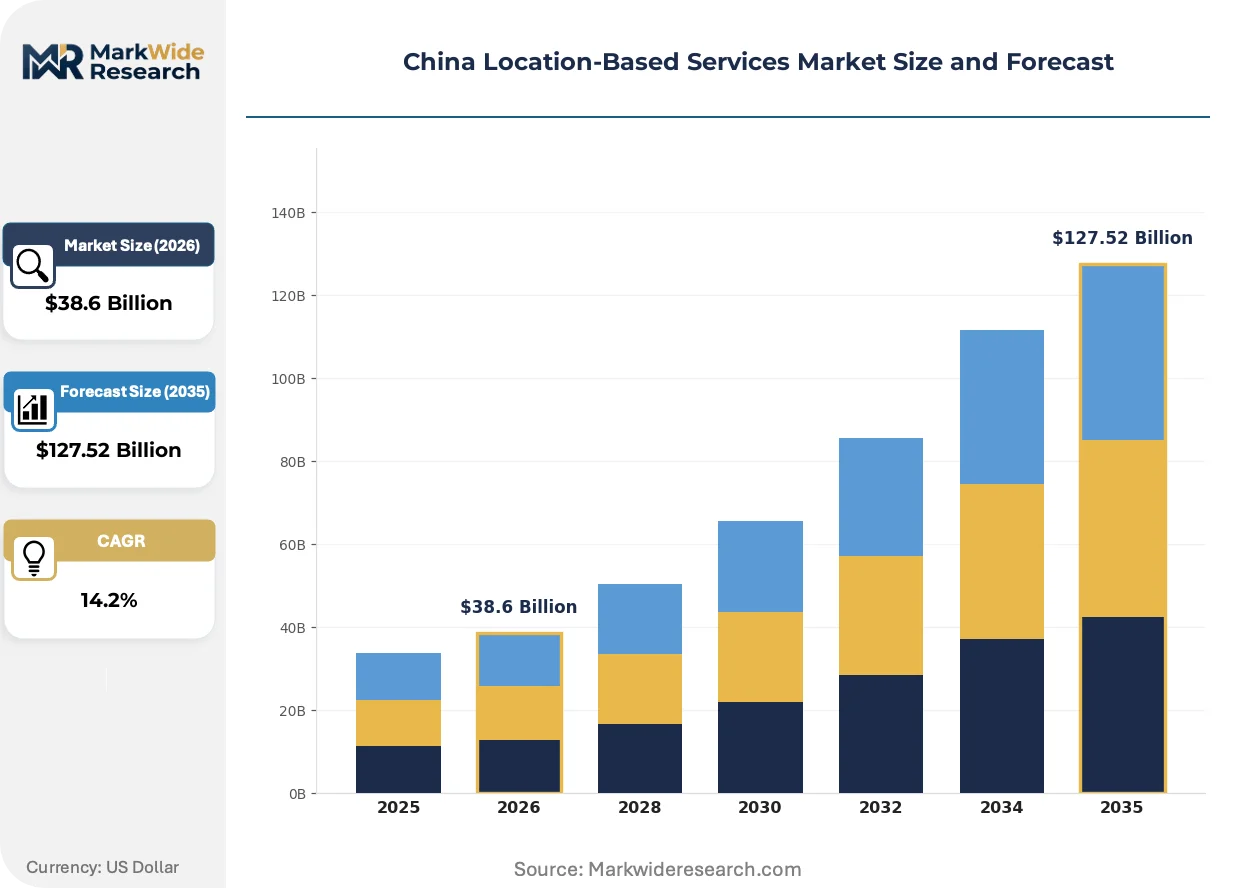
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Navigation, Tracking, Geofencing, Advertising End User: Retail, Transportation, Hospitality, Healthcare Technology: GPS, Bluetooth Beacons, Wi-Fi, RFID Application: Fleet Management, Location-Based Marketing, Asset Tracking, Indoor Navigation |
| Companies Covered | Alibaba Cloud (Alibaba Amap), Baidu, Tencent, TomTom International BV, HERE Technologies, Zebra Technologies Corp, Telenav Inc, Meituan-Dianping, Jimdou, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Location-Based Services Market Trends and Innovations
Positioning technology is fusing with artificial intelligence inference layers and cloud-native service architectures, compressing the latency between raw signal acquisition and contextual service delivery. This convergence is redrawing competitive boundaries between hardware suppliers, platform operators, and vertical application developers.
Ultra-wideband (UWB) ranging chips are converging with BeiDou-GPS dual-frequency receivers to enable seamless indoor-outdoor positioning handoffs. Automotive OEMs and industrial asset-tracking buyers are specifying this fused architecture for next-generation telematics units. The technology is converging with 5G network timing synchronization to deliver sub-30-centimeter accuracy without dedicated infrastructure.
MIIT's encryption mandates for raw positioning data are forcing architecture redesigns across platform operators. Domestic server storage requirements and pre-transfer security reviews are extending deployment timelines for multinational service providers. State-contracted navigation systems face the most stringent GB standards compliance obligations, with BeiDou interoperability certification now a gatekeeper for government procurement eligibility.
Enterprise buyers are consolidating vendor relationships around full-stack location intelligence providers rather than point-solution GPS hardware suppliers. Logistics and retail chains are demanding bundled navigation, geofencing, and analytics capabilities through single API contracts. This consolidation pattern is most visible in Yangtze River Delta manufacturing clusters, where procurement teams prioritize operational integration over component cost minimization.
China Location-Based Services Market Segmentation
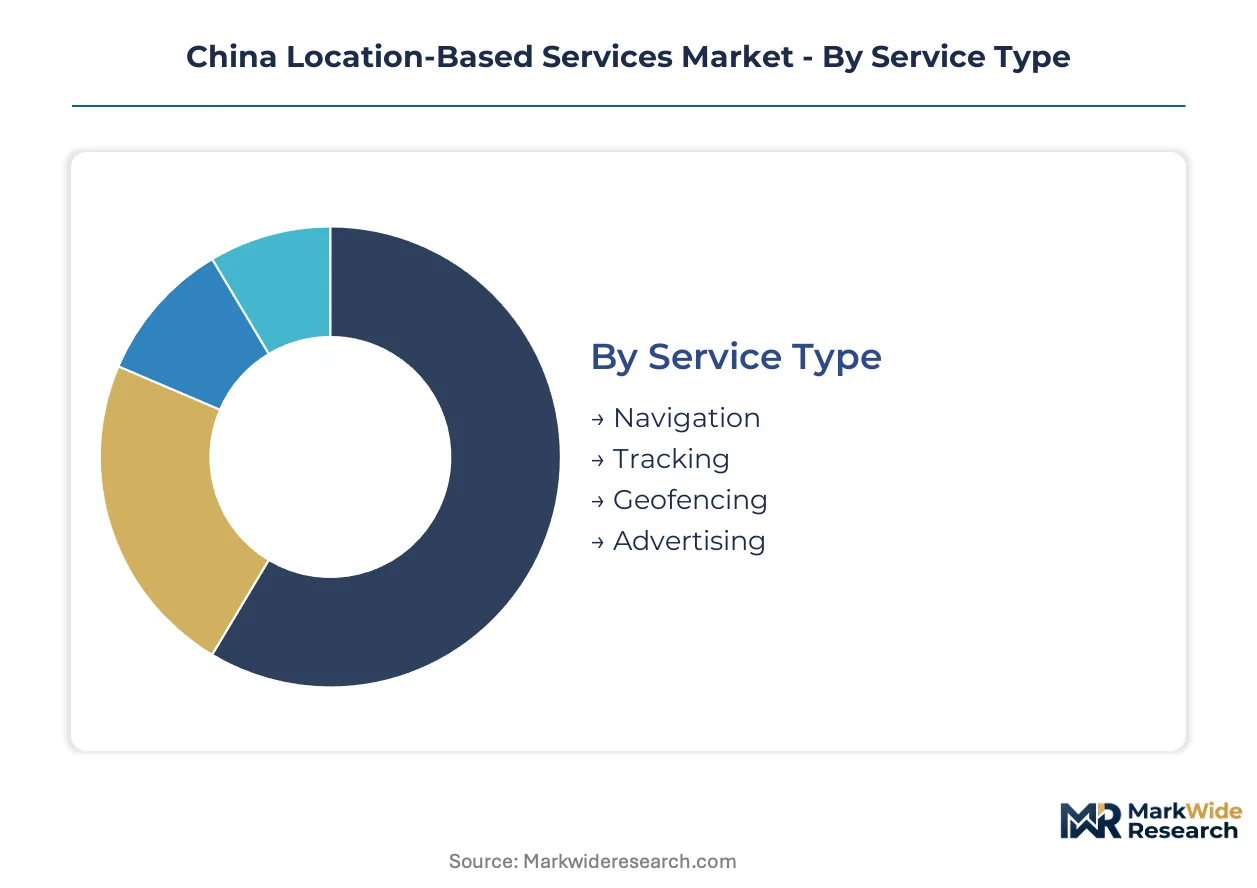
Service differentiation across China's location-based services ecosystem reflects diverging accuracy requirements and integration complexity. Buyers are consolidating procurement around bundled offerings rather than discrete positioning modules.
Service Type:
Upgrade cycles in commercial navigation platforms are compressing as BeiDou-3 integration mandates force hardware refreshes across municipal and enterprise fleets.
- Navigation:Real-time route calculation engines process dual-constellation GNSS signals with sub-meter accuracy for consumer and commercial vehicle guidance. Guangdong Province's smart city procurement contracts specify lane-level precision thresholds, driving replacement of legacy GPS-only units.
- Tracking:Continuous position monitoring for fleet assets and mobile workforce management leverages cellular backhaul with geofenced alert triggers. E-commerce fulfillment networks in the Yangtze River Delta are deploying these systems for last-mile visibility.
- Geofencing:Perimeter-based automation triggers operational workflows when assets cross defined boundaries. Warehouse operators specify these capabilities for yard management security protocols.
- Advertising:Proximity-triggered promotional content delivery targets consumers within defined retail radii. Shopping mall operators integrate these services with payment ecosystem data.
Volume placements concentrate in Navigation; the faster expansion belongs to Geofencing.
End User:
Cost tier stratification separates state-contracted infrastructure deployments from commercial self-service platform subscriptions.
- Retail:Location-based marketing and indoor wayfinding services integrate with merchant payment and loyalty systems. Department store chains in Shanghai and Beijing are deploying Bluetooth beacon density for personalized promotion delivery.
- Transportation:Fleet telematics and autonomous vehicle mapping layers demand centimeter-accuracy positioning stacks. Robotaxi corridors along Shenzhen-Guangzhou expressways are sourcing high-definition road network data.
- Hospitality:Guest experience optimization through indoor navigation and proximity service delivery targets tourism and business travel segments. Airport operators specify these capabilities for terminal wayfinding.
- Healthcare:Medical asset tracking and emergency response routing require HIPAA-equivalent data protection standards under MIIT cybersecurity frameworks. Hospital networks in provincial capitals are piloting these deployments.
Transportation commands the largest contract values; Retail is climbing the fastest as merchant digitization accelerates.
Technology:
Application-specific accuracy requirements determine technology stack selection, with satellite-dependent and infrastructure-independent options competing for indoor-outdoor continuity.
- GPS:Global Positioning System reception remains standard for outdoor navigation, though vendors now engineer dual-frequency compatibility with BeiDou-3 signals to satisfy MIIT procurement mandates.
- Bluetooth Beacons:Short-range wireless transmitters enable sub-room indoor positioning where satellite signals degrade. Manufacturing clusters in Jiangsu Province are deploying dense beacon arrays for asset tracking.
- Wi-Fi:Fingerprinting techniques leverage existing network infrastructure for coarse indoor positioning without dedicated hardware deployment.
- RFID:Passive and active radio-frequency identification supports short-range asset verification at chokepoints rather than continuous positioning.
GPS retains the installed base dominance; Bluetooth Beacons are gaining share fastest as indoor positioning demand intensifies.
Application:
Customer type differentiation separates enterprise workflow integration requirements from consumer-facing service delivery models.
- Fleet Management:Real-time vehicle tracking, route optimization, and driver behavior analytics integrate with ERP systems through API-native architectures. State-owned logistics enterprises in Sichuan Province are consolidating heterogeneous telematics infrastructures.
- Location-Based Marketing:Proximity-triggered consumer engagement delivers point-of-interest recommendations and promotional content through super-app architectures.
- Asset Tracking:High-value equipment and inventory monitoring combines geofencing alerts with predictive maintenance scheduling for industrial users.
- Indoor Navigation:Wayfinding services for complex built environments require fused positioning combining beacons, Wi-Fi, and inertial sensors.
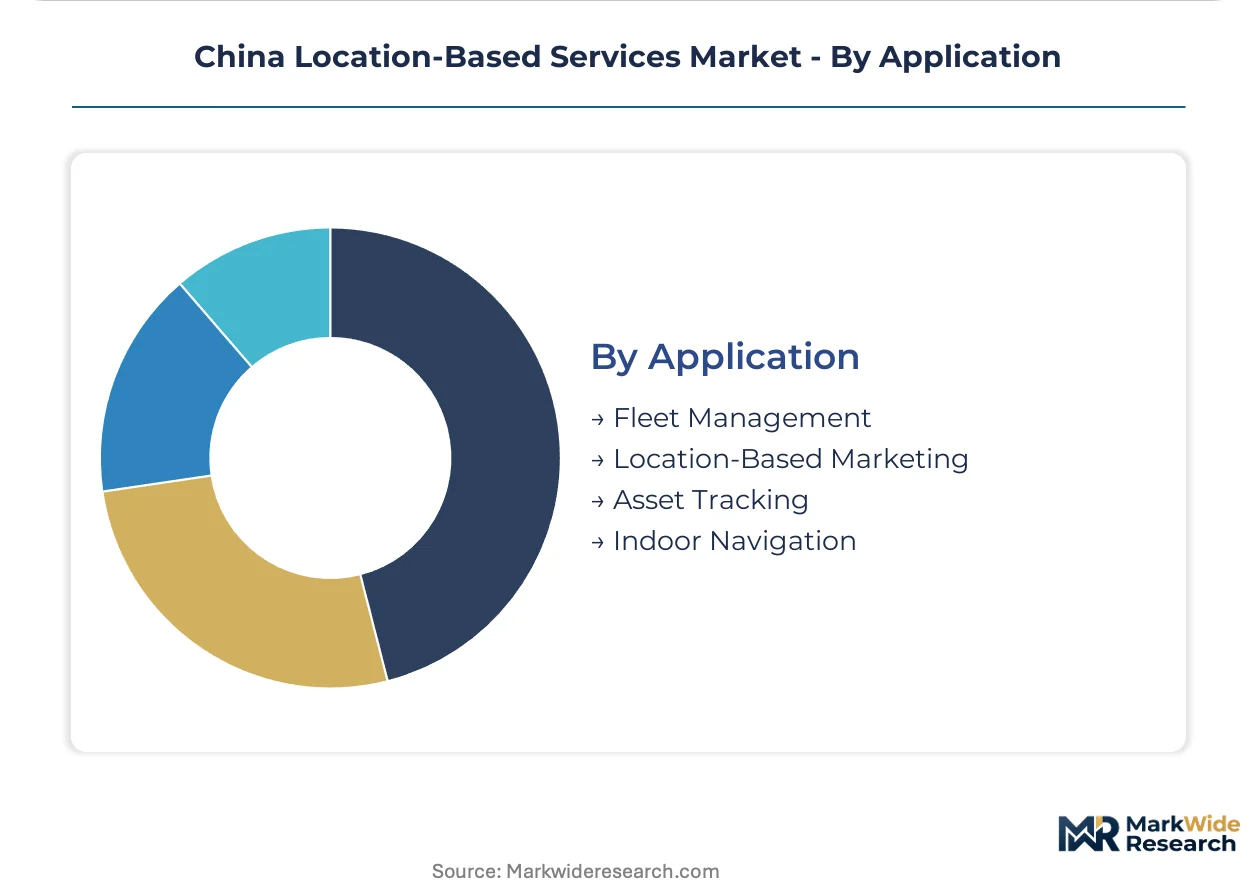
Fleet Management anchors current revenue; Indoor Navigation presents the steepest expansion trajectory as smart building deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's location-based services sector concentrates production capacity in eastern coastal provinces while consumption demand spreads inland through municipal digitization programs. Manufacturing clusters dominate component fabrication, yet deployment contracts increasingly originate from central and western regions upgrading legacy infrastructure.
Guangdong Province
Shenzhen and Guangzhou anchor smart city procurement for sub-meter accuracy navigation systems. MIIT mandates BeiDou-3 integration for all state-contracted fleet management platforms. The Pearl River Delta manufacturing corridor supplies dual-constellation GNSS receivers to logistics operators digitizing cross-border freight corridors.
Jiangsu Province
Nanjing and Suzhou industrial zones deploy dense Bluetooth beacon arrays for manufacturing asset tracking. SAMR oversight of platform-based location data aggregation shapes vendor compliance architectures. Yangtze River Delta procurement teams prioritize API-native integration over discrete hardware sourcing.
Sichuan-Chongqing
Chengdu and Chongqing municipalities drive fleet management digitization for state-owned logistics enterprises. GB standards prescribe encryption protocols for raw positioning data collected across critical transport nodes. Western China infrastructure contracts favor domestic vendors meeting cybersecurity review frameworks.
Beijing-Tianjin-Hebei
Capital region autonomous driving programs source high-definition mapping layers for robotaxi corridors. SAMR anti-competitive practice reviews influence platform data aggregation strategies. Beijing's AI-geospatial fusion R&D clusters attract engineering talent from satellite navigation and computer vision disciplines.
China Location-Based Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across China's location services sector, creating a tiered structure where cloud-platform bundling determines procurement outcomes. Consolidation pressures favor vendors controlling payment ecosystems and merchant data flywheels. Three archetypes dominate: infrastructure-integrated cloud operators, mapping-technology specialists, and vertical-application developers. Competitive moves center on API ecosystem expansion and BeiDou interoperability certification.
Among infrastructure-integrated cloud operators, Alibaba Cloud exemplifies the platform-bundling archetype through navigation-layer and merchant-data integration. Baidu occupies a position within mapping-technology specialists, sustaining R&D intensity through autonomous driving program linkages. Tencent represents the super-app embedding strategy, controlling consumer access to point-of-interest data through messaging architecture dominance.
| Leading Market Players |
|---|
| Alibaba Cloud (Alibaba Amap) |
| Baidu |
| Tencent |
| TomTom International BV |
| HERE Technologies |
| Zebra Technologies Corp |
| Telenav Inc |
| Meituan-Dianping |
| Jimdou |
| Others |
Pricing and Supply Chain Analysis
Geospatial AI engineering clusters in Beijing-Tianjin-Hebei and the Yangtze River Delta concentrate scarce satellite navigation-machine learning hybrid talent, widening labor-cost differentials between premium certified platforms and economy-grade positioning modules.
Pricing Analysis
Cost-down pressure on standard-tier positioning services accelerates because GNSS receiver chip fabrication concentrates among limited foundry capacity, compressing hardware margins. Subscription-based SaaS pricing stratifies across premium BeiDou-3 certified, standard dual-constellation, and economy GPS-only tiers. Price differentiation hinges on MIIT cybersecurity certification grade and API integration depth. State-owned logistics enterprises exhibit highest price sensitivity; autonomous driving programs demonstrate lowest sensitivity due to centimeter-accuracy requirements.
Supply Chain Analysis
Workforce availability for BeiDou-GPS dual-frequency receiver design concentrates in Shenzhen and Shanghai manufacturing corridors, tethering component sourcing to eastern coastal provinces. Raw material dependencies span Taiwan-sourced RF front-end chips, South Korean memory modules, and domestic Chinese ceramic antenna substrates. Single-source vulnerability in advanced node semiconductor fabrication poses structural risk. Distribution runs through cloud-platform bundling partnerships rather than discrete hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's location services sector functions as a vertical-integration race where control over merchant data flywheels and payment ecosystem embedding determines pricing power and customer lock-in.
For Market Incumbents: Deepen API-native integration capabilities to defend against modular point-solution challengers. Consolidate heterogeneous telematics infrastructures at state-owned logistics enterprises through backward integration into legacy fleet management systems. Prioritize BeiDou-3 interoperability certification investment to maintain government procurement eligibility under tightening GB standards. For New Entrants and Emerging Players: Super-app embedded distribution routes offer lowest customer acquisition friction for proximity marketing services. Target Tier-3 and Tier-4 county governments for undersupplied smart city digital service contracts. Pursue white-label indoor navigation partnerships with airport operators and shopping mall chains lacking dense POI databases. For Investors and Strategic Acquirers: Re-rating potential sits with full-stack location intelligence providers given enterprise buyer consolidation around bundled navigation-geofencing-analytics contracts. Long-term viability favors vendors controlling cloud infrastructure layers rather than discrete GPS hardware suppliers. Watch for MIIT encryption mandate compliance delays as inflection indicator for multinational platform operator exit opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| BeiDou-3 Interoperability Certification | MIIT procurement mandates now gate government fleet management contracts behind domestic satellite navigation compliance. |
| API-Native Platform Integration | Yangtze River Delta manufacturing clusters prioritize operational ERP connectivity over component cost minimization. |
| Super-App Embedding Partnership | WeChat architecture dominance channels most Chinese consumer POI access through messaging-layer location intelligence. |
| Autonomous Vehicle Mapping Layer Development | Apollo and robotaxi programs source centimeter-accuracy road network data for Shenzhen-Guangzhou expressway corridors. |
| Domestic Data Sovereignty Architecture | MIIT cybersecurity review frameworks block cross-border geospatial flows, favoring indigenous server infrastructure. |
Research Methodology
MIIT regulatory filings, SAMR anti-competitive practice disclosures, and GB standards documentation formed the secondary backbone. Primary interviews with cloud platform engineering directors, fleet management procurement leads at state-owned logistics enterprises, smart city digitization officers in Guangdong and Sichuan provinces, and autonomous driving program mapping specialists combined with secondary validation. Bottom-up and top-down triangulation cross-checked service-type deployment estimates against regional infrastructure contract values.
Analytical lenses alternated between bottom-up segment summation and top-down macro constraint calibration across the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, technology stack, and application workflow. CAGRs derived from fitted growth curves against documented procurement contract ramps and BeiDou-3 integration mandate timelines. Forecast inputs incorporated smart city infrastructure spend trajectories and e-commerce fulfillment network geofencing automation adoption rates.
The model holds under continued MIIT data localization enforcement and stable semiconductor foundry capacity; deviation in export control friction or encryption mandate acceleration would shift vendor consolidation timelines. Forecasts reflect documented procurement specifications and regulatory compliance trajectories. Material deviation in cybersecurity review framework stringency or autonomous driving program mapping data sourcing patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Business Mapping Software Market