
 South Korea Geospatial Analytics Market | 2026-2036
South Korea Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Geospatial Analytics Market Insights
MFDS data-sharing mandates is decoupling legacy spatial data vendors from hospital and public health mapping contracts. SK Telecom leverages its 5G network density to deliver real-time geospatial edge computing services. Samsung SDS anchors enterprise demand through integrated cloud-GIS platforms for logistics and supply chain visualization. Naver Labs differentiates via proprietary HD mapping engines purpose-built for autonomous navigation corridors.
South Korea Geospatial Analytics encompasses the acquisition, processing, and spatial modeling of location-tagged data using satellite imagery, LiDAR point clouds, and AI-driven raster analysis at sub-meter resolution. The discipline enables precise terrain modeling, infrastructure monitoring, and predictive environmental simulation for both public planning authorities and private asset operators. Urban Planning applications dominate current procurement volumes as municipal authorities digitize zoning and land-use frameworks. Government Agencies represent the most entrenched end-user category, though Transportation Operators are expanding fastest through fleet telematics and route optimization contracts. Cloud-Based deployment now captures the majority of new implementations, displacing legacy on-premises installations that require dedicated server maintenance.
MFDS standards for health-related spatial data, KISDI certification for geospatial information systems, and the Ministry of Environment's EIA digital reporting requirements collectively elevate compliance costs for market entrants. These frameworks mandate encrypted data pipelines, interoperable coordinate reference systems, and audit-ready metadata tagging that favor established domestic platforms. Stakeholders must weigh the trade-off between proprietary AI analytics development and alignment with evolving national spatial data infrastructure protocols.
Market Dynamics
Cloud migration mandates from Seoul Metropolitan Government and the Ministry of Land, Infrastructure and Transport are compressing procurement cycles for legacy on-premises spatial data infrastructure.
Growth Catalysts
- Digital Twin Mandates:The Ministry of Land, Infrastructure and Transport's national spatial data infrastructure roadmap requires municipal authorities to deploy city-scale digital twins for zoning and traffic management.
- 5G Network Density:Telecommunications carriers leverage ultra-low latency infrastructure to deliver real-time edge computing for autonomous vehicle corridor mapping and fleet telematics.
- LiDAR Cost Compression:Hardware price declines for aerial and mobile LiDAR systems enable construction firms to internalize terrain surveying rather than outsourcing to specialized vendors.
Market Restraints
- Coordinate Reference System Fragmentation:Legacy municipal datasets use non-standard projections that require expensive reprocessing before integration with national NSDI frameworks.
- Domestic Platform Concentration:Three domestic cloud-GIS providers control government procurement channels, creating barriers for specialized foreign analytics vendors.
- Encrypted Pipeline Requirements:MFDS and KISDI certification mandates force health and public safety applications onto domestic-only server infrastructure with restricted cross-border data flows.
Strategic Opportunities
- Busan-Ulsan Industrial Corridor:Port automation and heavy manufacturing clusters in the southeast lack dedicated geospatial service providers serving predictive maintenance and supply chain visualization.
- AI-Raster Convergence:Satellite imagery providers partner with domestic machine learning platforms to automate change detection for environmental impact assessments.
- Subscription Telemetry Models:Transportation operators in the Greater Seoul area pilot usage-based pricing for real-time traffic optimization services rather than perpetual license purchases.
Industry Challenges
- Geomatics Talent Scarcity:Universities produce insufficient graduates with combined GIS and cloud architecture skills to staff municipal digital twin projects.
- Interoperability Debt:Construction firms face multi-year migration timelines to reconcile proprietary CAD formats with open geospatial consortium standards required for government submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Geospatial Analytics Market |
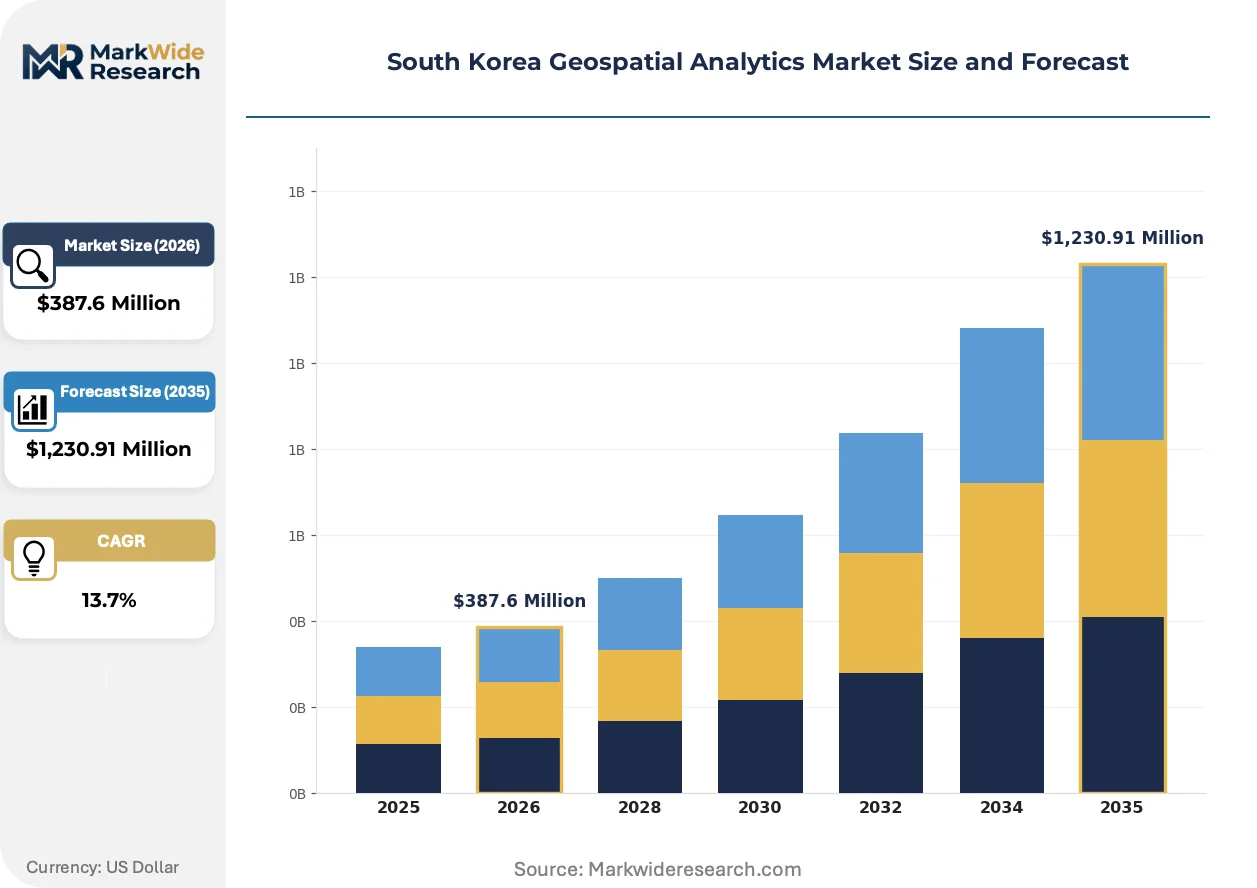
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,230.91 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Disaster Management, Agriculture Monitoring, Environmental Assessment End User: Government Agencies, Construction Firms, Environmental Corporations, Transportation Operators Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Platforms Technology: GIS Software, Remote Sensing, Satellite Imagery, AI-Driven Analytics |
| Companies Covered | Dabeeo Inc., LG CNS, ESRI Inc., SK Telecom, Samsung SDS, InSpace Co., Ltd., Naver Labs, KT, Bentley Systems, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Geospatial Analytics Market Trends and Innovations
Edge-native processing architectures and regulatory data-sharing frameworks are redrawing competitive boundaries between telecommunications infrastructure, cloud platforms, and specialized spatial analytics vendors.
Containerized geospatial processing engines are modularizing how municipal authorities deploy analytical workflows. Seoul's smart city command centers now orchestrate traffic, environmental, and emergency response analytics through interchangeable microservices rather than monolithic enterprise GIS suites. This architecture compresses vendor lock-in and accelerates procurement of best-of-breed point solutions.
MFDS data-sharing mandates for health-related spatial information are forcing hospital networks to replace legacy mapping vendors with certified domestic platforms. The regulation requires encrypted coordinate pipelines and audit-ready metadata tagging that foreign-hosted services cannot satisfy. Public health mapping contracts are consolidating onto KISDI-approved infrastructure.
Construction procurement teams now unbundle software licensing from implementation services. Large contractors in the Greater Seoul metropolitan area negotiate direct platform subscriptions while hiring specialized systems integrators for project-specific customization. This split separates commodity cloud-GIS access from high-margin consulting on digital twin deployment.
South Korea Geospatial Analytics Market Segmentation
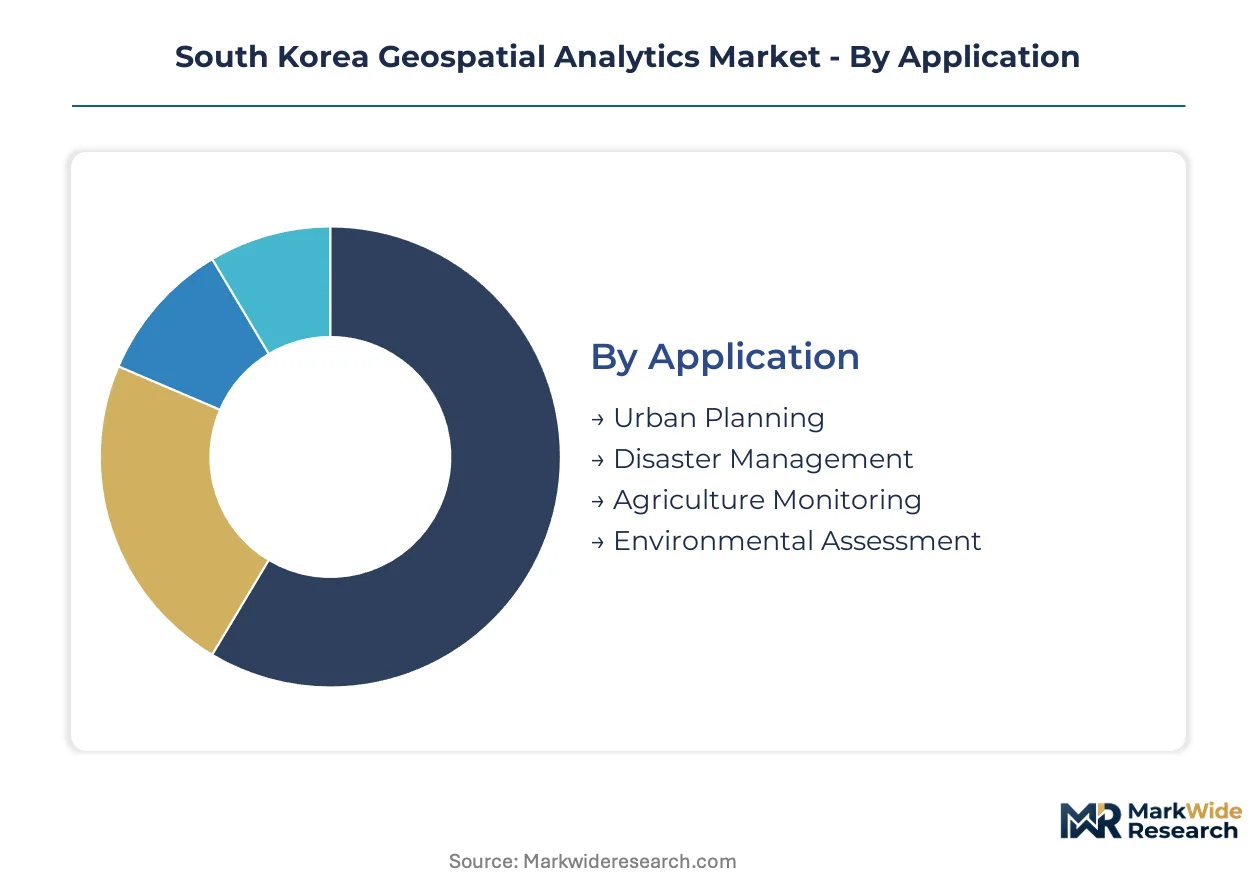
Segmentation in South Korea's geospatial analytics market reveals how procurement priorities diverge between centralized government mandates and decentralized enterprise requirements. Each dimension exposes distinct compliance burdens, technology preferences, and vendor selection criteria that shape competitive positioning.
Application:
Customization intensity varies sharply across this category, with some applications demanding bespoke sensor fusion while others run on standardized municipal templates.
- Urban Planning:Municipal authorities deploy city-scale digital twins integrating LiDAR point clouds with cadastral databases for zoning enforcement. Seoul Metropolitan Government compresses procurement cycles through pre-approved cloud-GIS templates, though satellite cities still require tailored implementations.
- Disaster Management:Real-time flood and landslide prediction systems fuse meteorological feeds with terrain models at sub-meter resolution. The Ministry of the Interior and Safety mandates interoperable coordinate reference systems, forcing expensive reprocessing of legacy municipal datasets before deployment.
- Agriculture Monitoring:Jeolla Province cooperatives pilot NDVI-based crop health dashboards for rice paddy management.
- Environmental Assessment:EIA digital reporting requirements from the Ministry of Environment standardize submission formats but allow flexibility in underlying analytics engines.
Leading the category by volume: Urban Planning. Growing fastest: Disaster Management.
End User:
Cost tier stratification separates capital-intensive infrastructure owners from subscription-oriented service operators.
- Government Agencies:National spatial data infrastructure mandates require encrypted pipelines and KISDI-certified platforms. The Ministry of Land, Infrastructure and Transport anchors procurement through multi-year digital twin contracts that favor established domestic vendors.
- Transportation Operators:Fleet telematics providers in the Greater Seoul area pilot usage-based pricing for real-time traffic optimization rather than perpetual licenses. SK Telecom leverages 5G network density to deliver edge-native routing services.
- Construction Firms:Large contractors unbundle software licensing from implementation services, negotiating direct cloud-GIS subscriptions while hiring specialized integrators.
- Environmental Corporations:EIA consultants face compressed margins as automated change detection displaces manual satellite imagery interpretation.
Dominating procurement value: Government Agencies. Expanding most quickly: Transportation Operators.
Deployment:
Customer type determines architecture preference, with security-conscious agencies resisting cloud migration despite operational advantages.
- Cloud-Based:Containerized microservices now orchestrate traffic, environmental, and emergency response analytics through interchangeable modules rather than monolithic suites. Seoul's smart city command centers compress vendor lock-in through this architecture.
- Hybrid Solutions:Construction firms reconcile proprietary CAD formats with open geospatial consortium standards through staged migration timelines spanning multiple project cycles.
- On-Premises:Legacy installations persist where MFDS and KISDI certification mandates restrict cross-border data flows.
- Mobile Platforms:Field survey teams in the Busan-Ulsan industrial corridor access offline terrain models with delayed synchronization to central repositories.
Capturing majority share: Cloud-Based. Steepest expansion trajectory: Hybrid Solutions.
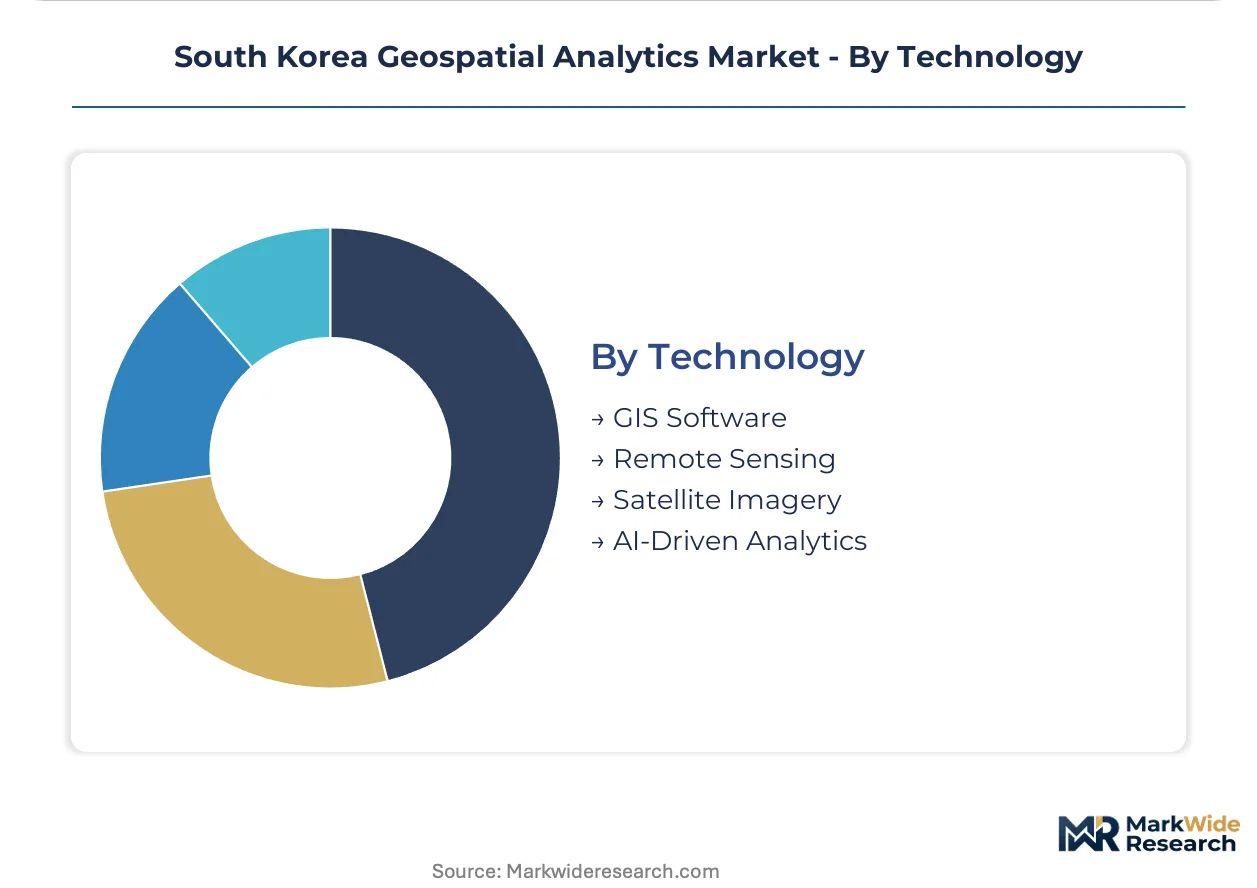
Technology:
Maturity gradients separate established software stacks from emerging AI-native approaches still seeking standardization.
- AI-Driven Analytics:Domestic machine learning platforms automate change detection for environmental impact assessments through partnerships with satellite imagery providers. Naver Labs differentiates via proprietary HD mapping engines purpose-built for autonomous navigation corridors.
- GIS Software:Samsung SDS anchors enterprise demand through integrated cloud-GIS platforms serving logistics and supply chain visualization requirements.
- Remote Sensing:Aerial and mobile LiDAR hardware price declines enable construction firms to internalize terrain surveying.
- Satellite Imagery:Sub-meter resolution products face procurement consolidation as domestic platforms bundle analytics with raw data access.
Highest revenue concentration: GIS Software. Gaining share fastest: AI-Driven Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area's smart city special zone concentrates national procurement for spatial data infrastructure. Busan-Ulsan and Daegu-Gyeongbuk industrial corridors anchor secondary demand clusters for port automation and manufacturing logistics visualization.
Seoul Capital Area
Seoul Metropolitan Government's cloud migration mandates compress procurement cycles for municipal digital twin deployments. The Ministry of Land, Infrastructure and Transport anchors multi-year contracts through its national spatial data infrastructure roadmap. Pangyo Techno Valley hosts containerized geospatial microservices orchestrating traffic, environmental, and emergency response analytics.
Busan-Ulsan
Port automation and heavy manufacturing clusters generate demand for predictive maintenance and supply chain visualization services. The Ministry of Oceans and Fisheries digitizes maritime logistics corridors through real-time vessel tracking and berth optimization systems. Ulsan's petrochemical complexes deploy LiDAR-based terrain monitoring for pipeline integrity assessment.
Daegu-Gyeongbuk
Automotive component manufacturing hubs require HD mapping for autonomous vehicle testing corridors. The Ministry of Trade, Industry and Energy funds smart factory initiatives integrating spatial analytics with production line digital twins. Gumi's electronics manufacturing cluster pilots edge-native processing for facility layout optimization.
Daejeon-Sejong
Government research institutes anchor public sector demand for satellite imagery analysis and environmental simulation. The Korea Aerospace Research Agency's space development program stimulates domestic remote sensing platform procurement. Sejong City's administrative district serves as a testbed for integrated national spatial data infrastructure protocols.
Gwangju-Honam
Jeolla Province agricultural cooperatives pilot NDVI-based crop health dashboards for rice paddy management. The Ministry of Agriculture, Food and Rural Affairs subsidizes precision farming geospatial tools for regional deployment. Gwangju's AI research cluster partners with satellite imagery providers to automate agricultural change detection.
South Korea Geospatial Analytics Market Competitive Landscape
Domestic conglomerate affiliates anchor one tier; specialized geospatial software vendors and telecommunications carriers hold differentiated positions. Three domestic cloud-GIS providers control government procurement channels, creating barriers for foreign analytics vendors. The market stratifies across integrated platform operators, network infrastructure specialists, and point-solution developers. Competitive moves concentrate on vertical integration into LiDAR hardware supply and strategic partnerships with satellite imagery providers.
Among telecommunications-anchored service providers, SK Telecom and KT exemplify the network-leverage archetype, converting 5G infrastructure density into edge computing delivery for real-time geospatial applications. Samsung SDS occupies a position within the enterprise platform tier, integrating cloud-GIS with logistics and supply chain visualization. Naver Labs represents the specialized mapping engine segment, developing proprietary HD mapping for autonomous navigation corridors.
| Leading Market Players |
|---|
| Dabeeo Inc. |
| LG CNS |
| ESRI Inc. |
| SK Telecom |
| Samsung SDS |
| InSpace Co., Ltd. |
| Naver Labs |
| KT |
| Bentley Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Government procurement concentration through the Ministry of Land, Infrastructure and Transport's digital twin mandates anchors subscription-based pricing for cloud-GIS platforms. Construction firms unbundling software from services creates tiered access models separating commodity platform fees from premium integration margins.
Pricing Analysis
Short lead-time premiums apply to KISDI-certified deployments for health and public safety applications where MFDS mandates compress vendor selection windows. Three-tier pricing structure across premium, standard, and economy levels separates encrypted government-grade pipelines from commercial cloud access and basic on-premises licensing. Cost compression in mobile LiDAR hardware is intensifying price competition for terrain surveying services as construction firms internalize data capture. Transportation operators exhibit highest price sensitivity through usage-based telemetry pilots, while national spatial data infrastructure contracts show lowest sensitivity due to compliance-driven vendor consolidation.
Supply Chain Analysis
KISDI certification and MFDS encrypted pipeline requirements gate foreign platform access, favoring domestic cloud-GIS providers for government contracts. Hardware supply draws from Japan for precision LiDAR sensors, the United States for satellite imagery constellations, and domestic Korean foundries for edge computing chipsets. Single-source vulnerability concentrates in 5G network infrastructure where SK Telecom and KT control edge-native service delivery. Distribution runs through systems integrators for construction sector deployments and direct ministry contracts for public sector implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over LiDAR hardware supply and satellite imagery partnerships determines margin capture. Players pursuing backward integration into sensor manufacturing secure cost advantages in terrain surveying services.
For Market Incumbents: Anchor multi-year digital twin contracts through Pangyo Techno Valley consortium relationships to preempt municipal procurement consolidation. Invest in KISDI certification maintenance as foreign platform restrictions tighten, while building captive LiDAR hardware capabilities to offset outsourcing margins eroded by construction firm internalization. For New Entrants and Emerging Players: Capture predictive maintenance white space in the Busan-Ulsan industrial corridor where port automation lacks dedicated geospatial service providers. The agriculture monitoring segment in Jeolla Province offers lowest competitive density for NDVI-based crop health platforms. Partner with domestic machine learning platforms for AI-raster convergence rather than building proprietary analytics engines. For Investors and Strategic Acquirers: The window for entry favors specialized HD mapping engine developers with autonomous navigation corridor deployments. Long-term viability hinges on vertical integration depth across hardware, platform, and analytics layers. Watch for MFDS mandate expansion beyond health into environmental and safety applications as the inflection signal for regulatory-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| LiDAR Hardware Backward Integration | Construction firm internalization of terrain surveying compresses outsourced service margins. |
| KISDI Certification Investment | MFDS encrypted pipeline mandates restrict public health contracts to approved domestic platforms. |
| 5G Edge-Native Service Launch | SK Telecom leverages network density for real-time autonomous vehicle corridor mapping. |
| Satellite Imagery Partnership | Domestic ML platforms automate environmental change detection through data provider alliances. |
| Busan-Ulsan Geographic Expansion | Port automation and heavy manufacturing clusters lack dedicated predictive maintenance providers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with municipal digital twin project managers, construction procurement leads, cloud-GIS platform engineers, and transportation fleet operations directors validated demand assumptions. KISDI certification databases, MFDS health data-sharing guidelines, Ministry of Land, Infrastructure and Transport procurement disclosures, and Seoul Metropolitan Government smart city expenditure reports supplied quantitative benchmarks. Bottom-up segment sizing triangulated against top-down national spatial data infrastructure budget allocations.
Granularity-level modeling deployed application-specific growth rates for urban planning and disaster management, end-user tier differentiation across government agencies and transportation operators, and deployment architecture shifts from on-premises to cloud-based and hybrid solutions. Technology trajectories for AI-driven analytics and GIS software were assessed separately. CAGRs derived from regression analysis of historical procurement cycles and projected infrastructure investment schedules across the analysis window. Satellite imagery resolution improvements and LiDAR hardware cost curves informed technology adoption assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MFDS mandate scope expansion and 5G network density deployment timelines. Forecasts reflect assumptions about municipal budget continuity and national spatial data infrastructure roadmap adherence. A model refresh is warranted upon material change in digital twin procurement acceleration or LiDAR hardware price compression rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market