
 India Location-Based Services Market | 2026-2036
India Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Location-Based Services Market Insights
Modular API bundling is hardening as the dominant configuration pattern across India's LBS ecosystem, letting enterprises mix navigation layers with fleet analytics without full-stack commitments. MapmyIndia leverages its proprietary digital map database to sustain dominance in automotive OEM integrations. Google LLC competes through dense POI coverage and Android-native distribution. Ola anchors mobility-specific location intelligence through its ride-hailing infrastructure.
Location-based services encompass spatial data acquisition, coordinate processing, and contextual delivery systems that fuse GPS satellite triangulation with Wi-Fi positioning and Bluetooth beacon proximity to enable real-time geospatial decision-making. The technology stack processes latitude-longitude fixes against digital elevation models and vector map layers to output routing, geofencing, or asset-tracking commands. GPS-based deployments lead in precision-critical use cases such as emergency response and highway logistics, while Wi-Fi and Bluetooth segments capture indoor positioning demand from retail analytics operators. Cloud deployment models are expanding fastest among mid-market transportation firms seeking elastic compute for seasonal route optimization.
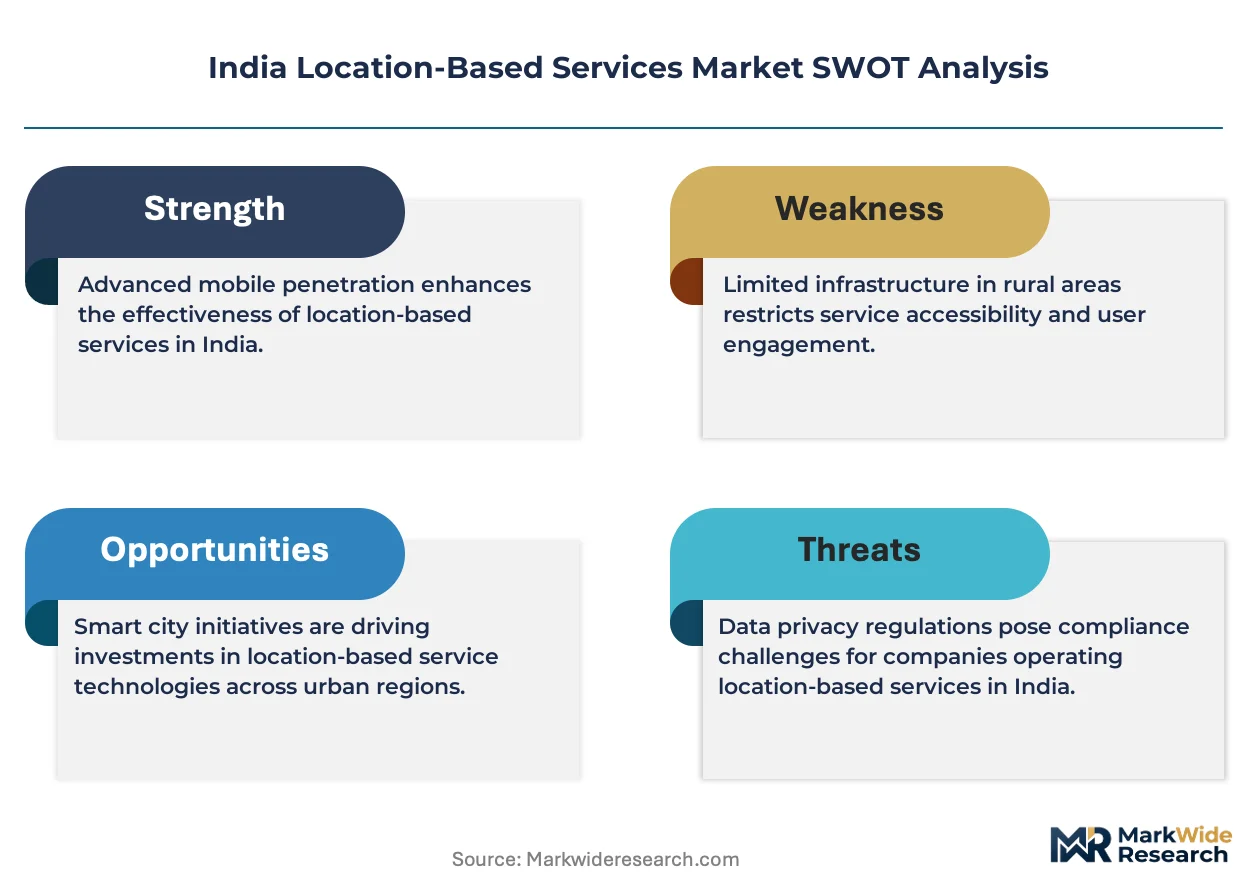
BIS geospatial data guidelines, TRAI location-privacy directives, and the Digital India framework collectively shape data localization mandates and accuracy standards for commercial LBS providers. CDSCO and state-level transport authorities impose additional traceability requirements on healthcare logistics and commercial fleet operators respectively. Stakeholders must monitor evolving BIS certification timelines and state-level smart city procurement shifts to calibrate platform investments.
Market Dynamics
Modular API architectures are fragmenting platform monopolies across India's LBS stack, forcing incumbents to unbundle navigation, analytics, and geofencing into interoperable microservices that mid-market logistics operators can recombine without vendor lock-in.
Growth Catalysts
- Digital India Geospatial Mission:The national geospatial data infrastructure mandate is compelling state governments to procure standardized location platforms for urban planning and emergency response systems.
- Fleet electrification tracking:Battery-electric commercial vehicle operators require sub-meter positioning accuracy for range optimization and charging station sequencing, pulling precision LBS into transport logistics.
- Maharashtra-Karnataka-Telangana logistics corridor:Concentrated warehousing and smart city investments across these three states are generating clustered demand for real-time asset visibility.
Market Restraints
- Semiconductor component import dependence:GPS module and Bluetooth beacon chip supply remains concentrated in East Asian manufacturing hubs, exposing domestic integrators to input cost volatility and customs clearance friction.
- BIS certification timelines:Geospatial data accuracy standards under Bureau of Indian Standards review cycles extend platform commercialization windows by 8-14 months for new market entrants.
- Wi-Fi positioning substitution:Indoor navigation demand in retail and healthcare facilities is partially captured by infrastructure-light computer vision systems that bypass dedicated beacon deployments.
Strategic Opportunities
- Tier-2 smart city penetration:Municipal corporations in Indore, Coimbatore, and Chandigarh are issuing location platform tenders for intelligent traffic management with less incumbent saturation than Mumbai or Bangalore.
- CDSCO pharmaceutical cold chain mandates:Temperature-sensitive drug distribution regulations are creating compliance-driven demand for integrated location-telemetry sensors in healthcare logistics.
- 5G-RTK convergence:Network-based real-time kinematic positioning fused with cellular latency improvements is enabling centimeter-accurate navigation without dedicated base station infrastructure.
Industry Challenges
- Geospatial data science talent scarcity:Domestic universities produce insufficient graduates trained in coordinate reference systems, spatial statistics, and SLAM algorithms to staff platform engineering teams.
- Legacy fleet management system integration:Transportation operators running decade-old telematics hardware face API incompatibility and data format migration costs when adopting cloud-native LBS stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Location-Based Services Market |
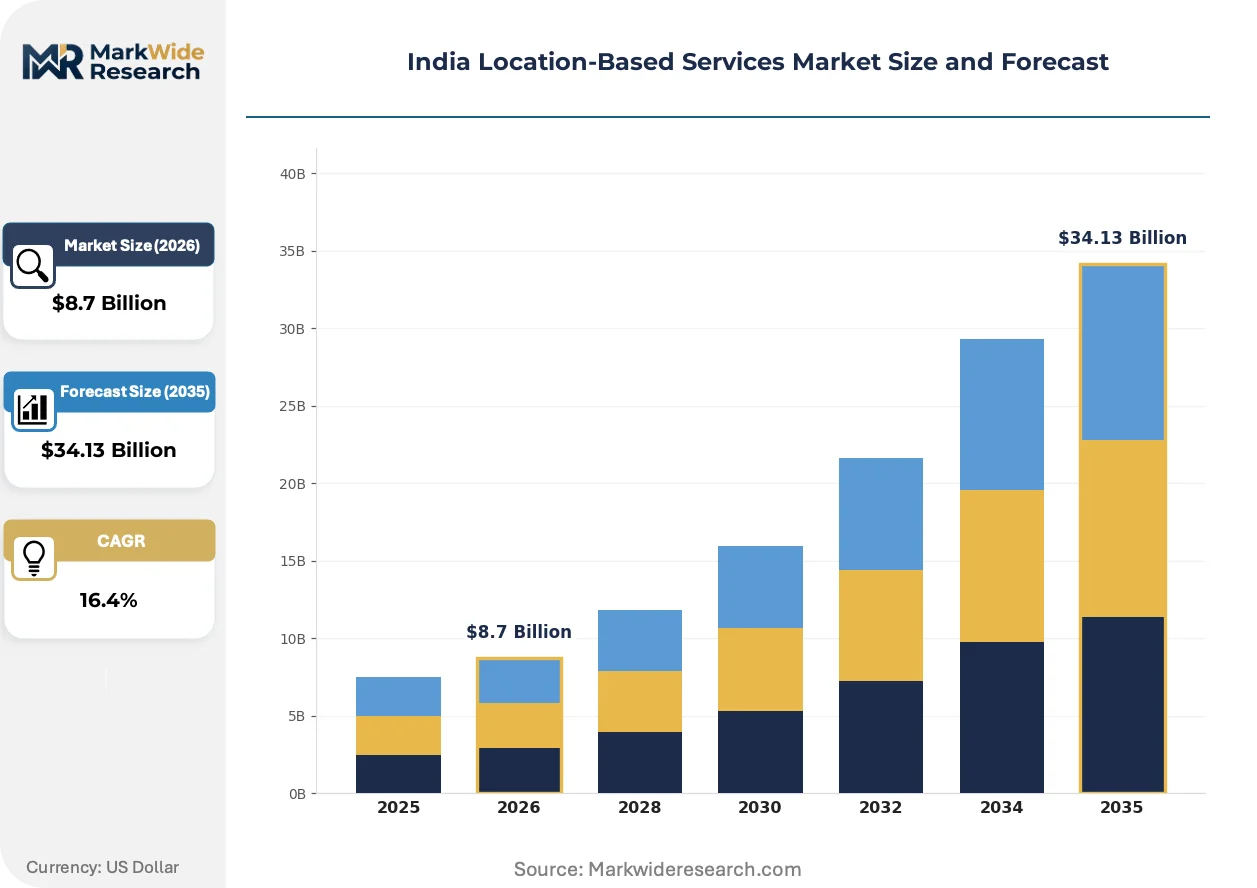
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Wi-Fi, Bluetooth, RFID Application: Navigation, Emergency Services, Fleet Management, Retail Analytics End User: Healthcare, Transportation, Retail, Entertainment Deployment: Cloud, On-Premises, Hybrid, Mobile |
| Companies Covered | Google LLC, MapmyIndia, Microsoft Corporation, Genesys International Corporation, Pert Telecom Solutions Pvt Ltd, GeoIQ, LocationIQ, Ola, Reliance Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Location-Based Services Market Trends and Innovations
Edge-computing architectures are relocating coordinate processing from centralized cloud instances to vehicle-mounted and smartphone-embedded chipsets, reducing latency for safety-critical navigation decisions while compressing data transmission costs.
Multi-constellation GNSS receivers integrating NavIC, GPS, GLONASS, and Galileo signals are decentralizing positioning authority away from single-satellite-system dependence. Indian automotive OEMs and drone manufacturers are adopting these chipsets to ensure continuity in urban canyon environments where building occlusion degrades GPS-only fixes. This hardware shift is compressing the addressable market for proprietary correction services that previously locked customers into vendor-specific augmentation networks.
Bureau of Indian Standards geospatial data localization guidelines are mandating domestic storage and processing of sensitive coordinate datasets. Cloud providers and platform operators are establishing Mumbai, Hyderabad, and Delhi region data centers to comply, redirecting infrastructure investment away from Singapore and Frankfurt hosting arrangements. Healthcare logistics and defense-adjacent applications face the strictest compliance scrutiny, with CDSCO and Ministry of Defence procurement specifications now explicitly requiring sovereign data residency.
Logistics buyers are unbundling location platform procurement from full-stack telematics contracts, negotiating direct API access to raw coordinate streams and geofencing engines. Large fleet operators in e-commerce and cold chain verticals are building in-house analytics layers atop commodity positioning infrastructure, displacing the systems-integration markup that historically captured 30-40% of contract value. This procurement pattern is most pronounced among Series C-funded logistics startups in Bangalore and Gurgaon seeking to differentiate through proprietary route optimization algorithms.
India Location-Based Services Market Segmentation
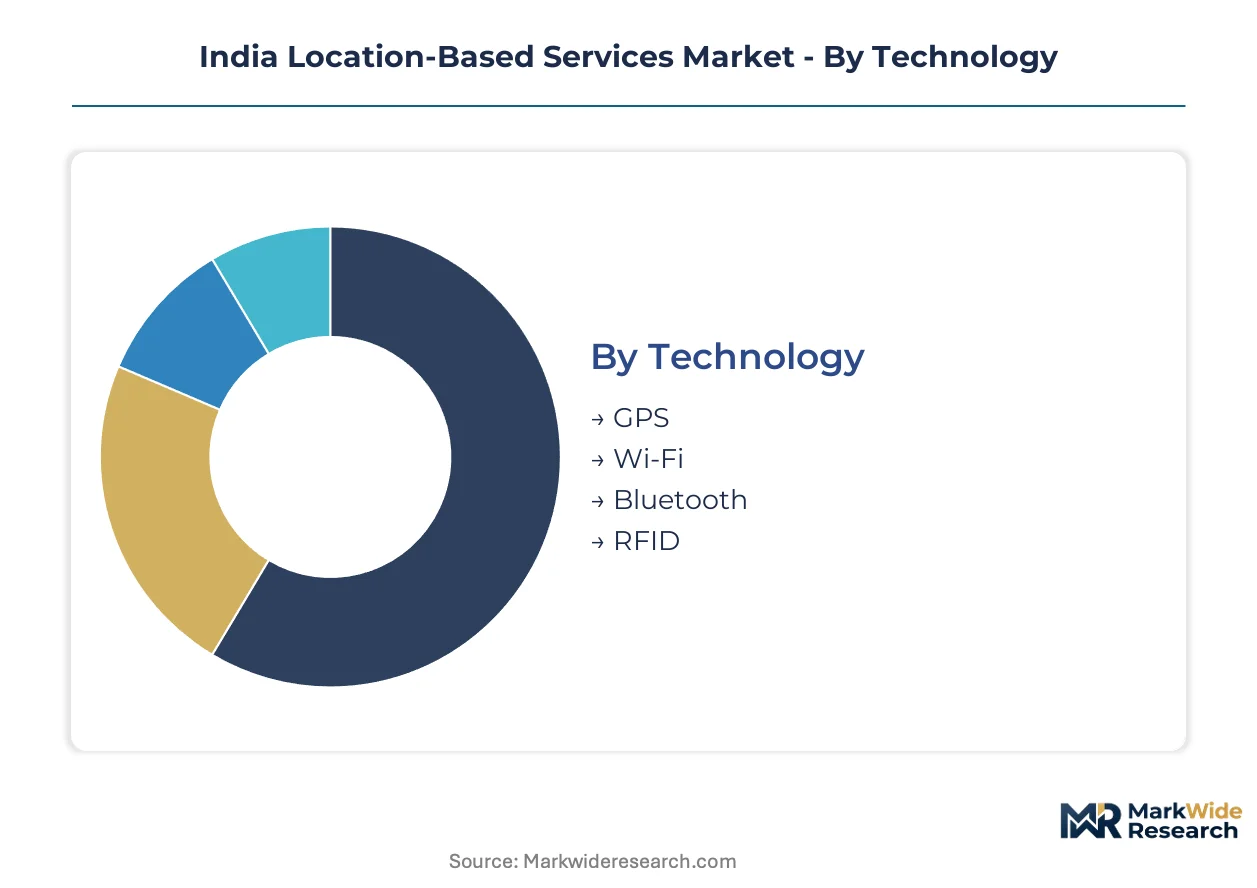
Segmentation in India's LBS market reveals how technology choices, deployment constraints, and end-user compliance requirements fragment procurement patterns. Buyers prioritize accuracy thresholds, data residency mandates, and integration complexity when selecting across these dimensions.
Technology:
Precision requirements and infrastructure availability drive technology selection, with outdoor versus indoor use cases dictating satellite versus beacon-dependent architectures.
- GPS:Satellite triangulation delivers sub-meter accuracy for highway logistics and emergency response routing. Fleet operators in Maharashtra and Karnataka deploy GPS-dominant stacks for commercial vehicle tracking under state transport authority mandates.
- Wi-Fi:Fingerprinting against known access point locations enables indoor positioning without dedicated hardware. Retail analytics deployments in Bangalore and Delhi shopping complexes favor Wi-Fi for customer journey mapping where beacon installation costs prove prohibitive.
- Bluetooth:Low-energy beacon proximity detection supports micro-location use cases in healthcare asset tracking and museum navigation systems.
- RFID:Passive and active radio-frequency identification handles short-range asset verification in warehouse inventory and supply chain gate operations.
Volume sits with GPS; growth tilts toward Bluetooth as indoor positioning demand expands beyond retail into healthcare and smart building applications.
Application:
Use-case specificity determines whether buyers prioritize real-time routing, compliance traceability, or behavioral analytics in platform procurement.
- Navigation:Turn-by-turn routing and mapping services power automotive OEM integrations and consumer mobility applications. Automotive manufacturers in Chennai and Pune source navigation layers for in-vehicle infotainment systems.
- Fleet Management:Real-time vehicle tracking, route optimization, and driver behavior analytics dominate logistics procurement. E-commerce fulfillment operators across the Mumbai-Pune corridor deploy fleet management platforms to meet delivery SLA commitments.
- Emergency Services:Location dispatch and responder coordination systems serve police, fire, and medical emergency infrastructure under state disaster management authority specifications.
- Retail Analytics:Footfall measurement, dwell time analysis, and proximity marketing support merchandising decisions in organized retail chains.
Fleet management commands current deployment scale; emergency services are climbing the fastest as state governments modernize disaster response infrastructure.
End User:
Regulatory intensity and operational criticality vary sharply across end-user verticals, with compliance mandates accelerating adoption in healthcare and transportation.
- Transportation:Commercial fleet operators, ride-hailing platforms, and logistics providers constitute the largest addressable base. Trucking companies and last-mile delivery services in Telangana integrate location platforms for regulatory compliance and fuel optimization.
- Healthcare:Hospital systems, pharmaceutical distributors, and emergency medical services require location-telemetry for asset tracking and cold chain verification. CDSCO mandates on temperature-sensitive drug distribution are pulling integrated location sensors into pharmaceutical logistics.
- Retail:Organized brick-and-mortar chains and quick-service restaurants deploy indoor positioning for customer analytics and operational efficiency.
- Entertainment:Theme parks, stadiums, and event venues leverage proximity services for crowd management and personalized visitor experiences.
Transportation anchors installed base; healthcare shows steepest expansion trajectory as regulatory traceability requirements harden.
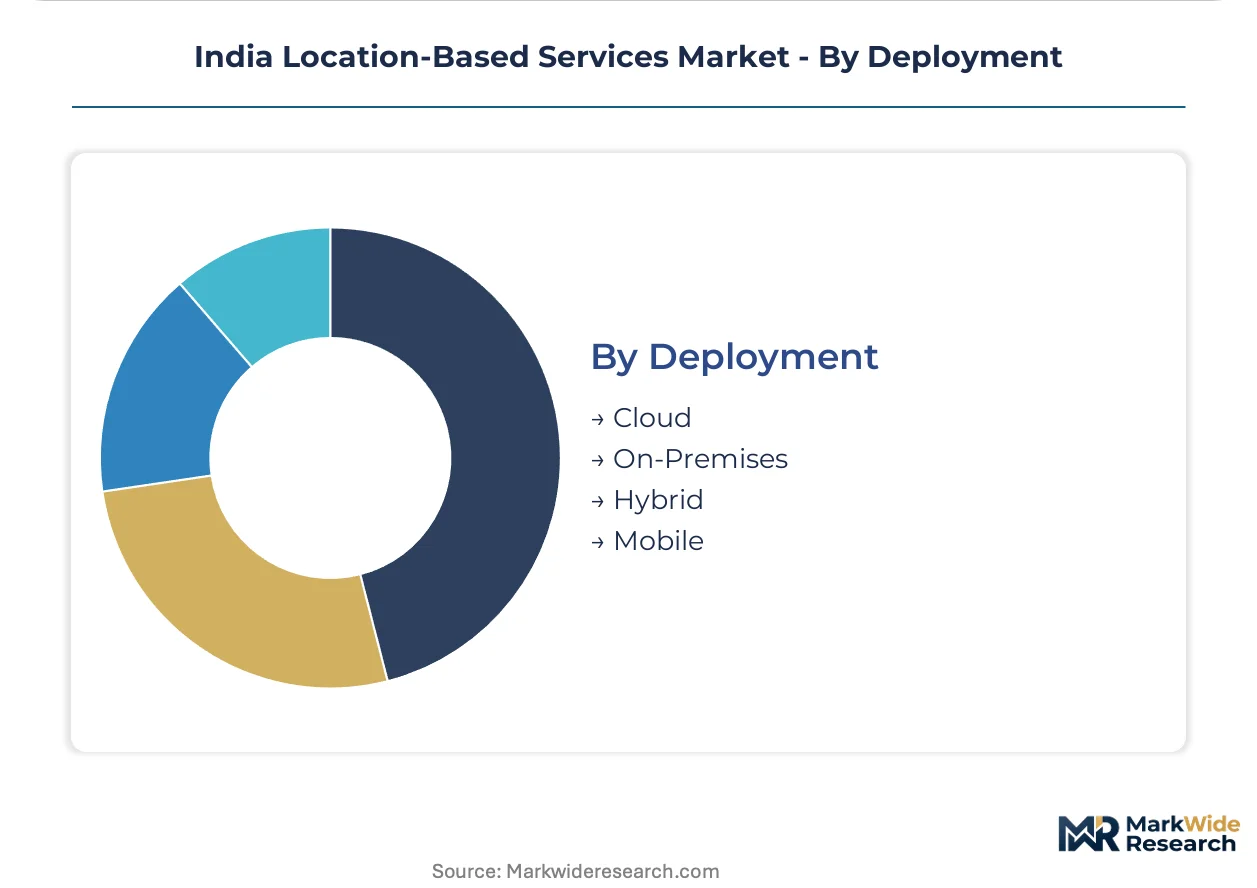
Deployment:
Infrastructure control preferences and data sovereignty obligations shape whether buyers accept vendor-managed cloud instances or retain on-premises processing.
- Cloud:Elastic compute and storage resources support seasonal demand fluctuations and rapid scaling. Mid-market logistics firms in Gurgaon and Bangalore prefer cloud deployment to avoid capital expenditure on server infrastructure.
- On-Premises:Dedicated hardware and private data centers satisfy defense-adjacent applications and strict data residency requirements. Ministry of Defence contractors and select healthcare networks mandate on-premises processing for sensitive coordinate datasets.
- Hybrid:Split architectures route non-sensitive processing to cloud instances while retaining critical operations locally. Smart city operators in Chandigarh and Indore adopt hybrid models to balance scalability with municipal data control.
- Mobile:Smartphone-embedded SDKs and edge-processing capabilities enable consumer-facing applications without dedicated backend infrastructure.
Cloud deployment holds dominant share; hybrid configurations are gaining share fastest as BIS localization guidelines compel domestic data residency without full infrastructure ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform consumption concentrates in western and southern India where logistics corridors and smart city investments cluster, while production of LBS hardware components remains import-dependent from East Asian manufacturing hubs.
Maharashtra
Mumbai-Pune logistics operators deploy real-time fleet tracking to meet e-commerce delivery SLAs under state transport authority mandates. The Digital India Geospatial Mission drives municipal procurement of location platforms for urban planning. Organized retail chains in Mumbai shopping complexes favor Wi-Fi-based indoor positioning for customer journey analytics.
Karnataka
Bangalore-based Series C logistics startups build proprietary route optimization atop commodity positioning APIs to differentiate service offerings. BIS geospatial data guidelines compel domestic data residency for platform operators serving state government contracts. Automotive OEMs in Chennai-Pune corridor source navigation layers from local integrators for in-vehicle infotainment systems.
Telangana
Hyderabad warehousing clusters generate concentrated demand for asset visibility platforms serving pharmaceutical cold chain distribution. CDSCO temperature-sensitive drug mandates pull integrated location-telemetry sensors into healthcare logistics networks. State disaster management authorities modernize emergency response infrastructure with location dispatch systems.
Gujarat
Kandla-Mundra port logistics operators adopt GPS-dominant stacks for commercial vehicle tracking and customs clearance optimization. DGFT trade facilitation programs accelerate digital documentation linked to real-time cargo positioning. Chemical and pharmaceutical manufacturers in Ahmedabad-Vadodara belt deploy geofencing for hazardous material movement compliance.
Tamil Nadu
Chennai automotive manufacturing hubs integrate multi-constellation GNSS receivers combining NavIC with GPS signals for supply chain visibility. State electronics manufacturing clusters under PLI scheme attract component assembly for positioning chipsets. Smart city tenders in Coimbatore target intelligent traffic management with lower incumbent saturation than metropolitan markets.
India Location-Based Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's LBS stack, creating a tiered structure where global technology platforms, domestic mapping specialists, and vertical-specific operators each occupy distinct positioning. The vendor base separates into three strategic archetypes: global cloud-native platforms leveraging dense POI coverage, proprietary digital map database owners serving automotive OEM integrations, and mobility infrastructure operators monetizing ride-hailing location intelligence. Dominant competitive moves include modular API unbundling to reduce vendor lock-in and data center localization to satisfy BIS geospatial residency mandates.
Among global technology platforms, Google LLC and Microsoft Corporation exemplify the cloud-native archetype with broad service distribution, while MapmyIndia anchors the domestic specialist tier through proprietary mapping assets. Ola occupies a distinct position as a mobility-native operator leveraging ride-hailing infrastructure for location intelligence services.
| Leading Market Players |
|---|
| Google LLC |
| MapmyIndia |
| Microsoft Corporation |
| Genesys International Corporation |
| Pert Telecom Solutions Pvt Ltd |
| GeoIQ |
| LocationIQ |
| Ola |
| Reliance Industries |
| Others |
Pricing and Supply Chain Analysis
BIS geospatial data localization guidelines gate qualified supply and premium-tier pricing access for platform operators seeking government and defense-adjacent contracts. Compliance-capable providers command pricing premiums while non-compliant vendors face exclusion from high-value procurement channels.
Pricing Analysis
Margin tightening in the mid-market tier reflects unbundling pressure as logistics operators bypass systems-integration markups for direct API access. Pricing stratifies across BIS-certified premium tiers, standard commercial deployments, and economy-grade commodity positioning services. Price differentiation hinges on certification grade and data residency compliance. Cost-down pressure on standard-tier offerings accelerates because cloud-native entrants are compressing subscription rates. Small fleet operators in Tier-2 cities exhibit highest price sensitivity; defense contractors and pharmaceutical distributors show lowest sensitivity due to compliance mandates.
Supply Chain Analysis
GPS module and Bluetooth beacon chip supply rests on Taiwanese, South Korean, and Chinese semiconductor manufacturing clusters. Raw material dependencies span silicon wafers, rare-earth magnet components for antenna assemblies, and lithium-ion cells for beacon power systems. Single-source vulnerability concentrates in advanced GNSS receiver chipsets where NavIC-compatible fabrication capacity remains limited. Distribution runs through domestic systems integrators serving automotive OEMs, logistics operators, and smart city implementers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor component import dependence props pricing power for compliant domestic integrators who can guarantee supply continuity. Capacity bottlenecks in certified geospatial data processing infrastructure sustain premium-tier margins.
For Market Incumbents: Cement dominance in automotive OEM channels through proprietary NavIC-GPS multi-constellation chipset partnerships. Deepen backward integration into domestic data center infrastructure to satisfy BIS residency mandates. Defend against modular API unbundling by embedding analytics layers that increase switching costs for fleet management customers. For New Entrants and Emerging Players: Municipal corporations in Tier-2 smart cities represent the most penetrable channel partner type for location platform tenders with reduced incumbent saturation. Target Indore, Coimbatore, and Chandigarh for intelligent traffic management contracts. Pursue CDSCO pharmaceutical cold chain compliance as a differentiated entry wedge against generalist competitors. For Investors and Strategic Acquirers: State-level smart city procurement award acceleration is the leading indicator that platform demand is inflecting beyond metropolitan saturation. Long-term viability favors acquisition of domestic mapping specialists with sovereign data residency infrastructure. Watch BIS certification timeline compression as the signal for competitive entry window narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| NavIC-GPS Multi-Constellation Integration | Indian automotive OEMs adopt indigenous satellite positioning to ensure urban canyon continuity. |
| Domestic Data Center Establishment | Cloud providers build Mumbai, Hyderabad, Delhi regions to satisfy BIS geospatial residency mandates. |
| Modular API Unbundling | Logistics operators recombine navigation, analytics, and geofencing microservices without vendor lock-in. |
| Pharmaceutical Cold Chain Certification | CDSCO temperature-sensitive drug mandates pull integrated location-telemetry sensors into healthcare logistics. |
| Tier-2 Smart City Platform Deployment | Municipal corporations in Indore, Coimbatore, Chandigarh issue tenders with lower incumbent saturation. |
Research Methodology
Document review covered BIS geospatial guidelines, TRAI location-privacy directives, CDSCO pharmaceutical distribution regulations, and state transport authority mandates, complemented by interviews with fleet management operators, automotive OEM platform engineers, smart city procurement officers, and cloud infrastructure architects. Secondary sources included Digital India mission documentation, SEC filings of listed technology platforms, hyperscaler capex disclosures, and customs import data for positioning chipsets. Bottom-up demand modeling and top-down market sizing were triangulated to validate volume estimates.
Cross-referencing historical deployment trajectories against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology type, application use case, end-user vertical, and deployment architecture. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure investment pipelines. Forecast inputs incorporated 5G-RTK convergence timelines and state-level smart city budget allocations.
Caveats apply where BIS certification timeline extensions, semiconductor supply disruptions, or Wi-Fi positioning substitution by computer vision systems could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Mobile Mapping Market