
 FMCG Spending on Analytics Market | 2026-2036
FMCG Spending on Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
FMCG Spending on Analytics Market Foresight
EU Green Deal compliance obligations are restructuring how European FMCG procurement teams evaluate supplier analytics capabilities. Nestlé leverages integrated demand-sensing platforms to reduce food waste across its European manufacturing network. Unilever anchors its competitive position through proprietary pricing analytics that respond to real-time commodity volatility. PepsiCo dominates cloud-based deployment spending among North American beverage manufacturers, extending analytics access from headquarters to regional bottling partners.
FMCG spending on analytics encompasses the allocation of capital and operating budgets by fast-moving consumer goods enterprises toward data infrastructure, statistical modeling platforms, and decision-support systems that convert transactional, operational, and external data into actionable commercial intelligence. These investments typically support demand forecasting at SKU-location-day granularity, promotional elasticity measurement, and automated replenishment triggers across multi-echelon distribution networks. Customer insights solutions command the largest share of solution-type spending as brands prioritize first-party data activation following cookie deprecation, while supply chain optimization registers the fastest growth trajectory as manufacturers rebuild buffer inventory strategies post-disruption. Cloud-based deployment leads in new contract value though hybrid architectures gain traction among enterprises with legacy ERP dependencies in emerging markets.
FDA food traceability rules under the Food Safety Modernization Act compel analytics investments that enable lot-level tracking from ingredient source to retail shelf. REACH chemical disclosure requirements in Europe force reformulation analytics that model substitution impacts on product performance and cost. India's BIS certification mandates for packaged goods drive quality-control analytics integration into manufacturing execution systems. Stakeholders must weigh build-versus-buy decisions for edge analytics infrastructure as retail partners impose increasingly granular data-sharing requirements.
Market Dynamics
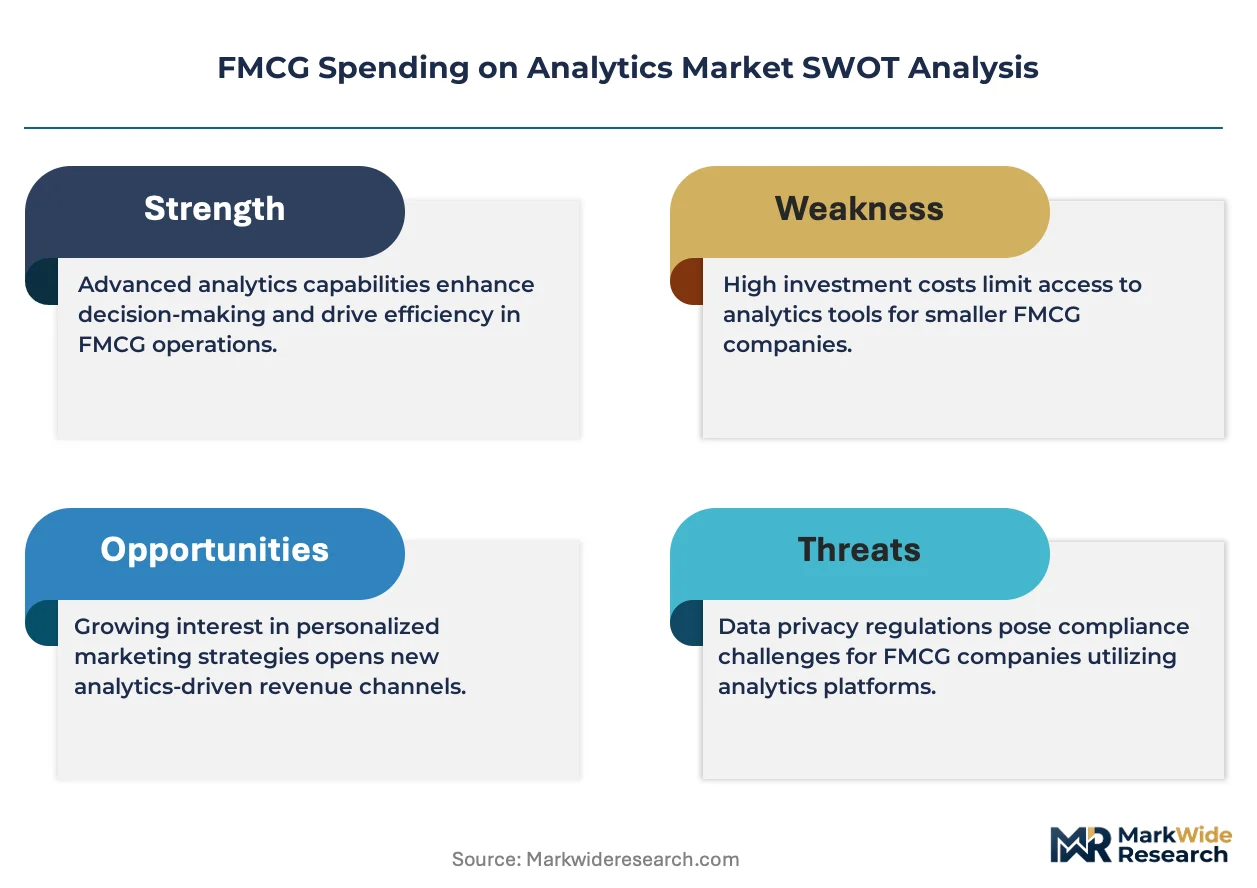
Retailer sustainability scorecards are forcing FMCG manufacturers to restructure supplier data-sharing protocols, compressing procurement cycles while expanding analytics infrastructure budgets.
Growth Catalysts
- EU Green Deal compliance:European procurement teams now mandate supplier analytics capabilities for carbon footprint verification, redirecting vendor selection criteria toward data transparency.
- AI-driven demand sensing:Machine learning platforms enable SKU-location-day granularity in forecasting, cutting food waste across manufacturing networks.
- Cloud deployment concentration:United States, Germany, and India host the majority of new analytics contracts as brands compete on supply chain visibility.
Market Restraints
- Legacy ERP dependencies:Hybrid architectures face implementation friction where emerging market enterprises maintain decades-old system investments.
- Data talent scarcity:Edge analytics infrastructure requires specialized skill sets that concentrate in technology hubs, inflating compensation costs.
- REACH chemical disclosure:European reformulation analytics impose compliance timelines that delay product launches and increase R&D overhead.
Strategic Opportunities
- First-party data activation:Cookie deprecation pushes customer insights solutions to the top of solution-type spending priorities.
- Buffer inventory rebuilding:Post-disruption supply chain optimization registers accelerated investment as manufacturers hedge against volatility.
- PLI scheme alignment:India's production-linked incentive framework rewards quality-control analytics integration into manufacturing execution systems.
Industry Challenges
- Edge infrastructure build-versus-buy:Retail partners impose granular data-sharing requirements that strain capital allocation decisions.
- Multi-echelon integration:Automated replenishment triggers must synchronize across incompatible distributor systems.
- FDA traceability compliance:Lot-level tracking from ingredient source to retail shelf demands analytics investments with uncertain ROI timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FMCG Spending on Analytics Market |
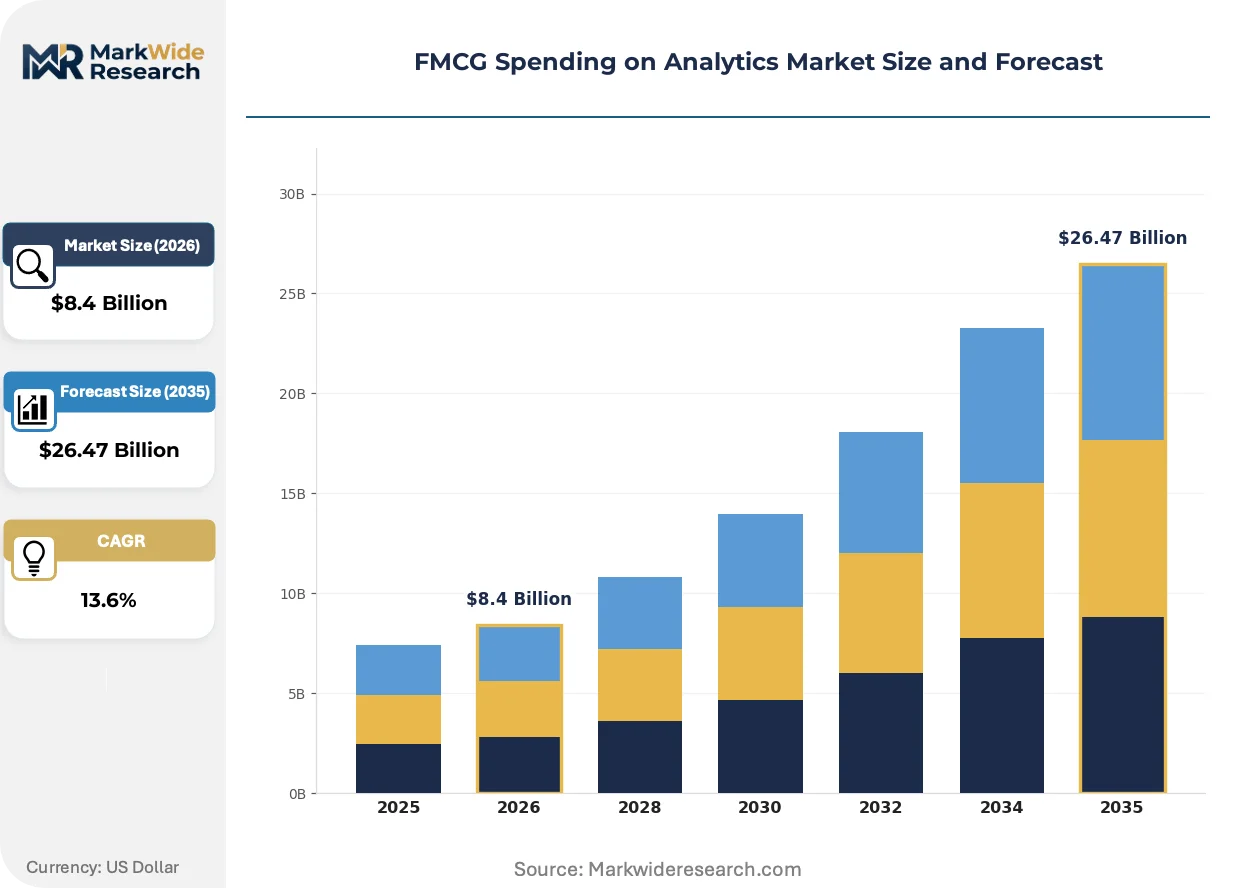
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premise, Hybrid, Edge Analytics, SaaS Solution Type: Customer Insights, Demand Forecasting, Supply Chain Optimization, Pricing Analytics, Marketing Analytics Use Case: Sales Performance Analysis, Inventory Management, Consumer Behavior Tracking, Campaign Effectiveness, Risk Management Customer Type: Retail Chains, Wholesalers, Distributors, E-commerce Platforms, Packaging Suppliers |
| Companies Covered | PepsiCo, Johnson and Johnson, Nestlé, Dabur India, Anheuser Busch InBev, Procter & Gamble, Coca-Cola Company, ITC Limited, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FMCG Spending on Analytics Market Shifts & Advancements
Data infrastructure architecture is fragmenting as manufacturers balance cloud scalability against sovereign data requirements, creating divergent deployment patterns across regulatory jurisdictions.
Edge computing is decentralizing analytics processing from centralized cloud warehouses to manufacturing floor sensors and retail point-of-sale terminals. Mid-sized beverage bottlers in North America are deploying these systems faster than headquarters-led rollouts anticipated. This topology is decentralizing decision velocity, compressing replenishment cycles from days to hours while reducing bandwidth costs.
REACH chemical disclosure requirements in Europe force continuous reformulation analytics that model substitution impacts on product performance and cost. Manufacturers must maintain dynamic ingredient databases that update with each regulatory amendment. Cosmetics and household cleaning categories face the steepest compliance curves, driving cross-functional teams to embed regulatory analysts directly into product development workflows.
Retailer sustainability scorecards now dictate vendor retention decisions, replacing price-only procurement with multi-criteria supplier evaluation. European grocery chains lead this transition, while North American mass merchants follow with modified implementations. Food and beverage manufacturers experience the strongest pressure, reconfiguring data collection systems to capture farm-level provenance and transport emissions.
FMCG Spending on Analytics Market Segmentation
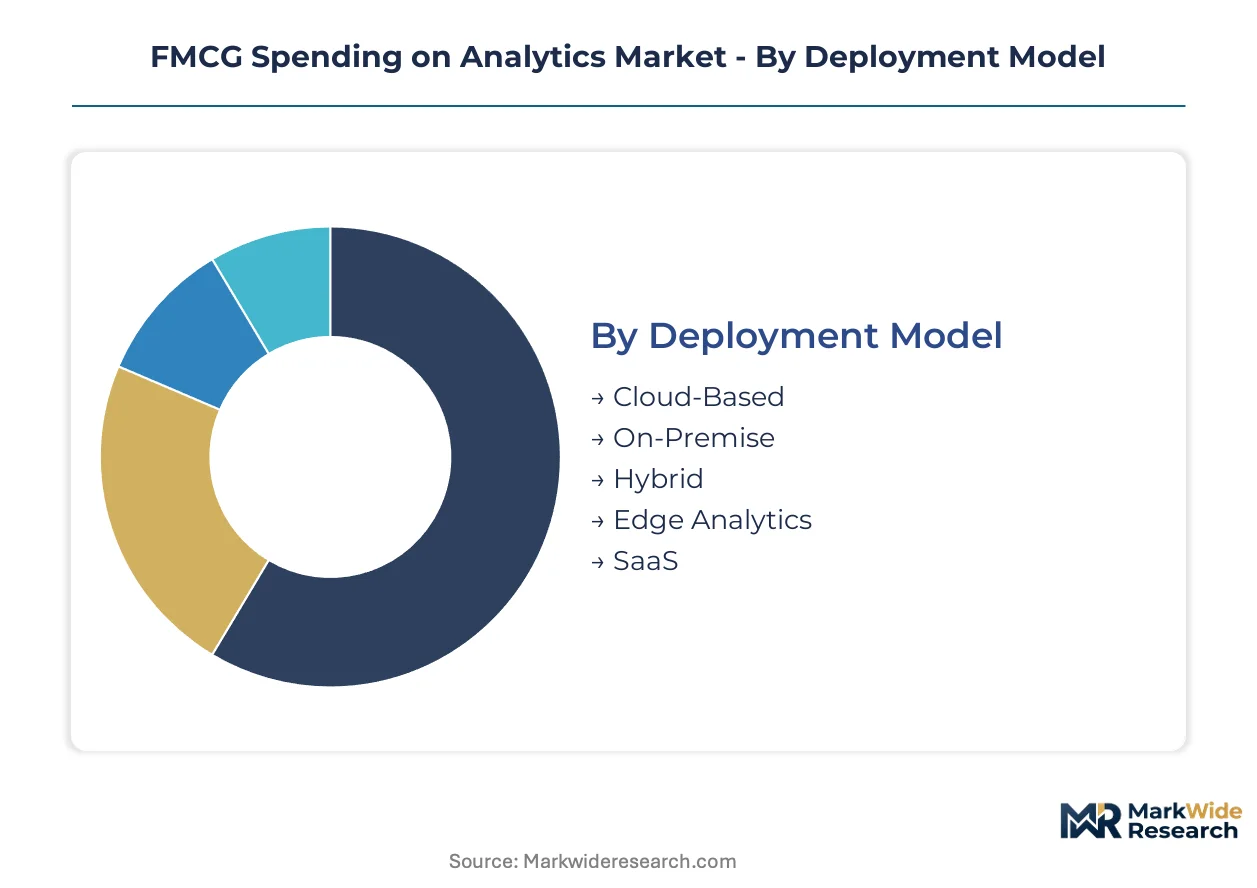
Deployment architecture, solution specialization, and customer procurement maturity determine how analytics budgets fragment across the FMCG value chain. Procurement teams evaluate total cost of ownership against data sovereignty requirements when selecting vendor configurations.
Deployment Model:
Capital intensity and data residency requirements shape procurement decisions across infrastructure categories.
- Cloud-Based:Scalable compute resources enable real-time demand sensing without hardware procurement cycles. United States-based manufacturers concentrate spending here to support SKU-location-day forecasting granularity while minimizing IT overhead.
- On-Premise:Dedicated server installations maintain physical control over proprietary formulation data and pricing algorithms. German manufacturers prioritize this model to satisfy GDPR data localization requirements in competitive intelligence applications.
- Hybrid:Split architectures process sensitive pricing analytics on-premises while pushing demand forecasting workloads to cloud environments. Emerging market enterprises with legacy ERP dependencies favor this transitional approach.
- Edge Analytics:Distributed processing at manufacturing sensors and retail terminals reduces latency for automated replenishment triggers.
- SaaS:Subscription-based access lowers upfront investment barriers for mid-sized beverage bottlers expanding analytics capabilities.
Cloud-Based leads on scale; Edge Analytics leads on momentum.
Solution Type:
Functional priority reflects competitive pressure points across revenue and cost centers.
- Customer Insights:First-party data activation platforms replace deprecated cookie-based targeting with direct consumer relationship management. Brands in India deploy these solutions to capture behavioral signals from e-commerce platform integrations.
- Demand Forecasting:Machine learning models project consumption patterns at granular geographic and temporal intervals. Food manufacturers leverage these tools to reduce waste across European manufacturing networks subject to EU Green Deal compliance timelines.
- Supply Chain Optimization:Multi-echelon inventory positioning responds to post-disruption volatility in input costs and availability.
- Pricing Analytics:Real-time commodity volatility monitoring enables dynamic margin protection.
- Marketing Analytics:Campaign attribution measurement quantifies promotional elasticity across retail channels.
Customer Insights commands procurement priority; Supply Chain Optimization expands most quickly.
Use Case:
Operational pain points determine which analytical applications receive implementation resources.
- Sales Performance Analysis:Territory-level revenue tracking identifies underperforming retail execution.
- Inventory Management:Automated replenishment triggers synchronize stock levels across incompatible distributor systems.
- Consumer Behavior Tracking:Purchase pattern analysis informs product assortment decisions.
- Campaign Effectiveness:Promotional ROI measurement validates trade spend allocation.
- Risk Management:Scenario modeling hedges against supply disruption and regulatory non-compliance.
Inventory Management absorbs the largest implementation budgets; Consumer Behavior Tracking climbs the fastest.
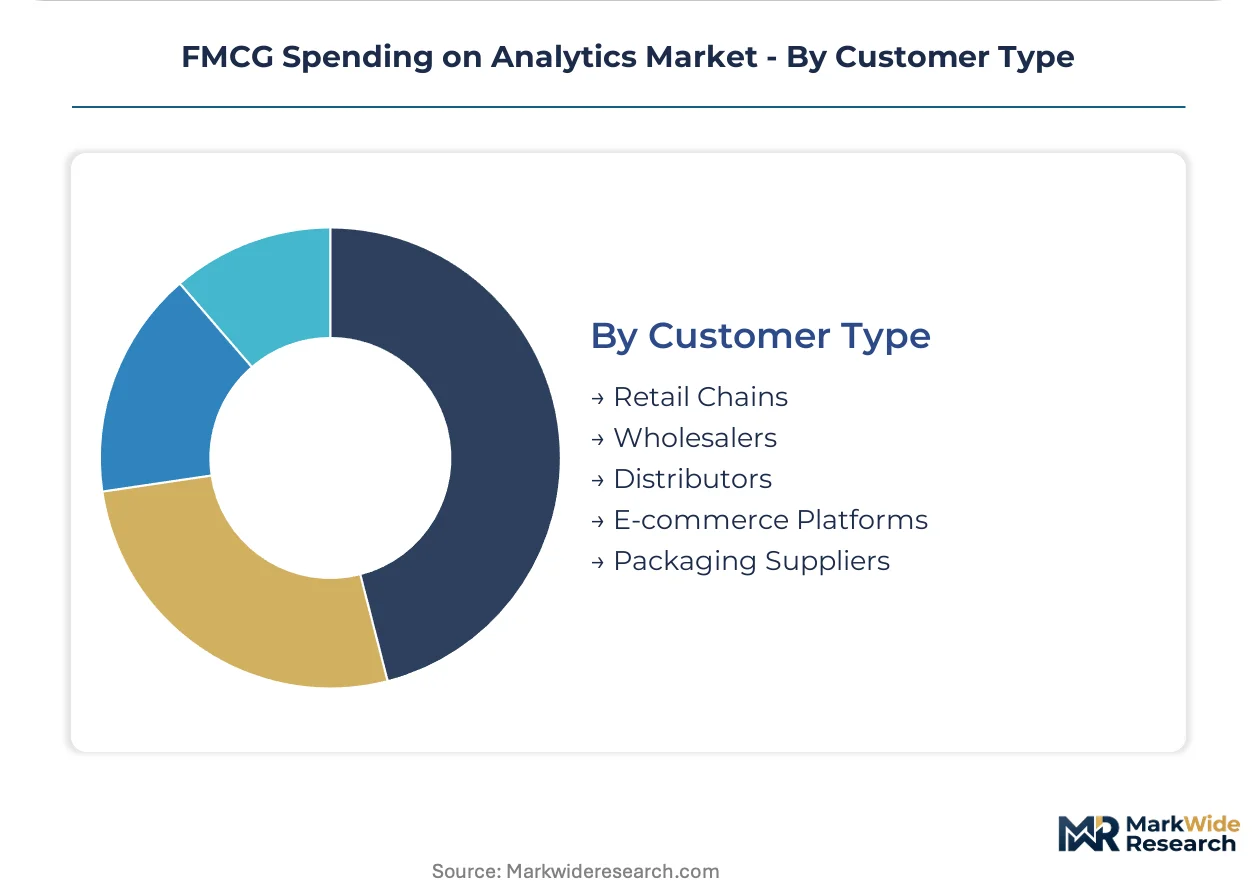
Customer Type:
Channel power and data sophistication create divergent analytics requirements.
- Retail Chains:Category management analytics support private label competition and shelf-space negotiations.
- Wholesalers:Demand aggregation platforms balance inventory across fragmented downstream accounts.
- Distributors:Route optimization and load planning tools reduce last-mile delivery costs.
- E-commerce Platforms:Clickstream analysis and recommendation engines drive conversion optimization.
- Packaging Suppliers:Quality-control analytics integrate into manufacturing execution systems to meet BIS certification requirements in India.
Retail Chains deploy at greatest scale; E-commerce Platforms gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern FMCG analytics industry traces its commercial origins to post-war consumer research bureaus in the United States, where Nielsen and IRI pioneered scanner data analysis for CPG manufacturers during the 1980s. These methodologies diffused to European headquarters operations by the 1990s, then accelerated through cloud infrastructure adoption in the 2010s.
United States
American beverage and packaged food manufacturers anchor cloud-based analytics deployment, with PepsiCo extending demand-sensing platforms to regional bottling partners. FDA food traceability rules under the Food Safety Modernization Act compel lot-level tracking investments from ingredient source to retail shelf. Chicago and Bentonville serve as analytics talent clusters, where CPG headquarters compete for data science expertise against retail technology centers.
Germany
German manufacturers prioritize on-premise deployment architectures to satisfy GDPR data localization requirements in competitive intelligence applications. REACH chemical disclosure mandates force continuous reformulation analytics that model substitution impacts on household cleaning and cosmetics formulations. The Rhine-Ruhr industrial corridor concentrates quality-control analytics integration into manufacturing execution systems for export-oriented producers.
India
Indian FMCG enterprises leverage the PLI scheme to reward quality-control analytics integration into manufacturing execution systems for packaged goods. BIS certification mandates drive edge computing deployment at plant floors across Maharashtra and Gujarat. Bangalore and Hyderabad host cloud analytics development centers serving both domestic brands and multinational regional operations.
United Kingdom
British grocery retailers lead sustainability scorecard implementation, replacing price-only procurement with multi-criteria supplier evaluation frameworks. CSRD disclosure requirements accelerate carbon footprint verification analytics across manufacturer supply chains. London concentrates customer insights platform development as brands rebuild first-party data capabilities following cookie deprecation.
Brazil
Brazilian consumer goods manufacturers deploy demand forecasting at SKU-location-day granularity to manage volatility across fragmented retail channels. ANVISA pharmaceutical and food safety regulations shape traceability analytics investments for multinational subsidiaries operating in São Paulo state. The São Paulo metropolitan area anchors Latin American analytics service delivery for regional CPG headquarters.
FMCG Spending on Analytics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment sophistication, with cloud-native specialists commanding valuation multiples above legacy systems integrators. The vendor landscape organizes into three tiers: multinational technology platforms, regional implementation specialists, and vertical-specific SaaS providers. Consolidation pressure concentrates among mid-scale analytics consultancies as enterprise buyers prefer end-to-end capability bundles. Dominant competitive moves include strategic partnerships between cloud hyperscalers and CPG-focused software vendors, plus geographic expansion through acquired delivery centers in India and Eastern Europe.
Within the multinational CPG archetype, Nestlé, Unilever, and PepsiCo exemplify divergent analytics strategies. Nestlé anchors integrated demand-sensing platforms across European manufacturing networks. Unilever occupies a position defined by proprietary pricing analytics responding to commodity volatility. PepsiCo sits within the cloud-deployment vanguard among North American beverage manufacturers, extending headquarters analytics access to regional bottling partners.
| Leading Market Players |
|---|
| PepsiCo |
| Johnson and Johnson |
| Nestlé |
| Dabur India |
| Anheuser Busch InBev |
| Procter & Gamble |
| Coca-Cola Company |
| ITC Limited |
| Unilever |
| Others |
Supply & Pricing Matrix
EU Green Deal compliance timelines now gate both qualified supplier status and premium-tier pricing access for analytics vendors serving European FMCG procurement teams. Manufacturers lacking carbon footprint verification capabilities face exclusion from retailer sustainability scorecards, compressing their addressable market to price-sensitive commodity tiers while certified providers command implementation premiums.
Pricing Analysis
Subscription-based SaaS tiers with volume-scaled per-user licensing dominate contract structures across cloud deployment models. Price differentiation rests on data sovereignty certifications and real-time processing latency guarantees, with GDPR-compliant German installations commanding 15-25% premiums over standard cloud configurations. Cost compression in mid-market SaaS offerings intensifies as hyperscaler marketplaces commoditize baseline demand forecasting modules. Small beverage bottlers exhibit highest price sensitivity, while multinational headquarters prioritize total cost of ownership over per-seat licensing.
Supply Chain Analysis
Data engineering talent scarcity in Bangalore and Hyderabad constrains analytics platform delivery capacity for Asia-Pacific rollouts. Supply concentration centers on the United States for cloud infrastructure, Germany for on-premise competitive intelligence systems, and India for quality-control edge computing hardware. Component dependencies span NVIDIA GPU clusters, proprietary demand-sensing algorithms, and regulatory compliance databases. Single-source vulnerability in specialized ML operations talent inflates implementation timelines. Distribution runs through direct enterprise sales for headquarters deployments and hyperscaler marketplaces for mid-market SaaS access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FMCG analytics spending behaves as a stable compounder, with regulatory compliance mandates creating irreversible infrastructure commitments that renew and expand across economic cycles.
For Market Incumbents: Anticipate margin compression from cloud hyperscalers packaging baseline forecasting tools into retail partnerships. Defend position by deepening proprietary pricing analytics capabilities that respond to commodity volatility faster than standardized platforms. Prioritize certification investments for EU Green Deal and FDA traceability compliance to maintain retailer scorecard eligibility. For New Entrants and Emerging Players: The mid-market pricing gap between premium integrated suites and basic reporting tools offers white-space for specialized supply chain optimization modules targeting Indian PLI scheme beneficiaries. Focus initial deployment on Maharashtra and Gujarat manufacturing clusters where BIS certification mandates create urgent quality-control analytics demand. Pursue channel partnerships with legacy ERP systems integrators to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific SaaS providers because retailer data-sharing requirements fragment procurement decisions across dozens of mid-scale analytics consultancies. Five-to-ten-year viability hinges on cloud-native architecture migration completion. Target acquisition profiles emphasize customer insights platforms with first-party data activation capabilities post-cookie deprecation. Monitor FDA enforcement discretion on Food Safety Modernization Act traceability deadlines as inflection indicator for compliance-driven spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Analytics Infrastructure Deployment | Reduces replenishment latency for PepsiCo's regional bottling partners from days to hours. |
| First-Party Data Platform Launch | Replaces deprecated cookie targeting with direct consumer relationship management for Indian e-commerce integrations. |
| Regulatory Compliance Certification | Unlocks EU Green Deal procurement eligibility for Nestlé's European manufacturing network suppliers. |
| Strategic Partnership with Hyperscaler | Extends Unilever's proprietary pricing analytics to cloud marketplaces serving mid-market CPG entrants. |
| Geographic Expansion to Emerging Markets | Captures PLI scheme-aligned quality-control analytics demand across Maharashtra and Gujarat plant floors. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down vendor contract tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at retail chains, supply planning directors, and cloud procurement officers generated demand-side intelligence. Secondary validation drew from Nielsen retail audit data, hyperscaler capex disclosures, FDA enforcement documentation, EU Green Deal implementation guidance, and customs records of analytics software imports. Triangulation across these sources established spending estimates by deployment model and solution type.
Input-output matrices mapped analytics investment to operational outcomes across SKU-location-day forecasting granularity, promotional elasticity measurement, and automated replenishment trigger deployment. Segmentation dimensions modeled include deployment architecture, solution specialization, use case priority, and customer procurement maturity. CAGRs emerged from curve-fitting observed contract values against projected compliance deadline acceleration and cloud adoption S-curves. Industry-specific forecast inputs incorporated retailer sustainability scorecard rollout timelines and REACH chemical disclosure amendment schedules.
Caveats apply where FDA enforcement discretion on traceability deadlines or EU Green Deal implementation pacing could materially shift the outlook. Forecasts reflect assumptions about cloud migration continuity and data talent availability in key development clusters. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Telecom Analytics Market
Analytics
Supply Chain Analytics Market
Analytics
Global Big Data Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Global Development Analytics Tools Market
Analytics
Cyprus ICT Market
Analytics
Europe Big Data and Business Analytics Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Voice Analytics Market
Analytics
Patent Analytics Services Market
Analytics
Manufacturing Analytics Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
UK Video Analytics Market
Analytics
Marketing Mix Optimization Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Customer Identity Graph Drift Monitoring Market