
 High Definition (HD) Maps Market | 2026-2036
High Definition (HD) Maps Market Size, Share, and Industry Trends Forecast 2026-2036
High Definition (HD) Maps Market Foresight
A shortage of geospatial engineers with sensor fusion expertise is unwinding the pace at which HD map layers can be validated for production deployment. HERE Technologies leverages its decades of automotive OEM relationships to sustain long-term mapping contracts. TomTom anchors European coverage density through owned survey fleets and crowd-sourced correction layers. NVIDIA Corporation dominates the silicon-mapping software boundary with platforms that fuse GPU compute with vector tile pipelines.
High Definition Maps are georeferenced digital representations containing centimeter-level accuracy for road geometry, lane markings, traffic signs, and elevation data, constructed through lidar point clouds, camera triangulation, and GNSS-IMU trajectories to enable machine-readable navigation for autonomous systems. Static Maps still occupy the largest revenue share due to legacy automotive integration cycles, though Real-Time Updates are recording the fastest expansion as edge computing and V2X networks reduce latency between road change and map refresh. Within End User segments, Autonomous Vehicles command the deepest per-vehicle map spend, while Fleet Management spreads subscription revenue across lighter accuracy tiers.
The EU AI Act, the US DOT's AV guidance through NHTSA, and China's MIIT mapping资质 requirements collectively restrict cross-border data flows and mandate sovereign storage for raw survey data. These frameworks force providers to duplicate infrastructure or partner with licensed domestic entities, raising capital intensity for geographic expansion. Stakeholders must weigh the cost of regulatory compliance against the revenue premium of operating in jurisdictions with the strictest autonomous vehicle certification standards.
Market Dynamics
Autonomous vehicle fleets are compressing map refresh cycles from quarterly to real-time, forcing providers to restructure data pipelines around edge computing architectures and V2X network integration.
Growth Catalysts
- EU AI Act compliance mandates:Vehicle-type approval frameworks now require traceable data governance for navigation inputs, pushing OEMs toward certified HD map suppliers with sovereign infrastructure.
- Sensor fusion densification:Lidar-camera-GNSS-IMU integration is lowering per-kilometer survey costs, expanding economically viable coverage to secondary road networks previously excluded from commercial mapping.
- German automotive clustering:OEMs and tier-one suppliers co-locating R&D with manufacturing in Baden-Württemberg and Bavaria are creating concentrated demand pools that justify dedicated survey fleet deployment.
Market Restraints
- Geospatial engineer scarcity:Validation pipelines for production-grade HD layers require specialized sensor fusion expertise that universities and vocational programs have not scaled to match fleet expansion timelines.
- Cross-border data fragmentation:China's MIIT mapping资质 requirements and the EU AI Act's sovereign storage clauses force providers to duplicate cloud infrastructure rather than leverage centralized global assets.
- Static map legacy lock-in:Automotive integration cycles spanning 4-7 years delay real-time update adoption, constraining revenue migration toward higher-margin dynamic subscription tiers.
Strategic Opportunities
- India's PLI scheme alignment:Automotive component manufacturing incentives are attracting tier-one suppliers who will require localized HD map layers for autonomous testing and eventual deployment.
- Fleet management vertical expansion:Logistics operators managing heavy trucks and last-mile delivery vans represent underpenetrated demand for lighter-accuracy map subscriptions at volume price points.
- V2X-edge convergence:Roadside unit deployments by infrastructure operators create partnership channels for map providers to embed correction layers directly into municipal traffic management systems.
Industry Challenges
- Production validation bottlenecks:Centimeter-level accuracy requirements demand manual review of edge cases in lidar point clouds, creating throughput ceilings that automation has not yet eliminated.
- Multi-jurisdiction certification complexity:Providers seeking vehicle-type approval across Germany's KBA, the US DOT through NHTSA, and Japan's METI face non-harmonized test protocols that extend time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Definition (HD) Maps Market |
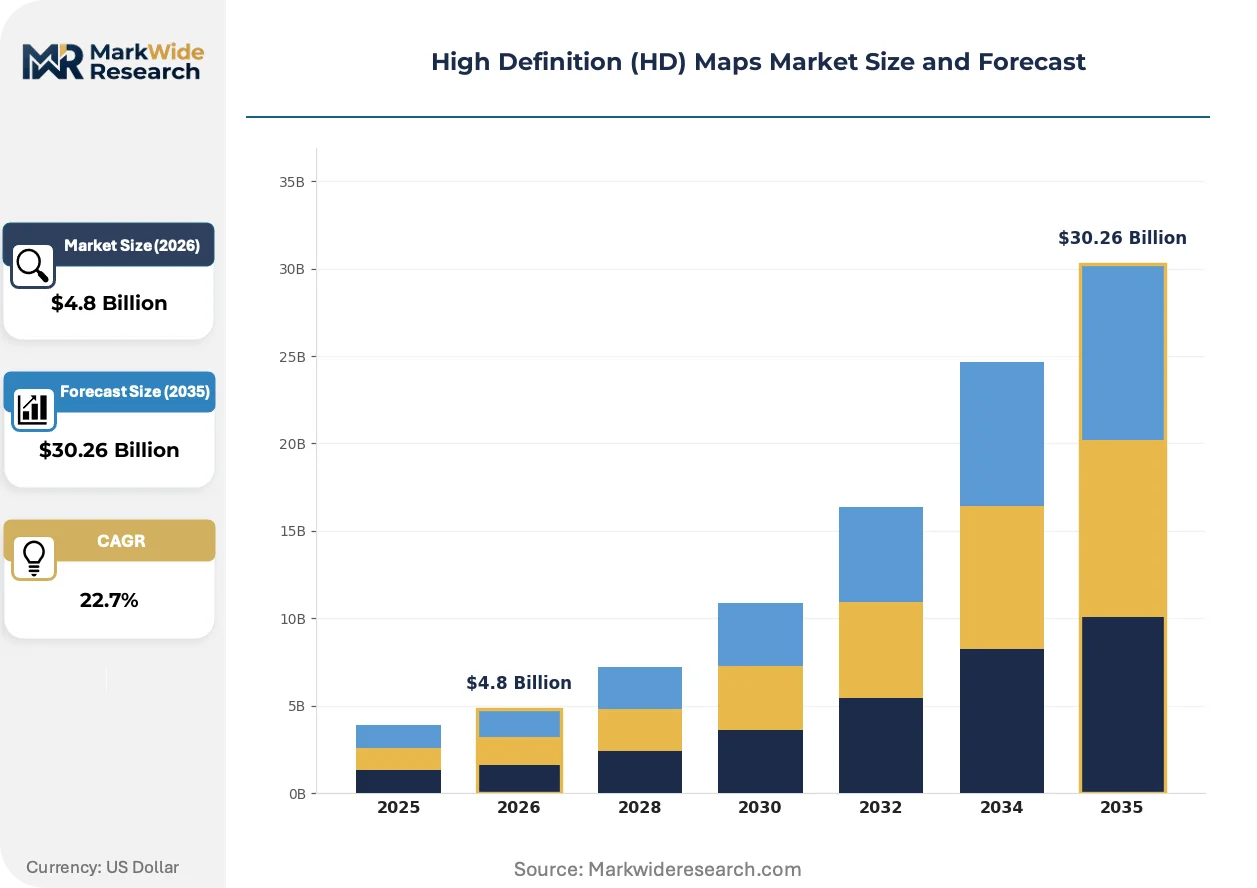
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Maps, Dynamic Maps, Real-Time Updates, 3D Visualization End User: Autonomous Vehicles, Fleet Management, Navigation Systems, Mobile Applications Technology: Lidar, Computer Vision, Sensor Fusion, Mapping Software Application: Urban Planning, Road Safety, Aerial Surveying, Smart City Solutions |
| Companies Covered | HERE Technologies, TomTom, Baidu, NVIDIA Corporation, Mobileye, NavInfo, Dynamic Map Platform, Waymo, Mapbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Definition (HD) Maps Market Shifts & Advancements
Vector tile streaming architectures are displacing monolithic map databases, enabling differential updates that reduce bandwidth consumption and extend viable deployment to bandwidth-constrained edge devices.
Neural radiance fields (NeRFs) derived from survey imagery are decomposing the traditional separation between static base maps and dynamic object layers, allowing autonomous systems to infer road geometry from sparse observations rather than dense pre-mapping. Robotaxi operators in California and Arizona are piloting NeRF-based localization that reduces dependency on pre-surveyed lidar point clouds. This compression of the mapping-collect-localize pipeline is threatening incumbent business models built on proprietary survey fleet ownership.
The EU AI Act's risk-classification framework for autonomous vehicle components is mandating algorithmic transparency and training data documentation that map providers must embed into their quality management systems. German regulators through KBA are requiring evidence of map freshness provenance for Level 3+ system approvals. Providers are responding by restructuring data lineage systems to generate audit trails that satisfy both Brussels framework requirements and national type-approval bodies.
Fleet procurement departments are consolidating vendor relationships around map providers who bundle navigation data with simulation environments for autonomous validation. Automotive OEMs in Stuttgart and Munich are negotiating enterprise licenses that cover both production vehicle map feeds and virtual testing grounds. This bundling pattern is most pronounced in Germany, where integrated toolchains reduce procurement overhead and align with consolidated supplier management practices.
High Definition (HD) Maps Market Segmentation
HD map procurement patterns diverge sharply across accuracy tiers, refresh frequencies, and integration depths. Understanding where margin pools concentrate within each dimension enables providers to align R&D spend with the highest-value deployment scenarios.
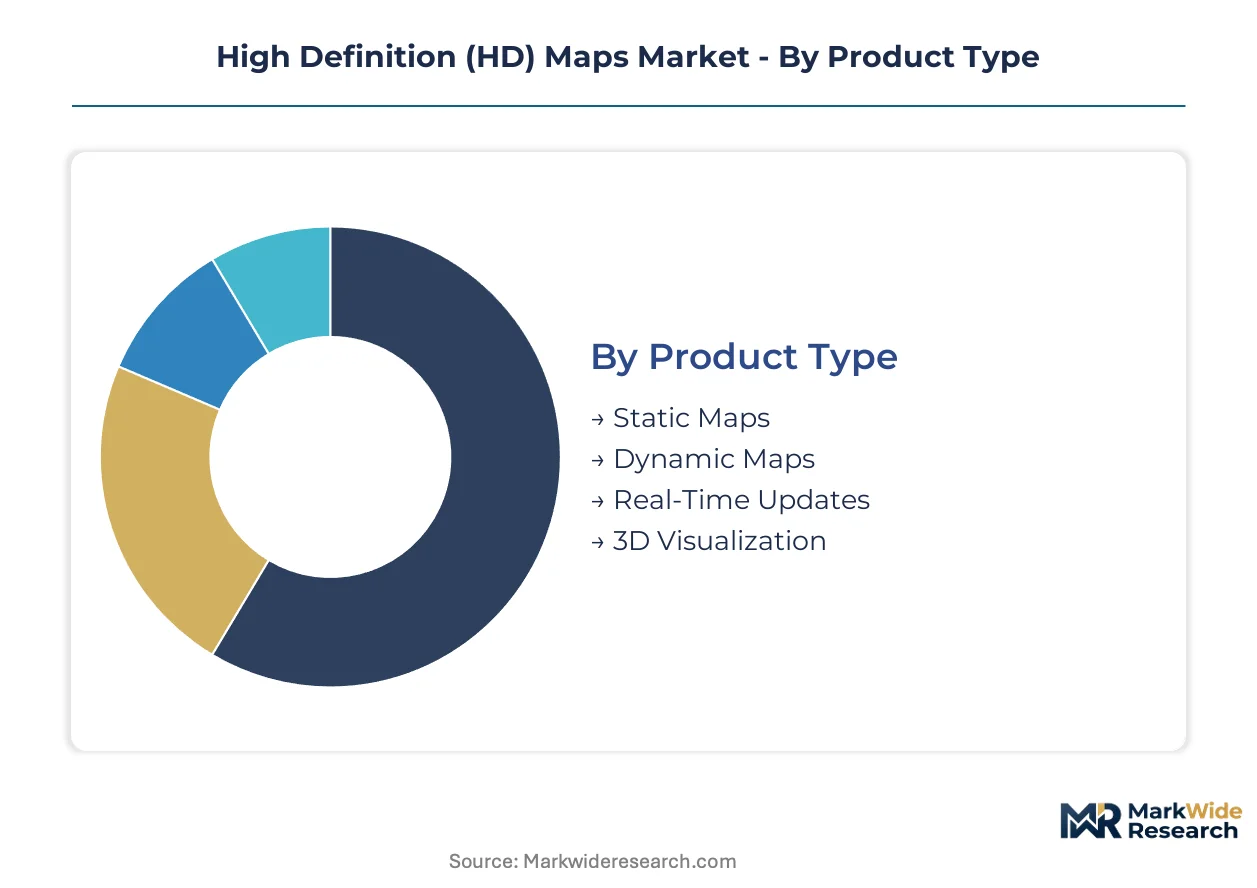
Product Type:
Margin pools concentrate in subscription-based refresh models rather than perpetual licenses for static base layers.
- Static Maps:Centimeter-accurate base layers derived from lidar point clouds and camera triangulation, delivered as one-time data packages. German automotive OEMs in Stuttgart and Munich still anchor procurement volume here due to legacy integration cycles spanning 4-7 years, though pricing pressure intensifies as commoditization spreads.
- Real-Time Updates:Differential vector tile streams pushed through V2X networks and edge computing nodes, enabling sub-second latency between road change and vehicle notification. California robotaxi operators and Arizona test fleets are compressing refresh cycles from quarterly to continuous, creating the steepest expansion trajectory across all product tiers.
- Dynamic Maps:Hybrid architectures combining static base geometry with periodic refresh layers for construction zones and temporary traffic control.
- 3D Visualization:Mesh and texture outputs for simulation environments and human-machine interface rendering.
Static Maps holds installed capacity. Real-Time Updates is rotating up the share rankings.
End User:
Per-vehicle spend varies by an order of magnitude depending on automation level and liability exposure.
- Autonomous Vehicles:Level 4-5 systems require full-stack HD layers with lane-level geometry, traffic sign semantics, and elevation profiles for path planning. Waymo and Cruise procurement teams in California negotiate enterprise licenses covering both production feeds and simulation environments, commanding the deepest per-unit map investment of any end-use segment.
- Fleet Management:Logistics operators managing heavy trucks across German autobahn corridors and last-mile delivery vans in dense urban cores purchase lighter-accuracy subscriptions at volume price points. DHL and DB Schenker procurement departments spread costs across asset bases exceeding 10,000 vehicles, prioritizing route optimization over centimeter localization.
- Navigation Systems:Tier-one automotive suppliers integrating HD layers into production vehicle infotainment stacks.
- Mobile Applications:Consumer-facing mapping services with degraded accuracy requirements for augmented reality and location-based services.
Autonomous Vehicles captures the premium tier. Fleet Management is climbing the fastest in absolute revenue contribution.
Technology:
Cost structures bifurcate between capital-intensive survey hardware and software-only licensing plays.
- Sensor Fusion:Integration pipelines combining lidar point clouds, camera imagery, GNSS-IMU trajectories, and radar returns into unified georeferenced outputs. HERE Technologies and TomTom engineering teams in Germany concentrate validation expertise here, as production-grade accuracy demands manual review of edge cases that automation has not yet eliminated.
- Lidar:Active ranging systems generating dense 3D point clouds for road geometry extraction. Survey fleet operators face per-kilometer costs that sensor fusion densification is now compressing, expanding economically viable coverage to secondary road networks previously excluded from commercial mapping.
- Computer Vision:Convolutional neural networks extracting lane markings, traffic signs, and road surface features from camera imagery.
- Mapping Software:Vector tile pipelines, differential update engines, and quality management systems for data lineage.
Sensor Fusion anchors the value chain. Computer Vision is gaining share fastest as neural radiance fields reduce dependency on pre-surveyed point clouds.
Application:
Public-sector procurement cycles and private fleet deployment timelines create divergent revenue recognition patterns.
- Road Safety:HD layers enabling predictive hazard notification, curve speed advisory, and intersection collision avoidance. Germany's KBA mandates map freshness provenance for Level 3+ system approvals, concentrating regulatory-driven demand in Baden-Württemberg and Bavaria where automotive OEMs co-locate R&D with manufacturing.
- Smart City Solutions:Municipal traffic management systems integrating HD maps with roadside unit deployments for V2X-edge convergence. Singapore and Dubai infrastructure operators are embedding correction layers directly into urban traffic control centers, creating partnership channels that bypass traditional automotive sales cycles.
- Urban Planning:Static base layers for zoning analysis, construction permitting, and infrastructure investment prioritization.
- Aerial Surveying:Dracquired photogrammetry and lidar for corridor mapping and change detection.
Road Safety holds regulatory-mandated demand. Smart City Solutions is expanding most quickly as infrastructure operators bypass automotive procurement bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA in Germany anchors the most stringent vehicle-type approval framework for HD map freshness provenance, concentrating regulatory-driven procurement across Baden-Württemberg and Bavaria where automotive OEMs co-locate R&D with manufacturing clusters.
Germany
Level 3+ system approvals through KBA mandate traceable data governance for navigation inputs, pushing OEMs toward certified suppliers with sovereign infrastructure. The EU AI Act's risk-classification framework requires algorithmic transparency and training data documentation embedded into quality management systems. Stuttgart and Munich procurement teams negotiate enterprise licenses bundling production vehicle map feeds with simulation environments for autonomous validation.
United States
Robotaxi operators in California and Arizona are compressing map refresh cycles from quarterly to continuous, creating the steepest expansion trajectory across all product tiers. NHTSA's AV guidance through the US DOT restricts cross-border data flows and mandates documentation protocols for autonomous system navigation inputs. Waymo and Cruise procurement teams in the San Francisco Bay Area command the deepest per-unit map investment of any end-use segment.
China
MIIT mapping资质 requirements force providers to duplicate infrastructure or partner with licensed domestic entities, raising capital intensity for geographic expansion. Sovereign storage clauses mandate that raw survey data remain within national borders, preventing centralized global asset deployment. Baidu and NavInfo anchor domestic coverage through owned survey fleets and crowd-sourced correction layers.
Japan
METI standards harmonization efforts face non-aligned test protocols with Germany's KBA and the US DOT, extending time-to-revenue for providers seeking multi-jurisdiction certification. Dynamic Map Platform concentrates validation expertise for sensor fusion pipelines combining lidar point clouds with camera imagery. Tokyo and Nagoya automotive clusters prioritize route optimization over centimeter localization for fleet management applications.
India
PLI scheme alignment for automotive component manufacturing is attracting tier-one suppliers who will require localized HD map layers for autonomous testing and eventual deployment. The country's national automotive regulator is developing framework conditions for navigation input certification that mirror EU AI Act transparency requirements. Maharashtra and Gujarat manufacturing corridors are emerging as concentrated demand pools for lighter-accuracy map subscriptions at volume price points.
High Definition (HD) Maps Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across sensor hardware, mapping software, and data validation services. The upper tier commands long-term automotive OEM relationships and sovereign infrastructure investments that satisfy EU AI Act compliance mandates. Three archetypes dominate: survey fleet operators with owned data acquisition assets, silicon-mapping software integrators fusing GPU compute with vector tile pipelines, and cloud-native platforms streaming differential updates through edge computing architectures. Competitive moves concentrate on strategic partnerships with roadside unit deployers and portfolio diversification into simulation environment bundling.
Within the integrated mapping services tier, HERE Technologies and TomTom exemplify European-headquartered operators leveraging decades of automotive OEM relationships to sustain long-term contracts. NVIDIA Corporation occupies a position at the silicon-mapping software boundary, anchoring the GPU compute layer that enables real-time vector tile processing. These three entities represent distinct competitive positions: legacy survey infrastructure ownership, crowd-sourced correction layer density, and hardware-software integration control.
| Leading Market Players |
|---|
| HERE Technologies |
| TomTom |
| Baidu |
| NVIDIA Corporation |
| Mobileye |
| NavInfo |
| Dynamic Map Platform |
| Waymo |
| Mapbox |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German automotive OEMs and certified HD map providers lock in sovereign infrastructure access while anchoring price visibility across multi-year vehicle platform cycles. These arrangements bundle static base layers with real-time update subscriptions, insulating procurement teams from spot market volatility in geospatial engineering talent.
Pricing Analysis
Long-term offtake structures dominate HD map procurement, with subscription-based refresh models commanding premium pricing over perpetual static licenses. Price differentiation rests on certification grade under KBA and EU AI Act frameworks, with volume scale discounts spreading across fleet management deployments. Pricing pressure stems from NeRF-based localization pilots reducing dependency on pre-surveyed point clouds. Fleet management operators exhibit highest price sensitivity, while Level 4-5 autonomous vehicle programs absorb deepest per-unit investment.
Supply Chain Analysis
Geospatial engineer scarcity in Germany and the United States chokes validation throughput for production-grade HD layers. Survey fleet operations draw from lidar sensor manufacturing concentrated in China, South Korea, and the United States, with GNSS-IMU component supply anchored in European and Japanese precision electronics clusters. Single-source vulnerability runs through specialized sensor fusion expertise that universities have not scaled to match fleet expansion timelines. Distribution feeds through direct enterprise licensing to automotive OEM procurement teams and tier-one supplier integration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HD maps market rewards providers who control scarce sensor fusion validation pipelines and sovereign data infrastructure, while penalizing those dependent on commoditized static base layers. Geospatial engineering talent gaps and regulatory certification bottlenecks create durable moats for incumbents with established OEM relationships.
For Market Incumbents: Consolidate validation pipeline capacity through targeted hiring in Baden-Württemberg and Bavaria engineering clusters, while extending sovereign cloud footprints to satisfy EU AI Act data residency mandates. NeRF-based localization threatens proprietary survey fleet economics, making backward integration into simulation environment bundling essential for defending subscription revenue tiers. For New Entrants and Emerging Players: Anchor in India's PLI-aligned automotive corridors, where tier-one supplier localization creates demand for lighter-accuracy map subscriptions at volume price points. Fleet management verticals remain underpenetrated relative to autonomous vehicle premiums, with V2X-edge convergence partnerships offering bypass channels around entrenched OEM procurement relationships. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platforms with differential update architectures and established regulatory certification across multiple jurisdictions. Long-term viability across the next decade hinges on controlling edge computing integration points rather than owning depreciating survey hardware. Watch for inflection signals in KBA approval timelines for Level 3+ systems, as acceleration or delay directly translates to revenue recognition patterns for certified providers.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Talent Acquisition | HERE Technologies and TomTom engineering teams in Germany concentrate scarce validation expertise for production-grade accuracy. |
| Sovereign Infrastructure Expansion | EU AI Act compliance mandates push providers toward duplicating cloud assets rather than leveraging centralized global deployments. |
| Simulation Environment Bundling | Stuttgart and Munich OEM procurement teams negotiate enterprise licenses covering both production feeds and virtual testing grounds. |
| V2X-Edge Partnership Channels | Singapore and Dubai infrastructure operators embed correction layers directly into municipal traffic management systems. |
| NeRF-Based Localization R&D | California robotaxi pilots threaten incumbent business models built on proprietary survey fleet ownership. |
Research Methodology
Desk research of automotive regulatory filings, vehicle-type approval databases, and hyperscaler edge computing disclosures preceded structured interviews with OEM platform engineers, tier-one supplier procurement leads, geospatial engineering directors, and fleet management operations heads. Secondary validation drew from KBA approval registries, NHTSA AV guidance documentation, MIIT mapping资质 announcements, and EU AI Act implementation guidelines. Bottom-up segment sizing triangulated against top-down market envelope checks.
Variance decomposition across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate synthesis, with autonomous vehicle fleet expansion curves and V2X network deployment timelines as primary industry-specific inputs. Modeling incorporated differential update adoption trajectories and static map legacy lock-in effects.
Material uncertainties — regulatory harmonization delays, geospatial engineer supply elasticity, and NeRF localization technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and sovereign data infrastructure investment continuity. Practitioners should keep alternative scenarios live as KBA approval velocity and EU AI Act enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Geomarketing Market