
 France Geospatial Imagery Analytics Market | 2026-2036
France Geospatial Imagery Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
France Geospatial Imagery Analytics Market Insights
Modular platform unbundling is decoupling satellite imagery acquisition from analytics processing, letting buyers mix data sources with specialized software layers. Esri leverages its ArcGIS ecosystem to anchor enterprise accounts across French utility networks. Hexagon AB competes through deep positioning in defense-grade geospatial intelligence. Airbus Defence and Space extends its native satellite constellation advantage into downstream analytics services for European government buyers.
France Geospatial Imagery Analytics encompasses the extraction of location-based intelligence from aerial and satellite imagery through spectral analysis, orthorectification, and machine learning classification to support decision-making in land-use, infrastructure, and environmental management. Remote sensing dominates technology uptake as Sentinel constellation access normalizes free high-resolution data inputs, while photogrammetry retains stronghold status in cadastral surveying where centimeter-grade accuracy remains mandatory. Application demand skews toward environmental monitoring, where drought tracking and rewilding compliance create recurring revenue streams, and urban planning, where ZAC development mandates feed continuous mapping refresh cycles. Government end users control the largest procurement budgets, though private sector adoption accelerates in logistics and insurance verticals.
France's national mapping agency IGN operates under EU INSPIRE directives that standardize geospatial data interoperability across member states, while CNIL enforces GDPR constraints on automated image recognition processing personal location data. The EU AI Act adds algorithmic transparency requirements for predictive geospatial models used in public administration. Stakeholders must monitor how forthcoming CSRD disclosure rules expand corporate demand for geospatial environmental footprint verification.
Market Dynamics
Modular platform unbundling is decoupling satellite imagery acquisition from analytics processing, letting buyers mix data sources with specialized software layers. This structural shift is reshaping how French agricultural cooperatives, defense agencies, and urban planners procure geospatial intelligence.
Growth Catalysts
- EU AI Act compliance mandates:CNIL guidance on algorithmic transparency for predictive geospatial models is forcing public administration buyers to upgrade legacy systems, creating recurring demand for compliant analytics platforms.
- Sentinel constellation normalization:Free high-resolution Copernicus data inputs are eliminating raw imagery cost barriers for Occitanie vineyard monitoring and nationwide drought tracking applications.
- CSRD disclosure expansion:Corporate sustainability reporting requirements are driving demand for geospatial environmental footprint verification across French logistics and insurance verticals.
Market Restraints
- GDPR location data constraints:CNIL enforcement on automated image recognition processing personal location data creates compliance friction for urban surveillance and mobility analytics deployments.
- Photogrammetry equipment concentration:Centimeter-grade cadastral surveying hardware supply concentrates among German and Swiss precision optics manufacturers, exposing French surveyors to import dependency.
- Spectral analysis skill scarcity:Machine learning classification expertise for hyperspectral imagery interpretation remains concentrated within aerospace engineering programs in Toulouse and Paris-Saclay clusters.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur rewilding compliance:EU Green Deal biodiversity mandates are creating recurring revenue streams for ecosystem monitoring subscriptions in Mediterranean conservation zones.
- Edge computing convergence:Onboard satellite processing combined with 5G terrestrial networks is enabling real-time analytics for disaster response coordination in flood-prone Atlantic coastal departments.
- Utility network digital twin integration:ZAC development mandates are feeding continuous mapping refresh cycles that link geospatial basemaps to infrastructure asset management platforms.
Industry Challenges
- Orthorectification certification timelines:IGN accuracy standards for national mapping products require extended validation periods that compress vendor delivery windows.
- Interoperability fragmentation:EU INSPIRE directive implementation varies across French regional planning authorities, forcing analytics providers to maintain multiple data format pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Geospatial Imagery Analytics Market |
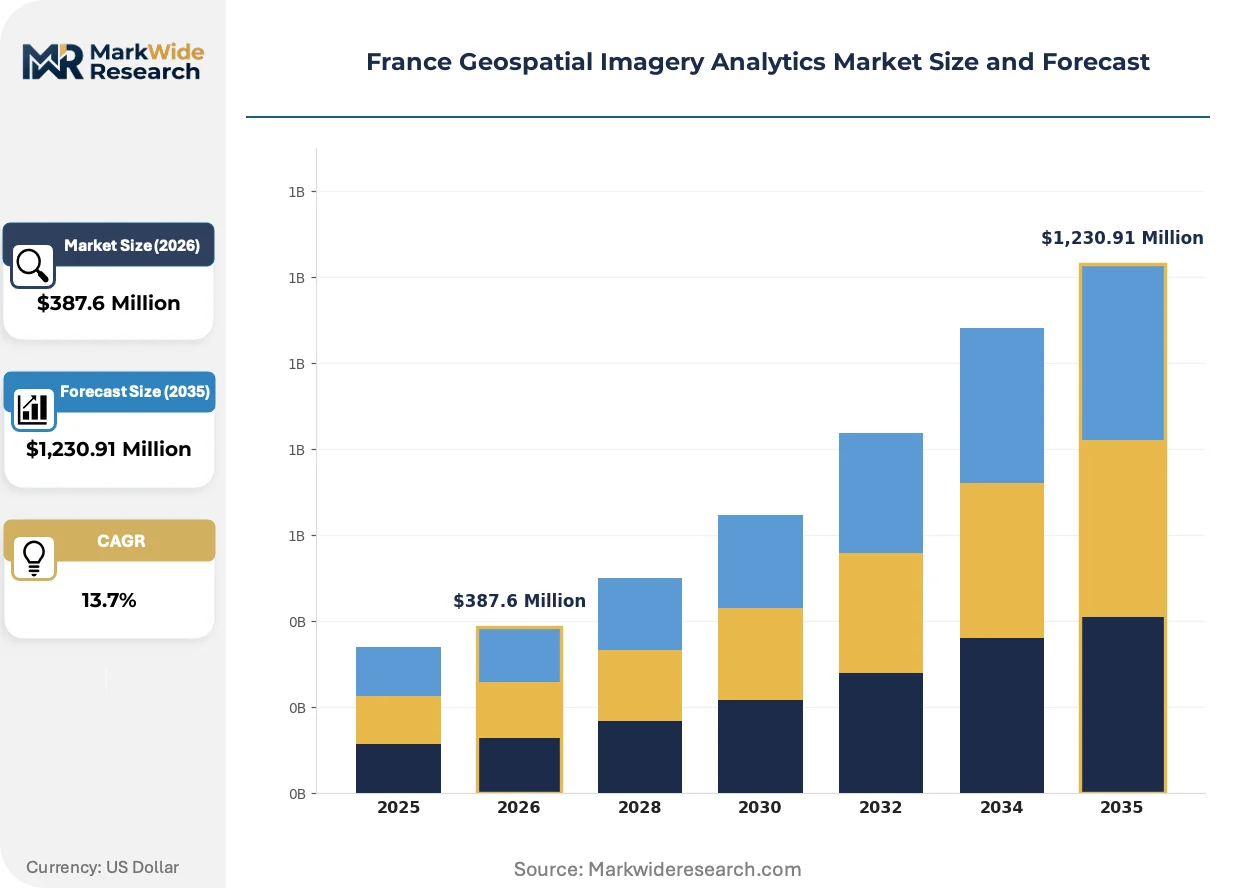
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,230.91 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Remote Sensing, Photogrammetry, GIS, GPS Application: Agriculture, Urban Planning, Environmental Monitoring, Disaster Management End User: Government, NGOs, Research Institutes, Private Sector Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Esri, Hexagon AB, Google LLC, Microsoft Corporation, Airbus Defence and Space, IGN, Trimble Inc., Oracle Corporation, L3Harris Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Geospatial Imagery Analytics Market Trends and Innovations
Synthetic aperture radar integration with optical multispectral stacks is electrifying all-weather monitoring capabilities for precision agriculture and infrastructure surveillance. French buyers are demanding fused data products that eliminate seasonal acquisition gaps.
Synthetic aperture radar integration with optical multispectral stacks is electrifying all-weather monitoring capabilities for precision agriculture and infrastructure surveillance. Agricultural cooperatives in Occitanie are adopting SAR-optical fusion at accelerated procurement cycles. This technology convergence is compressing the competitive advantage of pure-play optical providers while elevating vendors with multi-sensor processing architectures.
CNIL's algorithmic transparency enforcement under France's EU AI Act implementation is mandating explainable AI documentation for public-sector geospatial models. Predictive land-use classification tools must now provide decision audit trails. Defense and environmental monitoring agencies are responding by embedding interpretability layers into procurement specifications, favoring vendors with native model documentation capabilities.
Subscription-based analytics licensing is displacing perpetual software ownership across French utility networks and regional planning authorities. Esri's ArcGIS ecosystem anchors enterprise accounts through consumption-based pricing that bundles data refreshes with processing tools. This shift is most visible in Île-de-France, where Grand Paris infrastructure coordination demands continuous basemap updates rather than static annual purchases.
France Geospatial Imagery Analytics Market Segmentation
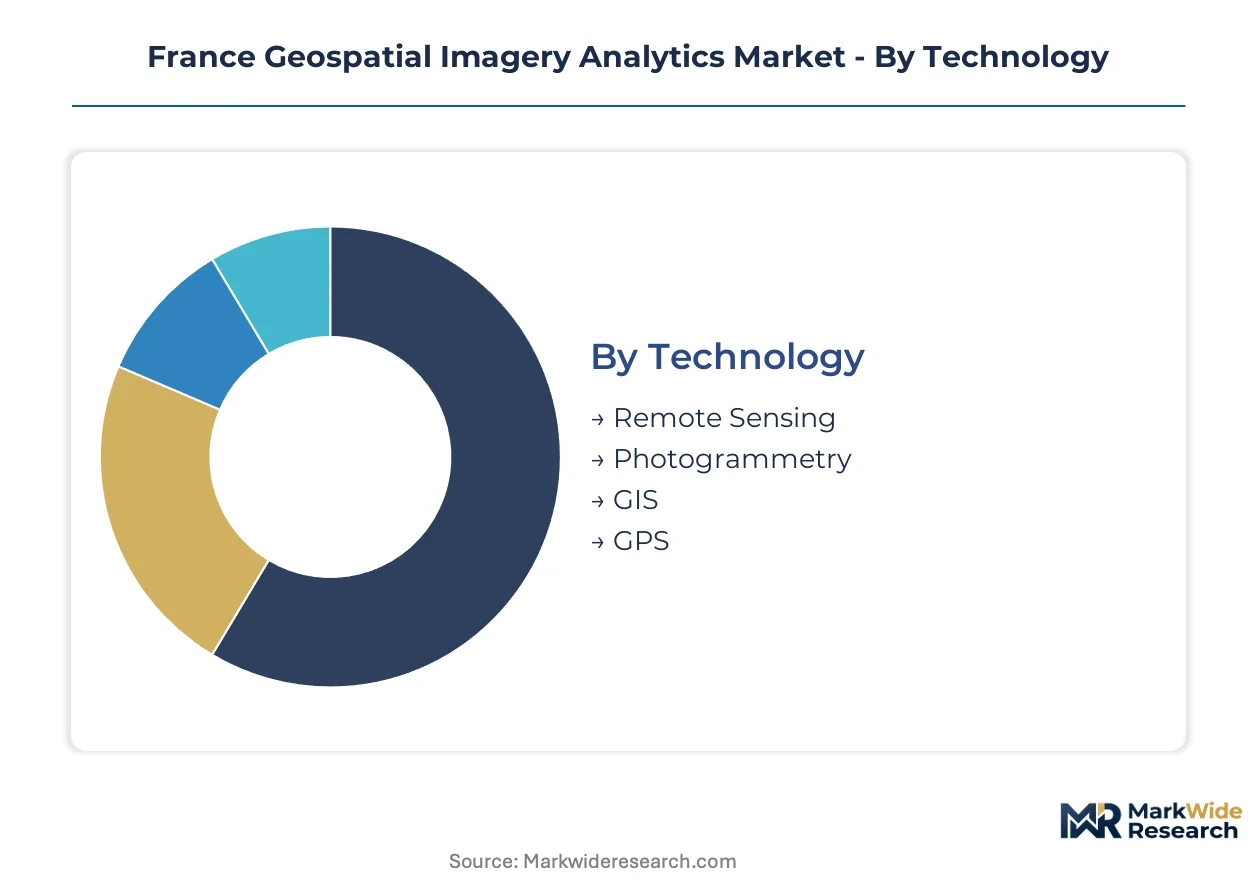
Technology architecture determines procurement patterns across French geospatial buyers. Spectral processing capabilities, data sovereignty requirements, and integration complexity create distinct competitive arenas within each segmentation axis.
Technology:
Spectral resolution and acquisition modality define performance boundaries for French defense, agriculture, and infrastructure buyers.
- Remote Sensing:Satellite and aerial platforms capture multispectral and hyperspectral imagery through passive radiometric sensors. Sentinel constellation access normalizes free data inputs for Occitanie vineyard cooperatives, though proprietary SAR-optical fusion commands premium pricing from defense agencies requiring all-weather coverage.
- Photogrammetry:Active stereo imaging systems generate centimeter-grade elevation models through overlapping aerial photography. Cadastral surveying mandates from IGN sustain hardware demand despite import dependency on German and Swiss precision optics manufacturers.
- GIS:Spatial database management and cartographic visualization tools anchor enterprise workflows across French utility networks.
- GPS:Satellite positioning augmentation enables real-time kinematic corrections for field surveying and precision agriculture guidance systems.
Remote Sensing leads on scale; Photogrammetry leads on margin stability.
Application:
Regulatory compliance intensity and data refresh frequency vary sharply across use cases, reshaping vendor pricing architectures.
- Agriculture:Precision crop management subscriptions leverage NDVI time-series for irrigation optimization and yield prediction. Occitanie cooperatives drive recurring revenue through vineyard health monitoring tied to AOC certification requirements.
- Urban Planning:ZAC development mandates and Grand Paris infrastructure coordination demand continuous basemap updates rather than static annual purchases.
- Environmental Monitoring:EU Green Deal biodiversity tracking and drought surveillance create government-backed demand cycles with multi-year procurement horizons.
- Disaster Management:Flood response coordination in Atlantic coastal departments requires rapid orthorectification and edge-computing delivery timelines.
Agriculture captures the largest addressable base; Environmental Monitoring exhibits the steepest expansion trajectory.
End User:
Budget authority and technical sophistication create divergent sales cycle dynamics across buyer categories.
- Government:IGN, CNES, and regional planning authorities control the largest procurement budgets with extended validation requirements under EU AI Act transparency mandates.
- NGOs:Conservation organizations in Provence-Alpes-Côte d'Azur rewilding zones purchase ecosystem monitoring subscriptions with restricted funding horizons.
- Research Institutes:INRAE and aerospace engineering programs in Toulouse concentrate spectral analysis expertise for hyperspectral algorithm development.
- Private Sector:Logistics and insurance verticals accelerate adoption for CSRD-compliant environmental footprint verification.
Government dominates current spending; Private Sector is gaining share fastest.
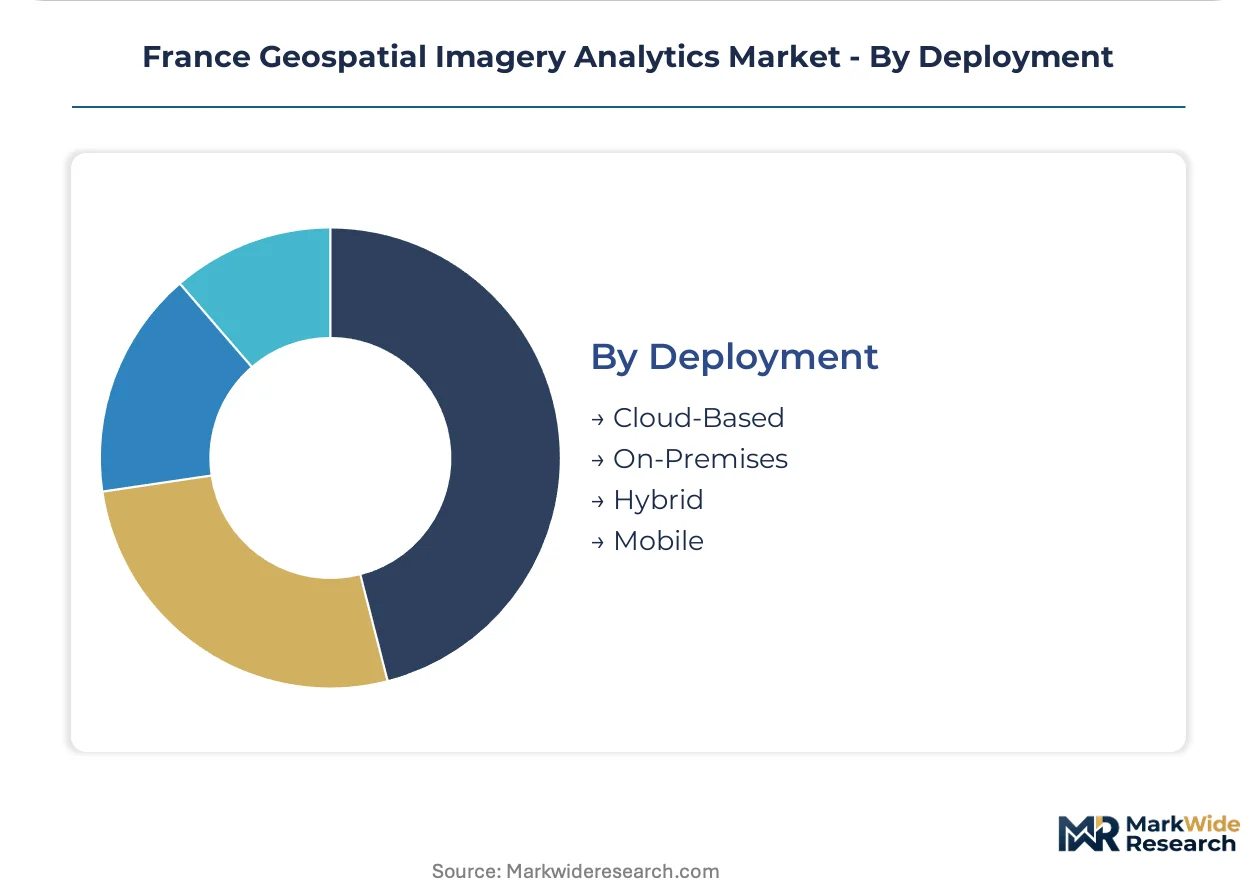
Deployment:
Infrastructure location dictates data sovereignty exposure and latency performance for French buyers.
- Cloud-Based:Scalable processing architectures from Esri and Hexagon AB serve Île-de-France enterprise accounts with consumption-based pricing bundling data refreshes.
- On-Premises:Defense-grade installations at CNES facilities and classified government sites satisfy air-gapped security requirements.
- Hybrid:Split architectures process sensitive raw imagery locally while pushing derived analytics to cloud visualization layers.
- Mobile:Field-deployed tablets and UAV ground stations enable real-time decision support for surveyors and emergency responders.
Cloud-Based anchors commercial volume; Hybrid deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France pioneered operational satellite imagery through CNES-established programs dating to the 1980s. This institutional foundation seeded aerospace clusters that now concentrate geospatial analytics expertise in specific metropolitan zones. Regional demand patterns reflect this historical distribution overlaid with sector-specific regulatory requirements.
Île-de-France
Grand Paris infrastructure coordination drives continuous basemap refresh cycles across utility networks and regional planning authorities. CNIL enforces GDPR constraints on automated image recognition processing personal location data for urban surveillance deployments. The Paris-Saclay aerospace engineering cluster concentrates machine learning classification expertise for hyperspectral algorithm development.
Occitanie
Agricultural cooperatives expand satellite imagery subscriptions for precision crop management and vineyard health monitoring tied to AOC certification requirements. EU AI Act compliance mandates through national CNIL guidance force public administration buyers to upgrade legacy systems. The Toulouse aerospace cluster anchors defense-grade geospatial intelligence procurement with multi-sensor processing architectures.
Provence-Alpes-Côte d'Azur
EU Green Deal biodiversity mandates create recurring revenue streams for ecosystem monitoring subscriptions in Mediterranean conservation zones. CSRD disclosure rules expand corporate demand for geospatial environmental footprint verification from logistics and insurance verticals. Rewilding compliance programs concentrate monitoring demand along coastal and alpine corridor restoration sites.
Hauts-de-France
Photogrammetry retains stronghold status in cadastral surveying where IGN accuracy standards require centimeter-grade elevation models. ZAC development mandates feed continuous mapping refresh cycles linking geospatial basemaps to infrastructure asset management platforms. Lille metropolitan planning authorities drive hybrid cloud-on-premises deployments for sensitive raw imagery processing.
Nouvelle-Aquitaine
Flood response coordination in Atlantic coastal departments requires rapid orthorectification and edge-computing delivery timelines for disaster management applications. Sentinel constellation access normalizes free high-resolution data inputs for drought tracking across agricultural zones. Bordeaux logistics hubs accelerate private sector adoption for supply chain environmental verification.
France Geospatial Imagery Analytics Market Competitive Landscape
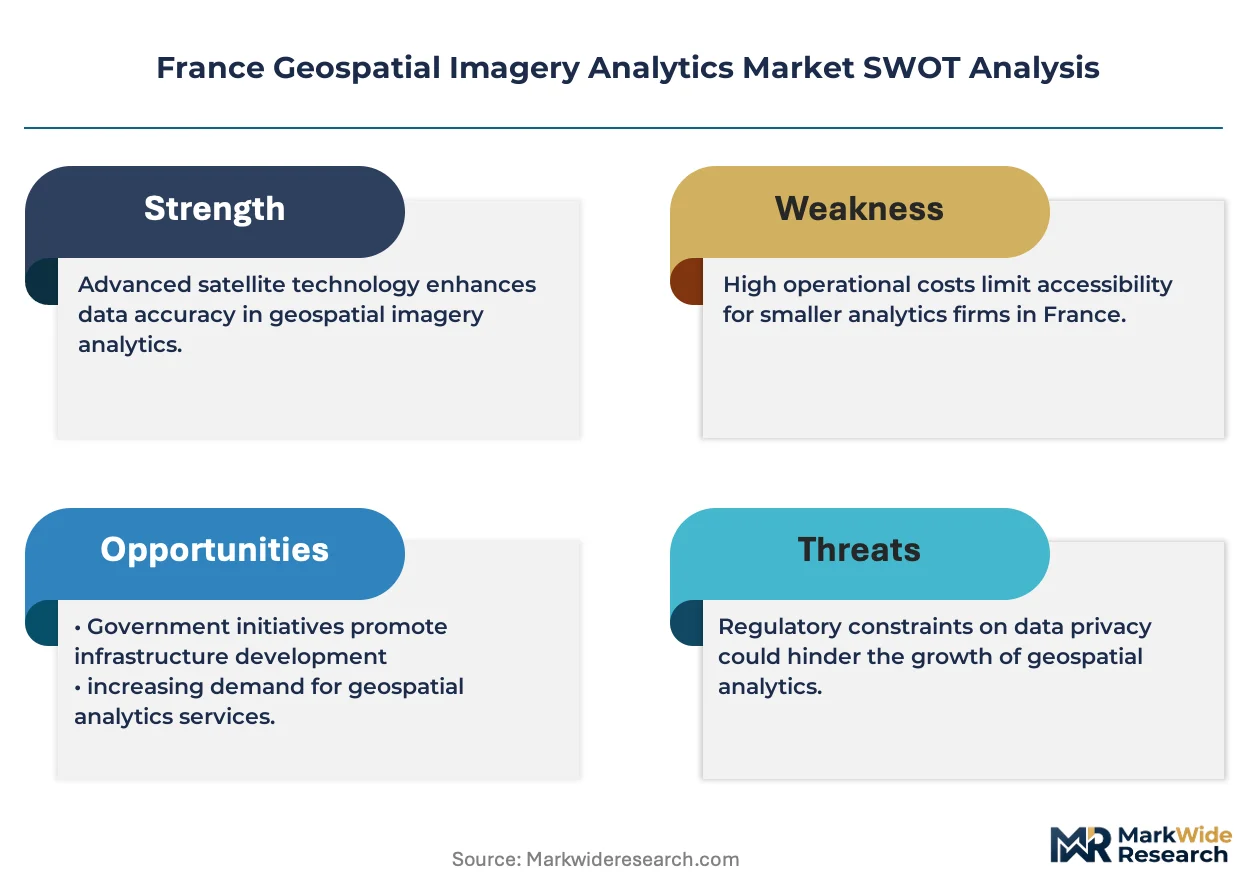
Premium-margin players sit above commodity-margin players across data sovereignty and multi-sensor fusion capabilities. The vendor base stratifies between full-stack satellite operators, specialized analytics software providers, and systems integrators serving defense and government accounts. Two archetypes dominate: constellation owners with native imagery supply and platform-agnostic analytics specialists. Competitive moves center on modular platform unbundling and subscription-based licensing displacement of perpetual software ownership.
Among U.S.-based software platforms, Esri and Microsoft Corporation occupy positions anchoring enterprise accounts through consumption-based pricing models. European aerospace and defense specialists exemplify the full-stack archetype. Hexagon AB represents the analytics-focused tier with deep positioning in precision measurement and geospatial intelligence workflows.
| Leading Market Players |
|---|
| Esri |
| Hexagon AB |
| Google LLC |
| Microsoft Corporation |
| Airbus Defence and Space |
| IGN |
| Trimble Inc. |
| Oracle Corporation |
| L3Harris Technologies |
| Others |
Pricing and Supply Chain Analysis
Hyperspectral sensor fabrication costs cascade through three distinct pricing tiers for French geospatial buyers, with German and Swiss precision optics manufacturers commanding premium positioning for centimeter-grade photogrammetry hardware while Sentinel-derived remote sensing normalizes commodity-tier data inputs.
Pricing Analysis
Consumption-based subscription licensing anchors enterprise procurement across French utility networks and regional planning authorities, displacing perpetual software ownership. Price differentiation separates defense-grade multi-sensor fusion platforms from vineyard monitoring subscriptions tied to AOC certification requirements. Pricing pressure stems from free Copernicus data inputs compressing raw imagery margins. Agricultural cooperatives in Occitanie exhibit highest price sensitivity; CNES and defense agencies demonstrate lowest.
Supply Chain Analysis
Refurbished aerial survey equipment and remanufactured GPS augmentation systems flow back through Toulouse aerospace clusters, extending hardware lifecycles for cadastral surveyors. Supply concentrates in Germany, Switzerland, and the United States for precision optics, radiometric sensors, and edge-computing chipsets. Raw material dependencies include germanium substrates, indium gallium arsenide detectors, and stabilized gyroscopic platforms. Single-source vulnerability concentrates in Swiss photogrammetry lens manufacturers. Distribution runs through IGN-certified systems integrators serving government accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Geospatial Imagery Analytics Market operates as a regulatory compounder where EU AI Act algorithmic transparency mandates through CNIL guidance force recurring platform upgrades across public administration buyers.
For Market Incumbents: Lock in defense-grade accounts by embedding explainable AI documentation capabilities into native model architectures before procurement specifications harden. Counter modular platform unbundling threats through vertical integration into proprietary SAR-optical fusion processing. Prioritize certification investment for IGN orthorectification accuracy standards to compress vendor delivery windows. For New Entrants and Emerging Players: Begin with CSRD-compliant environmental footprint verification services for Bordeaux logistics hubs and Atlantic coastal insurance verticals, the most penetrable private-sector expansion corridor. Target hybrid cloud-on-premises deployments for Hauts-de-France metropolitan planning authorities seeking sensitive raw imagery processing with derived analytics visualization. Pursue partnership-led go-to-market angles with established IGN-certified systems integrators. For Investors and Strategic Acquirers: Consolidation pressure builds where spectral analysis skill scarcity concentrates within Toulouse and Paris-Saclay aerospace engineering programs. Long-term viability favors analytics-focused vendors with multi-sensor processing architectures over pure-play optical providers facing seasonal acquisition gaps. Target acquisition profiles center on specialists with native SAR-optical fusion capabilities. Monitor CNIL enforcement patterns on automated image recognition as inflection indicator for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ArcGIS ecosystem bundling anchors Esri's enterprise accounts across French utility networks. |
| Acquisition of Specialist Firm | Multi-sensor processing architectures elevate vendors above pure-play optical providers. |
| Regulatory Approval Pathway | IGN orthorectification certification compresses vendor delivery windows for national mapping products. |
| Strategic Partnership | 5G terrestrial network alliances enable real-time edge-computing analytics for Atlantic flood response. |
| Geographic Expansion | Provence-Alpes-Côte d'Azur rewilding compliance creates recurring ecosystem monitoring subscriptions. |
Research Methodology
Coverage spans France's five metropolitan geospatial clusters, with primary inputs from each region's aerospace engineering programs, agricultural cooperatives, and regional planning authorities. The analysis combines structured interviews with IGN cartographic directors, CNES mission planners, vineyard cooperative managers, and utility network CTOs with secondary validation from EU INSPIRE directive implementation reports, CNIL algorithmic transparency guidance documents, and Copernicus program data access statistics. Bottom-up demand modeling from end-user procurement cycles triangulates against top-down market sizing from vendor revenue disclosures.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include technology architecture, application vertical, end-user category, and deployment mode, with regional regulatory intensity as an overlay factor. CAGRs derive from weighted scenario analysis incorporating Sentinel constellation access normalization, EU AI Act compliance cost trajectories, and CSRD disclosure rule adoption curves. Industry-specific forecast inputs include vineyard subscription renewal rates and ZAC development mandate mapping refresh frequencies.
Several conditions sit outside the modeled scope, including unforeseen GDPR enforcement escalations on personal location data processing and disruptive satellite constellation launches altering free data availability. Forecasts reflect documented assumptions about CNIL guidance stability and INSPIRE directive interoperability progress. Practitioners should monitor CSRD corporate adoption timelines and edge-computing infrastructure deployment in Atlantic coastal departments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
Geomarketing Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
Cloud GIS Market