
 Cloud GIS Market | 2026-2036
Cloud GIS Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud GIS Market Intelligence
Subscription-based access to specialized geospatial modeling tools is broadening the addressable market for cloud GIS platforms. This shift moves purchasing from perpetual licenses to flexible consumption models. Esri sustains its market leadership through its extensive ecosystem and established government contracts. Meanwhile, Google Earth Engine leverages its massive data processing capabilities, while CARTO specializes in providing location intelligence APIs for enterprise applications.
Cloud GIS refers to the delivery of geospatial software, data, and processing power over the internet, enabling analysis of petabyte-scale datasets. It facilitates collaborative spatial analysis without significant on-premise infrastructure investment. Within solution types, location analytics represents the fastest-growing segment, moving beyond basic mapping services. Applications in urban planning and disaster management are driving significant public sector procurement, particularly for platforms offering advanced geospatial modeling.
Data sovereignty and privacy regulations, such as the EU's GDPR and enforcement actions by the US FTC, govern the handling of location data. Concurrently, environmental mandates from bodies like China's MEE require geospatial data for compliance reporting. Vendors must now decide whether to build regionally isolated data centers or invest in advanced anonymization technologies to ensure compliance.
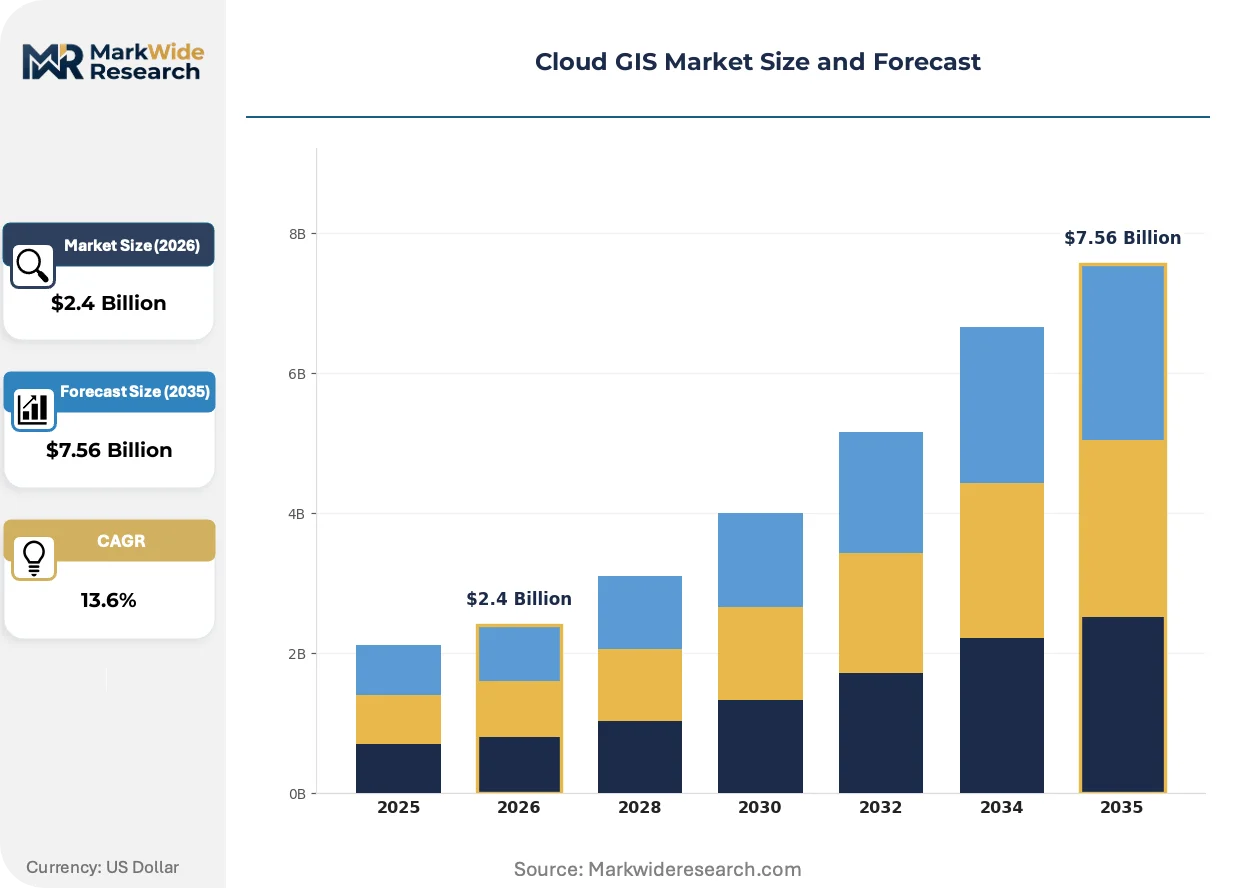
Market Dynamics
The fundamental shift from capital-intensive perpetual licenses to operational, subscription-based consumption models is the central force shaping the Cloud GIS market. This transition democratizes access to advanced geospatial analytics, expanding the user base beyond specialized government agencies and large enterprises to smaller organizations and individual project teams.
Growth Catalysts
- Sustainability Mandates:The EU Green Deal and similar national policies create a direct need for advanced geospatial analysis. Organizations use cloud GIS to monitor emissions, verify land use changes, and report on sustainability targets, driving public and private sector adoption.
- Smart City Initiatives:Urban development projects, particularly in the United States and Germany, rely on cloud GIS for infrastructure planning, traffic management, and public service optimization. This application creates sustained demand for collaborative spatial analysis platforms.
- Accessible Modeling Tools:The availability of specialized geospatial modeling functions through subscription access broadens the addressable market. This model lowers the entry barrier for users in sectors like real estate, retail, and logistics who previously lacked the budget for perpetual licenses.
Market Restraints
- Data Sovereignty and Privacy:Regulations like the EU's GDPR and enforcement actions by the US FTC impose strict rules on handling location data. These requirements can increase operational costs and complexity, forcing vendors to build regional data centers or invest in complex anonymization.
- High-Cost Geospatial Data:While cloud processing is scalable, the acquisition costs for high-resolution, frequently updated satellite or aerial imagery remain a significant barrier for many potential users. This input cost can limit the scope of analysis for budget-constrained projects.
- Interoperability and Standards:A lack of universal standards between different GIS data formats and platforms creates vendor lock-in and integration friction. This can deter organizations with existing legacy systems from migrating fully to a new cloud-native environment.
Strategic Opportunities
- AI-Powered Predictive Analytics:Integrating machine learning algorithms with cloud GIS platforms creates a significant opportunity for predictive spatial modeling. This moves the technology beyond historical mapping to forecasting events like urban growth patterns, crop yields, or climate-related risks.
- Specialized Environmental Compliance:Mandates from bodies like China's MEE for environmental reporting create an opening for tailored cloud GIS solutions. These platforms can automate the collection, analysis, and submission of geospatial data required for regulatory compliance.
- Location Intelligence for Insurance:The insurance industry represents an underpenetrated vertical. There is a clear opportunity for platforms offering granular, real-time risk assessment models for properties based on flood, wildfire, and other location-specific perils.
Industry Challenges
- Geospatial Talent Scarcity:The industry faces a persistent shortage of professionals who possess a dual expertise in data science and geospatial analysis. This skills gap can slow adoption and limit the ability of organizations to extract maximum value from their cloud GIS investments. *Legacy System Integration: Many large enterprises and government agencies struggle with the complexity of integrating modern cloud GIS platforms with their existing on-premise databases and enterprise resource planning systems. This friction can delay or derail migration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud GIS Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.56 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi Cloud Solution Type: Location Analytics, Spatial Data Management, Mapping Services, Geospatial Modeling Application: Urban Planning, Environmental Monitoring, Disaster Management, Real Estate Analysis End User Industry: Government Agencies, Telecommunications, Agriculture Firms, Transportation Services |
| Companies Covered | Cesium, Google Earth Engine, Esri, Cadcorp, TomTom, Felt, HERE Technologies, Bentley Systems, CARTO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud GIS Market Strategic Shifts & Innovations
The convergence of real-time data streams, artificial intelligence, and scalable cloud infrastructure is transforming GIS from a static cartographic tool into a dynamic analytical engine. This evolution enables live monitoring and predictive modeling of complex systems, from urban infrastructure to natural environments.
Digital Twin technology, which creates a virtual replica of a physical asset or system updated with real-time sensor data, is a key innovation. Urban planners and infrastructure operators are the primary adopters of this technology for monitoring and simulation. The integration of IoT data with 3D geospatial models is electrifying the practice of predictive maintenance and operational management for complex assets like utility networks and transportation systems.
Data residency and privacy regulations are actively shaping platform architecture and deployment strategies. For instance, the EU's GDPR and the US FTC's focus on location data privacy are compelling vendors to offer regionally isolated cloud environments. The public sector and industries handling sensitive personal information, such as healthcare and finance, are prioritizing vendors that can guarantee data processing remains within specific legal jurisdictions.
A definitive shift in purchasing behavior is underway, moving from perpetual software ownership to flexible, API-driven consumption models. This approach replaces large upfront capital investment with pay-as-you-go pricing for processing, storage, and specific analytical functions. This trend is most visible in the enterprise software development sector, where developers embed location intelligence into applications without needing a full GIS software stack.
Cloud GIS Market Segmentation
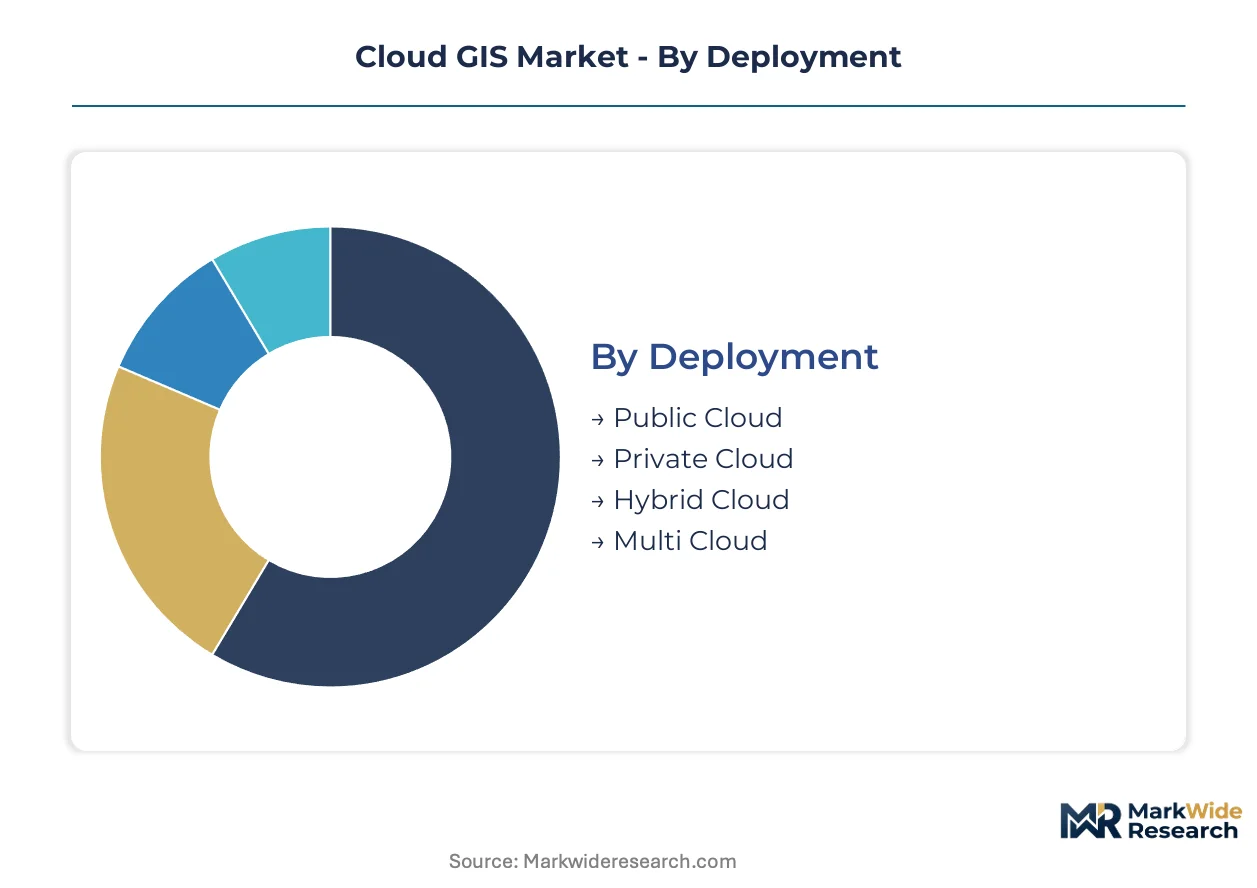
The Cloud GIS market segments into distinct categories reflecting diverse user needs and deployment preferences. Understanding these segments helps providers tailor solutions for specific operational environments and analytical requirements. This granular view reveals where innovation and demand converge across the industry.
Deployment:
The deployment options for cloud GIS solutions span a customization-vs-standardization spectrum, influencing infrastructure control and scalability for users.
- Public Cloud:Public Cloud deployments leverage shared computing resources hosted by third-party providers, offering high scalability and pay-as-you-go models. Demand concentrates in small and medium-sized enterprises seeking reduced upfront infrastructure investment and rapid deployment for project-specific geospatial analysis.
- Hybrid Cloud:Hybrid Cloud models combine private infrastructure with public cloud services, allowing organizations to manage sensitive data on-premises while using public cloud for burst workloads. Government agencies and large enterprises favor this approach for balancing data sovereignty concerns with the flexibility of scalable processing power.
- Private Cloud:Private Cloud solutions involve dedicated cloud infrastructure for a single organization, providing enhanced security and control over geospatial data.
- Multi Cloud:Multi Cloud strategies utilize multiple public cloud providers, enhancing resilience and avoiding vendor lock-in for complex geospatial platforms.
Leading the category by volume: Public Cloud. Growing fastest: Hybrid Cloud.
Solution Type:
Solution types within cloud GIS cater to specific analytical applications, ranging from basic visualization to complex predictive modeling.
- Location Analytics:Location Analytics solutions extract insights from spatial data to identify patterns, trends, and relationships, supporting informed decision-making. Demand is particularly strong in retail and real estate for site selection and customer behavior analysis.
- Geospatial Modeling:Geospatial Modeling tools enable the creation of predictive models and simulations based on spatial data, often incorporating AI and machine learning. Urban planners and environmental monitoring organizations utilize these for complex scenario analysis and impact assessment.
- Spatial Data Management:Spatial Data Management involves organizing, storing, and maintaining large volumes of geospatial information for efficient access and processing.
- Mapping Services:Mapping Services provide foundational cartographic visualization and basic data overlay capabilities for general spatial awareness.
The market prioritizes Location Analytics for its immediate business intelligence value. Geospatial Modeling demonstrates the steepest expansion trajectory.
Application:
Cloud GIS applications address diverse end-user needs, from public sector planning to private industry optimization.
- Urban Planning:Urban Planning applications leverage cloud GIS for infrastructure development, zoning, and resource allocation, enabling smart city initiatives. Public sector entities in Germany and the United States drive demand for these collaborative spatial analysis platforms.
- Environmental Monitoring:Environmental Monitoring uses cloud GIS to track ecological changes, pollution levels, and land use, supporting sustainability mandates. Organizations complying with the EU Green Deal and China's MEE require these tools for compliance reporting.
- Disaster Management:Disaster Management applications utilize cloud GIS for real-time hazard mapping, resource deployment, and emergency response coordination.
- Real Estate Analysis:Real Estate Analysis employs cloud GIS for property valuation, market trend identification, and site suitability assessment.
Urban Planning applications currently hold the largest share. Environmental Monitoring applications are gaining share fastest.
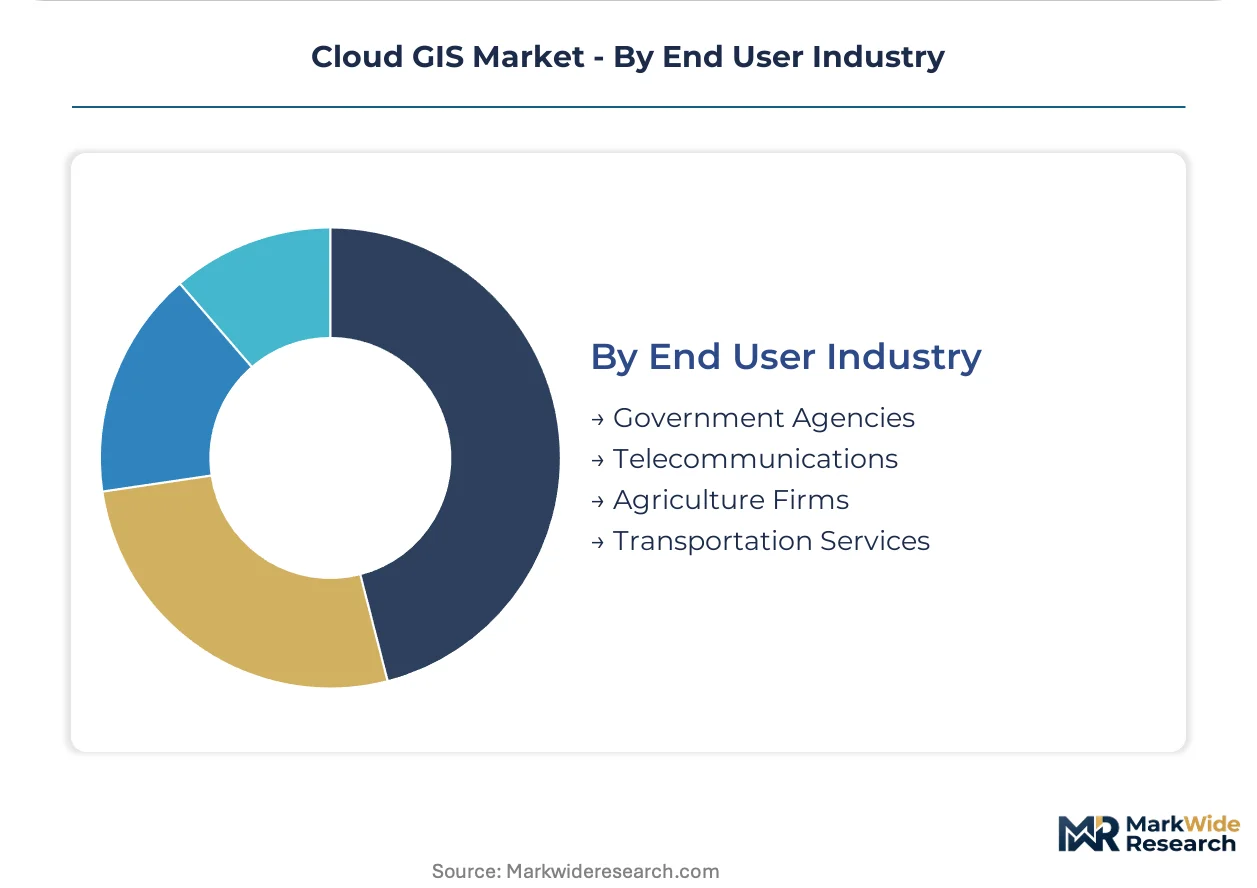
End User Industry:
End user industries for cloud GIS vary significantly in their data volume and analytical sophistication requirements.
- Government Agencies:Government Agencies employ cloud GIS for public services, land management, and regulatory compliance across various departments. Public sector procurement, especially for urban planning and disaster management, drives significant platform adoption.
- Telecommunications:Telecommunications companies use cloud GIS for network planning, infrastructure deployment, and service optimization, especially for 5G rollout. This industry requires precise location intelligence for asset management and coverage analysis.
- Agriculture Firms:Agriculture Firms utilize cloud GIS for precision farming, crop yield prediction, and land health monitoring to optimize operations.
- Transportation Services:Transportation Services leverage cloud GIS for route optimization, fleet management, and logistics planning to enhance efficiency.
Government Agencies represent the largest customer segment. Agriculture Firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Cloud GIS market exhibits a distinct pattern where consumption is broadly distributed, yet the development of advanced platforms and specialized geospatial modeling tools often concentrates in specific technological and economic hubs. This dynamic creates opportunities for both large-scale platform providers and niche solution developers.
United States
Demand for Cloud GIS platforms in the United States stems from extensive smart city initiatives and critical disaster management applications. The US FTC's focus on location data privacy significantly influences vendor compliance strategies for data handling. Major tech centers like Silicon Valley and urban planning departments in cities such as New York drive innovation in geospatial analytics.
Germany
German smart city projects and urban planning efforts create substantial demand for collaborative spatial analysis platforms. The EU Green Deal mandates and GDPR regulations require robust data sovereignty and environmental monitoring capabilities. Munich and Berlin serve as key hubs for geospatial technology development and smart urban infrastructure deployment.
China
China's Cloud GIS market is heavily influenced by environmental monitoring and compliance reporting requirements. The MEE's stringent environmental mandates and national dual carbon goals necessitate extensive geospatial data analysis. The Yangtze River Delta region, with its dense industrial zones, is a focal point for environmental oversight and smart infrastructure planning.
United Kingdom
Urban planning and infrastructure management across the United Kingdom drive demand for sophisticated Cloud GIS solutions. Post-Brexit data regulations, similar to GDPR, shape data residency requirements for vendors. London's financial and insurance sectors increasingly leverage location intelligence for risk assessment and property analysis.
India
India's Cloud GIS market experiences significant growth from precision agriculture firms and burgeoning smart city developments. Government initiatives, such as the PLI scheme for electronics manufacturing, indirectly foster demand for supporting geospatial infrastructure. Bengaluru, as a technology hub, leads in developing and deploying innovative cloud-based mapping and analytics solutions.
Cloud GIS Market Key Industry Players
Capital-heavy platform providers compete with asset-light specialized solution designers in the Cloud GIS market. The market structure features established leaders, niche API providers, and emerging AI-driven analytics firms. Strategic partnerships and portfolio diversification are common competitive moves among participants.
Esri represents established market leadership through its extensive ecosystem and deep government contracts. Google Earth Engine exemplifies massive data processing capabilities, leveraging its cloud infrastructure for petabyte-scale geospatial analysis. CARTO occupies a position as a specialized provider of location intelligence APIs for enterprise applications, enabling flexible consumption models for developers. These companies highlight the diverse business models within the cloud GIS sector.
| Leading Market Players |
|---|
| Cesium |
| Google Earth Engine |
| Esri |
| Cadcorp |
| TomTom |
| Felt |
| HERE Technologies |
| Bentley Systems |
| CARTO |
| Others |
Cost & Logistics Intelligence
The fundamental shift to cloud-native infrastructure for GIS platforms reshapes cost economics by moving from capital expenditure to operational expenditure, influencing vendor supply chain strategies for data centers. This transition impacts both pricing models and the geographic concentration of specialized resources.
Pricing Analysis
Cost-down pressure on basic mapping services accelerates because open-source alternatives offer free options, forcing vendors to differentiate. The dominant pricing structure is subscription-based, often tiered by features, data processing volume, or number of users. Price differentiation stems from the level of customization offered and the scale of data processing required. Small and medium-sized enterprises are most price-sensitive for routine tasks, while government agencies show less sensitivity for mission-critical urban planning or disaster management applications.
Supply Chain Analysis
Workforce availability for data scientists and geospatial engineers in the United States, Germany, and China heavily influences cloud GIS development. The supply chain relies on high-resolution satellite imagery and specialized geospatial algorithms as core inputs. Data sovereignty regulations, such as the EU's GDPR and actions by the US FTC, represent a structural risk, compelling vendors to establish regionally isolated data centers. Distribution primarily occurs direct-to-customer via cloud platforms, with API-driven integration for enterprise developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cloud GIS market represents a significant technology-transition phase, as scalable cloud infrastructure and AI-powered analytics displace traditional on-premise geospatial software. This shift democratizes access to advanced spatial analysis capabilities for diverse users.
For Market Incumbents:Cement market leadership by deepening vertical integration into specialized geospatial data processing and expanding API offerings for developer ecosystems. This strategy helps counter threats from emerging AI-driven analytics firms. Invest heavily in R&D for predictive modeling capabilities to maintain a competitive edge. Focus on long-term government contracts and enterprise solutions that require robust data security and compliance.
For New Entrants and Emerging Players:The EU Green Deal in Europe opens a window for specialized environmental compliance solutions, particularly for monitoring emissions and land use changes. Target underpenetrated segments like location intelligence for insurance, focusing on real-time risk assessment models for properties. A compelling go-to-market angle involves offering flexible, subscription-based access to niche geospatial modeling tools for small and medium-sized enterprises in smart city developments.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized AI-powered geospatial analytics firms and platform providers with strong regulatory compliance capabilities. The long-term viability of the cloud GIS market appears sustainable over the next decade, driven by increasing mandates for environmental monitoring and smart city initiatives. Increased public sector procurement for advanced modeling platforms serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Expands ecosystem reach for established providers like Esri. |
| AI-Powered Analytics Development | Enhances predictive modeling capabilities for urban planning. |
| Specialized Environmental Compliance Solutions | Addresses regulatory mandates from bodies like China's MEE. |
| Geographic Data Center Expansion | Ensures compliance with data sovereignty regulations like GDPR. |
| Subscription Model Refinement | Broadens market access for smaller organizations and developers. |
Research Approach
Multi-period observation of urban growth patterns and environmental compliance rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with geospatial data scientists, urban planners, IT procurement officers, and environmental compliance managers. Secondary validation drew from government spatial data portals, academic research papers, technology firm annual reports, and industry association publications, triangulating data for accuracy.
The segment-weighting approach informed the analytical framework across the modeling period, projecting market evolution. Segmentation dimensions modeled included deployment model, solution type, application, end-user industry, and regional regulatory environment. Compound annual growth rates were derived based on historical growth rates and future market drivers. Key industry-specific forecast inputs included the smart city project pipeline and environmental mandate enforcement levels.
Caveats apply where changes in data privacy regulations, advancements in AI-driven geospatial processing, or shifts in global economic stability could materially shift the outlook. Forecasts reflect assumptions regarding technological adoption and regulatory stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Location Based Advertising Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market