
 Europe Mobile Mapping Market | 2026-2036
Europe Mobile Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Mapping Market Insights
The EU Green Deal is realigning public procurement standards for geospatial services across member states. Hexagon AB leverages its sensor-to-software stack to dominate Nordic infrastructure contracts. Trimble Inc. anchors Western European civil engineering workflows through integrated GNSS hardware. HERE Technologies competes on real-time mapping layers for autonomous vehicle testing corridors.
Europe mobile mapping comprises vehicle-mounted and aerial platforms that capture georeferenced spatial data through LiDAR, photogrammetry, and GNSS integration at centimeter-level accuracy, serving infrastructure lifecycle management and regulatory compliance. Mobile LiDAR systems lead product type revenue due to highway authority upgrade cycles, while integration solutions within the technology dimension capture expanding margin pools as agencies demand unified sensor-to-cloud pipelines. The surveying application segment sustains baseline volume, though asset management is accelerating fastest as utilities digitize underground networks.
EMA coordination on cross-border infrastructure standards and the EU AI Act's geospatial data governance rules are tightening compliance requirements for automated mapping outputs. REACH chemicals regulation affects LiDAR component supply chains through restricted substance controls on sensor coatings. Stakeholders must monitor how the CSRD's spatial data disclosure mandates reshape public-sector vendor qualification criteria.
Market Dynamics
The EU Green Deal's digital infrastructure mandates are compressing procurement cycles for surveying equipment across member states while forcing interoperability standards that favor integrated sensor-to-cloud platforms over point solutions.
Growth Catalysts
- Smart city investments:German transportation authorities are accelerating fleet-wide mobile mapping deployments for real-time traffic management and autonomous vehicle corridor validation.
- REACH compliance automation:LiDAR manufacturers are redesigning sensor coatings to eliminate restricted substances, creating replacement demand across installed bases.
- Rail modernization:France's SNCF-led track digitization programs require centimeter-level asset inventories, driving multi-year mobile LiDAR service contracts.
Market Restraints
- GNSS receiver concentration:European survey-grade receiver supply depends on a narrow base of German and Swiss component specialists, exposing procurement to single-source risk.
- Photogrammetry substitution:Satellite imagery resolution improvements and drone-based capture are eroding price premiums for vehicle-mounted optical systems in low-accuracy use cases.
- CSRD disclosure lag:Spatial data governance rules remain in draft consultation, freezing long-term vendor qualification criteria until final EFRAG technical standards publish.
Strategic Opportunities
- Nordic environmental monitoring:Sweden and Finland's boreal forest carbon accounting programs are funding aerial mobile mapping for above-ground biomass quantification.
- EU AI Act geospatial carve-out:Automated feature extraction from point clouds receives favorable risk classification, accelerating permit timelines for AI-enabled mapping services.
- Utility underground digitization:Water and gas distribution operators in the Netherlands and Belgium are mandating as-built capture via mobile LiDAR for trenchless rehabilitation planning.
Industry Challenges
- Geodetic surveyor scarcity:Professional certification pipelines in France and Germany cannot match retirement rates, constraining field crew scaling for project delivery.
- Multi-sensor calibration complexity:Integrating LiDAR, IMU, and camera subsystems from different vendors demands specialized firmware engineering that delays system commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Mapping Market |
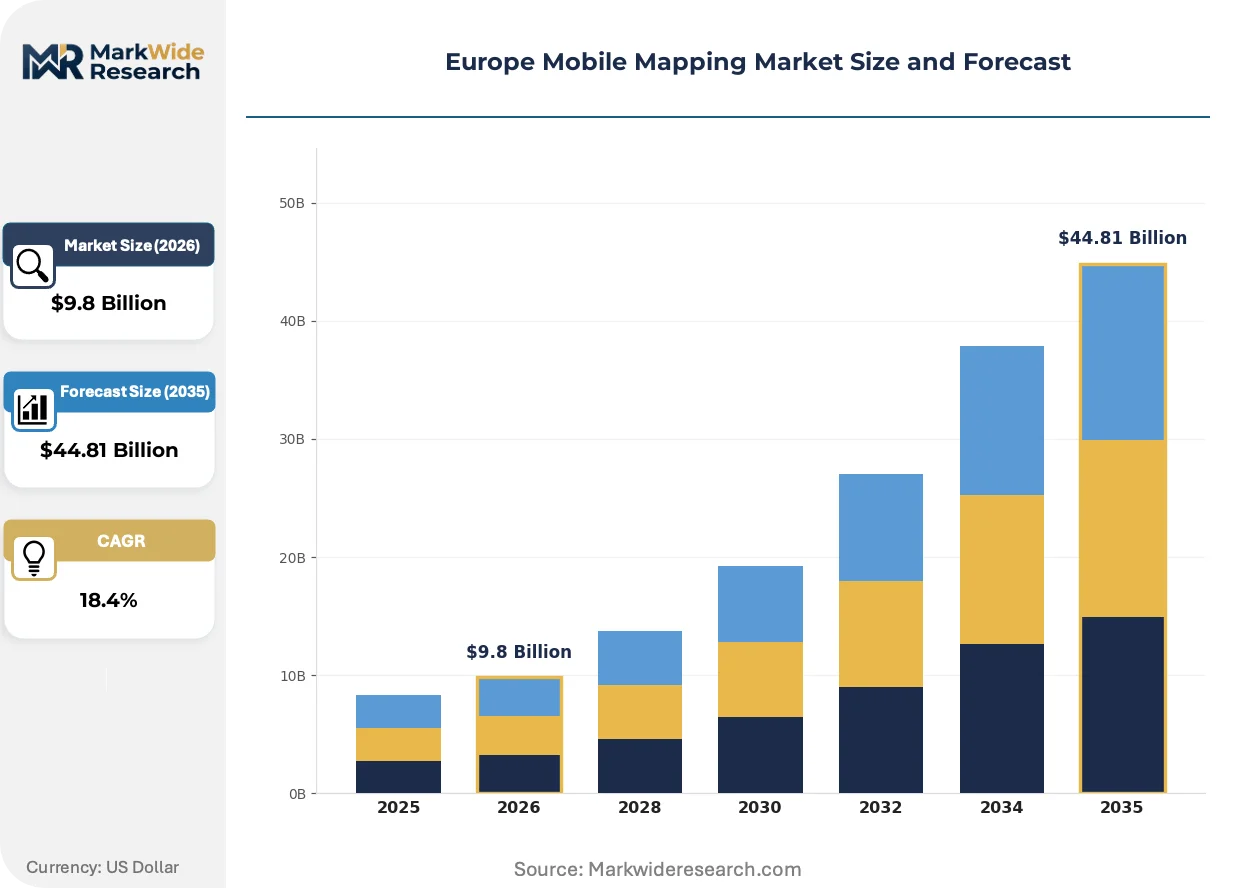
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $44.81 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile LiDAR, Aerial Imaging, 3D Mapping, GPS Systems End User: Civil Engineering, Environmental Agencies, Urban Planning, Transportation Technology: GNSS, Photogrammetry, Laser Scanning, Integration Solutions Application: Surveying, Asset Management, Disaster Management, Infrastructure Monitoring |
| Companies Covered | Trimble Inc., Hexagon AB, Topcon Corporation, Leica Geosystems, Teledyne Technologies, RIEGL, SICK AG, TomTom, HERE Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Mapping Market Trends and Innovations
Solid-state LiDAR architectures and edge-computing payloads are compressing hardware footprints while EU regulatory frameworks are mandating open data formats that threaten proprietary software lock-in.
Solid-state MEMS LiDAR is expanding into highway authority mobile mapping fleets by eliminating mechanical rotation components that fail under constant vibration. German and Austrian road agencies are piloting these units for pavement condition surveys at highway speeds. The technology is expanding into price-sensitive municipal contracts previously served by used equipment markets, compressing residual value recovery for legacy scanner hardware.
The EU AI Act's geospatial data governance rules are classifying automated mapping outputs as high-risk when used for critical infrastructure decisions. Engineering consultancies in France and Italy are restructuring quality assurance workflows to maintain human-in-the-loop validation for regulatory defensibility. Mobile mapping service providers serving rail and dam inspection verticals face the steepest compliance cost increases as they retrain annotation teams and document algorithmic decision trails.
Asset management departments at European utilities are unbundling data capture from engineering analysis, awarding separate contracts to mobile mapping specialists and GIS consultancies. French water authorities pioneered this split-procurement model, and Nordic energy distributors are adopting similar tender structures. The shift is most visible in underground utility mapping, where point cloud deliverables now transfer to in-house geospatial teams or third-party AI extraction platforms rather than bundled interpretation services.
Europe Mobile Mapping Market Segmentation
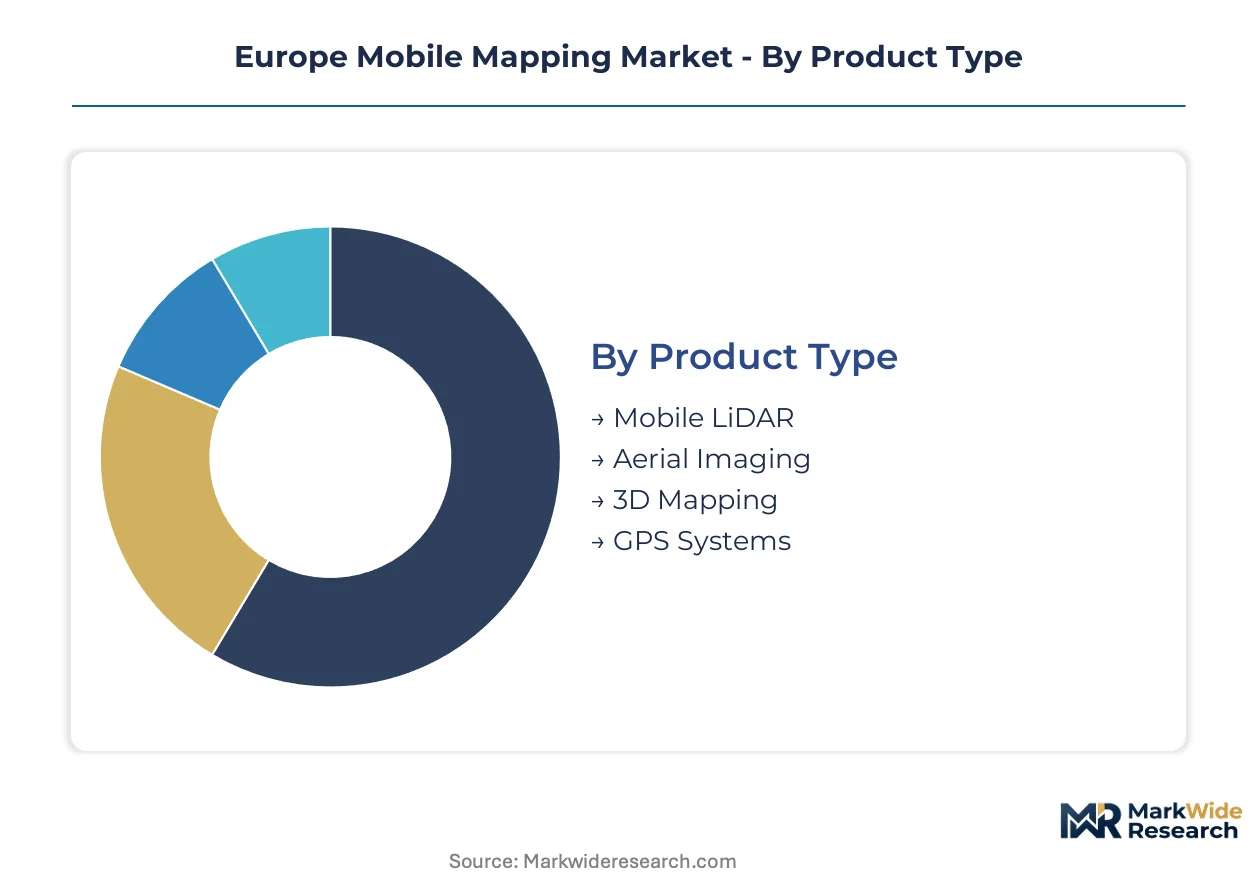
Europe mobile mapping segments reflect divergent buyer priorities across procurement sophistication, technical requirements, and regulatory exposure. Understanding these fault lines clarifies why integrated sensor-to-cloud platforms command premium positioning while point solutions face margin compression.
Product Type:
Buyers in this category separate by accuracy tolerance and fleet integration complexity rather than budget tier alone.
- Mobile LiDAR:Vehicle-mounted laser scanning systems capture dense point clouds at highway speeds through rotating or solid-state sensor heads. German and Austrian road agencies dominate procurement for pavement condition surveys, with REACH compliance mandates accelerating replacement cycles for legacy units with restricted sensor coatings.
- Aerial Imaging:Aircraft and drone-mounted camera arrays generate orthorectified imagery for corridor mapping and environmental monitoring. Sweden and Finland's boreal forest carbon accounting programs fund specialized contracts for above-ground biomass quantification, with EU Green Deal disclosure rules tightening deliverable standards.
- 3D Mapping:Photogrammetric reconstruction pipelines convert overlapping imagery into textured mesh models.
- GPS Systems:Survey-grade GNSS receivers provide geodetic positioning for mobile platform georeferencing.
Volume sits with Mobile LiDAR; growth tilts toward Aerial Imaging.
End User:
Procurement authority in this category clusters by project scale and in-house geospatial capability.
- Transportation:Highway authorities and rail operators commission fleet-wide deployments for real-time traffic management and track digitization. France's SNCF-led asset inventory programs drive multi-year service contracts requiring centimeter-level accuracy for maintenance planning.
- Civil Engineering:Construction firms and surveying consultancies deploy mobile mapping for earthwork verification and as-built documentation. Dutch and Belgian water utilities mandate mobile LiDAR capture for trenchless rehabilitation planning, unbundling data collection from engineering analysis.
- Environmental Agencies:Regulatory bodies monitor land use change and carbon stocks through repeatable aerial surveys.
- Urban Planning:Municipal governments generate base maps for zoning and development control.
Transportation commands procurement volume; Civil Engineering shows the steepest expansion trajectory as utilities digitize underground networks.
Technology:
Technology selection tracks buyer readiness for multi-sensor integration and cloud-native workflows.
- Integration Solutions:Unified sensor-to-cloud pipelines fuse LiDAR, IMU, and GNSS streams with automated feature extraction. EU AI Act geospatial carve-outs accelerate permit timelines for AI-enabled mapping services, while interoperability mandates from the EU Green Deal favor platforms over point solutions.
- Laser Scanning:Discrete LiDAR hardware captures point clouds without bundled software or processing workflows.
- GNSS:Satellite positioning subsystems provide georeferencing for mobile mapping platforms.
- Photogrammetry:Image-based reconstruction techniques compete on cost for lower-accuracy use cases.
Integration Solutions capture expanding margin pools; Laser Scanning retains baseline hardware volume.
Application:
Application segmentation reflects where mobile mapping displaces traditional survey methods versus complements existing workflows.
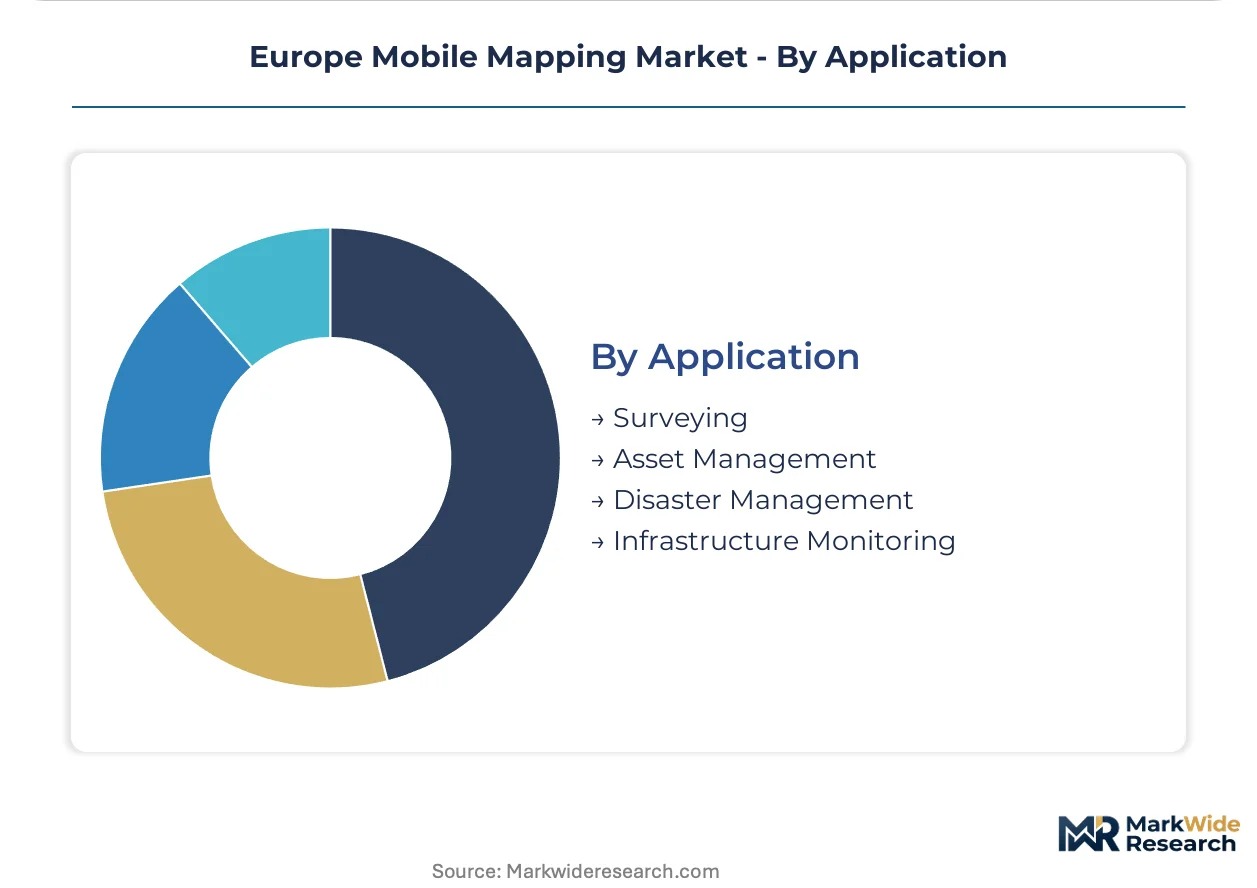
- Asset Management:Utilities and rail operators build centimeter-level inventories for predictive maintenance and regulatory compliance. French water authorities pioneered split-procurement models separating data capture from GIS analysis, with Nordic energy distributors adopting similar tender structures.
- Surveying:Engineering consultancies conduct topographic and boundary surveys under professional geodetic standards.
- Infrastructure Monitoring:Dam, bridge, and slope inspectors deploy repeat-pass mobile mapping for deformation tracking.
- Disaster Management:Emergency responders generate rapid post-event terrain models for damage assessment.
Surveying sustains transaction volume; Asset Management gains share fastest as operators unbundle capture from interpretation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's automotive corridor anchors European mobile mapping demand through autonomous vehicle testing infrastructure and precision manufacturing requirements.
Germany
Transportation authorities in Bavaria and Baden-Württemberg deploy fleet-wide mobile LiDAR for highway pavement surveys and traffic management optimization. KBA mandates on autonomous vehicle validation corridors accelerate procurement cycles for sensor-integrated mapping platforms. Stuttgart's automotive cluster drives solid-state LiDAR adoption for proving ground digitization.
France
SNCF's multi-year track modernization programs sustain demand for centimeter-level mobile mapping services across the national rail network. ANSM and CNIL oversight of geospatial data governance shapes vendor qualification criteria for automated feature extraction. The Île-de-France region concentrates procurement for urban infrastructure digitization under EU Green Deal interoperability mandates.
United Kingdom
Highways England's smart motorway programs fund mobile mapping deployments for asset inventory and condition monitoring. The Environment Agency's flood risk mapping initiatives drive aerial platform adoption for terrain modeling. Greater Manchester and West Midlands combined authorities pioneer split-procurement models separating data capture from GIS analysis.
Netherlands
Water utilities in Randstad mandate mobile LiDAR capture for trenchless rehabilitation planning of aging distribution networks. REACH compliance deadlines accelerate replacement cycles for legacy scanning equipment with restricted sensor coatings. Eindhoven's technology corridor hosts pilot programs for edge-computing payload integration in municipal mapping fleets.
Sweden
Boreal forest carbon accounting programs fund specialized aerial mobile mapping contracts for above-ground biomass quantification. The Swedish Transport Administration's road maintenance digitization drives solid-state LiDAR adoption for highway condition surveys. Stockholm's environmental monitoring cluster concentrates expertise in repeat-pass deformation tracking for infrastructure stability assessment.
Europe Mobile Mapping Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and sensor-to-software stack completeness. The vendor base organizes into three tiers: full-stack platform providers commanding systems-level contracts, hardware specialists delivering discrete LiDAR and GNSS components, and regional service operators executing project-specific capture campaigns. Dominant competitive moves include strategic partnerships between sensor manufacturers and cloud analytics platforms, plus geographic expansion through local service subsidiaries.
Among Sweden-based geospatial conglomerates, Hexagon AB exemplifies the full-stack archetype through sensor-to-software integration. Trimble Inc. represents the precision hardware tier with survey-grade GNSS anchoring civil engineering workflows. HERE Technologies occupies a distinct position on real-time mapping layers for connected vehicle infrastructure. These three entities illustrate how competitive positioning diverges across the platform-hardware-service spectrum.
| Leading Market Players |
|---|
| Trimble Inc. |
| Hexagon AB |
| Topcon Corporation |
| Leica Geosystems |
| Teledyne Technologies |
| RIEGL |
| SICK AG |
| TomTom |
| HERE Technologies |
| Others |
Pricing and Supply Chain Analysis
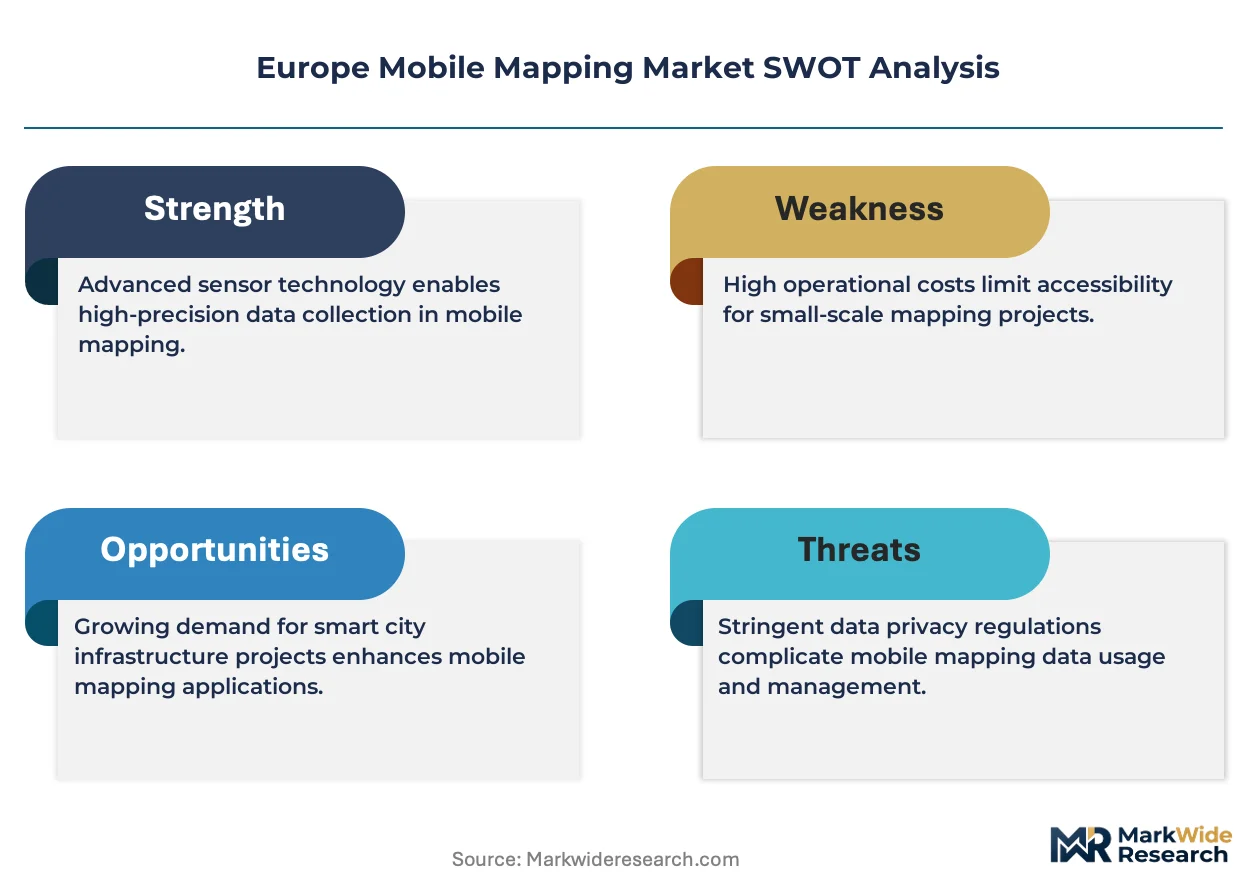
Captive sensor manufacturing in Germany and Switzerland anchors supply positioning for European survey-grade receivers while simultaneously propping pricing power through component scarcity. This integration pattern concentrates cost control among hardware incumbents and limits margin compression for integrated platform providers serving rail and utility verticals.
Pricing Analysis
Outcome-based pricing tied to centimeter-level accuracy certification anchors mobile LiDAR contracts, with French rail operators and Dutch utilities paying premiums for validated point cloud deliverables. Three-tier pricing structure across premium, standard, and economy levels separates Hexagon's full-stack platforms from Trimble's precision hardware and regional service operators. Cost compression in municipal pavement survey segments is intensifying because solid-state MEMS LiDAR entrants are undercutting rotating scanner residual values. Highway authorities show least price sensitivity due to EU Green Deal interoperability mandates, while municipal governments face severe budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss GNSS receiver specialists, exposing European mobile mapping procurement to concentrated component risk. Manufacturing draws from Germany, Switzerland, and Austria for survey-grade inertial measurement units, laser diode emitters, and precision optical assemblies. REACH chemicals regulation restricts sensor coating feedstocks, creating regulatory friction in component sourcing. Distribution runs through authorized dealer networks for hardware and direct enterprise sales for integration platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional geodetic surveyor scarcity across France and Germany props pricing for qualified field crews and integrated automation platforms, constraining capacity expansion regardless of equipment availability.
For Market Incumbents: To counter solid-state MEMS LiDAR price erosion in municipal contracts, deepen backward integration into IMU calibration firmware and anchor rail operator relationships through multi-year SNCF service agreements. Prioritize REACH-compliant coating substitution to accelerate legacy fleet replacement cycles. For New Entrants and Emerging Players: Capture Nordic aerial biomass quantification contracts where Swedish and Finnish carbon accounting programs fund specialized above-ground inventory services. Enter through AI-enabled feature extraction partnerships with utilities unbundling data capture from GIS analysis. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays, with full-stack sensor-to-software providers commanding premium multiples over hardware specialists. Long-term viability favors vendors with EU AI Act compliance infrastructure and CSRD-ready spatial data governance. Watch EFRAG technical standard finalization as inflection signal for vendor qualification criteria stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Cloud Platform Integration | Unifies LiDAR, IMU, and GNSS streams for SNCF track digitization mandates. |
| REACH Compliance Manufacturing Transition | Eliminates restricted sensor coatings to unlock German highway authority replacement demand. |
| AI-Enabled Feature Extraction Partnership | Accelerates permit timelines under EU AI Act geospatial carve-outs for automated mapping. |
| Geographic Service Subsidiary Expansion | Establishes local presence for Dutch utility underground digitization contracts. |
| Professional Certification Pipeline Investment | Addresses French and German geodetic surveyor scarcity constraining project delivery. |
Research Methodology
Multi-period observation of SNCF procurement cycles, KBA autonomous corridor mandates, and Nordic carbon accounting program budgets anchored the trend analysis, supplemented by interviews with mobile mapping fleet managers at German highway authorities, geodetic surveyors in France, utility asset managers in the Netherlands, and integration software engineers at platform vendors. Secondary validation drew from EU Green Deal implementation documents, EFRAG CSRD technical standards drafts, REACH restricted substance lists, and equipment customs records. Bottom-up project pipeline enumeration triangulated against top-down infrastructure spending forecasts.
An input-output matrix framed the analytical approach across the projection horizon, modeling segmentation dimensions spanning product type, end user vertical, technology integration depth, and application workflow position. CAGRs derived from fitted growth curves applied to disclosed public procurement values and utility capital expenditure patterns. Industry-specific forecast inputs included rail modernization program timelines and solid-state LiDAR adoption curves in highway condition surveys.
The model holds under continued EU digital infrastructure spending commitment and stable REACH enforcement; deviation in EFRAG standard publication timing or GNSS component supply disruption would shift vendor qualification and equipment replacement trajectories. Forecasts reflect documented assumptions about interoperability mandate compliance costs and AI Act risk classification stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Global HD Maps Market