
 US Geospatial Imagery Analytics Market | 2026-2036
US Geospatial Imagery Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
US Geospatial Imagery Analytics Market Insights
Cloud-native AI inference is reshaping how geospatial imagery pipelines process petabyte-scale satellite feeds. Maxar Technologies leverages its WorldView constellation to sustain high-resolution data supremacy for defense and intelligence clients. Planet Labs PBC competes through daily global coverage from its Dove and SkySat fleets, while BlackSky differentiates via rapid-revisit, low-latency tasking for tactical applications.
US Geospatial Imagery Analytics encompasses the extraction of actionable intelligence from aerial and satellite imagery through computational methods, typically processing multispectral and synthetic aperture radar data at spatial resolutions from sub-meter to thirty meters. The discipline serves commercial and government users requiring land cover classification, change detection, and object identification across vast geographic extents. Image processing services command substantial margin pools due to specialized sensor calibration and orthorectification expertise. Defense end users represent the most mature demand segment with entrenched procurement channels, whereas environmental monitoring applications are expanding fastest as federal climate accountability mandates intensify.
FAA regulations govern commercial remote sensing licensing and orbital debris mitigation for U.S.-registered satellite operators, while NGA and NRO contracting standards shape vendor qualification and data security protocols for classified geospatial products. The Federal Acquisition Regulation imposes cybersecurity and supply chain transparency requirements that filter market access for foreign-owned imagery providers. Stakeholders must monitor evolving CMMC certification thresholds and congressional appropriations for commercial imagery integration into national security architectures.
Market Dynamics
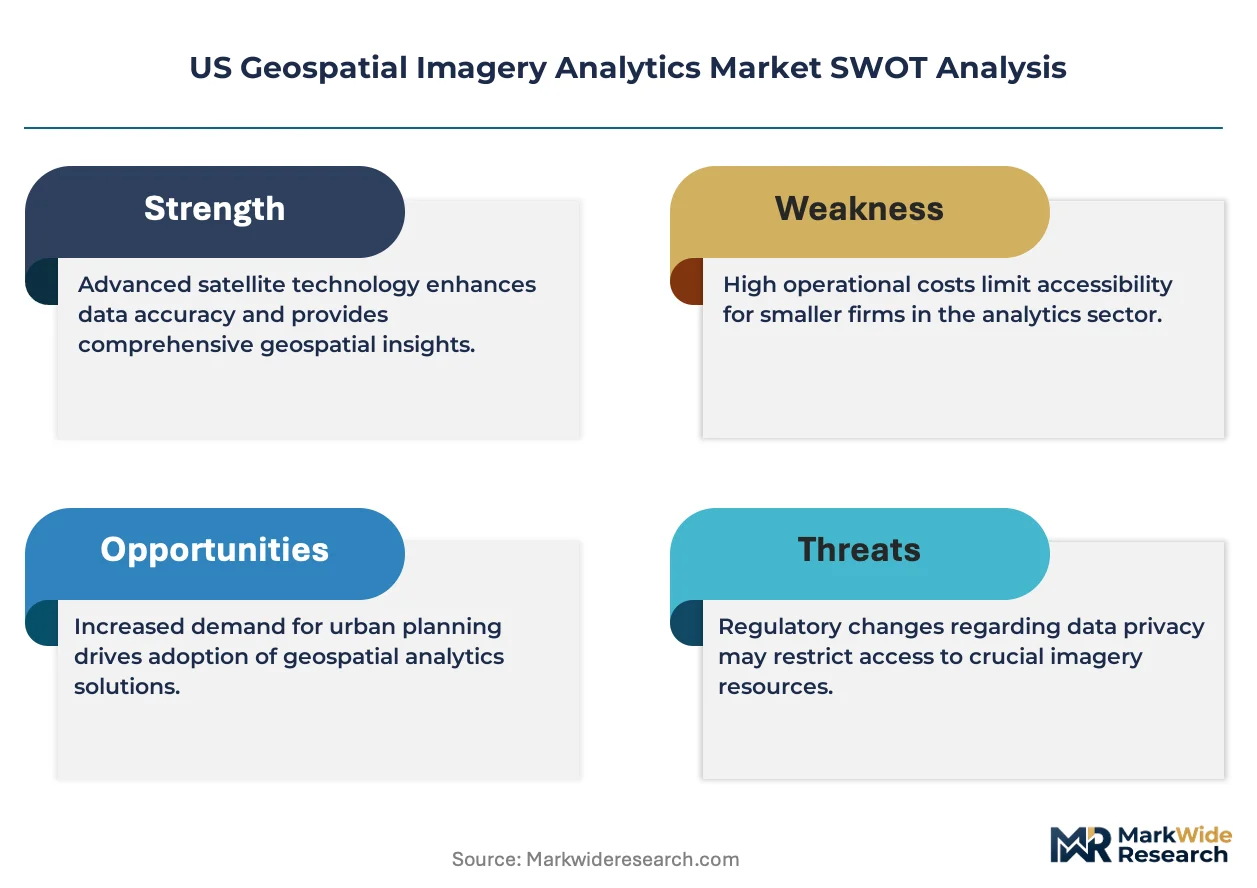
Federal defense procurement of commercial satellite intelligence is compressing vendor qualification timelines while cloud-native AI pipelines are displacing legacy on-premise processing architectures across Colorado's aerospace corridor.
Growth Catalysts
- CMMC Certification Mandates:Department of Defense contractors must achieve Cybersecurity Maturity Model Certification levels to access classified geospatial contracts, filtering qualified vendor pools.
- Climate Accountability Directives:Federal agencies face intensified environmental monitoring mandates requiring land cover classification and change detection at continental scales.
- Synthetic Aperture Radar Integration:All-weather, day-night imaging capabilities are expanding addressable use cases beyond optical satellite limitations for defense and disaster response.
Market Restraints
- Launch Cost Volatility:Satellite constellation deployment depends on SpaceX Falcon 9 and United Launch Alliance Atlas V pricing, with propellant and component supply constraining deployment schedules.
- Foreign Ownership Restrictions:Federal Acquisition Regulation cybersecurity and supply chain transparency requirements block non-US imagery providers from national security procurement channels.
- Sensor Calibration Expertise Scarcity:Orthorectification and radiometric correction require specialized talent concentrated in Colorado and Virginia defense corridors.
Strategic Opportunities
- Wildfire Monitoring Expansion:US Forest Service and Bureau of Land Management require rapid-revisit thermal imaging for western state fire suppression coordination.
- AI-Edge Processing Convergence:Onboard satellite inference chips combined with ground-based neural networks enable sub-hourly intelligence delivery for tactical military applications.
- State-Level Climate Disclosure:California's SB 253 and emerging state mandates create commercial demand for emissions verification through satellite-derived land use analytics.
Industry Challenges
- Security Clearance Pipeline:TS/SCI-cleared imagery analysts face 18-24 month onboarding timelines, constraining NGA contractor workforce scaling.
- Legacy System Integration:Defense intelligence networks require STANAG-compliant data formats, forcing vendors to maintain parallel processing pipelines for interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Geospatial Imagery Analytics Market |
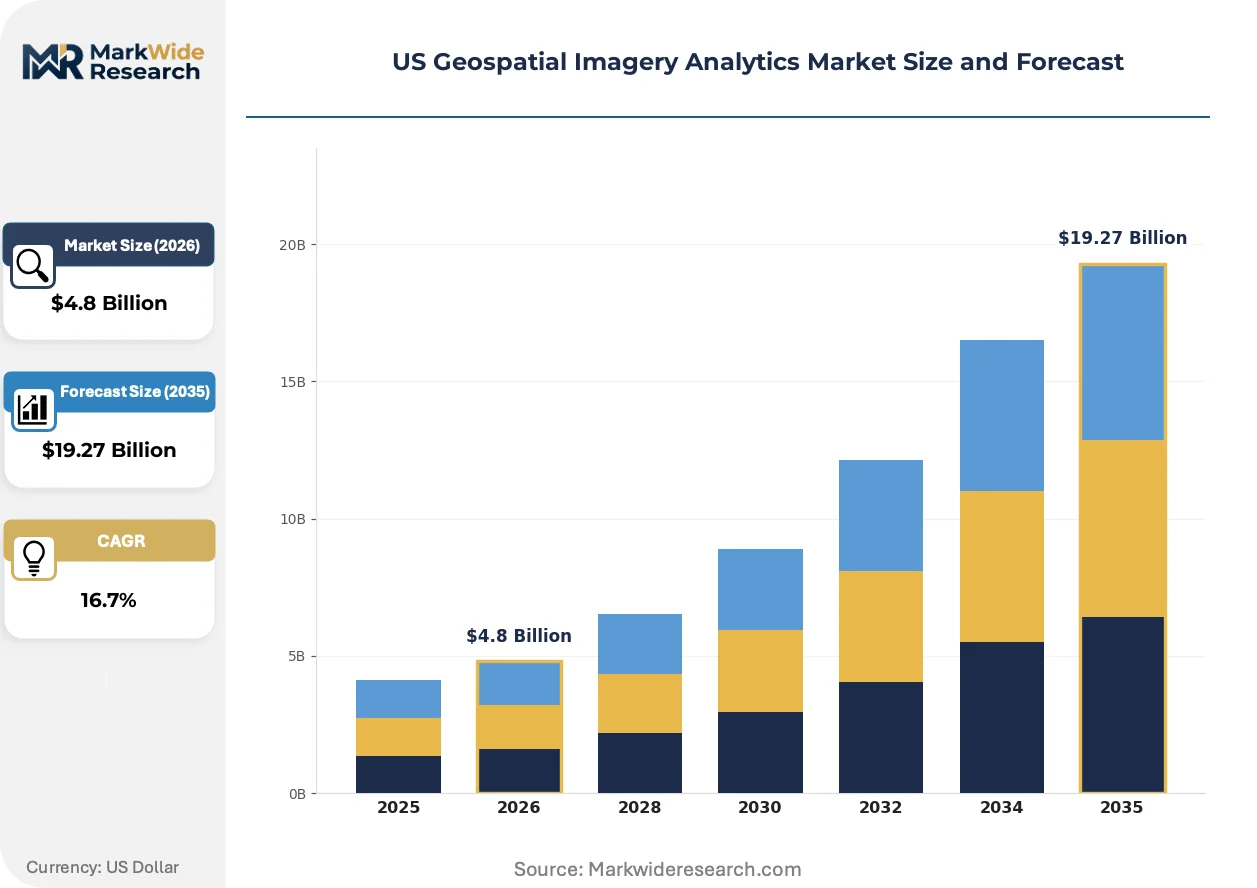
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Acquisition, Image Processing, Data Analysis, Visualization End User: Government, Agriculture, Transportation, Defense Technology: AI, Machine Learning, Remote Sensing, GIS Application: Urban Planning, Disaster Management, Environmental Monitoring, Land Use |
| Companies Covered | Esri, Google, Maxar Technologies, Trimble, L3Harris Technologies, BAE Systems, Planet Labs PBC, BlackSky, EOS Data Analytics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Geospatial Imagery Analytics Market Trends and Innovations
Cloud-native inference architectures are compressing satellite-to-decision latency from days to hours, while federal procurement vehicles are consolidating commercial imagery contracts under streamlined indefinite-delivery mechanisms.
Hyperspectral imaging sensors are migrating from experimental defense applications to operational agricultural and mineral exploration contracts. Commodity traders and precision agriculture operators in the Midwest Corn Belt are adopting 200-plus band spectral analysis for crop stress detection. This capability is migrating from government-exclusive tasking to commercial subscription models, compressing price points for mid-resolution data products.
FAA commercial remote sensing licensing now mandates orbital debris mitigation plans for new constellation authorizations, forcing operators to demonstrate post-mission disposal reliability. Small satellite ventures face extended review timelines for collision avoidance protocols. The regulatory burden falls heaviest on venture-backed newcomers lacking heritage defense relationships, advantaging established Colorado and Virginia contractors with pre-qualified safety documentation.
Defense buyers are unbundling imagery acquisition from analytic processing, creating separate contract vehicles for raw data feeds versus AI-derived intelligence products. NGA's Electro-Optical Commercial Layer program now segments procurement across data providers and algorithm developers. This bifurcation is most visible in Colorado Springs and St. Louis processing centers, where contractor specialization is deepening across the value chain.
US Geospatial Imagery Analytics Market Segmentation
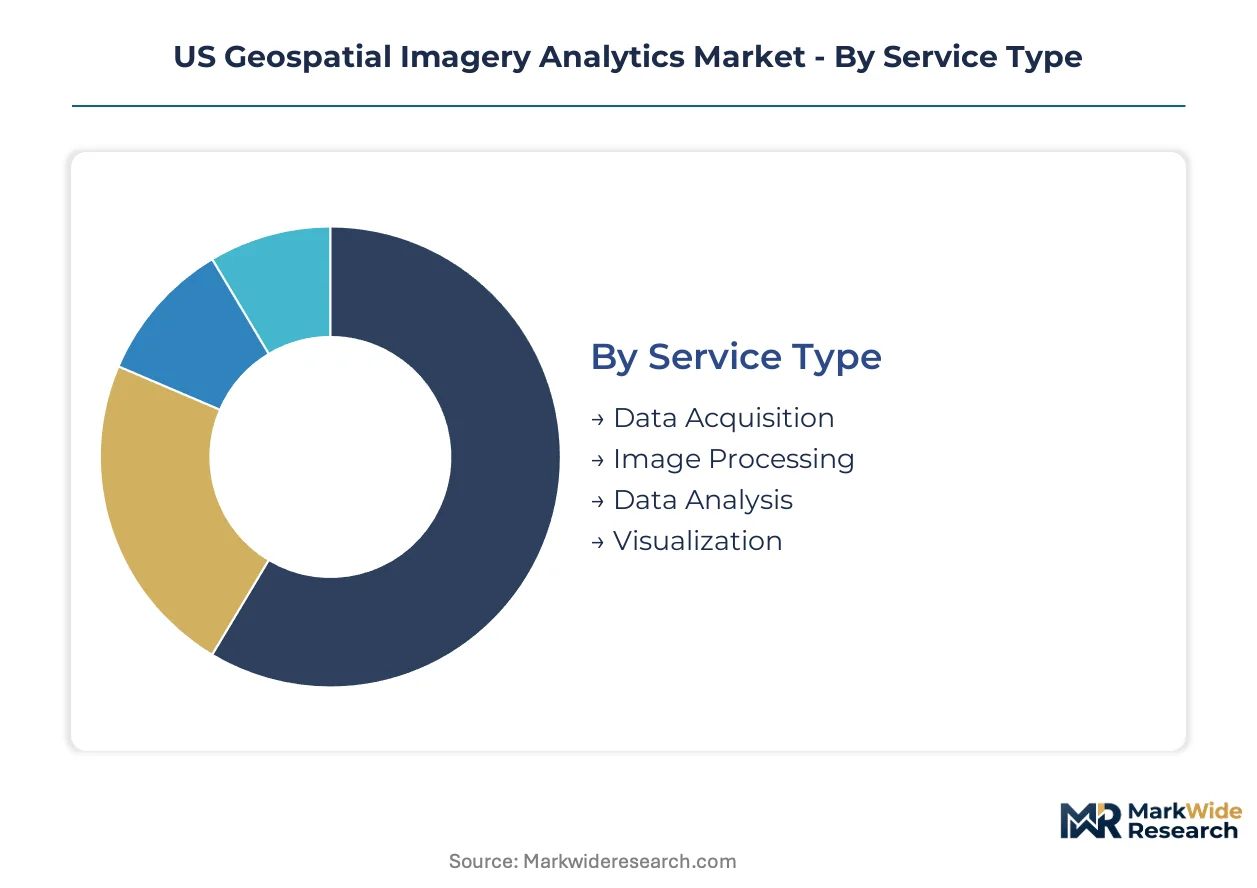
Segmentation in US geospatial imagery analytics reveals how procurement patterns, technical capabilities, and security requirements fragment demand across distinct service tiers and user communities. Colorado's defense corridor and federal contracting channels concentrate revenue in specialized segments requiring CMMC certification and cleared personnel.
Service Type:
Use-case spectrum spans raw data feeds through finished intelligence products, with margin concentration shifting toward analytic layers that transform pixels into decision-ready outputs.
- Data Acquisition:Satellite tasking and aerial collection services capture raw multispectral and synthetic aperture radar imagery at sub-meter to thirty-meter resolutions. Defense agencies dominate procurement through NGA's Electro-Optical Commercial Layer program, where rapid-revisit requirements favor vendors with constellation scale.
- Image Processing:Orthorectification, radiometric correction, and sensor calibration transform raw captures into analysis-ready products. Talent scarcity in Colorado and Virginia corridors limits vendor scaling, entrenching margin pools with established contractors possessing cleared workforces.
- Data Analysis:AI-derived object detection, change detection, and land cover classification extract actionable intelligence from processed imagery.
- Visualization:Geospatial data rendering and interactive mapping interfaces deliver finished products to end-user decision systems.
Established volume favors Data Acquisition; emerging adoption favors Data Analysis.
End User:
Customer type determines procurement velocity, with federal security clearances creating moats around classified contract pools.
- Government:Federal civilian agencies deploy geospatial analytics for environmental compliance, infrastructure monitoring, and regulatory enforcement. Climate accountability mandates from the EPA and USGS accelerate continental-scale land cover classification contracts.
- Defense:NGA, NRO, and combatant commands drive premium pricing through TS/SCI-cleared analyst requirements and STANAG-compliant data formats. Colorado Springs and St. Louis processing centers anchor this segment's geographic concentration.
- Agriculture:Precision farming operators and commodity traders adopt spectral analysis for crop stress detection.
- Transportation:DOT and state agencies leverage imagery for corridor planning and infrastructure condition assessment.
Defense commands margin concentration; Agriculture represents the steepest expansion trajectory as hyperspectral capabilities commercialize.
Technology:
Technical architecture choices separate cloud-native vendors from legacy on-premise installations across the value chain.
- AI:Neural network inference pipelines deployed on satellite edge chips and ground-based cloud clusters compress satellite-to-decision latency to sub-hourly delivery. Tactical military applications and wildfire response coordination drive deployment urgency.
- Machine Learning:Supervised classification algorithms trained on labeled imagery datasets enable automated feature extraction at scale.
- Remote Sensing:Multispectral, hyperspectral, and synthetic aperture radar sensor technologies capture electromagnetic signatures across wavelength bands.
- GIS:Geospatial information systems integrate imagery layers with vector data for spatial analysis and cartographic output.
Remote Sensing anchors current infrastructure investment; AI commands R&D prioritization as federal procurement bifurcates raw data from analytic contracts.
Application:
Functional use cases align with regulatory mandates and natural hazard patterns across domestic geography.
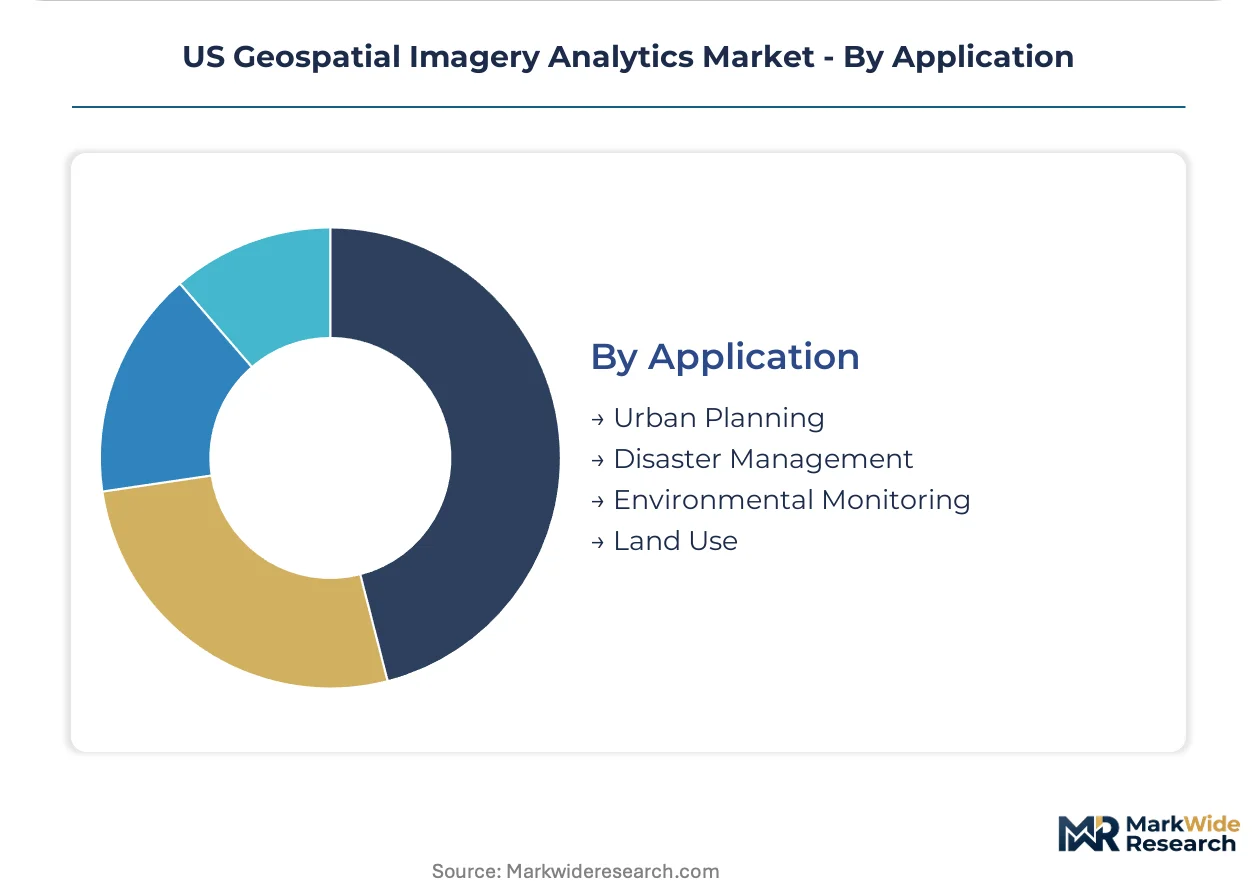
- Urban Planning:Municipal zoning authorities and real estate developers utilize high-resolution imagery for land use mapping and development impact assessment. California SB 253 climate disclosure requirements create commercial demand for satellite-derived emissions verification.
- Disaster Management:US Forest Service and Bureau of Land Management rapid-revisit thermal imaging contracts support western state fire suppression coordination. Low-latency tasking capabilities differentiate vendor selection in emergency response scenarios.
- Environmental Monitoring:Federal climate accountability directives intensify continental-scale change detection requirements.
- Land Use:Agricultural boundary delineation and property assessment applications serve county assessor and insurance underwriting workflows.
Land Use sustains recurring subscription revenue; Disaster Management exhibits the most volatile procurement spikes tied to seasonal fire and hurricane cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic geospatial imagery analytics flows concentrate in defense contracting corridors rather than export-oriented manufacturing zones. Colorado and Virginia corridors absorb federal procurement dollars while commercial demand fragments across agricultural and climate compliance applications.
Colorado Front Range
NGA contractor facilities and satellite operator headquarters cluster along the Denver-Aurora-Colorado Springs axis. CMMC certification requirements filter vendor access to classified imagery contracts. Lockheed Martin and Maxar Technologies sustain cleared workforces in this corridor.
National Capital Region
NGA headquarters in Springfield and NRO contracting offices in Chantilly anchor intelligence procurement. The Federal Acquisition Regulation imposes cybersecurity and supply chain transparency mandates on imagery providers. TS/SCI-cleared analyst talent concentrates in Virginia suburbs.
California Technology Corridor
SB 253 climate disclosure mandates drive commercial demand for satellite-derived emissions verification. Planet Labs PBC operates from San Francisco with cloud-native processing infrastructure. Agricultural commodity traders in the Central Valley adopt hyperspectral crop stress detection.
Midwest Agricultural Belt
Precision farming operators in Iowa and Illinois subscribe to spectral analysis services for yield optimization. USDA conservation programs fund satellite-derived land cover classification. University of Minnesota and Purdue University anchor academic remote sensing expertise.
Southwest Border Region
Customs and Border Protection tasking contracts require rapid-revisit thermal imaging for surveillance applications. Arizona and New Mexico test ranges support sensor calibration for defense contractors. Bureau of Land Management wildfire monitoring contracts spike seasonally across this zone.
US Geospatial Imagery Analytics Market Competitive Landscape
On the supply side, the industry is bifurcated between heritage defense contractors with cleared workforces and venture-backed satellite operators with cloud-native architectures. Established Colorado and Virginia contractors maintain moats through CMMC certification and TS/SCI personnel pipelines. Emerging competitors compete on latency and revisit frequency rather than security clearance depth. Dominant competitive moves include strategic partnerships with federal procurement vehicles and portfolio diversification into AI-derived analytic layers.
Within the satellite constellation tier, Maxar Technologies, Planet Labs PBC, and BlackSky represent distinct technical positioning. Maxar exemplifies the heritage defense contractor archetype with WorldView constellation scale and entrenched NGA relationships. Planet Labs PBC occupies a position emphasizing daily global coverage through Dove and SkySat fleets. BlackSky anchors the rapid-revisit, low-latency segment for tactical military applications. Esri and Google sit within the software platform layer, supplying geospatial information systems and cloud infrastructure rather than raw imagery collection.
| Leading Market Players |
|---|
| Esri |
| Maxar Technologies |
| Trimble |
| L3Harris Technologies |
| BAE Systems |
| Planet Labs PBC |
| BlackSky |
| EOS Data Analytics |
| Others |
Pricing and Supply Chain Analysis
Colorado's Front Range corridor concentrates cleared workforce capacity and CMMC-certified processing infrastructure, translating into pricing power for defense-tier imagery analytics that commercial buyers cannot replicate. The bifurcation between classified federal contracts and commercial subscriptions creates tiered margin pools across the value chain.
Pricing Analysis
Defense agencies anchor pricing structures around multi-year indefinite-delivery contracts with cost-plus fee structures, while commercial agriculture and climate compliance buyers face SaaS-tiered subscription models. Price differentiation rests on CMMC certification level and TS/SCI clearance depth, with the former commanding premium multiples over uncertified alternatives. Pricing pressure stems from cloud-native competitors compressing latency benchmarks and forcing heritage contractors to modernize legacy processing pipelines. Commercial precision agriculture operators exhibit highest price sensitivity, whereas NGA and combatant commands demonstrate inelastic demand for rapid-revisit, low-latency tasking.
Supply Chain Analysis
Maxar Technologies, Planet Labs PBC, and BlackSky hold satellite constellation capacity with manufacturing anchored in US aerospace corridors. Raw component dependencies draw from specialized sensor foundries, radiation-hardened chip suppliers, and precision optics manufacturers concentrated in domestic defense industrial base zones. Single-source vulnerability runs through SpaceX Falcon 9 and United Launch Alliance Atlas V launch manifests, where propellant constraints and component shortages compress deployment schedules. Distribution feeds from ground station networks into cloud-based processing clusters, with finished intelligence products delivered through STANAG-compliant data formats to defense networks or API endpoints for commercial subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Geospatial Imagery Analytics Market sits at a platform-economics inflection where NGA's unbundling of raw data from AI-derived intelligence creates interoperability standards that reshape competitive boundaries across the value chain.
For Market Incumbents: Build cleared workforce moats through accelerated TS/SCI pipeline investments and CMMC Level 3 certification maintenance ahead of contracting threshold escalations. Vertical integration into onboard satellite inference chips defends margin position against cloud-native challengers commoditizing ground-based processing. Lockheed Martin and Maxar Technologies should deepen Colorado Springs processing center specialization while monitoring Planet Labs PBC's latency compression in tactical military applications. For New Entrants and Emerging Players: Pursue wildfire monitoring white space through rapid-revisit thermal imaging subscriptions for US Forest Service and Bureau of Land Management coordination centers, where incumbent coverage gaps spike seasonally. California SB 253 emissions verification mandates create penetrable commercial demand for satellite-derived land use analytics without requiring defense clearance infrastructure. Go-to-market positioning should emphasize sub-hourly delivery guarantees through AI-edge processing convergence rather than competing on resolution specifications. For Investors and Strategic Acquirers: Long-term, this sits as a defense-cleared infrastructure play because federal procurement consolidation under streamlined indefinite-delivery vehicles favors scale incumbents with pre-qualified safety documentation and heritage NGA relationships. Acquisition targets should display CMMC certification progress and cleared analyst bench strength rather than pure technology differentiation. Watch NGA Electro-Optical Commercial Layer contract award velocity as the signal for procurement vehicle consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Certification Acceleration | Defense contractors achieve Level 3 thresholds to access classified NGA imagery contracts before qualification timelines compress further. |
| AI-Edge Processing Deployment | Onboard satellite inference chips from vendors like BlackSky enable sub-hourly intelligence delivery for tactical military coordination. |
| Wildfire Monitoring Subscription Launch | Rapid-revisit thermal imaging contracts with US Forest Service capture seasonal procurement spikes across western states. |
| Hyperspectral Commercialization | 200-plus band spectral analysis migrates from defense-exclusive tasking to Midwest Corn Belt agricultural subscription models. |
| Cloud-Native Pipeline Migration | Heritage contractors displace legacy on-premise architectures to match Planet Labs PBC latency benchmarks in commercial segments. |
Research Methodology
Desk research of FAA commercial remote sensing licensing records, NGA contracting disclosures, and SEC filings from satellite operators preceded structured interviews with NGA program managers, defense contractor capture executives, commercial imagery product directors, and precision agriculture technology officers. Secondary validation drew from USGS land cover databases, USDA conservation program allocations, and CMMC accreditation registries. Bottom-up segment sizing across service type, end user, technology, and application dimensions was triangulated against top-down federal appropriations tracking for commercial imagery integration.
Assumptions held fixed across the modeling period include sustained DoD procurement velocity for commercial satellite intelligence and continued FAA orbital debris mitigation enforcement without regulatory expansion. Variables tested included SpaceX launch cost trajectories, CMMC certification threshold escalations, and state-level climate disclosure mandate adoption rates. CAGRs were derived from segment-level growth rate reconciliation against macro defense spending and agricultural technology investment patterns. Forecast inputs incorporated synthetic aperture radar integration timelines and hyperspectral sensor commercialization curves.
Sensitivities concentrate around congressional appropriations volatility for NGA commercial imagery programs and launch manifest disruptions from propellant supply constraints. Forecasts reflect these assumptions with explicit scenario boundaries for federal procurement consolidation and commercial subscription scaling. Quarterly review of NGA Electro-Optical Commercial Layer award velocity and CMMC accreditation pipeline depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market