
 Geographic Information System (GIS) Market | 2026-2036
Geographic Information System (GIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Geographic Information System (GIS) Market Analysis
North American geospatial software development is broadening as defense and civilian agencies expand mapping procurement. Esri leverages its ArcGIS ecosystem to anchor enterprise accounts across federal and municipal layers. Hexagon competes through sensor-to-software integration, while Bentley Systems extends digital twin capabilities into infrastructure lifecycle management.
A geographic information system constitutes a computational framework for capturing, storing, manipulating, analyzing, and displaying geographically referenced data, typically operating through layered vector and raster architectures with coordinate precision to sub-meter resolution. Its primary commercial purpose enables location-based decision support across asset tracking, land administration, and environmental monitoring functions. Cloud-based deployment now leads new contract value as utilities and governments abandon capital-intensive on-premise server farms. Spatial analysis solutions command premium pricing where real-time routing and predictive terrain modeling integrate with IoT sensor networks.
FAA geofencing mandates for unmanned aerial systems and EPA watershed delineation standards shape product compliance requirements for U.S. vendors. EU Green Deal spatial reporting obligations and CSRD disclosure rules force European adopters to upgrade from static mapping to dynamic carbon-accounting geodatabases. Stakeholders must weigh interoperability investments against proprietary platform lock-in as open-source alternatives mature.
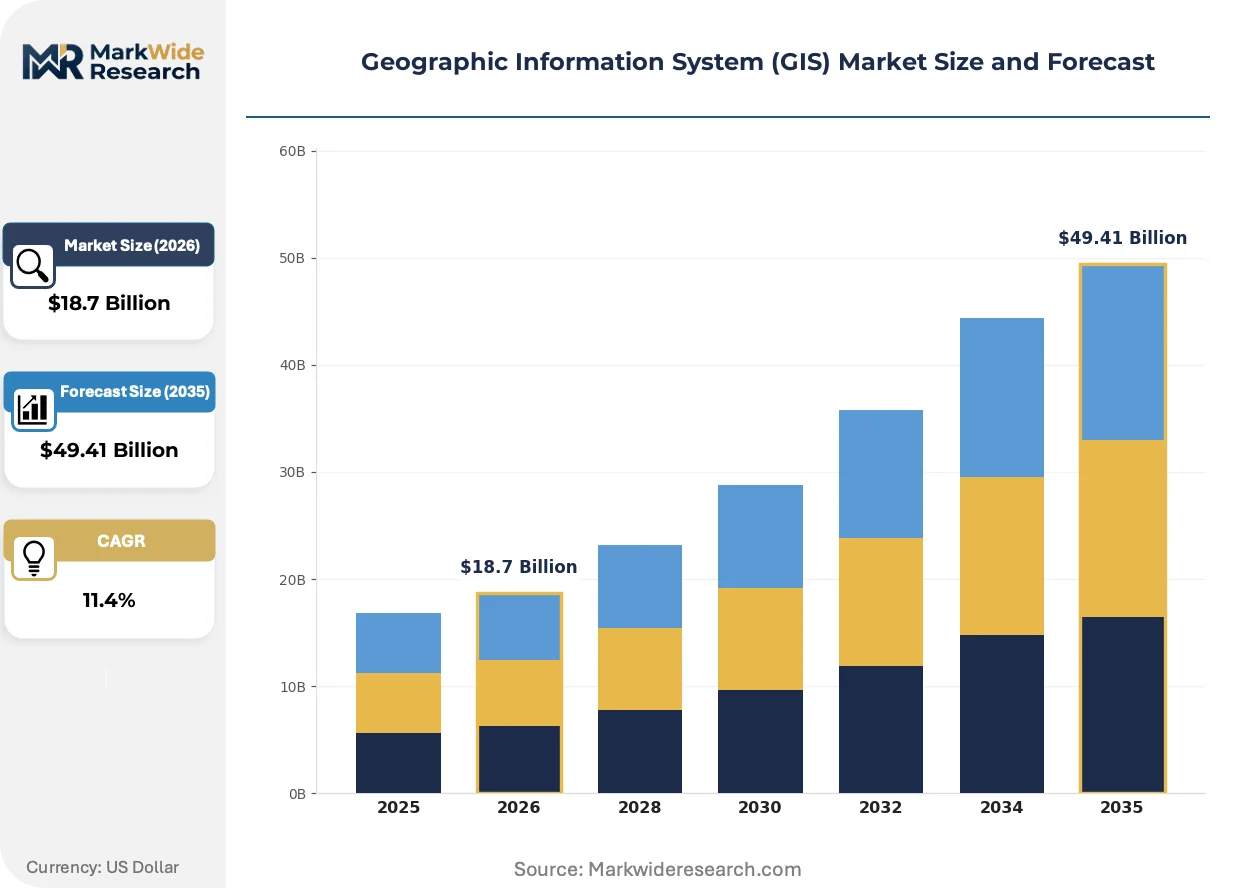
Market Dynamics
Cloud-native geospatial architectures are compressing procurement cycles as utilities and municipal agencies abandon capital-intensive on-premise server deployments for consumption-based SaaS models. This infrastructure shift reconfigures vendor pricing power and customer switching economics across the entire value chain.
Growth Catalysts
- EU Green Deal spatial mandates:German urban planning agencies now require geospatial compliance for infrastructure permits, forcing static mapping upgrades to dynamic carbon-accounting geodatabases.
- IoT-sensor convergence:Real-time routing and predictive terrain modeling integrated with distributed sensor networks command premium pricing in utility asset management.
- FAA geofencing enforcement:Unmanned aerial system operational mandates create compliance-driven procurement for geofencing software across commercial drone operators.
Market Restraints
- Proprietary platform lock-in:Enterprise ArcGIS deployments create switching costs that deter migration to open-source alternatives despite maturing interoperability standards.
- Specialized talent scarcity:Geospatial data science and coordinate systems engineering expertise concentrates in defense-adjacent labor markets, inflating implementation costs.
- Legacy system integration friction:Municipal governments face decade-old CAD and asset management databases that resist API-based connectivity without expensive middleware.
Strategic Opportunities
- CSRD disclosure acceleration:European corporate sustainability reporting obligations expand addressable market for carbon-accounting geodatabases beyond traditional planning agencies.
- Digital twin lifecycle extension:Infrastructure operators seek unified platforms spanning design, construction, and operations, displacing point-solution vendors.
- Southeast Asian utility modernization:Cloud-based deployment absorbs bulk procurement across national water and electricity grids replacing obsolete paper-based cadastral systems.
Industry Challenges
- Interoperability investment timing:Stakeholders must weigh standardization costs against proprietary feature depth as OGC and ISO specifications evolve.
- Sub-meter accuracy certification:Survey-grade precision requirements for land administration create extended validation timelines that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geographic Information System (GIS) Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Solution: Spatial Analysis, Data Management, Visualization Tools, Mapping Software End User: Government, Transportation, Utilities, Environmental Application: Urban Planning, Disaster Management, Resource Management, Agriculture |
| Companies Covered | Fugro, Maxar Technologies, Esri, Mapbox, CARTO, Hexagon, Bentley Systems, GeoSLAM, Topcon Positioning Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geographic Information System (GIS) Market Emerging Trajectories
Real-time geospatial processing is displacing batch analytics across mission-critical applications. Three technology and behavioral shifts are compressing product lifecycles and rewiring competitive positioning in spatial intelligence markets.
Vector-tile streaming architectures are overtaking traditional raster pyramid serving for web mapping applications. Logistics platforms and ride-hailing operators now demand sub-second viewport rendering for fleet visualization. This performance threshold is compressing vendor differentiation around latency rather than feature breadth.
EPA watershed delineation standards are tightening data granularity requirements for environmental compliance software. Industrial discharge permit holders must now submit dynamic hydrological models rather than static catchment maps. Agricultural and mining operators in the Mississippi River basin face the steepest adaptation costs.
Subscription-based platform access is displacing perpetual license sales in municipal procurement. German and French regional governments now prioritize operational expenditure flexibility over capital ownership in RFP evaluation criteria. This preference shift favors vendors with mature multi-tenant cloud infrastructure over traditional on-premise specialists.
Geographic Information System (GIS) Market Segmentation
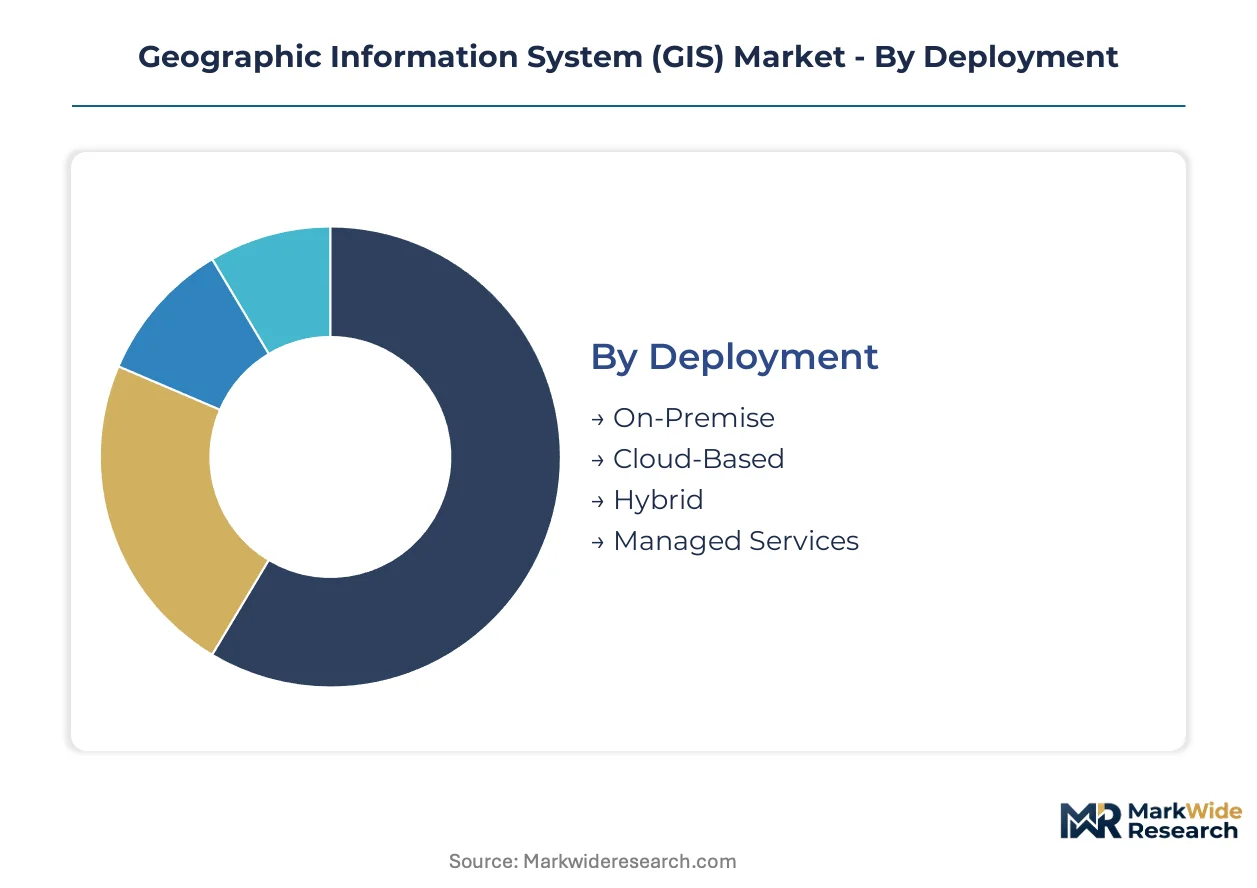
GIS procurement patterns diverge sharply across deployment architectures and end-use verticals, with cloud migration cycles and regulatory compliance timelines determining vendor selection criteria. Solution providers must align platform roadmaps with the replacement schedules of legacy CAD systems and the integration requirements of IoT sensor networks.
Deployment:
Upgrade cycles for on-premise server infrastructure are accelerating as municipal agencies confront end-of-life support deadlines for decade-old spatial databases.
- Cloud-Based:Multi-tenant SaaS architectures deliver consumption-based pricing that eliminates capital expenditure approval bottlenecks in German and French regional procurement. Southeast Asian utilities now mandate cloud-native deployment for national grid modernization contracts, displacing legacy paper-based cadastral systems.
- On-Premise:Air-gapped installations persist in defense and intelligence applications where data sovereignty requirements override cost considerations. FAA geofencing compliance systems and classified mapping workflows in US federal facilities sustain residual demand despite shrinking new license sales.
- Hybrid:Split architectures partition sensitive vector data on local servers while pushing raster processing to cloud compute nodes. European water utilities adopt this model to satisfy GDPR residency rules while leveraging elastic processing for flood simulation workloads.
- Managed Services:Outsourced infrastructure operations appeal to mid-sized municipalities lacking in-house geospatial data science expertise. Canadian provincial governments contract specialized operators to maintain survey-grade coordinate reference systems without direct personnel investment.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as regulated industries seek operational flexibility without full data migration.
Solution:
Functional specialization within GIS platforms tracks the divergence between technical users requiring analytical depth and executive consumers demanding visual accessibility.
- Spatial Analysis:Advanced geoprocessing engines execute overlay operations, network analysis, and predictive terrain modeling with sub-meter coordinate precision. EPA watershed delineation mandates and EU Green Deal carbon-accounting requirements drive premium pricing for dynamic hydrological modeling capabilities.
- Mapping Software:Core visualization platforms remain the entry point for municipal planning departments transitioning from static cartography to interactive web mapping. German urban agencies embed these tools into infrastructure permit workflows under revised EU spatial compliance directives.
- Data Management:Enterprise geodatabase systems govern version control, metadata standards, and multi-user editing workflows for distributed organizations. US county assessor offices deploy these solutions to reconcile parcel boundary disputes with federal cadastral benchmarks.
- Visualization Tools:Dashboard and storymap components translate complex spatial outputs into consumable formats for non-technical stakeholders. French regional governments prioritize these capabilities in RFP evaluations to satisfy transparency obligations under CSRD disclosure rules.
Mapping Software retains the largest installed base, though Spatial Analysis is gaining share fastest as environmental compliance mandates tighten data granularity requirements.
End User:
Procurement authority and budget scale vary dramatically across public sector hierarchies and regulated utility structures.
- Government:Federal, state, and municipal agencies constitute the foundational demand base for land administration and defense applications. US civilian and military mapping commands expand enterprise licensing across federal and municipal layers simultaneously.
- Utilities:Electricity, water, and gas network operators require real-time asset tracking integrated with predictive maintenance systems. Southeast Asian national grids replace obsolete infrastructure records with cloud-based spatial platforms to reduce non-revenue water losses.
- Transportation:Logistics platforms and ride-hailing operators demand sub-second viewport rendering for fleet visualization and route optimization. Vector-tile streaming architectures displace traditional raster serving for high-frequency location updates.
- Environmental:Agricultural and mining operators in regulated watersheds face steep adaptation costs as static catchment maps yield to dynamic hydrological models. Mississippi River basin discharge permit holders invest heavily to satisfy tightening EPA data standards.
Government dominates absolute expenditure, with Utilities expanding most quickly as grid modernization programs accelerate across emerging economies.
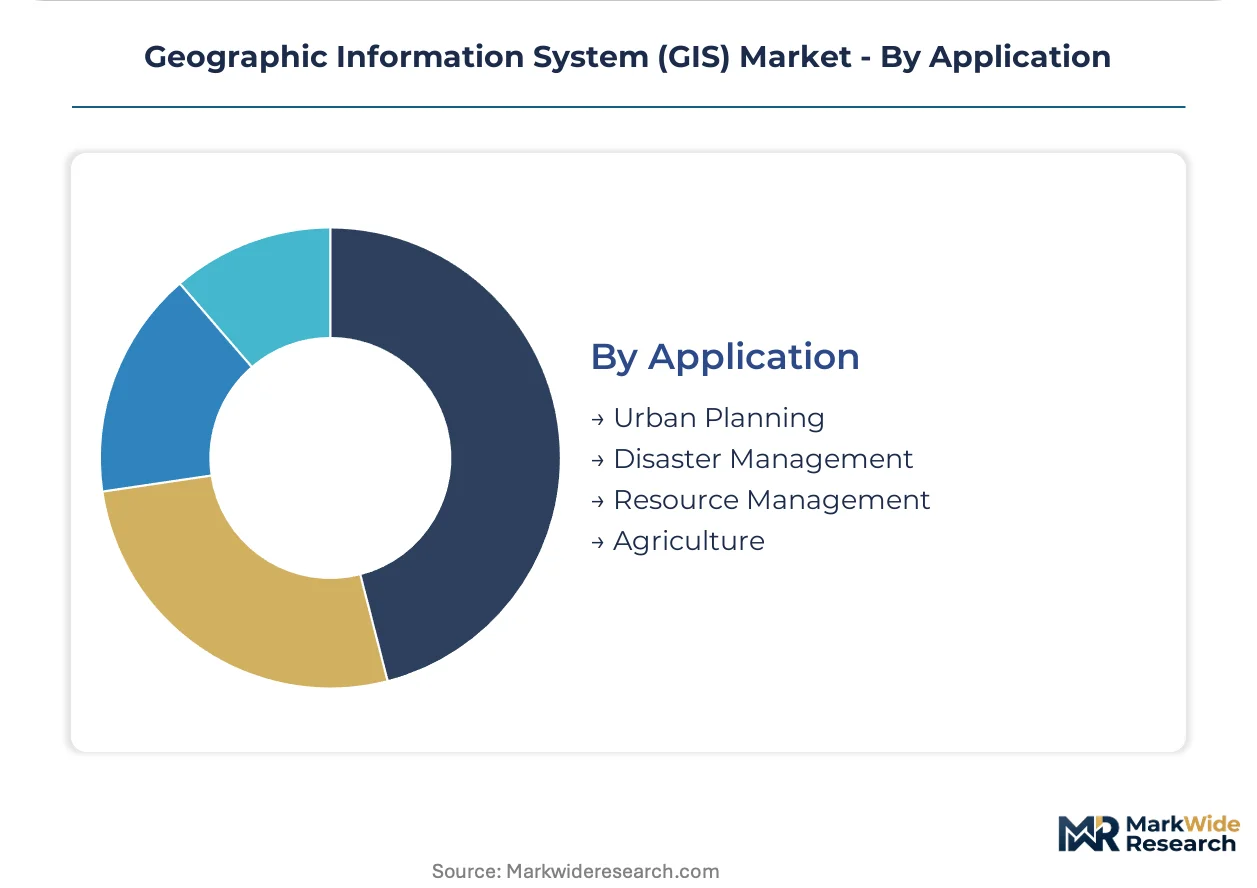
Application:
Use case maturity determines whether implementations emphasize established workflows or experimental technology integration.
- Urban Planning:Zoning analysis, site selection, and infrastructure corridor optimization represent the longest-established commercial application of GIS technology. German cities now embed carbon-accounting geodatabases directly into building permit approval processes.
- Disaster Management:Real-time flood forecasting and wildfire perimeter tracking command premium pricing where sensor network integration enables predictive alerting. Japanese prefectural governments prioritize these capabilities following intensified typhoon seasons.
- Resource Management:Forestry, mining, and petroleum operators balance extraction efficiency against environmental compliance documentation. Canadian provincial regulators mandate spatial submission standards for lease applications and reclamation bonding.
- Agriculture:Precision farming applications integrate satellite imagery, soil sampling grids, and yield monitoring to optimize input application. Variable-rate technology adoption concentrates in large-scale operations with sufficient acreage to justify subscription costs.
Urban Planning maintains the deepest penetration, while Disaster Management shows the steepest expansion trajectory as climate adaptation funding flows into municipal emergency preparedness budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping GIS procurement as vendors relocate development operations to jurisdictions with streamlined geospatial data governance. Compliance cost differentials between EU Green Deal jurisdictions and emerging markets are accelerating cloud infrastructure migration patterns.
United States
FAA geofencing mandates for unmanned aerial systems and EPA watershed delineation standards drive federal procurement volume. Defense and civilian mapping commands expand enterprise licensing across federal and municipal layers simultaneously. Greater Washington DC and Denver-Aurora clusters concentrate geospatial software engineering talent serving classified and civilian applications.
Germany
Urban planning agencies mandate geospatial compliance for infrastructure permits under EU Green Deal directives. KBA and federal building regulations force static mapping upgrades to dynamic carbon-accounting geodatabases. Bavaria and North Rhine-Westphalia host the densest concentrations of municipal GIS modernization contracts.
China
National grid operators and smart city initiatives absorb substantial spatial analytics capacity for utility asset management. MIIT data localization requirements and dual carbon goals shape domestic vendor selection criteria. Yangtze River Delta municipalities lead sub-meter cadastral system deployments for land administration reform.
Japan
Prefectural governments prioritize real-time disaster management capabilities following intensified typhoon seasons. METI standards for infrastructure resilience drive predictive terrain modeling procurement. Kanto and Kansai regions concentrate municipal emergency preparedness budgets for flood forecasting systems.
India
Smart Cities Mission and national water grid modernization programs displace obsolete paper-based cadastral systems. CEA mandates for electricity distribution mapping create compliance-driven procurement cycles. Karnataka and Maharashtra state utilities lead cloud-native deployment adoption for non-revenue water loss reduction.
Geographic Information System (GIS) Market Vendor Landscape
North American producers anchor the enterprise software tier; European specialists hold sensor-to-software integration positions. The vendor landscape exhibits moderate concentration with platform ecosystems commanding disproportionate account control. Three archetypes dominate: full-stack platform providers, sensor-hardware integrators, and cloud-native point-solution vendors. M&A activity concentrates on digital twin capabilities and real-time processing startups; strategic partnerships link geospatial engines with IoT sensor networks.
Among platform-centric providers, Esri and Hexagon occupy positions representing contrasting integration philosophies. Mapbox exemplifies the cloud-native specialist archetype with developer-facing tooling. These three anchors illustrate how competitive positioning diverges between incumbent ecosystem depth and API-first accessibility.
| Leading Market Players |
|---|
| Fugro |
| Maxar Technologies |
| Esri |
| Mapbox |
| CARTO |
| Hexagon |
| Bentley Systems |
| GeoSLAM |
| Topcon Positioning Systems |
| Others |
Supply Flow & Price Mechanics
Municipal procurement offices in Germany and France concentrate purchasing authority for geospatial platforms, anchoring contract value to operational expenditure flexibility rather than capital ownership models. This buyer concentration compresses vendor margins while rewarding multi-tenant cloud infrastructure investments that eliminate upfront server procurement.
Pricing Analysis
Distributor margins for enterprise GIS implementations range between fifteen and twenty-five percent, with direct-to-government contracts commanding steeper discounts than channel-mediated municipal sales. Pricing stratifies across premium, standard, and economy tiers based on coordinate precision certification and IoT sensor integration depth. Cost compression in the standard tier is intensifying because open-source alternatives mature and interoperability standards reduce switching friction. Small and mid-sized municipalities exhibit the highest price sensitivity, while defense and intelligence agencies prioritize air-gapped capabilities over cost optimization.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale demand from Southeast Asian national grid modernization programs, bypassing traditional systems integrators. Component manufacturing concentrates in the United States, Germany, and China, with sensor hardware sourcing from Japan and South Korea. Software development draws from specialized geospatial data science labor pools concentrated in Greater Washington DC and Denver-Aurora clusters. Single-source vulnerability in survey-grade coordinate reference system certification creates extended validation timelines. Distribution runs through specialized geospatial systems integrators for complex enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic Information System procurement has shifted toward late-cycle quality specifications as EU Green Deal mandates and FAA geofencing standards force upgrades from static mapping to dynamic carbon-accounting and real-time compliance platforms.
For Market Incumbents: Anchor platform ecosystems through sensor-to-software integration investments that deepen switching costs for enterprise accounts threatened by open-source migration. Prioritize backward integration into IoT sensor networks to capture predictive terrain modeling premiums. Defend municipal relationships by embedding carbon-accounting geodatabases directly into permit approval workflows before CSRD disclosure rules expand competitive bidding. For New Entrants and Emerging Players: Enter via cloud-native API-first architectures targeting mid-sized Canadian and Indian municipalities lacking in-house geospatial expertise. Southeast Asian water utilities represent the most penetrable segment, with national non-revenue water loss reduction programs mandating cloud deployment. Pursue managed services contracts for survey-grade coordinate system maintenance as a recurring revenue anchor. For Investors and Strategic Acquirers: Infrastructure software conglomerates are the most active acquirer in this space, targeting digital twin specialists with lifecycle management capabilities spanning design through operations. Long-term viability rests on platform consolidation around unified geospatial engines rather than point-solution fragmentation. Watch for EPA watershed delineation standard tightening as the signal for premium hydrological modeling demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies sensor networks with geospatial engines for real-time utility asset tracking. |
| Acquisition of Specialist Firm | Digital twin capabilities extend infrastructure lifecycle management beyond design phases. |
| Strategic Partnership | IoT sensor alliances enable predictive terrain modeling for flood forecasting systems. |
| Product Launch | Carbon-accounting geodatabases satisfy EU Green Deal spatial compliance mandates. |
| Geographic Expansion | Cloud infrastructure deployment captures Southeast Asian utility modernization contracts. |
Methodological Framework
Bottom-up utility and government procurement modeling reconciled against top-down vendor contract tracking forms the analytical core of this study. Primary interviews with municipal GIS directors, federal mapping command procurement officers, utility asset managers, and cloud platform engineers were validated against secondary sources including EPA enforcement databases, EU Green Deal implementation reports, FAA UAS integration filings, and municipal RFP documentation. Trade data from customs records and national grid operator procurement disclosures provided import and deployment pattern verification.
Historical trendline analysis established baseline penetration rates across deployment architectures and solution types. The projection framework models cloud, on-premise, hybrid, and managed services segments alongside spatial analysis, mapping software, data management, and visualization tool categories. End-use verticals including government, utilities, transportation, and environmental applications were tracked across urban planning, disaster management, resource management, and agriculture use cases. CAGRs were derived from replacement cycle timing, regulatory compliance deadlines, and infrastructure investment program announcements.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in classified defense procurement volumes introduce uncertainty bands around federal segment estimates. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and FAA geofencing enforcement timelines. Periodic stress-testing of base assumptions against emerging open-source platform maturity and interoperability standard adoption is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market