
 Asia Pacific Digital Maps Market | 2026-2036
Asia Pacific Digital Maps Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Digital Maps Market Outlook
Subscription-based map data layers is restructuring how vendors monetize geospatial intelligence across the Asia Pacific. Google LLC leverages its Street View capture infrastructure to sustain dominance in consumer navigation. Baidu, Inc. anchors its position through tight integration with China's mobility super-apps. HERE competes on automotive-grade HD mapping contracts with Japanese and Korean OEMs.
Asia Pacific digital maps are georeferenced spatial databases that encode terrain, infrastructure, and transportation networks with sub-meter GPS accuracy for commercial routing and visualization. These systems process satellite imagery, sensor feeds, and user-generated corrections to deliver real-time positional intelligence for fleet dispatch and augmented reality overlays. Navigation applications command the largest revenue pool due to embedded consumer dependency, while cloud-based maps represent the fastest-expanding technology segment as telecom operators deploy edge computing nodes. Fleet management end users generate the most stable recurring revenue, whereas augmented reality deployments remain nascent but carry premium pricing potential.
China's SAMR enforces geospatial data security classifications that restrict cross-border map transfers, compelling foreign vendors to localize server infrastructure. Japan's METI promotes QZSS augmentation standards that improve centimeter-level accuracy for autonomous vehicle testing. India's CEA coordinates with BIS on digital infrastructure codes that mandate interoperable mapping formats for government smart city tenders. Stakeholders must weigh data sovereignty compliance costs against the revenue upside of supplying automotive OEMs and logistics platforms across divergent national regulatory regimes.
Market Dynamics
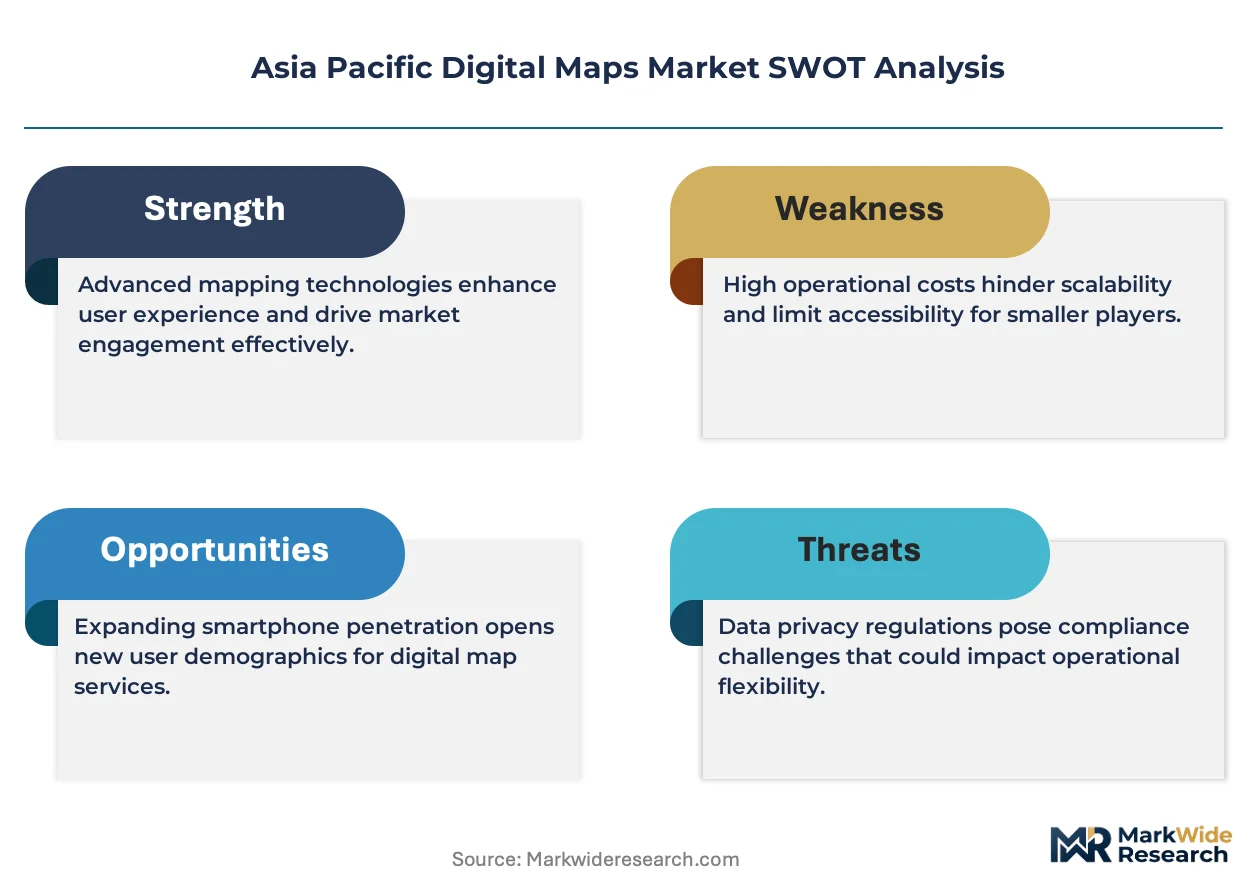
Data sovereignty mandates across Asia Pacific are fragmenting cloud infrastructure requirements, forcing map vendors to replicate compute nodes in every national jurisdiction while maintaining cross-border synchronization for multinational logistics clients.
Growth Catalysts
- Smart city infrastructure mandates:India's CEA coordinates with BIS on interoperable mapping codes for urban mobility tenders, accelerating procurement of real-time traffic layers.
- QZSS augmentation standards:Japan's METI promotes centimeter-accuracy protocols that enable autonomous vehicle testing corridors around Tokyo and Nagoya.
- Fleet electrification:Southeast Asian logistics platforms are integrating range-optimized routing algorithms with charging station databases to support commercial EV deployment.
Market Restraints
- Input cost volatility:Satellite imagery licensing fees from commercial constellation operators fluctuate with launch schedules and orbital capacity constraints.
- Supply concentration risk:High-precision LiDAR sensor production concentrates among Japanese and German component specialists, creating procurement bottlenecks for HD mapping projects.
- Regulatory friction:China's SAMR geospatial data security classifications restrict cross-border map transfers, compelling redundant infrastructure investment.
Strategic Opportunities
- Underpenetrated archipelago logistics:Indonesia's 17,000 islands present white space for maritime routing optimization platforms serving inter-island shipping.
- Technology convergence:Edge computing nodes deployed by telecom operators are converging with 5G positioning to enable sub-meter accuracy without dedicated GPS augmentation.
- Regulatory tailwind:South Korea's MFDS and transport ministry are mandating V2X communication standards that require HD map integration for highway certification.
Industry Challenges
- Geospatial data scientist scarcity:The specialized skill set combining remote sensing, machine learning, and cartographic standards faces acute shortage across the region's vendor base.
- Legacy system integration friction:Established fleet management platforms built on decade-old routing engines require costly middleware development to ingest real-time map updates.
- Multi-jurisdiction compliance timelines:Vendors must navigate simultaneous certification processes across MIIT, BIS, and METI frameworks with divergent documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Digital Maps Market |
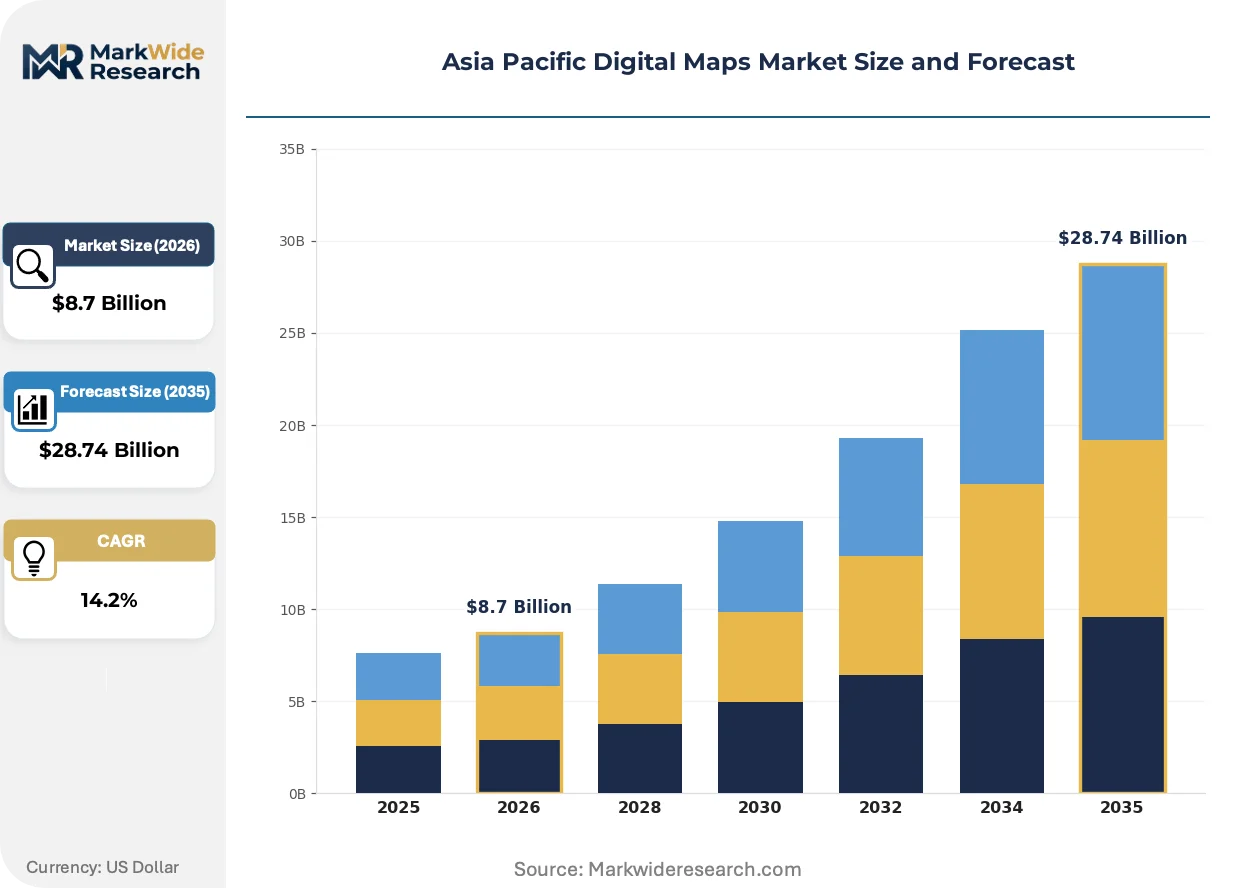
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Navigation, Geolocation Services, Fleet Management, Augmented Reality Technology: Satellite Imagery, Geographic Information System, 3D Mapping, Cloud-Based Maps End User: Transport Companies, Retail Chains, Government Agencies, Logistics Providers Distribution Channel: Online Platforms, Mobile Applications, SaaS, Hardware Integrations |
| Companies Covered | Google LLC, Apple Inc., Baidu, Inc., Tencent Holdings Ltd., TomTom NV, HERE, Esri, MapmyIndia, Maxar Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Digital Maps Market Strategic Shifts
Edge-native map rendering is displacing cloud-dependent architectures across latency-sensitive applications, while regulatory pressure on data residency accelerates investment in distributed compute infrastructure throughout the region.
Blockchain-based map verification protocols are decentralizing trust mechanisms for crowdsourced road condition updates. Indonesian and Vietnamese ride-hailing platforms are piloting these systems to reduce dependency on centralized quality control teams. The architecture is decentralizing verification costs across driver networks while compressing update latency from weeks to hours.
China's MIIT geospatial data security classifications are mandating localized server infrastructure for all foreign map providers. The regulation fragments operational architectures and raises capital requirements for cross-border service continuity. Automotive OEMs are responding by segmenting their Asia Pacific supply chains into China-specific and rest-of-region configurations.
Subscription-based API access is displacing perpetual licensing for enterprise map consumption. Logistics platforms in India and Southeast Asia are shifting from annual data purchases to metered usage models aligned with shipment volumes. This behavioral pivot is most visible among mid-sized 3PL providers seeking to align mapping costs with revenue cyclicality.
Asia Pacific Digital Maps Market Segmentation
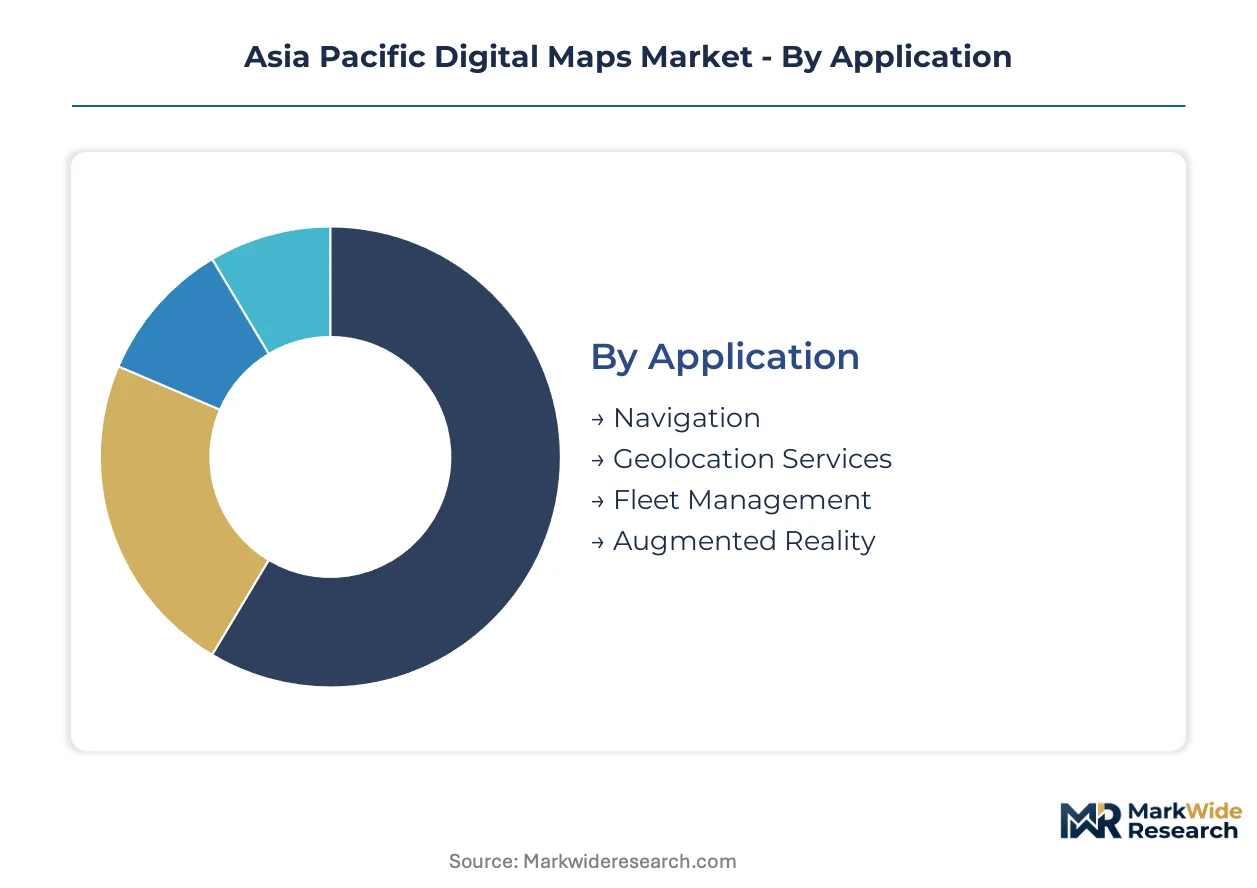
Segmentation reveals how capital requirements and regulatory exposure vary dramatically across the Asia Pacific digital maps value chain. Vendors must calibrate infrastructure investments differently for consumer-facing navigation versus automotive-grade HD mapping contracts.
Application:
Capital intensity peaks in applications requiring real-time sensor fusion and sub-meter accuracy validation.
- Navigation:Consumer routing engines aggregate probe data from millions of devices to generate predictive traffic models. Demand concentrates in India's urban mobility corridors where smart city tenders mandate interoperable real-time layers. India's CEA coordinates procurement standards that accelerate platform upgrades.
- Fleet Management:Commercial dispatch systems integrate telematics feeds with range-optimized routing for electrified logistics networks. Southeast Asian 3PL providers generate the most stable recurring revenue as they shift from perpetual licenses to metered API consumption.
- Geolocation Services:Point-of-interest databases power location-aware advertising and asset tracking across retail and insurance verticals.
- Augmented Reality:Spatial anchors for industrial maintenance and gaming overlays remain nascent but command premium pricing due to centimeter-accuracy requirements.
Most installed capacity flows through Navigation. Expansion is steepest in Fleet Management.
Technology:
Technology selection determines whether vendors build proprietary capture infrastructure or license third-party feeds.
- Cloud-Based Maps:Distributed compute architectures enable elastic scaling for enterprise clients while satisfying data residency mandates. China's MIIT and India's BIS impose divergent localization requirements that fragment operational architectures across the region.
- Satellite Imagery:Commercial constellation licensing provides foundational terrain data but exposes vendors to launch schedule volatility and orbital capacity constraints.
- Geographic Information System:Layered spatial databases serve government planning agencies and utility operators with cadastral and infrastructure mapping.
- 3D Mapping:LiDAR-derived point clouds support autonomous vehicle testing corridors in Japan and South Korea where METI and MFDS mandate HD map integration for certification.
Cloud-Based Maps absorb the majority of new vendor investment. 3D Mapping climbs the fastest as automotive OEMs accelerate validation programs.
End User:
End user type shapes contract structure, with government tenders favoring multi-year framework agreements while commercial clients prefer consumption-based pricing.
- Logistics Providers:Route optimization platforms serving Southeast Asian archipelago shipping generate demand for maritime-aware algorithms and charging station databases. Indonesia's 17,000 islands present white space for inter-island routing specialization.
- Government Agencies:Smart city mandates in India and Japan drive procurement of standardized mapping formats for urban mobility and disaster response coordination.
- Transport Companies:Public transit authorities require real-time passenger information systems with GTFS-integrated map layers.
- Retail Chains:Location intelligence for site selection and delivery zone optimization depends on demographic overlay accuracy.
Government Agencies anchor long-term contract value. Logistics Providers are gaining share fastest as electrification accelerates platform refresh cycles.
Distribution Channel:
Channel strategy determines whether vendors capture margin through direct subscription relationships or cede value to hardware and platform intermediaries.
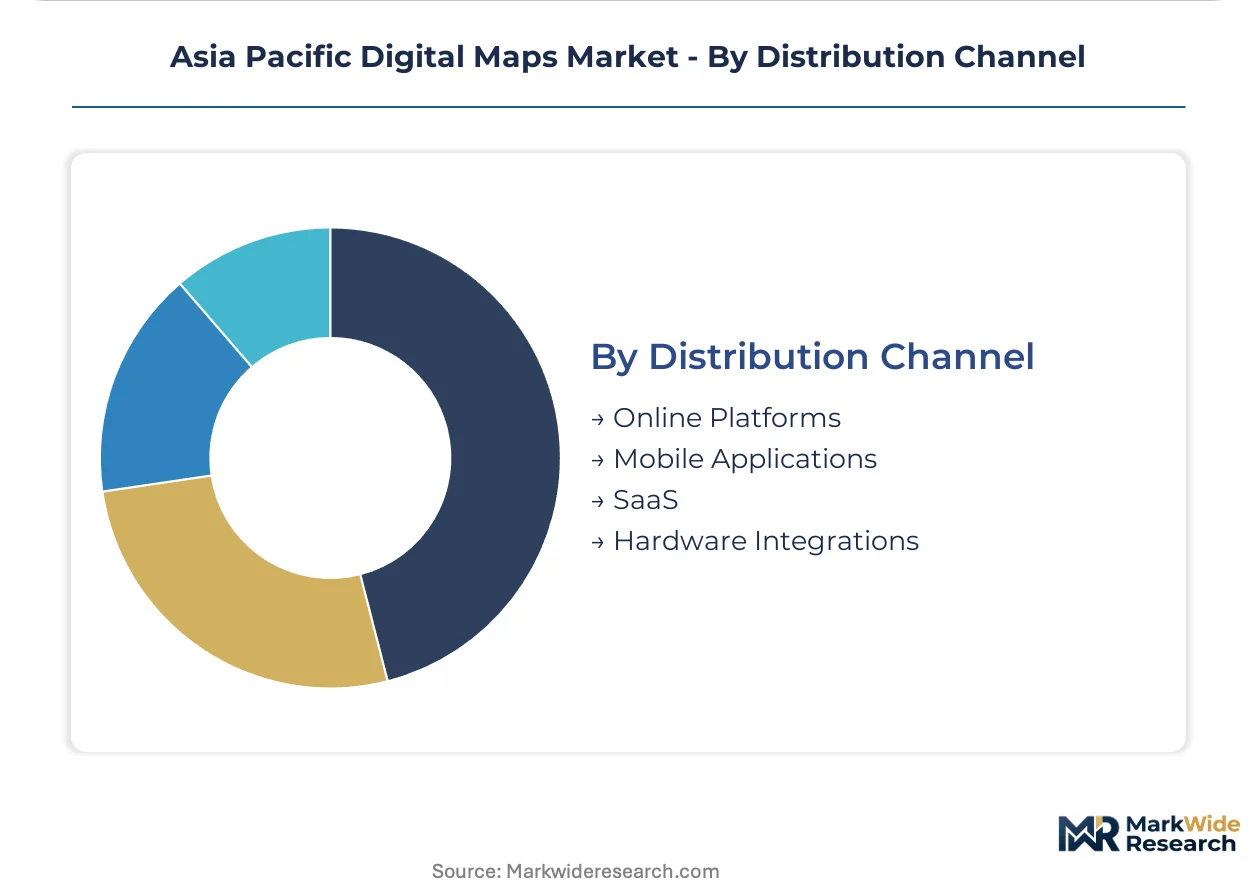
- SaaS:Metered API access allows mid-sized 3PL providers to align mapping costs with shipment cyclicality. Subscription revenue models are displacing perpetual licenses across India and Southeast Asia.
- Mobile Applications:Embedded consumer navigation depends on pre-installation agreements with smartphone OEMs and operating system providers.
- Online Platforms:Web-based visualization tools serve enterprise clients requiring browser-accessible spatial analytics without local software deployment.
- Hardware Integrations:Automotive-grade HD maps ship through tier-1 supplier contracts with Japanese and Korean OEMs, requiring ASIL-certified quality management systems.
SaaS channels capture the highest margin expansion. Hardware Integrations concentrate the largest individual contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT data localization mandates contrast with Japan's METI open-standard approach, illustrating divergent regulatory philosophies across the region. India's smart city procurement volumes exceed Southeast Asia's combined logistics platform investments. South Korea's V2X mandates create automotive-grade demand clusters absent in archipelago markets.
China
Domestic mobility super-apps drive consumption of real-time traffic layers and POI databases. SAMR geospatial security classifications restrict cross-border map transfers, compelling foreign vendors to localize server infrastructure. Shanghai and Beijing host validation corridors where HD mapping specialists test autonomous vehicle integration.
Japan
QZSS augmentation standards enable centimeter-level positioning for automotive OEM testing programs. METI promotes interoperability protocols that reduce vendor lock-in for public transit authorities. Nagoya and Tokyo metropolitan areas concentrate autonomous vehicle proving grounds requiring HD map certification.
India
Urban mobility tenders from smart city missions accelerate procurement of standardized routing platforms. CEA coordinates with BIS on interoperable mapping codes that mandate open-format compliance. Bengaluru and Mumbai generate concentrated demand from ride-hailing platforms and logistics aggregators.
South Korea
MFDS and transport ministry V2X mandates require HD map integration for highway certification standards. Domestic automotive OEMs source mapping data through tier-1 supplier contracts with ASIL quality requirements. Seoul Capital Area hosts edge computing deployments converging with 5G positioning infrastructure.
Indonesia
Archipelago logistics platforms seek maritime-aware routing algorithms for inter-island shipping optimization. Limited terrestrial mapping coverage creates white space for satellite-augmented navigation services. Jakarta and Surabaya anchor demand from 3PL providers electrifying commercial fleets across 17,000 islands.
Asia Pacific Digital Maps Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consumer navigation consolidating around platform-integrated providers while automotive-grade HD mapping fragments across tier-1 supplier channels. The vendor base organizes into three archetypes: cloud-native API platforms, sensor-capture infrastructure owners, and automotive certification specialists. Competitive moves concentrate on data residency compliance investments and edge computing node deployment.
Within the infrastructure-owner tier, Google LLC and Baidu, Inc. exemplify divergent geographic anchoring strategies—Mountain View-based and Beijing-based respectively—while HERE occupies a position bridging European automotive certification requirements with Asia Pacific OEM contracts. These three represent distinct regulatory compliance postures: one navigating China's SAMR localization mandates, one leveraging Street View capture networks, and one pursuing ASIL-certified quality management for tier-1 supplier integration.
| Leading Market Players |
|---|
| Google LLC |
| Apple Inc. |
| Baidu, Inc. |
| Tencent Holdings Ltd. |
| TomTom NV |
| HERE |
| Esri |
| MapmyIndia |
| Maxar Technologies |
| Others |
Value Chain & Pricing Dynamics
Geospatial data scientist scarcity in Bengaluru and Singapore widens labor-cost differentials between premium HD mapping specialists and economy-tier navigation providers. This talent concentration anchors pricing-tier spreads as vendors compete for machine learning engineers combining remote sensing expertise with cartographic standards compliance.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for automotive-grade HD mapping contracts. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-certified tier-1 supplier integrations from metered API access for mid-sized 3PL providers. Pricing pressure stems from satellite imagery licensing volatility as commercial constellation operators adjust orbital capacity. Fleet management platforms exhibit highest price sensitivity due to thin logistics margins, while automotive OEMs absorb premium tiers for certification compliance.
Supply Chain Analysis
ASIL quality certification and MIIT data localization mandates gate supplier participation across divergent national frameworks. High-precision LiDAR sensor production concentrates in Japan and Germany, while cloud compute nodes fragment across China, India, and South Korea to satisfy residency requirements. Raw material dependencies span commercial satellite imagery, edge computing hardware, and specialized photogrammetry equipment. Single-source vulnerability runs through Japanese LiDAR component specialists. Distribution runs through tier-1 automotive supplier contracts and direct SaaS API provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific digital maps constitute a late-cycle quality story as procurement shifts toward centimeter-accuracy HD mapping for autonomous vehicle certification corridors. Premium specification demand from Japan's METI QZSS standards and South Korea's MFDS V2X mandates separates viable vendors from commodity navigation providers.
For Market Incumbents: Extend data residency infrastructure across MIIT, BIS, and METI jurisdictions to defend automotive OEM contracts against localization-compliant challengers. Capture scarce geospatial data science talent in Bengaluru and Singapore through backward integration into university research partnerships. Certification investment in ASIL quality management systems remains the critical defensive lever as tier-1 supplier contracts concentrate among qualified vendors. For New Entrants and Emerging Players: Blockchain-based map verification protocols offer technology-first wedge into Indonesian and Vietnamese ride-hailing platforms seeking decentralized crowdsourced updates. Maritime-aware routing algorithms for Indonesia's 17,000 islands represent the most penetrable white space, with inter-island shipping logistics underserved by terrestrial mapping incumbents. Go-to-market through direct API integration with 3PL electrification platforms bypasses entrenched hardware supplier channels. For Investors and Strategic Acquirers: Valuations sit cheapest among cloud-native API platforms lacking automotive certification but possessing scalable edge computing architectures. Long-term viability hinges on regulatory compliance breadth across fragmented data sovereignty regimes. Target acquisition archetype: mid-tier SaaS providers with established India-Southeast Asia logistics relationships and nascent HD mapping R&D pipelines. Signal to watch: MIIT expansion of geospatial security classifications to additional data categories beyond current map transfer restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Node Deployment | Telecom operators in Seoul and Tokyo converge 5G positioning with sub-meter accuracy for latency-sensitive routing. |
| ASIL Quality Certification Investment | HD mapping specialists secure tier-1 supplier contracts with Japanese and Korean automotive OEMs. |
| Data Localization Infrastructure Buildout | Foreign vendors satisfy China's SAMR cross-border transfer restrictions through redundant server replication. |
| Blockchain Verification Protocol Pilot | Indonesian ride-hailing platforms decentralize crowdsourced road condition validation across driver networks. |
| Maritime Routing Algorithm Development | Specialized platforms capture inter-island shipping optimization demand across Indonesia's archipelago logistics. |
Study Parameters
Direct dialogue with fleet management platform CTOs, automotive OEM procurement leads, telecom edge computing strategists, and geospatial data science directors grounded qualitative findings. Secondary validation drew from MIIT regulatory filings, METI QZSS standard documentation, BIS interoperability codes, commercial satellite operator capacity disclosures, and hyperscaler capex reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level projections across navigation, fleet management, geolocation services, and augmented reality applications combined with technology splits between cloud-based maps, satellite imagery, GIS, and 3D mapping. End-user disaggregation by logistics providers, government agencies, transport companies, and retail chains informed demand-side calibration. CAGRs derived from regression analysis against smart city investment flows, fleet electrification penetration curves, and autonomous vehicle testing corridor expansion.
The model holds under stable data sovereignty enforcement and continued fleet electrification capex; deviation in MIIT security classification scope or QZSS augmentation adoption timelines would shift trajectory. Forecasts embed assumptions regarding satellite launch schedules and LiDAR sensor production capacity. A model refresh is warranted upon material change in automotive OEM HD mapping certification requirements or blockchain verification protocol adoption rates across Southeast Asian logistics platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Business Mapping Software Market