
 India Satellite Imagery Services Market | 2026-2036
India Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Satellite Imagery Services Market Insights
ISRO's launch cadence from Sriharikota is pivoting domestic imagery supply toward higher revisit frequencies. SatSure Analytics India Pvt Ltd leverages proprietary crop-risk models to anchor its position in agricultural underwriting. Maxar Technologies sustains competitive advantage through its sub-meter optical archive spanning Indian territory. Pixxel Space Technologies Private Limited differentiates via hyperspectral constellation plans tuned for mineral and soil composition mapping.
Satellite imagery services encompass the acquisition, processing, and analytic transformation of Earth observation data captured by orbiting sensors, with spatial resolutions ranging from 30-meter multispectral to sub-meter panchromatic and spectral bands spanning visible through shortwave infrared wavelengths. These services convert raw orbital captures into decision-ready geospatial intelligence for infrastructure planning, crop health assessment, and territorial surveillance. Agriculture dominates application demand as insurers and commodity traders require plot-level yield visibility, while defense end users drive premium pricing through classified thermal and synthetic aperture radar tasking. Optical technology leads current revenue owing to heritage sensor maturity, though hyperspectral capabilities are capturing margin pools in mining and environmental compliance verticals.
The Department of Space enforces remote sensing data distribution policies through the National Remote Sensing Centre, while the Ministry of Defence regulates geospatial outputs under the Geospatial Information Regulation Bill framework. BIS certification requirements for surveying accuracy and ISRO's standardized data product formats shape procurement specifications for government contracts. Stakeholders must monitor Antrix Corporation's commercial pricing shifts and state-level smart city geospatial tenders as signals of public-sector demand velocity.
Market Dynamics
ISRO's liberalized remote sensing data norms are compressing the cost curve for Earth observation analytics while concentrating procurement authority under state-level geospatial tenders in Maharashtra and Gujarat. This policy recalibration is redistributing margin pools from raw imagery suppliers toward vertical-specific analytics providers.
Growth Catalysts
- National Geospatial Policy:State governments in Maharashtra and Gujarat are expanding precision agriculture adoption, creating sustained demand pull for plot-level crop monitoring services.
- Hyperspectral analytics:Mineral exploration applications in Rajasthan are concentrating investment around defense and natural resource monitoring verticals with premium pricing tolerance.
- Sriharikota launch cadence:Higher revisit frequencies from domestic orbital assets are reducing dependency on foreign satellite operators for time-critical tasking.
Market Restraints
- Ground segment infrastructure:Limited downlink station density in the Northeast and island territories creates latency bottlenecks for real-time defense applications.
- Data localization requirements:Geospatial Information Regulation Bill compliance adds processing overhead for foreign-owned analytics platforms serving Indian government contracts.
- Optical sensor weather dependency:Monsoon cloud cover across the Gangetic plain degrades usable capture windows for agricultural underwriting models.
Strategic Opportunities
- Smart city geospatial tenders:Urban local bodies in tier-2 municipalities are issuing bundled surveying and monitoring contracts with multi-year visibility.
- Synthetic aperture radar convergence:All-weather imaging capability is penetrating infrastructure monitoring applications where optical sensors face seasonal constraints.
- Sub-regional underpenetration:Odisha and Chhattisgarh exhibit minimal precision agriculture adoption relative to their cropped area, representing white space for yield prediction services.
Industry Challenges
- Photogrammetry talent scarcity:Indian technical institutes produce insufficient graduates with combined remote sensing and machine learning competencies to match hiring velocity.
- BIS certification timelines:Surveying accuracy standards approval processes extend 14-18 months, delaying product launches for domestic startups.
- Legacy system integration:State agriculture departments operate on fragmented databases that resist API-based ingestion of satellite-derived crop health indices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Satellite Imagery Services Market |
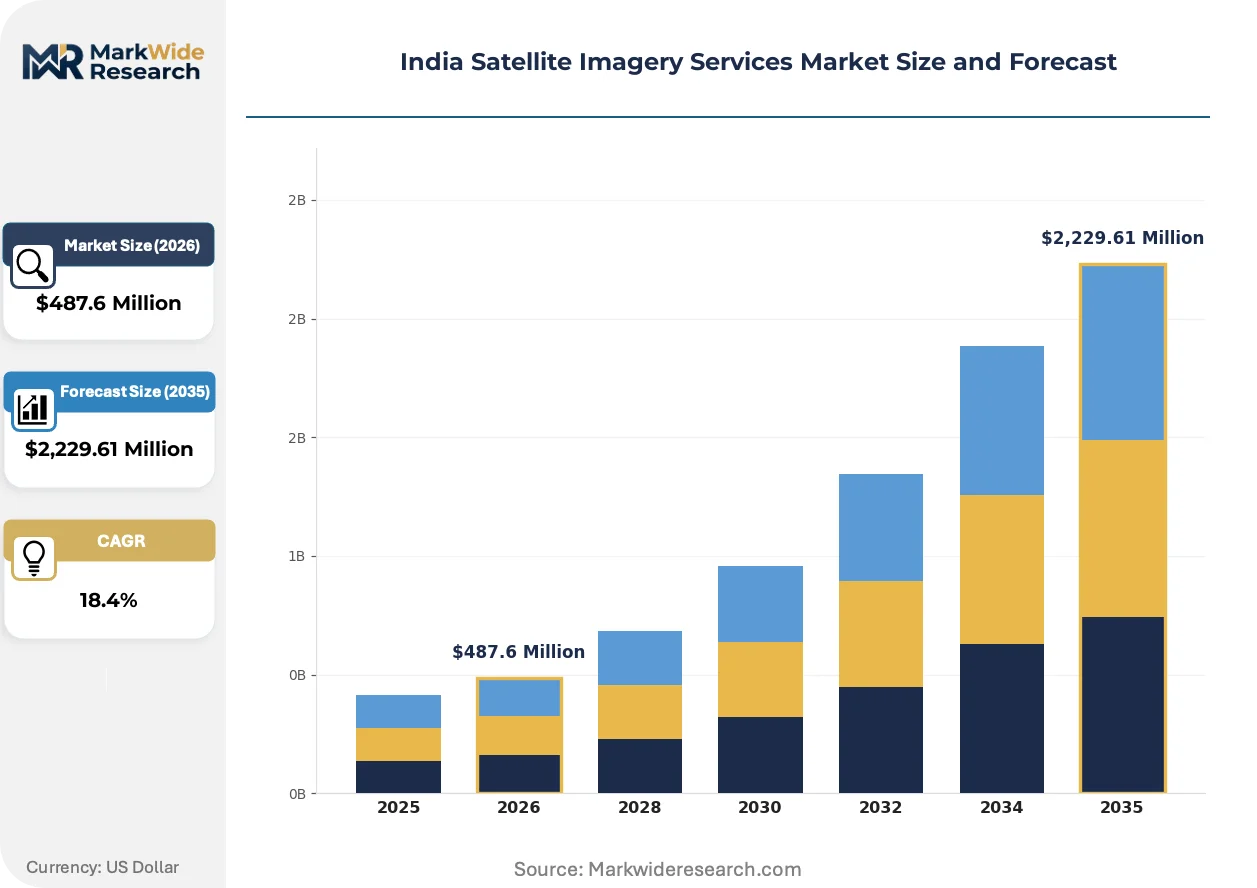
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Urban Planning, Disaster Management, Environmental Monitoring End User: Government, Defense, Retail, Energy Technology: Optical, Radar, Hyperspectral, LiDAR Service Type: Data Processing, Data Analysis, Custom Solutions, Consulting |
| Companies Covered | SatSure Analytics India Pvt Ltd, Maxar Technologies, Antrix Corporation Limited, Genesys International Corporation Ltd, Hexagon AB, RMSI Private Limited, MapmyIndia, Pixxel Space Technologies Private Limited, Airbus SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Satellite Imagery Services Market Trends and Innovations
Edge computing architectures are migrating processing workloads from centralized cloud facilities toward orbital and ground-segment nodes. This infrastructure shift is compressing latency for time-sensitive applications while altering competitive dynamics between hardware and software value capture.
Small satellite constellations are decentralizing the supply of high-revisit imagery across Indian territory. Agri-insurers and commodity traders are adopting daily-capture subscriptions at accelerating rates. This technology diffusion is fragmenting procurement authority away from national mapping agencies toward departmental end-users with discrete budgets.
The Geospatial Information Regulation Bill is formalizing classified versus unclassified data handling protocols for defense outputs. Foreign platform providers face compliance recertification requirements for government contract eligibility. Defense end-users are responding by bifurcating supplier relationships between domestic cleared entities and offshore analytics partners.
Subscription-based licensing is displacing perpetual purchase models across state government procurement. Annual recurring revenue structures are penetrating the public sector channel where capital budgets previously dominated. This shift is most visible in Karnataka and Telangana smart city authorities restructuring geospatial tenders as multi-year service agreements.
India Satellite Imagery Services Market Segmentation
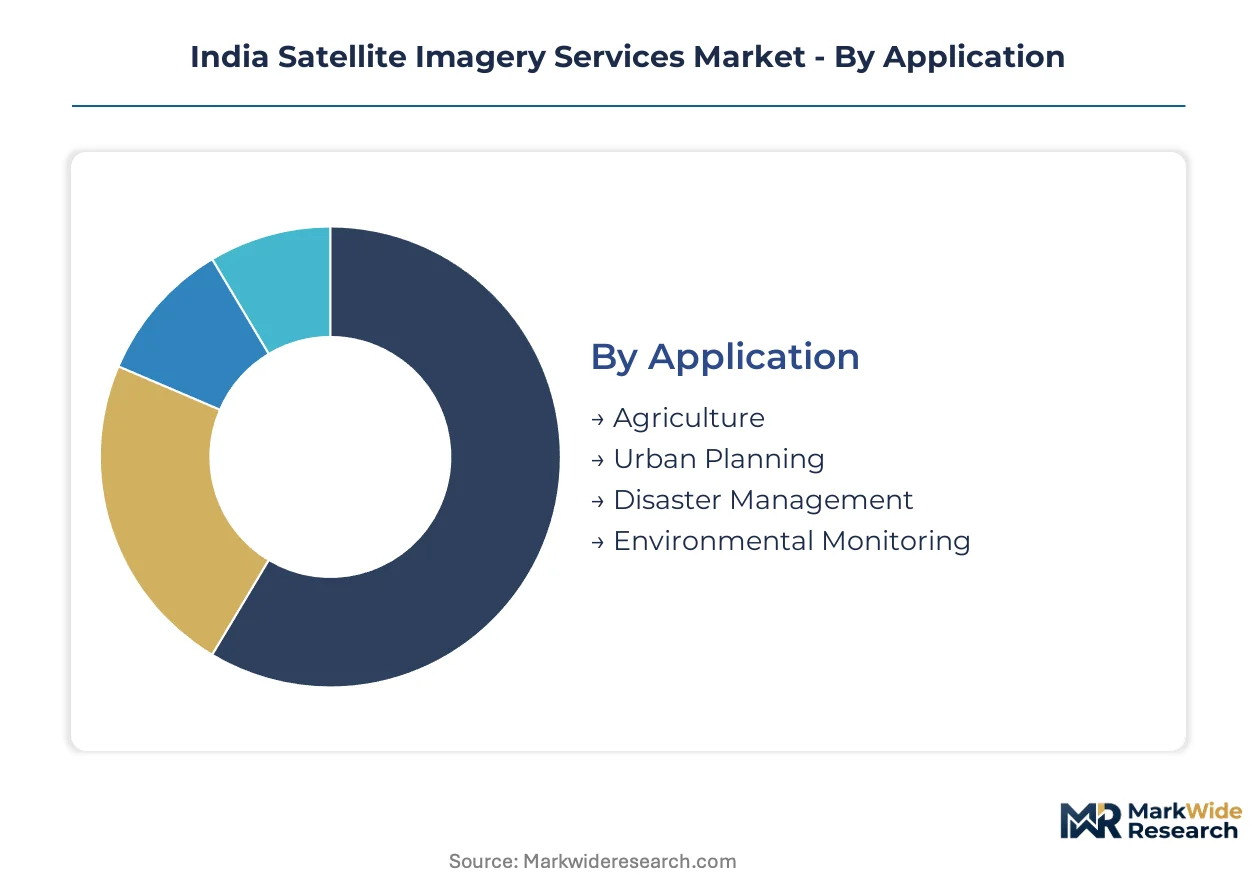
Segmentation of the India satellite imagery services market reveals how procurement authority fragments across state-level tenders, defense classified tasking, and commercial analytics subscriptions. Understanding these divisions exposes where margin pools concentrate and which technology-service combinations command premium pricing.
Application:
Agriculture dominates volume throughput while defense-adjacent verticals capture premium margins per square kilometer tasked.
- Agriculture:Plot-level crop health monitoring and yield prediction models drive subscription volumes from insurers and commodity traders in Maharashtra and Gujarat. Monsoon cloud cover constrains optical capture windows, pushing demand toward radar-augmented service bundles.
- Urban Planning:Smart city authorities in tier-2 municipalities issue multi-year surveying and change-detection contracts. Karnataka and Telangana tender structures favor annual recurring revenue over capital purchases.
- Disaster Management:Real-time flood and cyclone response requires sub-hourly revisit frequencies. Limited ground station density in the Northeast creates downlink bottlenecks for emergency tasking.
- Environmental Monitoring:Mining compliance and forest cover verification in Rajasthan and Odisha leverage hyperspectral signatures for soil and vegetation composition mapping.
Mature deployment sits with Agriculture. Newer deployment is concentrated in Environmental Monitoring.
End User:
Government contracts anchor baseline revenue while defense and energy verticals tolerate premium pricing for classified or time-critical outputs.
- Government:State agriculture departments and urban local bodies procure through standardized ISRO data formats and BIS-certified accuracy specifications. Procurement velocity tracks National Geospatial Policy implementation timelines.
- Defense:Classified thermal and synthetic aperture radar tasking operates under Geospatial Information Regulation Bill protocols. Domestic cleared entities capture onshore processing mandates.
- Retail:Agri-insurers and commodity trading desks purchase daily-capture subscriptions at accelerating rates. Fragmented procurement authority shifts toward departmental end-users with discrete operational budgets.
- Energy:Transmission corridor monitoring and solar site prospecting demand all-weather imaging capabilities where optical sensors face seasonal constraints.
Procurement maturity clusters around Government. Margin expansion is climbing the fastest in Defense.
Technology:
Optical heritage sensors dominate current revenue while hyperspectral and radar capabilities capture emerging margin pools.
- Optical:Sub-meter panchromatic and multispectral archives spanning visible through shortwave infrared wavelengths anchor commercial offerings. Weather dependency across the Gangetic plain degrades usable capture windows during monsoon months.
- Radar:Synthetic aperture radar penetrates cloud cover and darkness for infrastructure monitoring applications. All-weather capability is displacing optical-only contracts in energy and disaster response verticals.
- Hyperspectral:Mineral exploration in Rajasthan and soil composition mapping for precision agriculture require narrow spectral band discrimination. ISRO's liberalized remote sensing data norms compress cost curves for analytics providers.
- LiDAR:Elevation modeling for urban planning and flood simulation demands high-density point cloud generation. BIS certification timelines for surveying accuracy standards delay product launches for domestic startups.
Technology maturity centers on Optical. Capability investment is expanding most quickly in Hyperspectral.
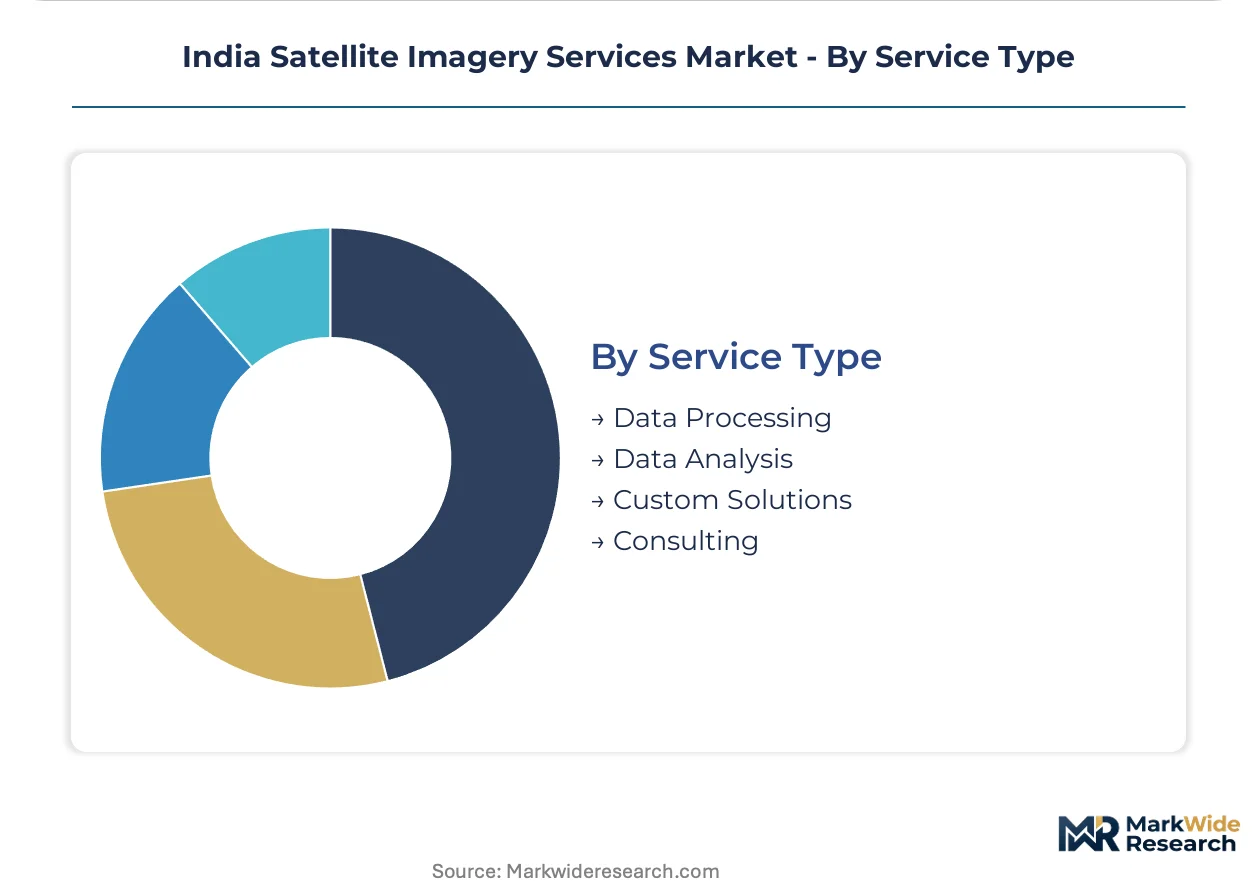
Service Type:
Raw data processing commands commodity pricing while vertical-specific analytics and consulting capture differentiated margins.
- Data Processing:Orthorectification, atmospheric correction, and mosaicking of orbital captures into standardized product formats. ISRO's National Remote Sensing Centre enforces distribution policies that shape baseline service economics.
- Data Analysis:Crop-risk models and mineral classification algorithms transform raw imagery into decision-ready intelligence. SatSure Analytics anchors agricultural underwriting through proprietary analytics.
- Custom Solutions:API-based integration of satellite-derived indices into state agriculture department legacy systems faces fragmentation resistance. Machine learning competencies remain scarce in Indian technical institute pipelines.
- Consulting:Geospatial strategy and regulatory compliance advisory for foreign-owned platforms navigating Geospatial Information Regulation Bill recertification requirements. Defense contract eligibility bifurcates between domestic cleared entities and offshore partners.
Service maturity concentrates in Data Processing. Value capture is gaining share fastest in Data Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rajasthan's mineral belt and the Gangetic agricultural corridor anchor spatial data demand across Indian territory. State-level procurement patterns concentrate service consumption in western and southern sub-regions where precision agriculture and urban digitization programs operate at scale.
Maharashtra
Plot-level crop monitoring subscriptions from agri-insurers drive volume throughput in the Marathwada and Vidarbha belts. The state's National Geospatial Policy implementation timeline shapes tender velocity for smart city authorities in Pune and Nagpur. Mumbai's commodity trading desks anchor commercial demand for daily-capture agricultural intelligence.
Gujarat
Cotton and groundnut precision agriculture adoption concentrates procurement authority in the Saurashtra peninsula. BIS certification requirements for surveying accuracy filter vendor eligibility for state infrastructure contracts. The Gujarat International Finance Tec-City cluster houses downstream analytics operations serving regional underwriting demand.
Karnataka
Silicon Valley of India technology transfer accelerates machine learning competency development for remote sensing applications. The state's smart city tender restructuring favors multi-year service agreements over capital purchases in Bengaluru and Mysuru. ISRO's National Remote Sensing Centre data distribution policies standardize procurement specifications for state agriculture departments.
Rajasthan
Hyperspectral mineral exploration applications in the Aravalli range command premium pricing tolerance from mining compliance operators. The Geospatial Information Regulation Bill bifurcates supplier relationships between domestic cleared entities and offshore analytics partners in Jaipur's industrial corridor. Zinc and copper deposit mapping drives spectral band discrimination requirements.
Telangana
Hyderabad's defense research ecosystem generates classified thermal and synthetic aperture radar tasking demand. Annual recurring revenue structures penetrate municipal geospatial procurement where capital budgets previously dominated. The state's grid modernization program requires transmission corridor monitoring with all-weather imaging capabilities.
India Satellite Imagery Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hyperspectral specialization and edge-computing architectures. The vendor base stratifies across three maturity tiers: heritage optical archive operators, domestic analytics platforms with proprietary crop-risk models, and constellation-stage startups targeting mineral composition mapping. Three strategic archetypes dominate: satellite operators with sub-meter resolution heritage, vertical-specific analytics providers with state-level tender relationships, and hardware-software integrated platforms. Competitive moves concentrate on API-based legacy system integration and BIS certification acceleration for surveying accuracy standards.
Within the domestic analytics tier, SatSure Analytics India Pvt Ltd and RMSI Private Limited exemplify platforms with proprietary agricultural underwriting capabilities. Pixxel Space Technologies Private Limited occupies the emerging constellation-developer position. Maxar Technologies and Airbus SE represent heritage archive operators with sub-meter optical coverage spanning Indian territory. Antrix Corporation Limited anchors the state-affiliated commercial channel through ISRO data distribution mandates.
| Leading Market Players |
|---|
| SatSure Analytics India Pvt Ltd |
| Maxar Technologies |
| Antrix Corporation Limited |
| Genesys International Corporation Ltd |
| Hexagon AB |
| RMSI Private Limited |
| MapmyIndia |
| Pixxel Space Technologies Private Limited |
| Airbus SE |
| Others |
Pricing and Supply Chain Analysis
ISRO's Geospatial Information Regulation Bill compliance mandates gate both qualified supply and premium-tier pricing access, bifurcating vendor eligibility between domestic cleared entities and offshore analytics partners while compressing margins for non-compliant foreign platforms.
Pricing Analysis
Service-bundling separates raw imagery provisioning from vertical-specific analytics, with unbundled data processing commanding commodity rates while integrated crop-risk models and mineral classification algorithms capture differentiated premiums. Price differentiation rests on BIS certification grade and API-based legacy system integration complexity. Cost compression in raw data tiers is intensifying because ISRO's liberalized remote sensing data norms expand supply. Government agriculture departments exhibit highest price sensitivity, while defense thermal and SAR tasking tolerates premium pricing.
Supply Chain Analysis
BIS certification timelines and DGFT data localization requirements filter vendor participation, creating 14-18 month qualification gates that advantage incumbent domestic platforms. Sensor hardware draws from the United States, France, and domestic ISRO production lines. Ground segment dependencies include downlink stations, edge computing nodes, and photogrammetry talent pipelines. Single-source vulnerability concentrates in foreign-owned optical archives spanning Indian territory. Distribution runs through Antrix Corporation's commercial channel and state-level geospatial tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photogrammetry talent scarcity props pricing power across analytics tiers, constraining hiring velocity for machine learning-augmented remote sensing competencies.
For Market Incumbents: Lock in multi-year smart city service agreements in Karnataka and Telangana before subscription-based licensing fully displaces capital purchases. Accelerate BIS certification for surveying accuracy standards to outpace constellation-stage startups. Vertical integration into edge computing architectures defends margin pools against hardware-software disaggregation. For New Entrants and Emerging Players: Enter via Odisha and Chhattisgarh's underpenetrated precision agriculture corridors, where minimal yield prediction adoption relative to cropped area creates white space. Target mineral exploration analytics in Rajasthan's Aravalli belt, where hyperspectral capabilities command premium tolerance. Lead with API-first integration to bypass state agriculture department legacy system fragmentation. For Investors and Strategic Acquirers: Antrix Corporation pricing shifts are the leading indicator that public-sector demand velocity is accelerating, signaling entry timing for downstream analytics platforms. Long-term viability favors domestic cleared entities with Geospatial Information Regulation Bill compliance and proprietary crop-risk model IP. Watch state-level tender restructuring from capital purchases to annual recurring revenue as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Constellation Deployment | Pixxel Space Technologies' mineral mapping capability captures Rajasthan mining compliance premiums. |
| API-Based Legacy System Integration | SatSure Analytics bypasses state agriculture department fragmentation through proprietary crop-risk model embedding. |
| BIS Certification Acceleration | Domestic startups reduce 14-18 month surveying accuracy approval timelines to outpace foreign competitors. |
| Edge Computing Architecture Migration | Orbital and ground-segment processing nodes compress latency for defense time-critical tasking applications. |
| Multi-Year Service Agreement Restructuring | Karnataka and Telangana smart city authorities displace capital budgets with subscription-based geospatial procurement. |
Research Methodology
Document review covered ISRO annual reports, National Remote Sensing Centre data distribution policies, and state government geospatial tender documents, complemented by interviews with satellite imagery procurement officers at state agriculture departments, defense research establishment program managers, agri-insurer underwriting leads, and smart city authority GIS directors. Secondary validation drew from Antrix Corporation commercial pricing disclosures, BIS certification standards documentation, and Geospatial Information Regulation Bill compliance frameworks. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level projections were produced for application verticals, end-user categories, sensor technology types, and service tiers across the modeling period. CAGRs were derived from regression analysis against ISRO launch cadence, state-level National Geospatial Policy implementation timelines, and precision agriculture adoption curves. Industry-specific forecast inputs included monsoon cloud cover degradation coefficients for optical capture windows and synthetic aperture radar convergence penetration rates in infrastructure monitoring.
Revisions become necessary when ISRO further liberalizes remote sensing data norms, when BIS certification timelines materially shift, or when state-level smart city tender structures change procurement authority distribution. Forecasts reflect assumptions around Sriharikota launch cadence maintenance and hyperspectral analytics cost curve compression. A model refresh is warranted upon material change in Geospatial Information Regulation Bill enforcement protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market