
 Brazil Location Based Services Market | 2026-2036
Brazil Location Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Location Based Services Market Insights
Cloud-native positioning middleware is rebalancing cost structures for LBS deployments across Brazilian enterprises. Google LLC leverages its mapping data corpus to anchor advertising and navigation layers within the domestic digital ecosystem. Ericsson Inc sustains network-side positioning capabilities through its 5G infrastructure partnerships with local carriers. IBM Corporation competes on enterprise-grade location analytics platforms serving retail and transportation verticals.
Location Based Services encompass spatial computing systems that determine, transmit, and act upon geographic coordinates through GNSS receivers, cellular triangulation, and proximity sensors operating at sub-10-meter accuracy thresholds. These systems enable real-time asset tracking, geomarketing, and route optimization across commercial and public-sector workflows. GPS-based navigation retains the largest revenue share among technology segments, while Bluetooth proximity layers capture expanding share in retail personalization and indoor wayfinding. Fleet management applications lead the application category due to Brazil's extensive road freight network, whereas smart cities deployment accelerates with municipal digitization programs in southeastern state capitals.
ANATEL governs spectrum allocation and telecommunications interoperability standards that directly shape LBS accuracy and coverage obligations for operators. LGPD compliance requirements impose geolocation data governance rules on platform providers, while INCRA's territorial mapping frameworks influence rural asset-tracking service design. Stakeholders must weigh the trade-off between centralized cloud processing latency and edge-computing investments as real-time use cases multiply across transportation and healthcare segments.
Market Dynamics
ANATEL's 5G spectrum auctions have triggered infrastructure densification that compresses positioning latency thresholds for real-time LBS applications across Brazilian logistics corridors.
Growth Catalysts
- Fleet digitization mandates:Logistics operators deploy GNSS-integrated telematics to optimize route efficiency across Brazil's 1.5 million kilometer road network. ANATEL's interoperability standards accelerate hardware refresh cycles.
- LGPD compliance frameworks:Brazil's data protection law creates structured governance requirements for geolocation platforms, pushing enterprises toward certified middleware providers with auditable data lineage.
- São Paulo metropolitan convergence:Retail and mobility platforms cluster in the southeastern corridor, generating network effects that reduce per-deployment infrastructure costs for adjacent LBS services.
Market Restraints
- Semiconductor import dependency:GNSS receiver chipsets and Bluetooth SoCs concentrate in East Asian foundries, exposing Brazilian integrators to currency volatility and extended lead times.
- Rural coverage gaps:Cellular triangulation fails in the Amazon basin and central-west agricultural zones, limiting asset-tracking service viability outside coastal infrastructure belts.
- LGPD enforcement friction:Brazil's data protection authority imposes consent-layer complexity on proximity marketing deployments, increasing compliance overhead for retail personalization applications.
Strategic Opportunities
- Northeast urban corridors:Recife and Salvador municipal digitization programs lag São Paulo by 36-48 months, creating first-mover windows for smart city positioning infrastructure.
- Healthcare emergency response:Ambulance fleet operators in Minas Gerais pilot sub-meter accuracy routing to compress emergency arrival intervals, opening clinical-grade LBS specifications.
- Edge-cloud convergence:Hybrid architectures that process positioning data at cell tower proximity reduce round-trip latency for autonomous vehicle pilot zones in Campinas.
Industry Challenges
- Embedded systems engineering scarcity:Brazilian universities produce fewer than 2,000 annual graduates with RF signal processing and GNSS firmware competencies, constraining localization R&D pipelines.
- Legacy telematics integration:Freight operators running 2016-2019 hardware generations face CAN bus protocol mismatches when upgrading to cloud-native positioning middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Location Based Services Market |
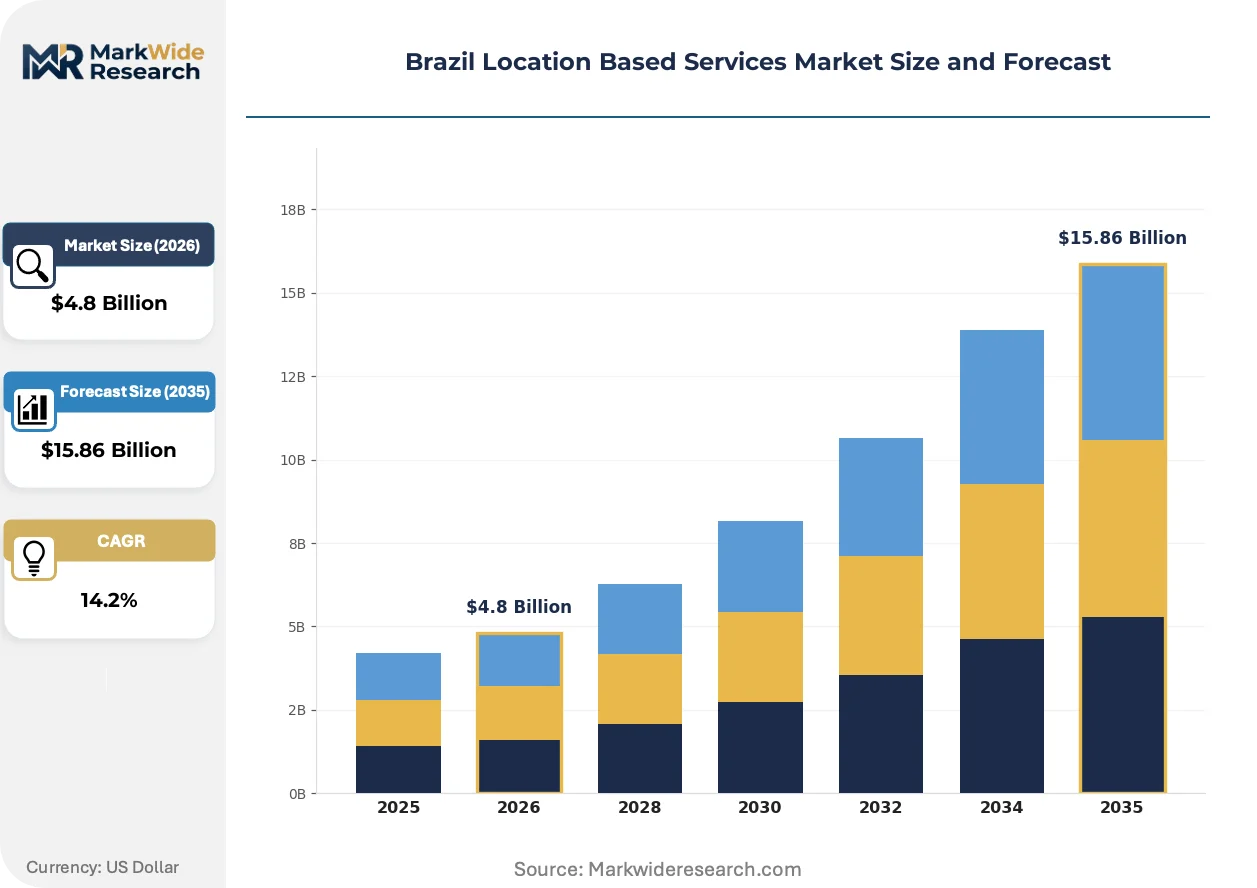
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Navigation, Tracking, Location Analytics, Advertising Technology: GPS, Wi-Fi, Bluetooth, RFID End User: Retailers, Transportation, Healthcare, Entertainment Application: Fleet Management, Smart Cities, Personalization, Tourism |
| Companies Covered | Maxar Technologies, Ericsson Inc, Google LLC, Movile, GL Communications Inc, IBM Corporation, Esri Technologies Ltd, Uber Technologies Inc, Cisco Systems Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Location Based Services Market Trends and Innovations
Cloud-native positioning middleware is compressing deployment timelines while regulatory pressure on data sovereignty reshapes architectural choices for Brazilian platform operators.
Ultra-wideband (UWB) proximity sensing is rewriting indoor positioning economics for Brazilian retail environments. Shopping mall operators in São Paulo and Rio de Janeiro deploy UWB anchor networks to enable sub-30-centimeter wayfinding accuracy. Department stores leverage this infrastructure for aisle-level promotional targeting, collapsing the cost gap between GPS outdoor navigation and indoor location services.
ANATEL's 5G standalone specifications impose stricter positioning accuracy obligations on carrier infrastructure than prior LTE generations. Network operators must deliver horizontal positioning within 3 meters for 80 percent of measurements in dense urban environments. This mandate accelerates multi-constellation GNSS receiver adoption in Brazilian handsets and IoT modules, compressing the addressable market for single-GPS legacy chipsets.
Freight procurement patterns are fragmenting across asset-light digital brokers. Small trucking fleets in Paraná and Santa Catarina bypass traditional telematics providers, subscribing instead to API-first location platforms that aggregate positioning data from driver smartphones. This channel shift erodes hardware-centric revenue pools while expanding addressable volume for software-only LBS vendors serving the long tail of Brazilian road transport.
Brazil Location Based Services Market Segmentation
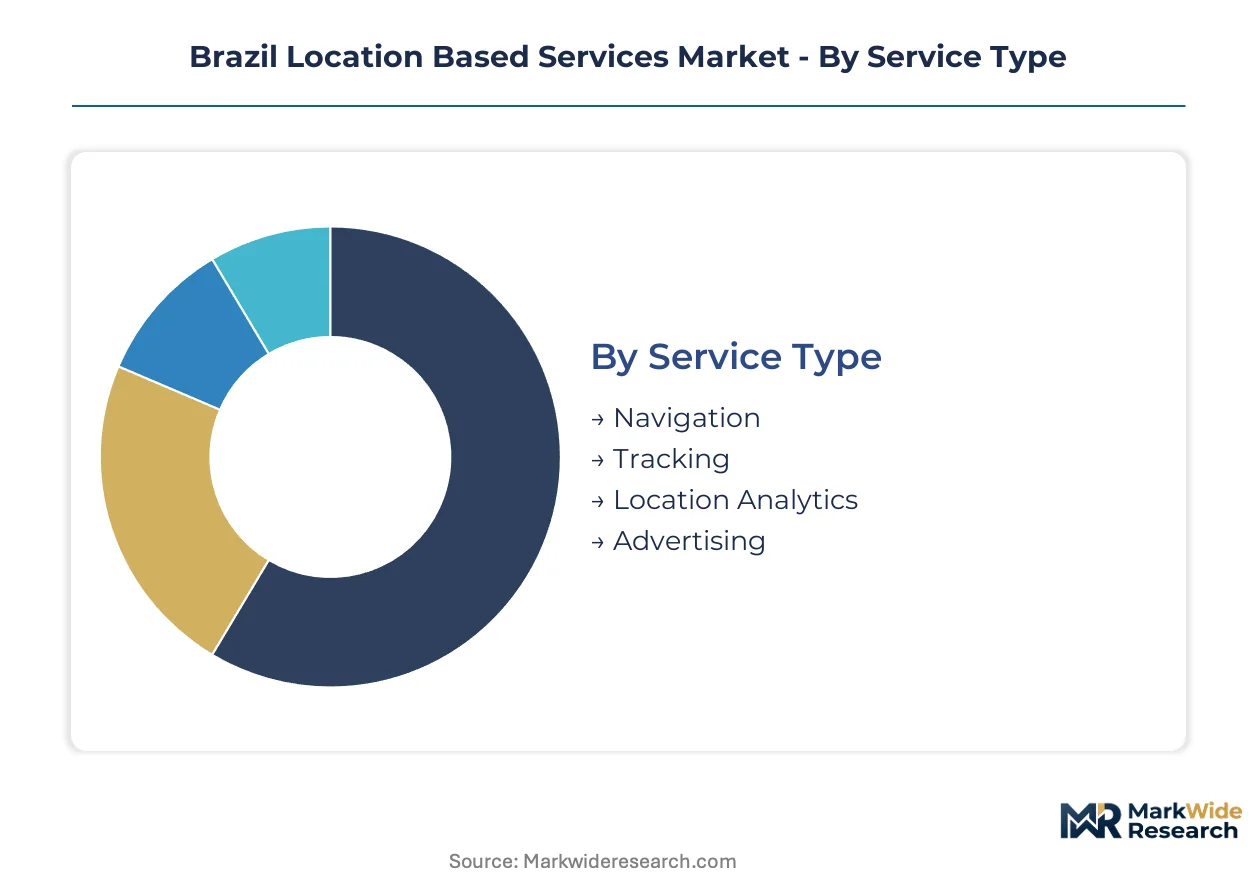
Brazil's LBS market fragments across service architectures, positioning technologies, and vertical workflows. Understanding these segment boundaries clarifies where infrastructure investments concentrate versus where platform margins compress.
Service Type:
Volume deployments cluster in commoditized navigation layers, while premium pricing attaches to analytics and advertising where data granularity commands higher rates.
- Navigation:Turn-by-turn routing dominates consumer smartphone penetration across São Paulo and Rio de Janeiro metropolitan zones. Fleet operators in Paraná's agribusiness corridors demand offline-capable navigation to circumvent cellular dead zones.
- Tracking:Real-time asset monitoring anchors logistics digitization mandates from ANATEL's interoperability frameworks. Cold chain operators in Santa Catarina deploy temperature-integrated tracking to satisfy export compliance requirements.
- Location Analytics:Footfall pattern analysis drives retail site selection in expanding northeastern corridors.
- Advertising:Proximity-triggered promotions face LGPD consent-layer friction that elevates compliance costs.
Mature deployment sits with Navigation. Newer deployment is concentrated in Location Analytics.
Technology:
Cost tiering separates high-precision GNSS receivers from proximity sensing layers that undercut hardware requirements.
- GPS:Multi-constellation receivers now dominate Brazilian handset and IoT module specifications following ANATEL's 5G standalone accuracy mandates. Single-GPS legacy chipsets retreat to ultra-low-cost asset tags in informal transport sectors.
- Bluetooth:Low-energy beacons enable sub-meter indoor positioning for shopping mall operators in São Paulo without infrastructure overhaul. Battery-constrained deployment cycles create recurring hardware refresh revenue.
- Wi-Fi:Fingerprinting approaches serve dense urban cores where AP density supports trilateration.
- RFID:Passive tags persist in yard management and high-value cargo authentication workflows.
Established infrastructure sits with GPS. Expanding most quickly is Bluetooth.
End User:
Customer sophistication varies sharply between data-native platforms and legacy verticals confronting digitization pressure.
- Transportation:Road freight operators across Brazil's 1.5 million kilometer network anchor telematics subscription volumes. ANATEL's fleet digitization mandates accelerate hardware refresh toward cloud-native middleware.
- Retailers:Department stores in southeastern corridors pilot aisle-level personalization using UWB anchor investments. LGPD enforcement friction elevates consent management platform costs.
- Healthcare:Ambulance fleet operators in Minas Gerais trial sub-meter routing for emergency response compression.
- Entertainment:Stadium and venue operators deploy crowd flow optimization for safety compliance.
Deep integration sits with Transportation. Steepest expansion trajectory is Healthcare.
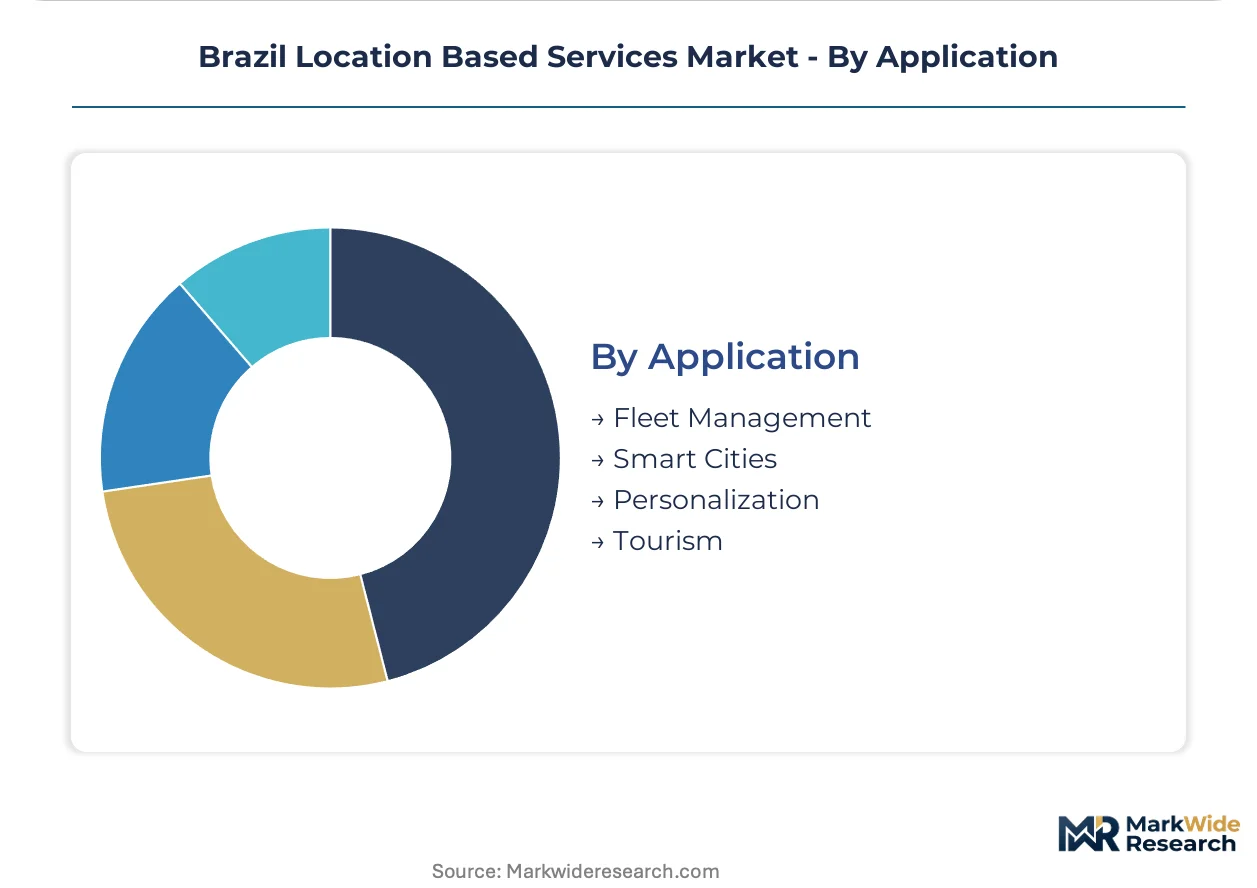
Application:
Margin profiles diverge between operational efficiency tools and citizen-facing municipal deployments with procurement complexity.
- Fleet Management:GNSS-integrated telematics optimize route efficiency across Brazil's extensive road freight network. API-first platforms now aggregate smartphone positioning from small trucking fleets, displacing hardware-centric providers.
- Smart Cities:Municipal digitization programs in Recife and Salvador lag São Paulo by 36-48 months, creating infrastructure deployment windows. Edge-cloud convergence pilots in Campinas target autonomous vehicle latency requirements.
- Personalization:Retail proximity marketing faces LGPD consent overhead that constrains campaign frequency.
- Tourism:Wayfinding applications concentrate in Rio de Janeiro and Bahia coastal corridors.
Scaled deployment sits with Fleet Management. Gaining share fastest is Smart Cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for location-based services concentrates in Brazil's southeastern corridor, where São Paulo's metropolitan density generates network effects that reduce per-deployment infrastructure costs for adjacent services.
São Paulo
Retail and mobility platforms cluster in the metropolitan corridor, driving cloud-native positioning middleware adoption among logistics operators. ANATEL's 5G spectrum auctions enable denser positioning infrastructure deployment across the state. Shopping mall operators in São Paulo deploy UWB anchor networks to enable sub-30-centimeter wayfinding accuracy for aisle-level promotional targeting.
Minas Gerais
Ambulance fleet operators trial sub-meter accuracy routing to compress emergency arrival intervals, opening clinical-grade LBS specifications. LGPD compliance frameworks push healthcare providers toward certified middleware providers with auditable data lineage. Belo Horizonte's municipal digitization programs accelerate smart city positioning infrastructure deployment.
Rio de Janeiro
Tourism wayfinding applications concentrate in coastal corridors, while stadium and venue operators deploy crowd flow optimization for safety compliance. Bluetooth low-energy beacons enable sub-meter indoor positioning for shopping mall operators without infrastructure overhaul. State-level fleet digitization mandates accelerate hardware refresh cycles among road freight operators.
Paraná and Santa Catarina
Small trucking fleets bypass traditional telematics providers, subscribing instead to API-first location platforms that aggregate positioning data from driver smartphones. Cold chain operators deploy temperature-integrated tracking to satisfy export compliance requirements. Curitiba and Florianópolis anchor agribusiness corridor demand for offline-capable navigation to circumvent cellular dead zones.
Bahia
Municipal digitization programs in Salvador lag São Paulo by 36-48 months, creating first-mover windows for smart city positioning infrastructure. Tourism wayfinding applications expand along coastal corridors as retail proximity marketing faces LGPD consent-layer friction. Northeast urban corridor development attracts edge-cloud convergence pilots targeting autonomous vehicle latency requirements.
Brazil Location Based Services Market Competitive Landscape
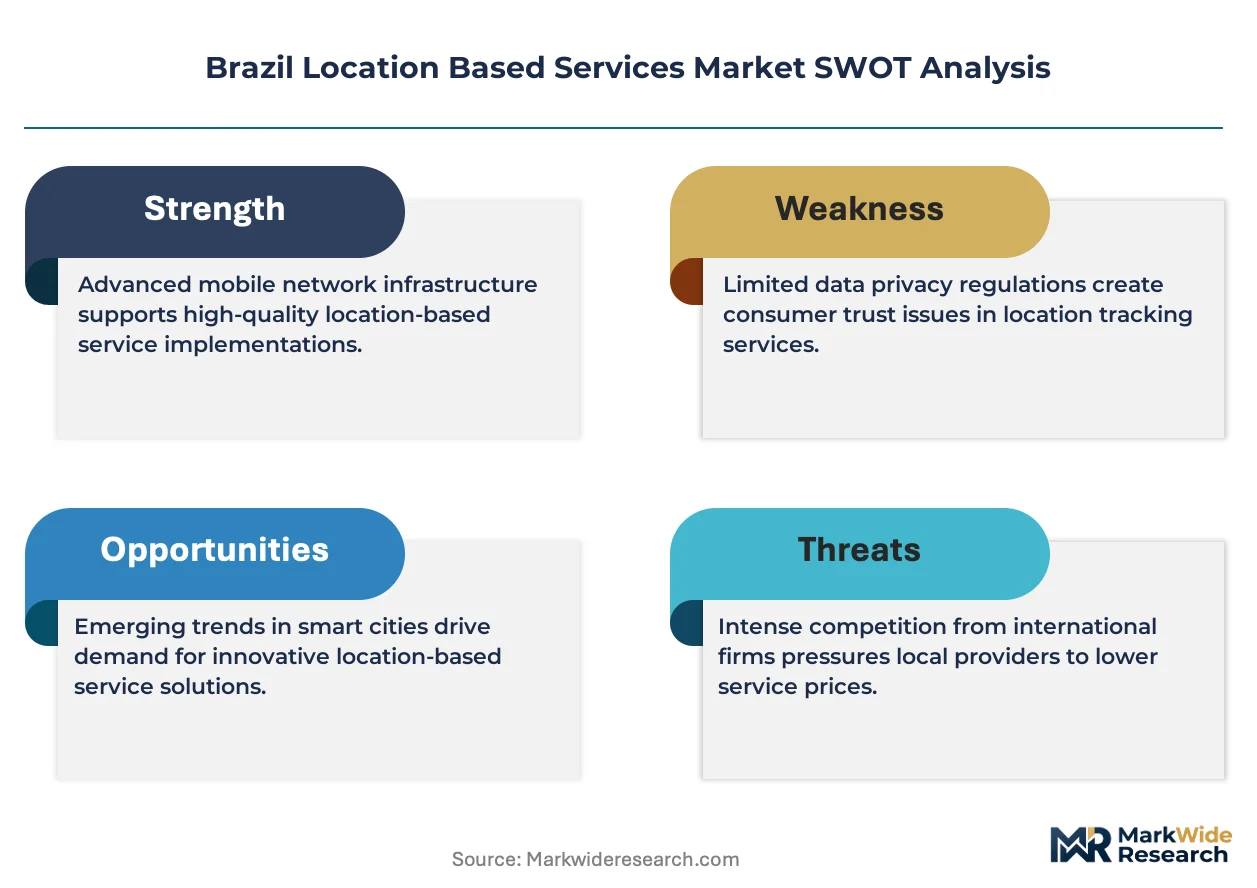
Branded specialists and contract manufacturers split share differently across segments, with cloud-native middleware providers displacing hardware-centric incumbents in the long tail of Brazilian road transport. The vendor base concentrates around three strategic archetypes: mapping data aggregators anchoring advertising and navigation layers, network infrastructure vendors sustaining carrier-side positioning capabilities, and enterprise analytics platforms serving retail and transportation verticals. Dominant competitive moves include API-first platform launches that aggregate smartphone positioning data and strategic partnerships with ANATEL-certified middleware providers.
Within the mapping and navigation tier, Google LLC occupies a position as the dominant data corpus holder, while Ericsson Inc exemplifies the network infrastructure archetype through its 5G carrier partnerships. IBM Corporation anchors the enterprise analytics segment with location intelligence platforms. These three companies represent the primary competitive anchors around which Brazilian LBS market structure organizes, each sitting within distinct value chain positions that limit direct confrontation while shaping procurement patterns across retail, logistics, and municipal verticals.
| Leading Market Players |
|---|
| Maxar Technologies |
| Ericsson Inc |
| Google LLC |
| Movile |
| GL Communications Inc |
| IBM Corporation |
| Esri Technologies Ltd |
| Uber Technologies Inc |
| Cisco Systems Inc |
| Others |
Pricing and Supply Chain Analysis
RF signal processing and GNSS firmware competencies concentrated in Brazil's southeastern university corridors widen labor-cost differentials between premium cloud-native middleware providers and economy-tier hardware integrators serving informal transport sectors.
Pricing Analysis
Volume-versus-margin splits separate high-velocity API-first location platforms from premium enterprise analytics suites. Three-tier pricing structure across premium, standard, and economy levels stratifies by data granularity, with certified middleware commanding premiums under LGPD compliance mandates. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in economy tiers intensifies as smartphone-aggregated positioning displaces dedicated hardware. Small trucking fleets in Paraná and Santa Catarina exhibit highest price sensitivity, while healthcare emergency response operators in Minas Gerais demonstrate lowest sensitivity due to clinical-grade accuracy requirements.
Supply Chain Analysis
Workforce-availability constraints in Brazilian RF engineering programs force middleware providers to source firmware development from Taiwan and South Korea. GNSS receiver chipsets and Bluetooth SoCs draw from East Asian foundries, creating single-source vulnerability for Brazilian integrators. Supply chain risk centers on currency volatility and extended lead times for semiconductor inputs. Distribution runs through carrier-certified middleware partnerships and direct API subscriptions to logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's LBS market reads as a consolidation play where ANATEL's 5G accuracy mandates and LGPD compliance overhead force sub-scale hardware providers toward exit or acquisition.
For Market Incumbents: Lock in carrier-side positioning capabilities through ANATEL-certified middleware partnerships before cloud-native platforms displace hardware-centric revenue pools. Defend against API-first aggregators by embedding temperature-integrated tracking modules for cold chain operators in Santa Catarina. Prioritize certification investment in LGPD auditable data lineage to capture healthcare emergency response specifications in Minas Gerais. For New Entrants and Emerging Players: Small trucking fleets in Paraná and Santa Catarina represent the most penetrable buyer archetype, bypassing traditional telematics providers through smartphone-aggregated positioning subscriptions. Northeast urban corridors in Recife and Salvador offer 36-48 month first-mover windows for smart city infrastructure. Go-to-market through municipal digitization program partnerships rather than direct enterprise sales. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native middleware providers given ANATEL's 5G standalone accuracy obligations accelerating multi-constellation GNSS adoption. Long-term viability favors platforms with hybrid edge-cloud architectures serving autonomous vehicle pilot zones. Watch Campinas latency-compression pilots as inflection indicator for clinical-grade and automotive-grade specification expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Middleware Certification | LGPD compliance mandates push enterprises toward certified providers with auditable data lineage. |
| Edge-Cloud Architecture Deployment | Campinas autonomous vehicle pilots require sub-10ms round-trip latency for real-time positioning. |
| UWB Anchor Network Installation | São Paulo shopping mall operators deploy sub-30cm wayfinding for aisle-level promotional targeting. |
| API-First Platform Launch | Smartphone-aggregated positioning displaces hardware-centric providers in Paraná trucking corridors. |
| Healthcare Emergency Response Partnership | Minas Gerais ambulance fleets trial sub-meter routing to compress emergency arrival intervals. |
Research Methodology
Document review covered ANATEL regulatory filings, carrier 5G deployment disclosures, and LGPD enforcement precedents, complemented by interviews with logistics operators, municipal digitization officers, and middleware platform engineers. Primary fieldwork engaged fleet procurement managers at cold chain exporters in Santa Catarina, smart city program directors in Recife and Salvador, and RF systems architects at Brazilian telecommunications equipment providers. Secondary validation drew from INCRA territorial mapping frameworks, INMETRO certification databases, and ANATEL spectrum auction documentation. Bottom-up service deployment counts triangulated against top-down carrier infrastructure investment disclosures.
Segment-level revenue estimates derived from modeling technology adoption curves across GPS, Bluetooth, and UWB positioning layers, combined with end-use penetration rates in transportation, retail, healthcare, and municipal verticals. The analytical framework incorporated service type splits between navigation, tracking, location analytics, and advertising, cross-referenced with deployment model differentiation between hardware-integrated and software-only platforms. CAGRs emerged from curve-fitting historical telematics subscription growth against projected 5G infrastructure densification timelines. Industry-specific inputs included ANATEL's 3-meter horizontal accuracy mandate for dense urban environments and LGPD consent-layer friction coefficients for proximity marketing applications.
Revisions become necessary when ANATEL delays 5G standalone rollout timelines, LGPD enforcement intensity shifts, or semiconductor supply disruptions extend GNSS chipset lead times beyond carrier hardware refresh cycles. Forecasts reflect assumptions about middleware certification adoption rates and edge-cloud infrastructure investment pacing across southeastern state capitals. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market