
 Business Mapping Software Market | 2026-2036
Business Mapping Software Market Size, Share, and Industry Trends Forecast 2026-2036
Business Mapping Software Market Outlook
API-first architecture is rewriting how business mapping platforms integrate with enterprise resource planning and customer relationship management stacks. Esri anchors the high-end geographic information systems segment through deep vertical specialization. Mapline competes on accessibility for mid-market sales teams with lightweight deployment models. eSpatial differentiates through native Salesforce connectivity that reduces implementation friction.
Business mapping software refers to platforms that render geocoded enterprise data onto interactive cartographic interfaces, typically supporting coordinate precision to street-level granularity and real-time layer compositing for spatial decision-making. The primary commercial purpose is to transform location-based intelligence into operational plans for sales territory design, supply chain routing, and service dispatch. Cloud-based deployment leads the product type dimension because subscription economics lower capital barriers for distributed workforces. Geographic analysis commands the feature category as organizations prioritize site selection and risk modeling over basic visualization. Multi-tenant architectures dominate deployment preferences where data isolation requirements remain moderate.
FCC guidelines on geolocation data privacy, EU GDPR location tracking provisions, and Japan's METI data sovereignty frameworks collectively shape product roadmaps and cross-border hosting strategies for vendors. Compliance with these regimes determines market access eligibility and influences feature development priorities around consent management and data residency. Stakeholders must weigh regulatory fragmentation against the operational benefits of unified global platform deployments when selecting vendor partnerships.
Market Dynamics
Cloud migration mandates under the EU AI Act and analogous US federal data governance directives are compressing procurement cycles and forcing platform consolidation. Logistics operators expanding route optimization adoption are pulling real-time geocoding capabilities into core enterprise stacks.
Growth Catalysts
- EU AI Act compliance deadlines:Cloud migration mandates accelerate replacement of on-premise geographic information systems with compliant multi-tenant architectures.
- Smart city infrastructure buildouts:Municipal investments in Germany, the United Kingdom, and Japan create concentrated demand for street-level precision mapping layers.
- API-first integration protocols:Native connectivity with Salesforce and ERP stacks reduces implementation friction for mid-market sales operations teams.
Market Restraints
- Geolocation data privacy compliance:FCC guidelines, EU GDPR location tracking provisions, and Japan's METI data sovereignty frameworks impose cross-border hosting complexity and consent management costs.
- Specialized geospatial talent scarcity:Shortages of professionals combining cartographic science with enterprise software architecture constrain deployment velocity.
- Legacy system integration friction:Proprietary coordinate reference systems in incumbent platforms resist standardization to modern web mercator tiling schemes.
Strategic Opportunities
- Real-time layer compositing for risk modeling:Insurance and logistics sectors seek dynamic flood, fire, and supply chain disruption overlays beyond static visualization.
- Edge computing deployment architectures:Processing geocoded telemetry at network periphery reduces latency for autonomous vehicle and drone navigation applications.
- India's smart city mission:Municipal digitization programs create demand for localized business mapping platforms with vernacular interface capabilities.
Industry Challenges
- Cross-functional implementation coordination:Sales operations, IT security, and facilities management stakeholders hold conflicting requirements for data granularity and access controls.
- ISO 19115 metadata standard compliance:Geospatial data lineage documentation demands specialized tooling that most SaaS platforms lack natively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Mapping Software Market |
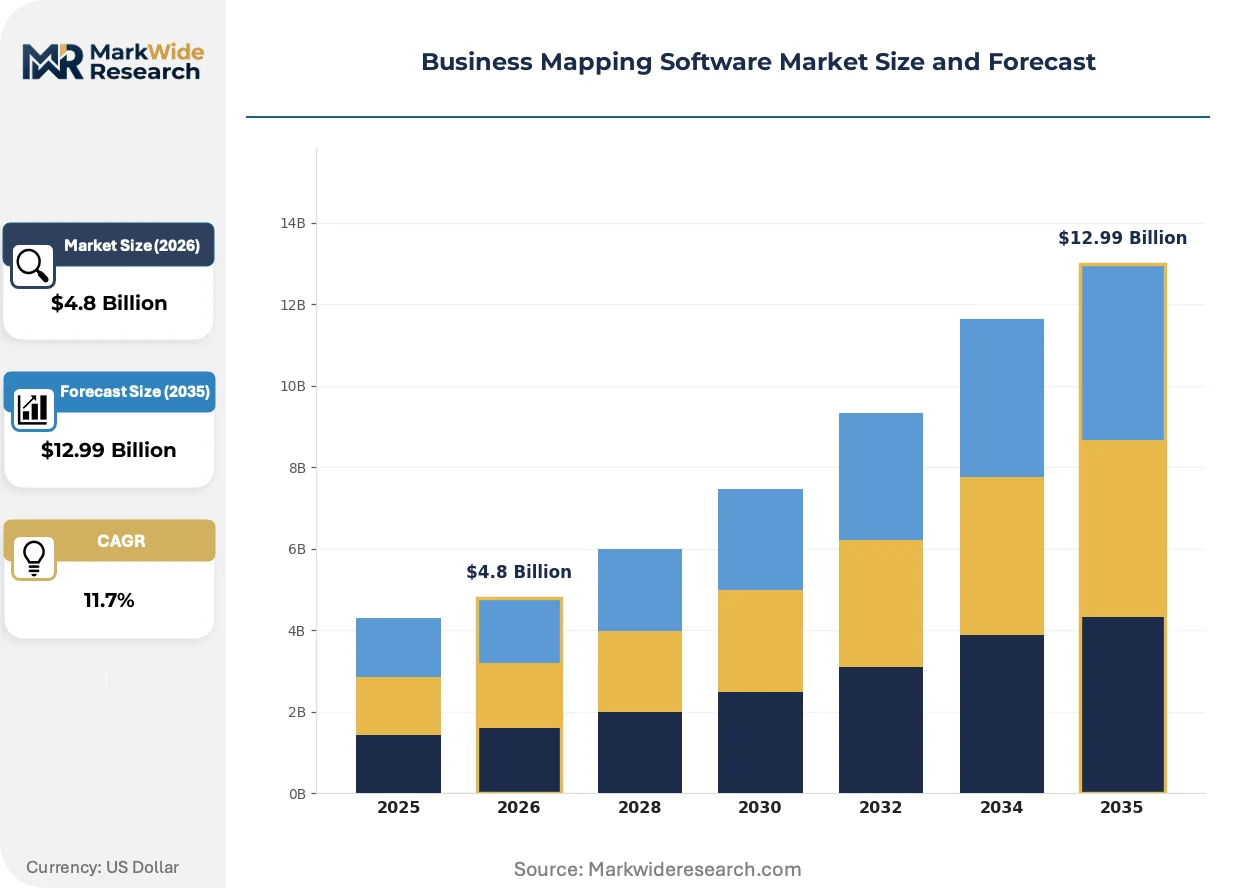
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile Feature: Data Visualization, Geographic Analysis, Collaboration Tools, Reporting Capabilities End User: Education, Healthcare, Retail, Transportation Deployment: Single Tenant, Multi-Tenant, Dedicated Server, Local Installation |
| Companies Covered | eSpatial, Z2Data, Esri, SPOTIO, Badger Maps, Mapline, Caliper (Maptitude), MapBusinessOnline, Maptive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Mapping Software Market Strategic Shifts
API-first architectures are rewriting integration patterns between business mapping platforms and enterprise resource planning stacks. Three developments are compressing competitive timelines and reshaping vendor positioning.
Serverless geocoding pipelines are rendering obsolete traditional batch-processing workflows that required dedicated infrastructure provisioning. Mid-market sales operations teams are adopting these elastic compute models to eliminate upfront capital commitments. The structural consequence is collapsing price points for entry-level territory management functionality.
The EU AI Act's data governance provisions are forcing platform operators to implement granular consent management and data residency controls. Vendors must now maintain region-specific hosting infrastructure or risk exclusion from public sector procurement. Geographic analysis features requiring cross-border data flows face the steepest compliance redesign burden.
Buyers are unbundling implementation services from software subscriptions and contracting specialized geospatial consultancies directly. This disintermediation pressures vendor professional services margins while elevating ecosystem partner certification programs. Germany and Japan exhibit the strongest preference for this separated procurement model among enterprise accounts.
Business Mapping Software Market Segmentation
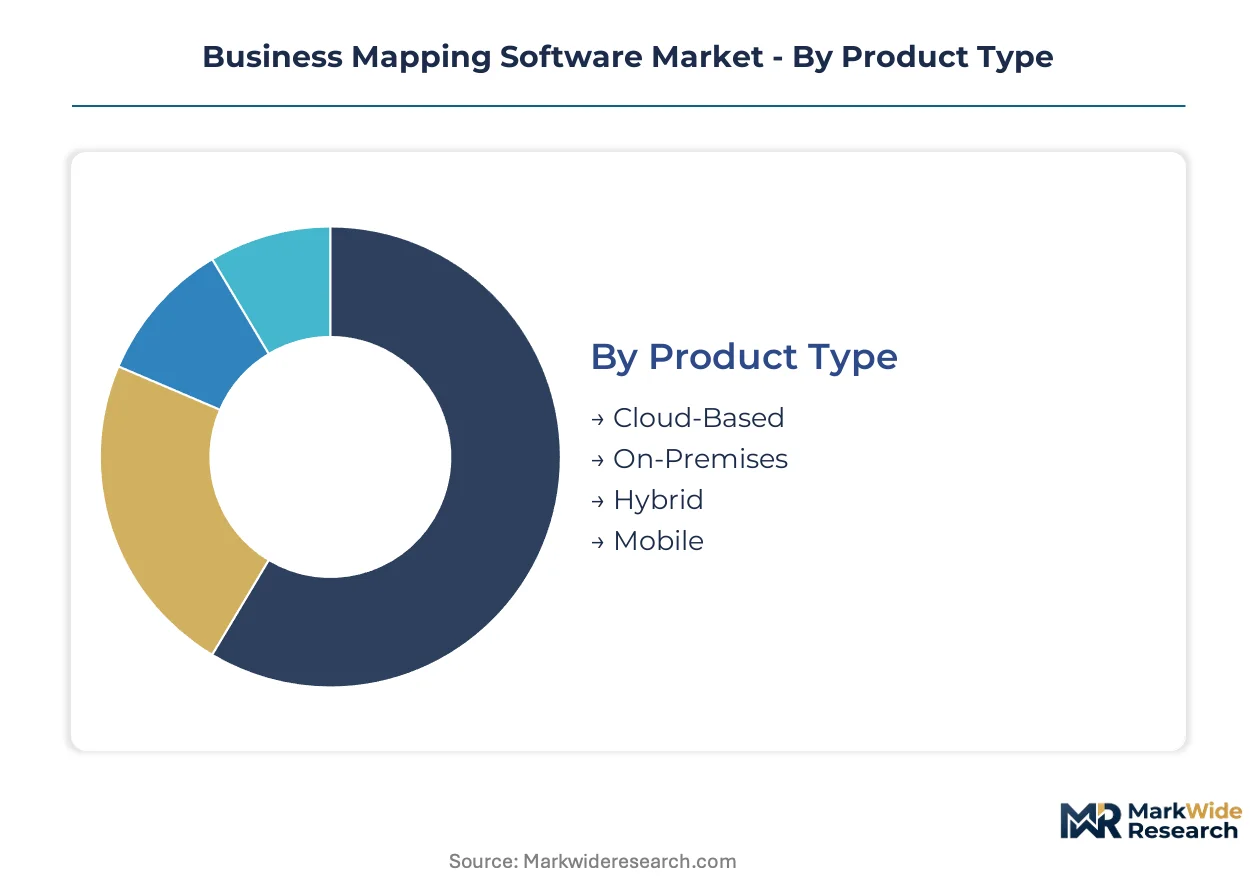
Business mapping software segments reflect divergent infrastructure requirements across cloud-native enterprises and legacy-bound institutions. Procurement patterns split sharply between organizations prioritizing elastic scaling versus those maintaining air-gapped geospatial data repositories.
Product Type:
Deployment economics range from zero-capital SaaS subscriptions to seven-figure perpetual license investments with dedicated hardware.
- Cloud-Based:Multi-tenant architectures provision geocoding engines and tile servers through browser-accessible interfaces. Logistics operators in Germany and the United Kingdom favor this model for distributed workforce coordination without VPN dependency. EU AI Act compliance deadlines accelerate displacement of on-premise alternatives.
- On-Premises:Self-hosted installations maintain complete data sovereignty within organizational firewalls. Defense contractors and critical infrastructure operators in Japan select this path despite METI data sovereignty framework complications. Capital intensity limits adoption to regulated sectors with legacy security mandates.
- Hybrid:Split architectures process sensitive coordinate data locally while leveraging cloud rendering for non-critical visualization layers. Mid-market manufacturers adopt this compromise to satisfy ISO 27001 auditors without sacrificing collaboration features.
- Mobile:Native iOS and Android SDKs embed mapping capabilities into field service applications. Utility inspection teams and delivery drivers constitute the primary demand concentration.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
Feature:
Capability depth determines pricing tiers and implementation complexity across buyer segments.
- Geographic Analysis:Spatial querying engines, drive-time polygon generation, and site suitability scoring support location intelligence workflows. Insurance underwriters in the United Kingdom deploy these tools for flood risk modeling alongside property portfolios. Real-time layer compositing for supply chain disruption overlays commands premium positioning.
- Data Visualization:Choropleth rendering, heatmap generation, and thematic cartography transform tabular datasets into interpretable spatial patterns. Sales operations teams leverage these capabilities for territory performance dashboards without specialized GIS training.
- Collaboration Tools:Shared annotation layers, version-controlled map projects, and role-based access management enable distributed planning sessions. Municipal smart city initiatives in Germany require these features for cross-departmental infrastructure coordination.
- Reporting Capabilities:Automated map export, scheduled spatial report generation, and API-connected business intelligence pipelines close the loop between analysis and executive presentation.
Functional maturity concentrates in Data Visualization; capability expansion concentrates in Geographic Analysis.
End User:
Sector-specific compliance requirements and operational rhythms shape feature prioritization and procurement cycles.
- Transportation:Fleet dispatch optimization, route sequencing algorithms, and real-time traffic integration dominate technical specifications. Third-party logistics providers across Japan and Germany represent concentrated demand as fuel efficiency mandates tighten.
- Retail:Trade area analysis, competitor proximity mapping, and customer density heatmaps guide expansion strategy. Franchise operators and commercial real estate teams constitute the core buyer profile.
- Healthcare:HIPAA-compliant patient geocoding, service area gap analysis, and mobile health route planning address population health management objectives. Hospital network planners balance accessibility optimization against privacy constraints.
- Education:Campus wayfinding, enrollment catchment mapping, and alumni distribution analysis serve administrative and advancement functions. K-12 districts and university systems deploy these tools for resource allocation equity assessments.
Procurement velocity favors Transportation; compliance complexity favors Healthcare.
Deployment:
Tenancy architecture determines data isolation guarantees and infrastructure cost structures.
- Multi-Tenant:Shared compute and storage resources with logical separation between customer datasets. Subscription economics and automatic platform updates attract growth-stage enterprises without dedicated DevOps capacity.
- Single Tenant:Isolated database instances and dedicated application servers for moderate data sovereignty requirements. Regional healthcare networks and financial services firms select this middle ground.
- Dedicated Server:Physically segregated hardware with custom security configurations. Government agencies and defense contractors in Japan mandate this deployment for classified geospatial intelligence handling.
- Local Installation:Air-gapped execution environments with no external network dependency. Research stations and critical infrastructure control centers maintain these configurations despite operational friction.
Cost efficiency favors Multi-Tenant; control requirements favor Dedicated Server.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise sales operations teams and logistics coordinators dominate procurement across concentrated urban technology corridors. Municipal smart city budgets and freight optimization mandates pull platform adoption into specific national markets. Regulatory compliance deadlines compress deployment timelines unevenly across jurisdictions.
Germany
Industrial manufacturers and third-party logistics providers drive demand for route optimization and territory management tools. The EU AI Act's cloud migration mandates accelerate displacement of legacy on-premise geographic information systems. Munich and Stuttgart clusters concentrate procurement among automotive supply chain operators seeking real-time fleet coordination.
United Kingdom
Insurance underwriters and commercial real estate teams prioritize flood risk modeling and site suitability analysis capabilities. GDPR location tracking provisions impose consent management requirements on cross-border data flows. London's financial services corridor anchors demand for compliance-ready geographic analysis platforms.
Japan
Critical infrastructure operators and defense contractors maintain stringent data sovereignty requirements under METI frameworks. Smart city investments in Tokyo and Osaka metropolitan areas create concentrated demand for street-level precision mapping. Local installation preferences persist despite operational friction from air-gapped security mandates.
United States
Mid-market sales operations teams and healthcare network planners constitute the primary buyer profile for cloud-based territory design tools. FCC geolocation data privacy guidelines shape product roadmaps around consent management features. Seattle and Boston technology corridors concentrate API-first platform adoption among SaaS-native enterprises.
India
Municipal digitization programs under the Smart Cities Mission generate demand for localized platforms with vernacular interface capabilities. State-level data localization requirements influence vendor hosting strategies. Bangalore and Hyderabad technology clusters emerge as early adoption centers for cloud-based geographic analysis among IT services exporters.
Business Mapping Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered price-performance segments. The vendor base organizes around three strategic archetypes: legacy geographic information systems incumbents with deep vertical specialization, lightweight SaaS challengers targeting mid-market accessibility, and API-native platforms emphasizing CRM connectivity. Competitive moves concentrate on M&A activity absorbing specialized geospatial consultancies and geographic expansion into compliance-constrained public sector procurement.
Within the incumbent tier, Esri anchors high-end positioning through decades of cartographic science investment. Mapline occupies the accessibility-focused mid-market segment with streamlined deployment models. eSpatial exemplifies the integration-native archetype, reducing implementation friction through pre-built enterprise connectivity. These three players collectively represent the competitive spectrum from specialized technical depth to frictionless commercial deployment.
| Leading Market Players |
|---|
| eSpatial |
| Z2Data |
| Esri |
| SPOTIO |
| Badger Maps |
| Mapline |
| Caliper (Maptitude) |
| MapBusinessOnline |
| Maptive |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in cloud infrastructure regions serving the EU AI Act compliance deadlines is compressing vendor margins while accelerating buyer procurement. Cloud service providers are prioritizing multi-tenant architecture deployments, forcing business mapping software vendors to absorb infrastructure cost escalations or risk losing public sector eligibility.
Pricing Analysis
Cost-plus contracts with cloud infrastructure indexation dominate vendor pricing structures, particularly for EU-deployed instances subject to data residency mandates. Pricing stratifies across enterprise-grade geographic analysis suites, mid-market territory management tools, and entry-level visualization tiers, with differentiation anchored in API call volumes and real-time layer compositing depth. Cost compression in the mid-market segment is intensifying as serverless geocoding pipelines eliminate upfront capital barriers. Third-party logistics providers exhibit the highest price sensitivity due to thin operational margins, while defense contractors accept premium positioning for air-gapped deployment guarantees.
Supply Chain Analysis
Contract-manufacturing concentration for geocoding engine hardware rests with Taiwan-based semiconductor foundries and South Korean memory fabricators supplying cloud data center expansion. The supply chain draws from specialized GIS component manufacturers in Germany and Japan, alongside open-source cartographic library maintainers distributed across North American and European developer communities. Single-source vulnerability in GPU acceleration chips for real-time rendering poses structural risk to platform scaling. Distribution runs through direct enterprise sales channels and hyperscaler marketplaces, with implementation services increasingly disintermediated to certified geospatial consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Business mapping software functions as a service-attach opportunity where recurring revenue from API consumption and implementation support expands faster than initial subscription capture. Professional services margins are compressing as buyers unbundle implementation from software procurement.
For Market Incumbents: Pre-empt displacement by lightweight SaaS challengers through acquisition of specialized geospatial consultancies with vertical certifications. Consolidate channel control by embedding territory optimization algorithms directly into ERP and CRM platform marketplaces, reducing implementation friction that mid-market entrants exploit. Investment in ISO 19115 metadata compliance tooling addresses a capability gap that most SaaS platforms lack natively. For New Entrants and Emerging Players: Build out localized platform variants for India's Smart Cities Mission, where vernacular interface capabilities and state-level data localization requirements create defendable positioning. Target municipal digitization programs in secondary German and Japanese urban centers underserved by enterprise-focused incumbents. Pursue API-native go-to-market strategies emphasizing pre-built Salesforce connectivity to reduce sales cycle friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across serverless deployment architectures, compressing barriers to entry for cloud-native challengers. Long-term viability favors vendors with sustainable differentiation in real-time layer compositing for insurance risk modeling or autonomous vehicle navigation edge cases. Acquisition targets should demonstrate certified compliance with EU AI Act data governance provisions and METI data sovereignty frameworks. Monitor hyperscaler partnership announcements as inflection indicators for platform distribution leverage.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Native ERP connectivity reduces implementation friction for mid-market sales operations teams. |
| Acquisition of Specialist Consultancies | Vertical certifications address ISO 19115 metadata compliance gaps in SaaS platforms. |
| Edge Computing Deployment | Peripheral processing reduces latency for autonomous vehicle navigation applications. |
| Geographic Expansion into India | Smart Cities Mission creates demand for vernacular interface capabilities. |
| Compliance Certification Investment | EU AI Act and METI framework adherence determines public sector procurement eligibility. |
Study Parameters
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings. Conversations with CTOs, IT procurement officers, platform engineers, and integration specialists informed deployment preference patterns and integration friction points. Secondary sources include SEC filings from publicly traded software vendors, hyperscaler capex disclosures, EU AI Act implementation guidance documents, and METI data sovereignty framework advisories. Bottom-up segmentation modeling triangulates against top-down market sizing from cloud infrastructure spending correlations.
Calibration against historical adoption curves in adjacent location intelligence markets validates the projection framework. The analytical model segments across deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster throughout the forecast period. CAGRs derive from elasticity-adjusted replacement cycles for on-premise geographic information systems and API consumption growth trajectories. Forecast inputs incorporate EU AI Act compliance deadline impacts and smart city infrastructure budget allocations in Germany, the United Kingdom, and Japan.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by hyperscaler-backed challengers would shift outcomes beyond modeled ranges. Regulatory enforcement intensity around geolocation data privacy and cross-border data flows represents a specific revision risk. Quarterly review of public sector procurement announcements and hyperscaler partnership disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
Global Digital Maps Market