
 Augmented Reality Book Market | 2026-2036
Augmented Reality Book Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality Book Market Insights
Educational institution procurement is rewriting how AR book publishers reach end users, bypassing traditional retail intermediaries. MIT Press leverages deep academic partnerships to sustain direct-to-institution sales. Snap Inc. competes through its Lens platform, which anchors interactive graphic distribution for third-party publishers. Penguin Random House Spatial Labs differentiates by controlling premium fiction AR content pipelines.
An augmented reality book overlays digital content—interactive graphics, three-dimensional models, audio integration, or virtual experiences—onto physical printed pages through camera-enabled devices, requiring marker recognition or spatial mapping algorithms for real-time rendering. Children's books lead product type revenue as parents prioritize screen-time alternatives with educational value, while educational books capture the fastest expansion among end users as K-12 districts formalize AR curriculum standards. Subscription services represent the emerging margin pool within distribution channels, shifting from unit sales to recurring content access models.
The EU AI Act imposes algorithmic transparency requirements on AR content recommendation engines, while the FCC governs wireless spectrum allocation for cloud-rendered AR experiences in the United States. China's SAMR enforces content review protocols for minors accessing interactive digital overlays, tightening market access for unapproved foreign publishers. Stakeholders must monitor evolving classification debates over whether AR-enhanced publications constitute software, media, or educational equipment, as this determination triggers divergent compliance obligations across jurisdictions.
Market Dynamics
Educational procurement contracts are compressing publisher margins while institutional buyers demand perpetual content licenses over unit sales, forcing AR book developers to rebuild revenue models around SaaS-style delivery infrastructure.
Growth Catalysts
- K-12 Curriculum Mandates:United States school districts are embedding AR literacy standards into state technology frameworks, creating institutional demand pull for classroom-ready interactive titles.
- Cloud Rendering Infrastructure:5G network densification is collapsing latency barriers for real-time spatial mapping, enabling markerless AR experiences on mid-tier smartphones without dedicated hardware.
- EU AI Act:Algorithmic transparency requirements for content recommendation engines are standardizing trust frameworks that accelerate public-sector adoption across German and French educational authorities.
Market Restraints
- Display Panel Concentration:OLED microdisplay supply for premium AR headsets concentrates among South Korean and Taiwanese suppliers, creating input cost volatility for hardware-bundled book programs.
- SAMR Content Review:China's State Administration for Market Regulation enforces multi-month approval protocols for interactive educational overlays, extending time-to-market for foreign publishers.
- Smartphone Substitution:Native AR apps on iOS and Android devices compete directly with dedicated AR book formats, eroding perceived value of physical-digital hybrid products among price-sensitive consumers.
Strategic Opportunities
- Subscription Licensing Models:Per-seat annual contracts for school districts in India offer recurring revenue streams that decouple publisher economics from print run volumes.
- Spatial Audio Convergence:Integration of Dolby Atmos and head-tracked audio is creating immersive narrative formats for fiction publishers targeting adult leisure readers.
- US IRA Education Technology Credits:Federal tax incentives for classroom digital infrastructure are expanding procurement budgets for AR-enabled curriculum packages in underserved districts.
Industry Challenges
- Spatial Computing Talent Scarcity:AR book developers face acute shortages of Unity and Unreal Engine specialists capable of optimizing real-time rendering for low-power mobile chipsets.
- Cross-Jurisdictional Classification:Divergent national treatments of AR-enhanced publications as software, media, or educational equipment trigger fragmented compliance obligations that extend legal review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality Book Market |
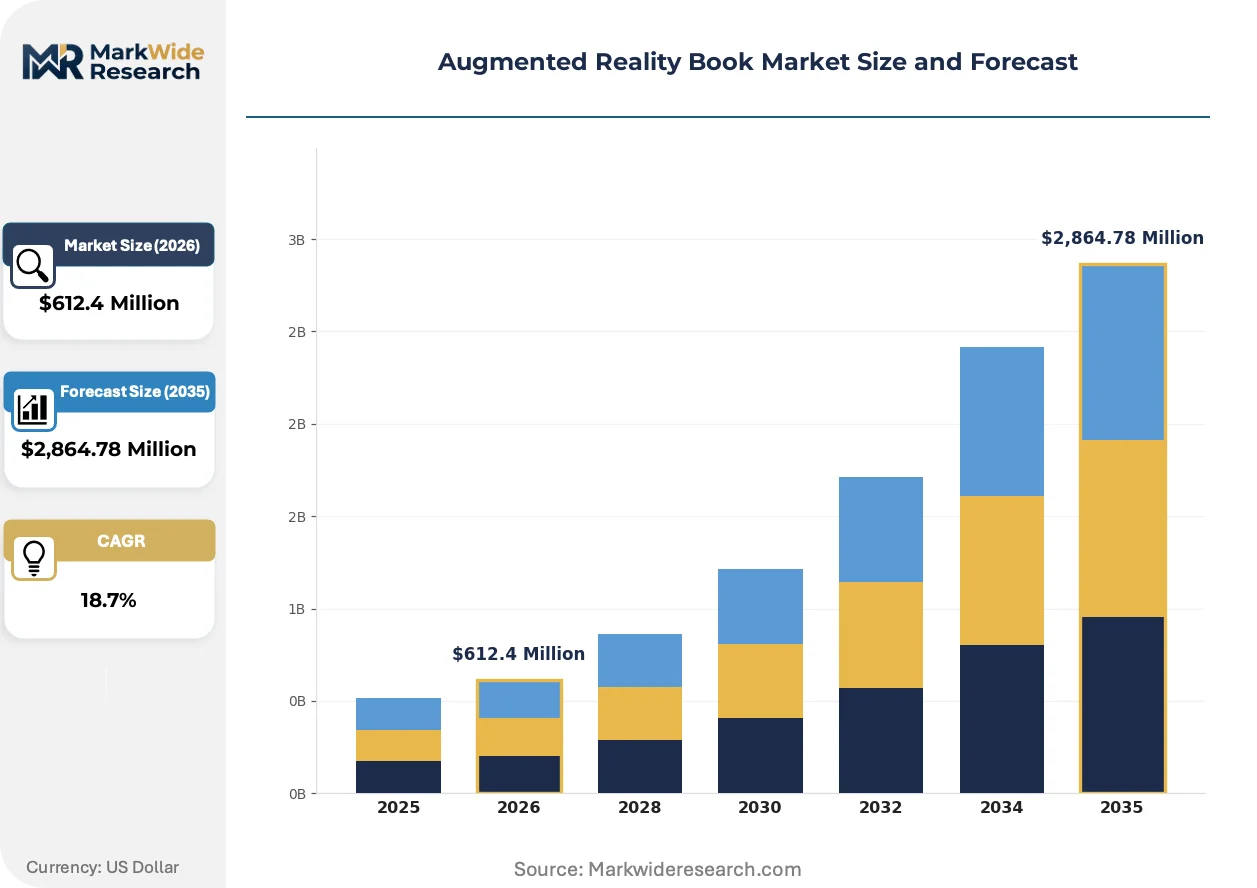
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Children's Books, Educational Books, Fiction, Non-Fiction End User: Students, Educators, Parents, Hobbyists Technological Feature: Interactive Graphics, 3D Models, Audio Integration, Virtual Experiences Distribution Channel: Online Retailers, Bookstores, Educational Institutions, Subscription Services |
| Companies Covered | Unity Literary Solutions, MIT Press, Dawn Ghostwriting, Snap Inc., Niantic, Penguin Random House Spatial Labs, New York Times R&D, Imvizar, Within Storyscapes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality Book Market Trends and Innovations
Markerless spatial mapping is eliminating hardware dependencies that previously gated AR book adoption, while cloud-rendered experiences are redistributing computational loads from devices to edge infrastructure.
Neural radiance fields (NeRF) are collapsing the production pipeline for three-dimensional asset generation, converting static illustrations into explorable volumetric scenes without manual modeling. K-12 publishers in California and Texas are adopting NeRF workflows for science textbook visualization, compressing content development timelines from months to weeks. This compression is eroding the traditional competitive moat of studios with large 3D asset libraries.
The EU AI Act's risk classification system for algorithmic content curation is imposing documentation burdens on AR recommendation engines that surface age-appropriate interactive elements. Publishers serving European educational markets must maintain audit trails for automated content filtering decisions, diverting engineering resources from feature development to compliance infrastructure. German state education ministries are piloting standardized conformity assessment protocols that may become de facto benchmarks across the continent.
Institutional procurement committees are consolidating vendor relationships around integrated platform providers rather than licensing individual titles, concentrating purchasing power among district-level technology coordinators. This consolidation is marginalizing standalone AR book publishers who lack learning management system integrations or single-sign-on compatibility. The pattern is most pronounced in United States suburban districts with centralized curriculum adoption cycles.
Augmented Reality Book Market Segmentation
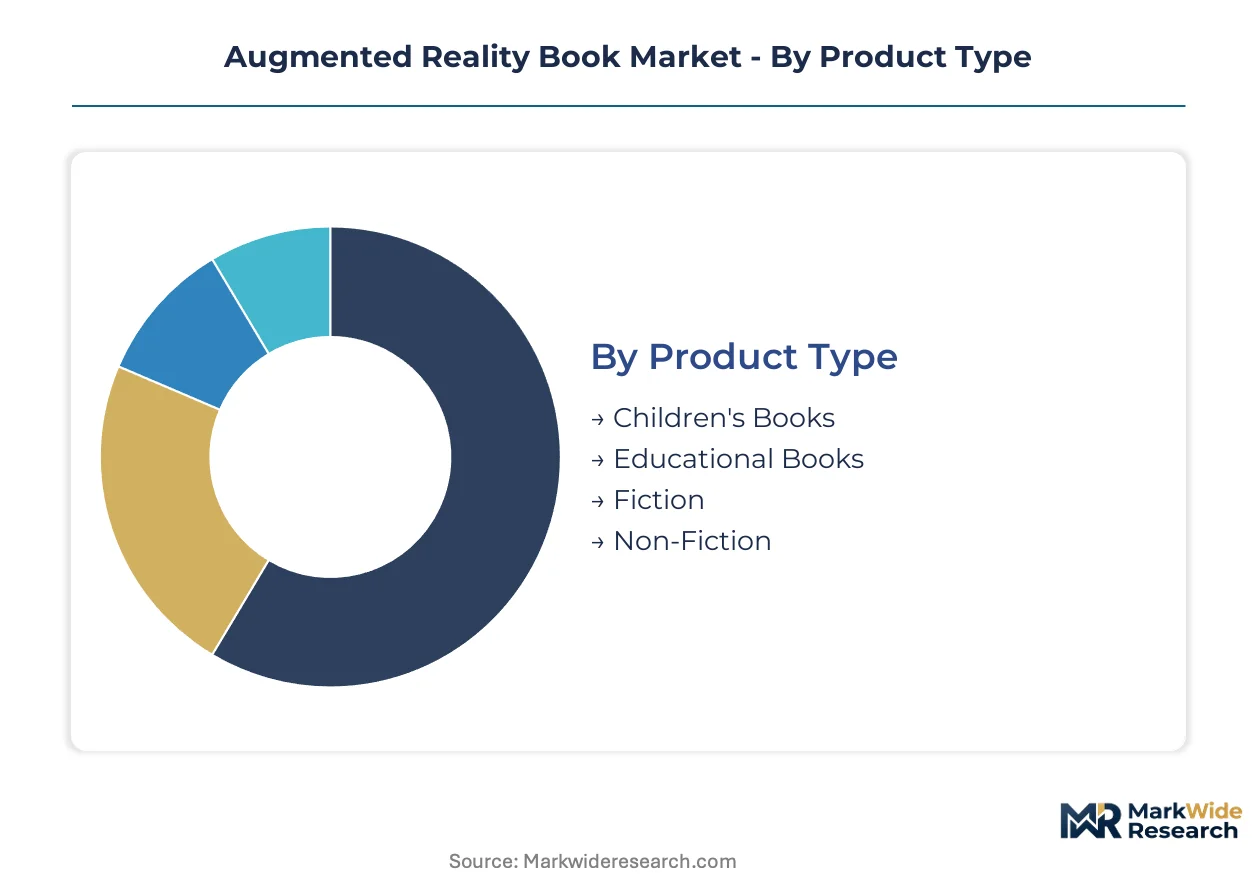
AR book segmentation reveals divergent monetization paths across consumer and institutional channels. Product type determines hardware dependency, while distribution channel selection dictates margin structure and customer lifetime value.
Product Type:
Children's educational needs span from entertainment to curriculum alignment, creating distinct technical specifications across product categories.
- Children's Books:Picture-driven formats deploy marker recognition for animated character overlays on printed pages. Parents in United States suburban districts prioritize screen-time alternatives, driving premium pricing for titles with embedded STEM activities.
- Educational Books:Curriculum-aligned titles integrate assessment dashboards and progress tracking for K-12 deployment. State technology framework mandates in Texas and California are accelerating institutional procurement cycles for science and history visualization modules.
- Fiction:Narrative AR layers spatial audio and environmental effects onto literary works. Adult leisure readers in Germany and France demonstrate willingness to pay for immersive editions of genre fiction.
- Non-Fiction:Reference formats emphasize explorable 3D artifacts and archival document overlays. Museum partnership programs in United Kingdom cultural institutions support specialized history and art publication lines.
Established volume favors Children's Books; emerging adoption favors Educational Books.
End User:
Procurement authority and technical sophistication vary sharply across user categories, reshaping sales motion requirements.
- Students:K-12 learners consume curriculum-mandated titles through district-licensed platforms. Individual purchasing power remains limited; access depends on institutional adoption decisions by technology coordinators.
- Educators:Classroom practitioners require lesson plan integration and professional development support. United States teacher preparation programs are embedding AR literacy certification, expanding addressable instructor base.
- Parents:Home purchasers respond to educational value propositions and screen-time mitigation messaging. China SAMR content review protocols for minors create compliance friction for foreign publishers targeting family buyers.
- Hobbyists:Enthusiast collectors drive limited-edition releases with premium hardware bundles. Japanese adult manga readers represent concentrated demand for AR-enhanced graphic novel formats.
Volume concentrates with Students; margin expansion concentrates with Hobbyists.
Technological Feature:
Rendering complexity and cloud dependency scale unevenly across feature categories, affecting device compatibility and development cost structures.
- Interactive Graphics:Marker-triggered animations overlay 2D illustrations with motion and sound. Mid-tier smartphone compatibility maximizes addressable device base for mass-market children's titles.
- 3D Models:Volumetric assets enable explorable objects viewable from multiple angles. NeRF pipeline adoption is collapsing production timelines for science textbook visualization in California school districts.
- Audio Integration:Spatial soundscapes and head-tracked narration enhance narrative immersion. Dolby Atmos certification is becoming a differentiation marker for adult fiction publishers targeting premium segments.
- Virtual Experiences:Fully simulated environments require cloud rendering and low-latency 5G connectivity. German educational authorities are piloting standardized assessment protocols for virtual field trip content.
Deployment breadth favors Interactive Graphics; steepest expansion trajectory favors Virtual Experiences.
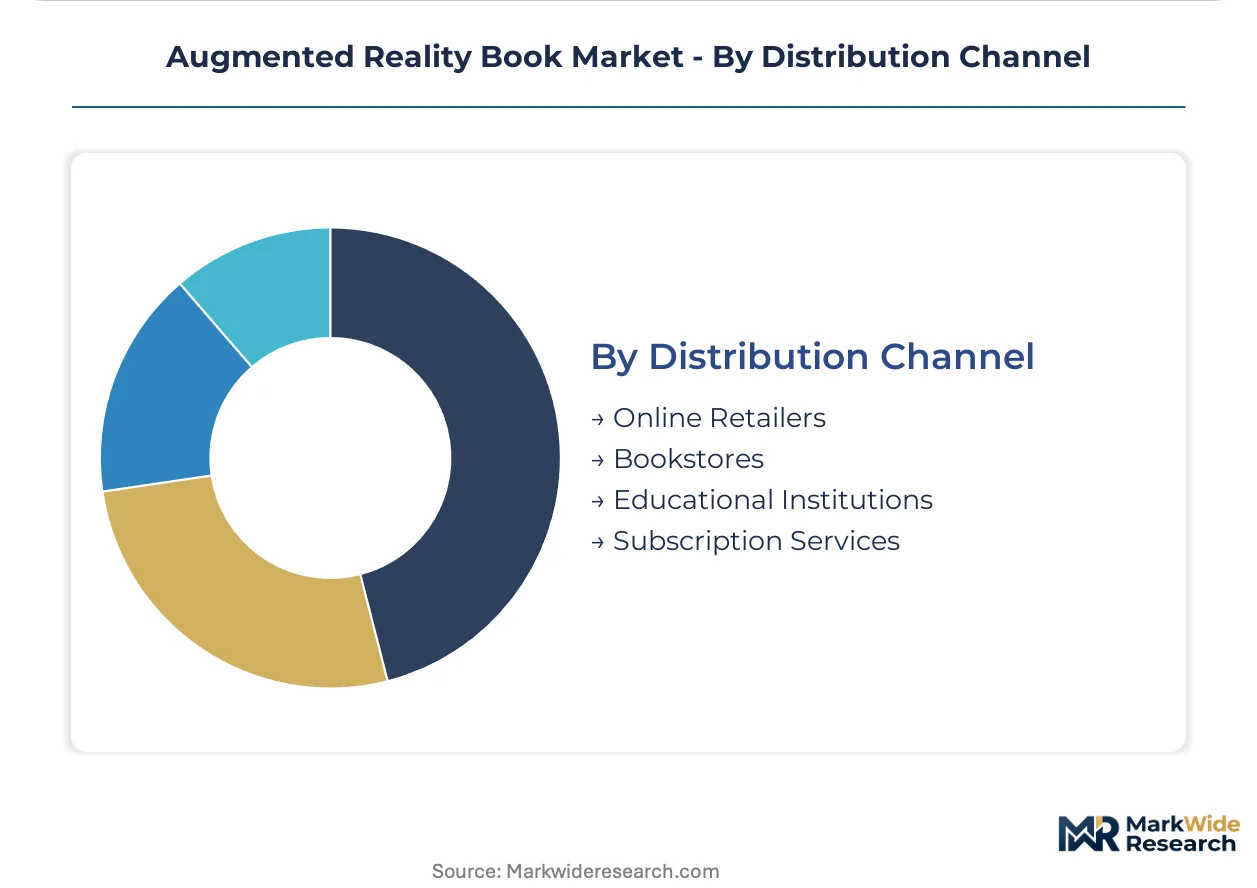
Distribution Channel:
Channel selection determines pricing control, customer data access, and recurring revenue potential for AR book publishers.
- Online Retailers:Marketplace platforms provide discovery reach but compress margins through fee structures and promotional pricing pressure. Amazon and Tmall dominate volume for consumer-directed children's titles.
- Bookstores:Physical retail enables demonstration-driven conversion through in-store AR experience stations. Independent chains in France and Germany maintain curated selections for adult fiction AR editions.
- Educational Institutions:District-level procurement committees consolidate vendor relationships around integrated platform providers. United States suburban districts with centralized curriculum adoption cycles are marginalizing standalone publishers lacking LMS compatibility.
- Subscription Services:Per-seat annual contracts decouple publisher economics from print run volumes. Indian state education boards are piloting subscription licensing for government school AR curriculum packages.
Transaction volume runs through Online Retailers; recurring revenue potential concentrates in Subscription Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The subsea cable corridors linking Frankfurt, London, and Amsterdam underpin Europe's cloud rendering capacity for AR book distribution. These fiber optic networks enable sub-20 millisecond latency for real-time spatial mapping experiences across continental educational markets.
United States
K-12 curriculum mandates in Texas and California drive institutional procurement of AR-enabled science textbooks. The FCC governs 5G spectrum allocation for cloud-rendered experiences, affecting markerless AR deployment in classrooms. Boston's academic corridor hosts MIT Press and specialized spatial computing developers serving district-level technology coordinators.
Germany
State education ministries pilot standardized conformity assessment protocols for AR curriculum content under EU AI Act transparency requirements. The EU AI Act imposes algorithmic documentation burdens on content recommendation engines filtering age-appropriate overlays. Bavaria's Munich-Stuttgart technology cluster anchors NeRF pipeline adoption for science textbook visualization workflows.
China
SAMR enforces multi-month content review protocols for interactive educational overlays targeting minors. The State Administration for Market Regulation's approval timelines extend time-to-market for foreign publishers seeking family buyer segments. Shenzhen's hardware manufacturing ecosystem supplies camera-enabled devices for mid-tier smartphone AR compatibility.
India
State education boards pilot per-seat annual subscription contracts for government school AR curriculum packages. The country's national education technology regulator evaluates content standards for public-sector procurement eligibility. Maharashtra's Mumbai-Pune corridor concentrates developer talent for Unity and Unreal Engine optimization on low-power mobile chipsets.
United Kingdom
Museum partnership programs support specialized history and art AR publication lines for non-fiction segments. The national media regulator monitors content classification debates over whether AR-enhanced publications constitute software or educational equipment. London's cultural institutions anchor premium reference format development for archival document overlay experiences.
Augmented Reality Book Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of learning management system compatibility and single-sign-on infrastructure. Three strategic archetypes dominate: academic press publishers leveraging direct institutional relationships, technology platform operators controlling distribution infrastructure, and traditional publishers establishing spatial computing divisions. Competitive moves concentrate on strategic partnerships for content pipelines and technology licensing for real-time rendering capabilities.
Within the academic press tier, MIT Press exemplifies direct-to-institution sales models bypassing retail intermediaries. Among technology platform operators, Snap Inc. occupies a position anchoring interactive graphic distribution through its Lens platform for third-party publishers. On the traditional publisher vector, Penguin Random House Spatial Labs represents premium fiction AR content pipeline control.
| Leading Market Players |
|---|
| Unity Literary Solutions |
| MIT Press |
| Dawn Ghostwriting |
| Snap Inc. |
| Niantic |
| Penguin Random House Spatial Labs |
| New York Times R&D |
| Imvizar |
| Within Storyscapes |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific fiber optic cable capacity constraints between Los Angeles and Shanghai are elevating cloud rendering costs for AR book publishers, compressing margins on economy-tier children's titles while enabling premium pricing power for hardware-bundled educational packages in United States suburban districts.
Pricing Analysis
Volume-discount tiering structures separate institutional site licenses from individual consumer purchases, with K-12 districts commanding per-seat rates below family buyers by an order of magnitude. Price differentiation rests on certification alignment with state technology frameworks and bundled professional development hours for educators. Pricing pressure stems from smartphone-native AR apps eroding perceived value of physical-digital hybrids. Parents in China represent the most price-sensitive segment due to SAMR compliance costs passed through to retail, while German state education ministries exhibit lowest sensitivity given dedicated digital infrastructure budgets.
Supply Chain Analysis
Upstream feedstock for AR book production draws from South Korean OLED microdisplay foundries, Taiwanese semiconductor packaging facilities, and Chinese camera module assembly plants. Critical component dependencies include spatial mapping chipsets, lithium-polymer batteries for headset bundles, and specialty paper stocks with embedded marker patterns. Supply chain risk concentrates in single-source vulnerability for premium display panels following consolidation among Seoul-based suppliers. Distribution runs through educational procurement committees rather than retail intermediaries for institutional volume, reversing traditional publishing economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with NeRF pipeline adoption collapsing content development timelines from months to weeks and accelerating publisher refresh cycles.
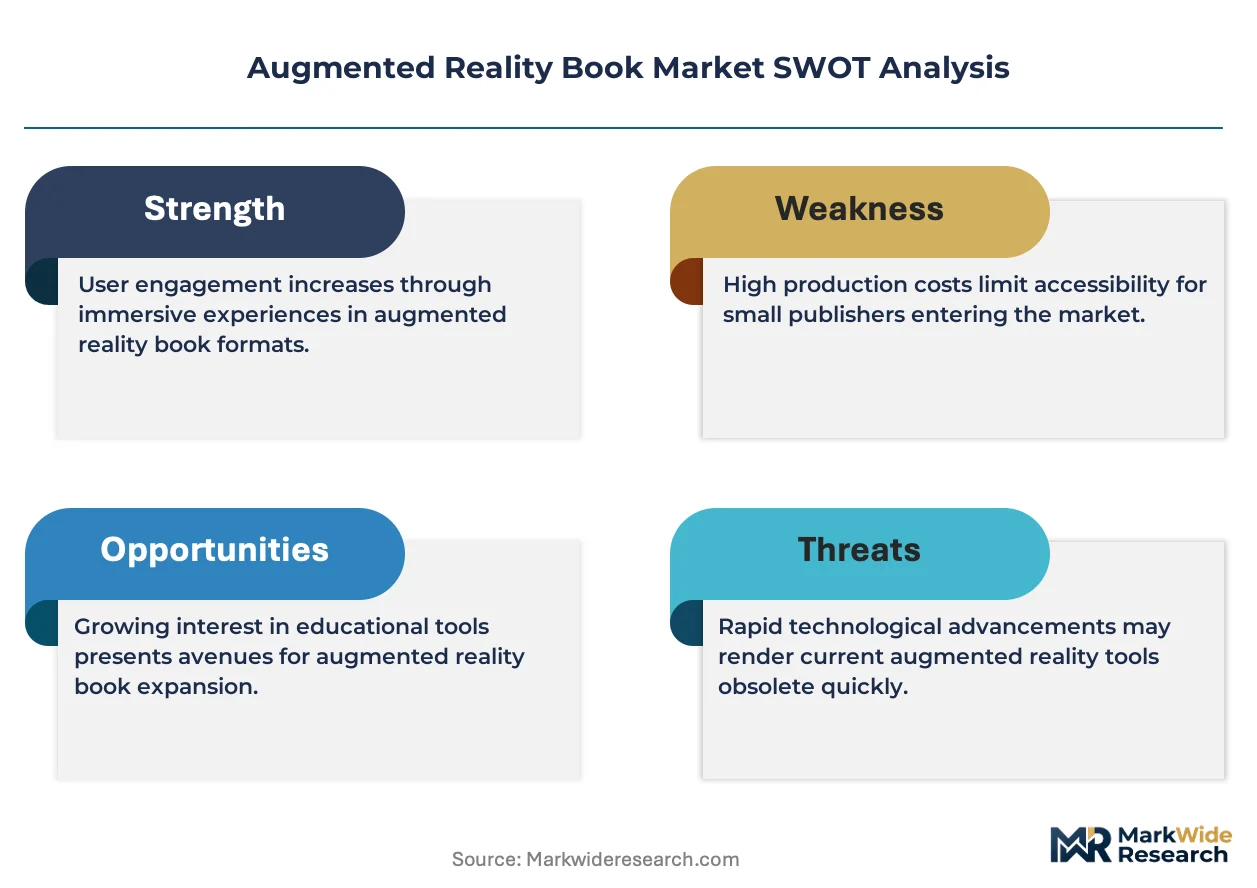
For Market Incumbents: Build learning management system integration moats to defend against standalone AR book publishers marginalization by United States suburban district procurement consolidation. Pursue backward integration into NeRF asset generation workflows to capture science textbook visualization demand in California and Texas. Prioritize EU AI Act compliance infrastructure investment ahead of German state ministry standardization. For New Entrants and Emerging Players: Mid-tier smartphone-compatible children's titles in India represent the most penetrable entry point, given state education board subscription pilot programs and lower competitive density from established Western publishers. Fiction AR with spatial audio for adult leisure readers in France offers secondary white-space with premium pricing tolerance. Go-to-market should emphasize direct educator relationship building through professional development certification partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from traditional publishers with dormant spatial computing divisions lacking SaaS delivery infrastructure for institutional recurring revenue conversion. Long-term viability favors platforms with district-level technology coordinator relationships and single-sign-on compatibility. Watch for German state ministry conformity assessment protocol adoption as inflection signal for EU-wide procurement standardization.| Strategic Initiative | Industry Significance |
|---|---|
| NeRF Pipeline Integration | Compresses 3D asset generation timelines for California K-12 science publishers. |
| LMS Compatibility Certification | Secures procurement committee inclusion in United States suburban district adoptions. |
| EU AI Act Compliance Infrastructure | Enables German state ministry pilot participation and continental expansion. |
| Spatial Audio Platform Partnership | Unlocks premium fiction pricing for adult leisure readers in France and Germany. |
| Per-Seat Subscription Licensing | Decouples publisher economics from print run volumes in Indian government schools. |
Research Methodology
Initial hypotheses were tested against primary input from K-12 technology coordinators, educational publisher product directors, spatial computing engineers, and cloud infrastructure procurement leads, then refined through secondary validation against SEC filings from platform operators, hyperscaler capex disclosures, state education technology framework documents, and EU regulatory transparency databases. Bottom-up segment sizing triangulated with top-down market boundary analysis.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling volume and value through segmentation across product type, end user category, technological feature tier, and distribution channel. CAGRs derived from historical adoption curve analysis applied to institutional procurement cycle timing and consumer device penetration thresholds. NeRF workflow adoption rates and 5G network densification timelines served as industry-specific forecast inputs.
Practitioners should monitor SAMR approval timeline fluctuations, EU AI Act enforcement variance across member states, and OLED microdisplay foundry capacity announcements for early signals of forecast revision. Cross-checking against IEA digital infrastructure investment tracking and national education technology budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market