
 Japan Corrugated Boxes Market | 2026-2036
Japan Corrugated Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Corrugated Boxes Market Intelligence
Heavy-duty triple-wall specifications for industrial machinery exports is unwinding premium pricing dynamics across the Japan corrugated boxes market. Oji Holdings Corporation leverages integrated pulp-to-box manufacturing to control input costs across Hokkaido mill operations. Rengo Co., Ltd. anchors its position through specialized beverage packaging formats serving Kirin and Suntory distribution networks. Nippon Paper Group Inc. competes via high-strength lightweight board technologies that reduce freight charges for e-commerce fulfillment.
Japan corrugated boxes are paper-based containerboard structures formed from fluted medium sandwiched between linerboard facings, typically manufactured through corrugating processes using steam-heated rollers at 160-180°C to achieve specific burst strength and edge crush test ratings. These containers protect goods during distribution while enabling efficient palletization and retail display. Die-cut box formats capture expanding share among cosmetics brands requiring retail-ready presentation without secondary unpacking. E-commerce end users now drive fastest volume expansion as last-mile delivery requirements multiply box touches per shipment. Single-wall thickness still dominates total tonnage though double-wall formats gain ground in electronics exports to Southeast Asia.
METI's Resource Circulation Strategy for Plastics and container recycling targets shape virgin fiber substitution rates, while JIS standards for corrugated fibreboard boxes mandate minimum compression strength thresholds for certified export packaging. PMDA traceability requirements for pharmaceutical shipments indirectly elevate box labeling and serialization standards. Stakeholders must monitor how Japan's dual carbon goals alter energy costs at kraft pulp mills and whether recycled content mandates expand beyond current voluntary frameworks.
Market Dynamics
Japan's corrugated box sector is contending with METI's Resource Circulation Strategy for Plastics, which mandates virgin fiber substitution rates and redirects raw material procurement toward certified recycled streams across the Kanto industrial corridor.
Growth Catalysts
- E-commerce fulfillment surge:Last-mile delivery networks in Tokyo and Yokohama are multiplying box touches per shipment, creating sustained volume pull for protective shipping formats.
- Export packaging certification:JIS standards for corrugated fibreboard boxes mandate minimum compression strength thresholds, forcing industrial machinery exporters toward heavy-duty triple-wall specifications.
- Carbon-reduction targets:METI's dual carbon goals are elevating demand for lightweight high-strength board technologies that reduce freight charges and emissions per unit shipped.
Market Restraints
- Kraft pulp input volatility:Energy cost spikes at Hokkaido mill operations are compressing margins for integrated manufacturers dependent on captive pulp supply.
- Recycled fiber quality degradation:Post-consumer OCC streams show rising contamination rates, limiting burst strength achievement in double-wall formats for electronics exports.
- Substitution by reusable plastic totes:Closed-loop distribution systems serving Kirin and Suntory beverage networks are displacing single-trip corrugated in select regional routes.
Strategic Opportunities
- Pharmaceutical serialization compliance:PMDA traceability requirements for drug shipments are elevating box labeling standards, creating premium positioning for certified packaging suppliers.
- Cosmetics retail-ready formats:Die-cut box specifications that eliminate secondary unpacking are capturing share among beauty brands targeting department store distribution.
- Recycled content mandate expansion:Voluntary frameworks under METI's container recycling targets may harden into binding thresholds, rewarding early movers with certified supply chains.
Industry Challenges
- Corrugator technician shortage:Steam-heated roller calibration and edge crush test optimization require specialized skills that aging workforces in Osaka and Nagoya struggle to replenish.
- Legacy ERP integration friction:Serialization and lot-tracking systems demanded by pharmaceutical clients clash with decades-old production scheduling software at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Corrugated Boxes Market |
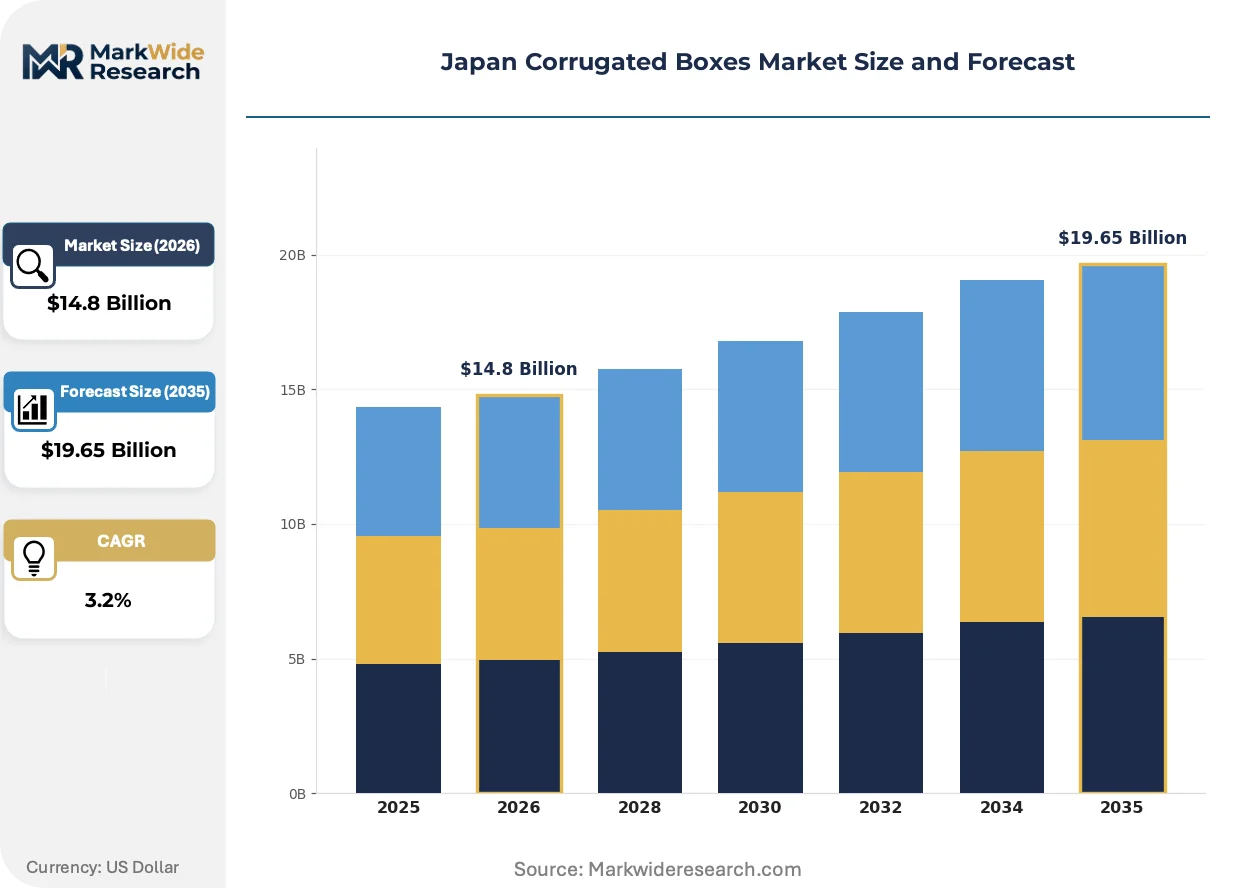
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $19.65 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Box Type: Regular Slotted Container, Die-Cut Box, Roll End Front Tuck Box, Half Slotted Container End User: Food & Beverage, Electronics, Cosmetics, E-Commerce Thickness: Single Wall, Double Wall, Triple Wall, Heavy Duty Supply Chain: Manufacturers, Wholesalers, Distributors, Retailers |
| Companies Covered | Yamakoh Co., Ltd., Dynapac Co., Ltd., Rengo Co., Ltd., Japan Pulp & Paper Company Co. Ltd., ISOWA Corporation, Oji Holdings Corporation, Tomoku Co., Ltd., TPG (HK) Ltd., Nippon Paper Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Corrugated Boxes Market Strategic Shifts & Innovations
Japanese corrugated manufacturing is pivoting toward material science advances and regulatory compliance automation, with technology adoption splitting along end-use sophistication tiers rather than uniform diffusion.
High-strength lightweight board technologies are bifurcating the market between premium specifications serving pharmaceutical and electronics exporters and commodity grades capturing standard e-commerce volume. Cosmetics brands and precision machinery shippers are adopting these boards fastest, while grocery and bulk industrial users lag. The structural consequence is compressing freight cost differentials between domestic and export-focused converters, rewarding capital-intensive producers with in-house linerboard mills.
METI's Resource Circulation Strategy for Plastics is tightening recycled content verification requirements across containerboard supply chains. Industrial converters must now document fiber provenance through certified recycling streams to maintain eligibility for government procurement contracts. Pharmaceutical and food-contact packaging segments are responding fastest, investing in blockchain-tracked batch records ahead of anticipated mandate expansion.
Direct procurement relationships between major e-commerce platforms and tier-one corrugators are displacing traditional wholesale distribution channels in the Kanto region. Brand-owners now specify exact burst strength and print registration tolerances in master service agreements, bypassing trading companies that previously aggregated fragmented buyer demand. This pattern is most visible in Tokyo's same-day delivery fulfillment networks, where platform-owned specifications dominate supplier qualification.
Japan Corrugated Boxes Market Segmentation
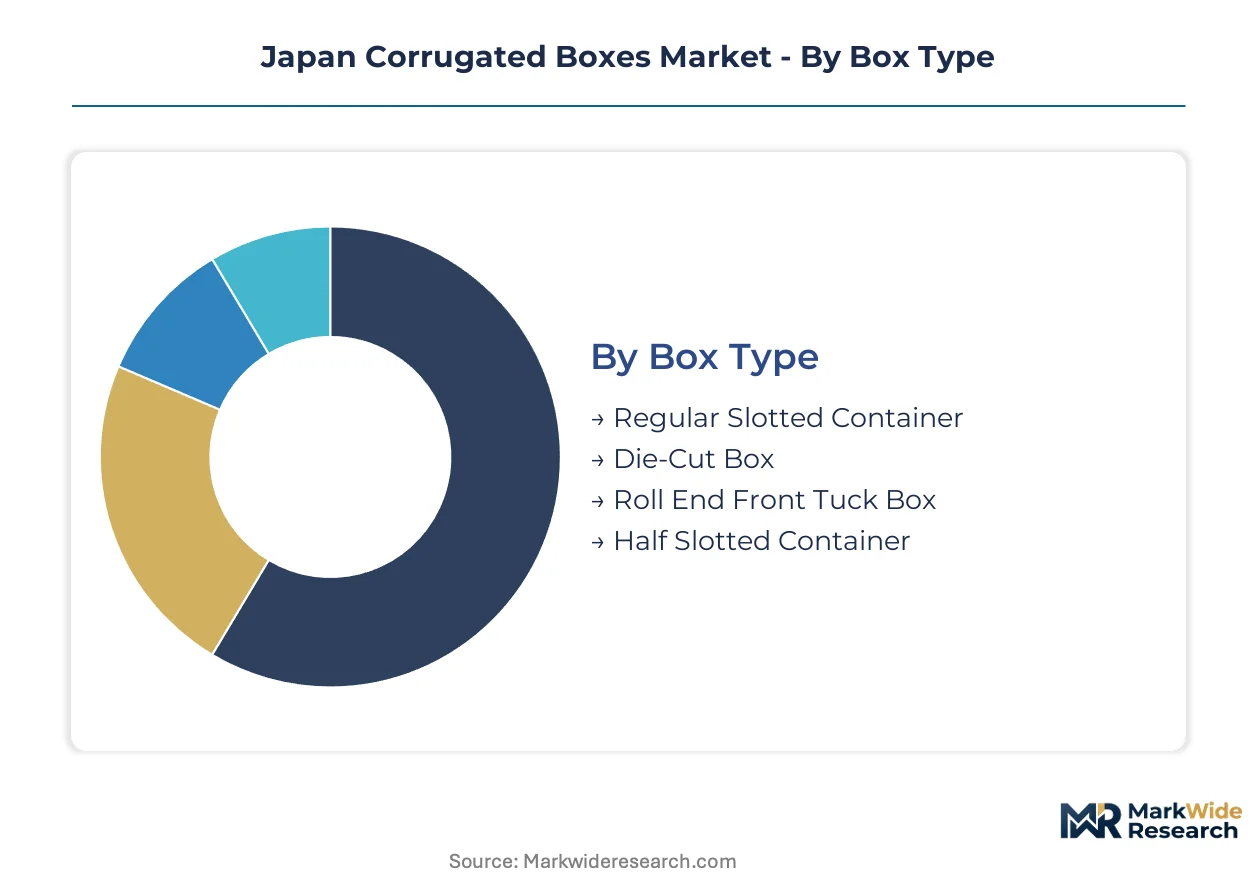
Segmentation in Japan's corrugated boxes market reveals how packaging specifications diverge across fulfillment channels. Channel-specific requirements from pharmaceutical serialization to retail-ready cosmetics presentation create distinct procurement patterns that reshape converter specialization.
Box Type:
Channel mix varies sharply by box construction, with direct-to-consumer formats bypassing traditional wholesale aggregation while industrial specifications retain distributor intermediaries.
- Regular Slotted Container:Standard four-flap construction with manufacturer's joint closure dominates bulk industrial shipments. Tokyo and Yokohama logistics hubs specify these for palletized electronics exports to Southeast Asia where compression strength thresholds matter most.
- Die-Cut Box:Precision-cut formats with retail-ready presentation eliminate secondary unpacking for department store cosmetics distribution. Kirin and Suntory beverage networks specify these for premium product lines requiring shelf-facing aesthetics.
- Roll End Front Tuck Box:Self-locking front closure suits lightweight consumer goods fulfillment. E-commerce platforms in the Kanto corridor specify exact burst strength tolerances in direct procurement agreements.
- Half Slotted Container:Open-top construction with cover separates for heavy machinery components. Industrial exporters around Osaka and Nagoya favor these for JIS-certified export packaging requiring custom lid integration.
Regular Slotted Container dominates installed base. Die-Cut Box is where expansion concentrates.
End User:
Cost tier stratification separates commodity volume from premium certification requirements across end-use verticals.
- Food & Beverage:Temperature-resistant specifications for chilled distribution networks. METI's container recycling targets drive fiber provenance documentation for government procurement eligibility.
- Electronics:Anti-static coatings and precision-fit cushioning for semiconductor shipments. Double-wall formats gain ground for Southeast Asia exports despite recycled fiber quality constraints.
- Cosmetics:Premium die-cut specifications with high-resolution print registration for department store presentation. Beauty brands specify exact color matching tolerances in master service agreements.
- E-Commerce:Lightweight high-strength boards reduce per-unit freight charges across last-mile networks. Platform-owned specifications now displace trading company intermediaries in Tokyo same-day fulfillment.
Food & Beverage anchors volume throughput. E-Commerce is climbing the fastest.
Thickness:
Application severity dictates wall construction, with export certification requirements forcing grade escalation in industrial corridors.
- Single Wall:One fluted medium between linerboard facings captures standard e-commerce and grocery volume. Kanto fulfillment networks specify these for domestic shipments under 15 kilograms.
- Double Wall:Two fluted layers for electronics and precision machinery exports. Rising post-consumer OCC contamination rates in Japan limit burst strength achievement for certified export packaging.
- Triple Wall:Three fluted layers meet JIS compression strength mandates for heavy industrial machinery. Premium pricing dynamics unwind as exporters absorb certification costs for Southeast Asian markets.
- Heavy Duty:Reinforced constructions exceeding standard triple-wall ratings for exceptional load requirements. Specialized applications in Hokkaido mill operations and automotive component distribution.
Single Wall dominates tonnage. Triple Wall is gaining share fastest.
Supply Chain:
Customer type determines channel length, with platform direct procurement shortening traditional wholesaler-distributor chains.
- Manufacturers:Integrated pulp-to-box producers like Oji Holdings control input costs through captive Hokkaido mill supply. Direct relationships with major e-commerce platforms bypass traditional trading company aggregation.
- Wholesalers:Trading companies that previously aggregated fragmented buyer demand now face displacement. Surviving intermediaries specialize in JIT replenishment for mid-tier converters lacking platform certification.
- Distributors:Regional logistics specialists manage inventory positioning for same-day delivery networks. Tokyo and Yokohama operations require real-time serialization tracking for pharmaceutical clients.
- Retailers:Department stores and mass merchandisers specify retail-ready formats with exact print registration. Cosmetics and premium beverage categories drive die-cut box procurement through direct brand negotiations.
Manufacturers dominate value capture. Distributors is where channel investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-box manufacturing concentrates in Hokkaido mill operations while final box production clusters around Tokyo-Yokohama logistics hubs. This geographic split shapes cost structures across Japanese corrugated supply chains.
Kanto/Tokyo
E-commerce fulfillment networks multiply box touches per shipment across same-day delivery corridors. METI's carbon-reduction targets elevate demand for lightweight high-strength specifications. Tokyo and Yokohama logistics hubs specify exact burst strength tolerances in direct procurement agreements with tier-one corrugators.
Kansai/Osaka
Industrial machinery exporters favor heavy-duty triple-wall formats meeting JIS compression strength mandates. Aging workforces struggle to replenish specialized corrugator technician skills for steam-heated roller calibration. Osaka and Nagoya manufacturing belts anchor JIS-certified export packaging for Southeast Asian markets.
Chubu/Nagoya
Automotive component distribution drives reinforced heavy-duty constructions exceeding standard ratings. Legacy ERP integration friction complicates serialization systems demanded by pharmaceutical clients. Regional converters face displacement as platform direct procurement shortens traditional wholesaler channels.
Hokkaido
Captive kraft pulp supply from integrated mill operations controls input costs for backward-integrated producers. Energy cost spikes at pulp mills compress margins despite captive fiber access. Hokkaido-based linerboard production feeds downstream box manufacturing across Honshu industrial corridors.
Kyushu
Electronics exports to Southeast Asia gain double-wall format share despite recycled fiber quality constraints. Post-consumer OCC streams show rising contamination rates limiting burst strength achievement. Regional logistics specialists manage inventory positioning for pharmaceutical serialization compliance.
Japan Corrugated Boxes Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Japanese corrugated boxes market. Integrated pulp-to-box manufacturers control upstream fiber costs while specialized converters capture premium specifications through certification depth. Three archetypes dominate: backward-integrated giants with captive mill supply, mid-tier regional converters serving local industrial clusters, and niche specialists in pharmaceutical serialization and retail-ready formats. Competitive moves center on direct platform procurement relationships displacing trading company intermediaries, and certified recycling stream documentation ahead of anticipated mandate expansion.
Among integrated producers, Oji Holdings Corporation, Rengo Co., Ltd., and Nippon Paper Group Inc. occupy positions reflecting distinct strategic emphases. Oji Holdings exemplifies the backward-integrated archetype through Hokkaido mill operations. Rengo Co., Ltd. anchors specialized beverage packaging relationships. Nippon Paper Group Inc. represents high-strength lightweight technology positioning. These three entities collectively illustrate how scale, specialization, and vertical control segment competitive space.
| Leading Market Players |
|---|
| Yamakoh Co., Ltd. |
| Dynapac Co., Ltd. |
| Rengo Co., Ltd. |
| Japan Pulp & Paper Company Co. Ltd. |
| ISOWA Corporation |
| Oji Holdings Corporation |
| Tomoku Co., Ltd. |
| TPG (HK) Ltd. |
| Nippon Paper Group Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between integrated pulp producers and Kanto-based corrugators lock in linerboard supply access while fixing input cost visibility across volatile energy markets. These contracts insulate backward-integrated players from spot OCC price swings while exposing non-integrated converters to margin compression when recycled fiber quality degrades.
Pricing Analysis
METI's Resource Circulation Strategy for Plastics dictates the pricing tier structure across Japan's corrugated box market. Three-tier pricing stratifies across pharmaceutical-grade certified packaging, industrial JIS-certified export specifications, and commodity e-commerce volume. Price differentiation hinges on compression strength certification and fiber provenance documentation. Pricing pressure stems from energy cost spikes at Hokkaido pulp mills compressing margins for captive supply operators. E-commerce platforms exhibit highest price sensitivity due to direct procurement scale, while pharmaceutical clients accept premium positioning for serialization compliance.
Supply Chain Analysis
Japan and Southeast Asian manufacturing clusters anchor containerboard supply for domestic box production. Raw material flows draw from Hokkaido kraft pulp mills, imported linerboard from Indonesia, and post-consumer OCC streams showing rising contamination rates. Single-source vulnerability concentrates in energy-intensive pulp production where gas price volatility feeds directly through input costs. Distribution runs through platform-direct procurement channels displacing traditional Tokyo trading company intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's corrugated box market sits in early-cycle recovery as e-commerce fulfillment volumes rebound from prior-period logistics normalization. Export packaging certification requirements and METI mandate expansion provide cyclical uplift for premium specification producers.
For Market Incumbents: Shield margin position through captive Hokkaido pulp supply expansion and pharmaceutical serialization certification depth. Energy cost volatility at integrated mills threatens cost leadership; counter through high-strength lightweight board R&D that reduces freight charges per unit. Secure direct platform procurement relationships before trading company displacement accelerates across Kanto fulfillment networks.
For New Entrants and Emerging Players: Retail-ready die-cut specifications for cosmetics brands represent an under-served service layer where incumbents lack print registration precision. Target department store distribution channels in Tokyo requiring exact color matching tolerances. Enter through specialized beverage packaging formats serving regional craft producers outside Kirin-Suntory network capture.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with certified recycling stream documentation. Five-to-ten-year viability hinges on METI mandate hardening from voluntary to binding thresholds. Watch for blockchain-tracked batch record adoption rates among pharmaceutical packaging segments as inflection signal for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linerboard Production | Hokkaido mill operations control input costs against energy price volatility at captive pulp facilities. |
| Pharmaceutical Serialization Certification | PMDA traceability requirements elevate box labeling standards for premium supplier positioning. |
| Direct Platform Procurement Relationships | Tokyo e-commerce networks bypass trading company intermediaries with exact burst strength specifications. |
| Recycled Content Supply Chain Documentation | METI container recycling targets reward early movers with certified fiber provenance systems. |
| High-Strength Lightweight Technology Investment | Cosmetics and electronics exporters adopt boards that reduce freight charges per shipment. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with corrugator plant managers, beverage procurement leads at Kirin and Suntory, e-commerce platform logistics officers, and pharmaceutical packaging compliance directors. Secondary validation drew from METI regulatory filings, JIS standard documentation, Japan Paper Association production statistics, and customs trade records for linerboard imports. Bottom-up volume estimates from individual converter capacity were triangulated against top-down pulp consumption data.
Across the analysis window, forecasts employed a segmented growth model tracking box type, end-use vertical, wall thickness specification, and supply chain channel. CAGRs were derived from elasticity-adjusted demand projections tied to e-commerce penetration curves and export shipment indices. Energy cost assumptions at Hokkaido mills and recycled fiber quality degradation rates informed margin compression scenarios for double-wall formats.
Material uncertainties — regulatory mandate timing, energy price trajectories, and post-consumer OCC contamination trends — sit outside the modeled envelope. Forecasts reflect assumptions about METI enforcement intensity and platform procurement consolidation speed. Recalibration cycles align with material shifts in carbon-reduction target stringency and pharmaceutical serialization adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Tablet Cartons Market
Cartons
Folding Carton in Healthcare Market
Cartons
Folding Cartons Market
Cartons
Luxury Folding Carton Market
Cartons
Mailers Market
Cartons
Liquid Packaging Cartons Market
Cartons
Fully Enclosed Cartons Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Carton Form Fill Seal Machine Market
Cartons
Cupcake Box Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Shaped Liquid Cartons Market
Cartons
Africa Folding Carton Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Tuck Top Box Market