
 Global Blister Packaging Machinery Market | 2026-2036
Global Blister Packaging Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blister Packaging Machinery Market Analysis
Direct-to-pharma OEM supply is rewriting how blister packaging machinery reaches end users. Uhlmann Group leverages its integrated service network to anchor high-value contracts across European pharmaceutical corridors. IMA Group competes through modular platform architectures that reduce changeover times for multi-product facilities. Marchesini Group specializes in complete packaging lines, extending its influence from machinery into line-integration consulting.
Blister packaging machinery forms, seals, and cuts thermoplastic or cold-form foil webs around products at speeds reaching 1,200 blisters per minute, serving primary containment and tamper-evidence functions for dose-sensitive goods. Thermoforming machines dominate installed base volumes due to lower tooling costs and material versatility, while cold forming equipment commands premium positioning for moisture-sensitive pharmaceuticals where aluminum-barrier integrity is non-negotiable. Automatic technology lines capture the bulk of new capital expenditure as labor-cost arbitrage fades against throughput and compliance requirements.
FDA 21 CFR Part 11, EU MDR, and EMA serialization directives are elevating validation documentation and machine-level data integrity to purchase prerequisites, effectively filtering non-compliant vendors from regulated supply chains. China's NMPA alignment with ICH Q9 quality risk management is creating parallel compliance obligations for machinery serving export-oriented domestic pharma. Stakeholders must weigh track-and-trace integration depth against total cost of ownership when specifying next-generation platform investments.
Market Dynamics
Serialization mandates from FDA and EU MDR are forcing pharmaceutical manufacturers to replace legacy blister lines with track-and-trace-capable machinery, compressing replacement cycles and elevating validation requirements to purchase prerequisites.
Growth Catalysts
- EU MDR traceability rules:European medical device regulations mandate unique device identification on primary packaging, driving machinery upgrades across German and Italian pharma manufacturing corridors.
- India's PLI scheme for pharmaceuticals:Production-linked incentives are expanding domestic packaging capacity, creating fresh demand for high-speed thermoforming equipment in Mumbai and Hyderabad clusters.
- Biologics packaging requirements:Cold-form aluminum barrier demand is accelerating for moisture-sensitive injectables, pulling premium machinery investments from specialized biotech facilities.
Market Restraints
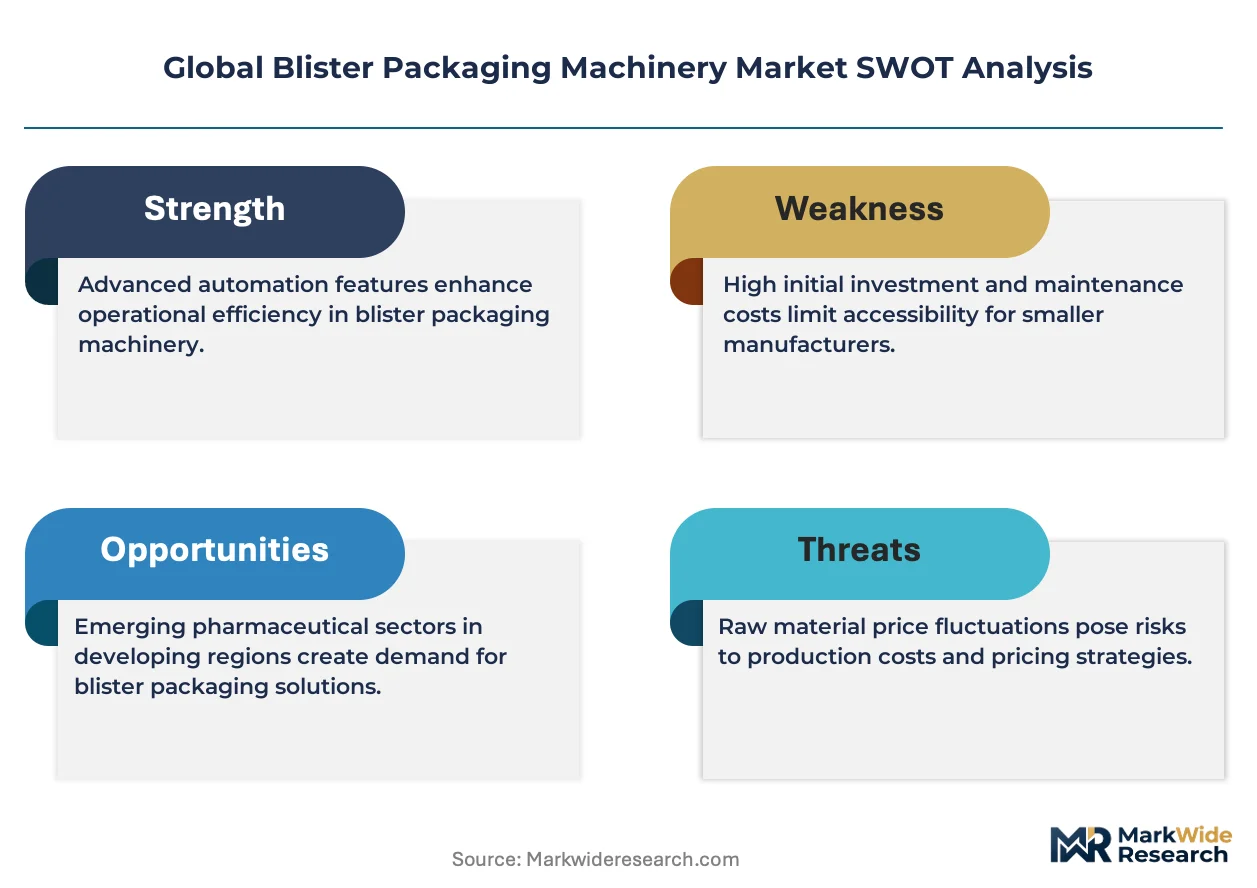
- Stainless steel and servo motor cost volatility:Input price swings for precision components compress OEM margins and extend quotation validity periods.
- Validation documentation burden:FDA 21 CFR Part 11 compliance requirements lengthen sales cycles and disqualify smaller vendors from regulated supply chains.
- Flexible pouch alternatives:Stick pack and sachet formats capture share in OTC nutraceuticals where barrier demands permit lighter containment.
Strategic Opportunities
- Brazil's ANVISA alignment with ICH standards:Regulatory harmonization opens export-oriented machinery supply from European OEMs into São Paulo's expanding pharma hub.
- Continuous manufacturing integration:Real-time release testing and direct compression lines demand blister machinery with in-line weight verification and automated rejection systems.
- Service contract unbundling:Predictive maintenance subscriptions and remote diagnostics create recurring revenue streams separate from capital equipment sales.
Industry Challenges
- Mechatronics and validation engineering talent scarcity:Cross-disciplinary expertise combining mechanical design, PLC programming, and GAMP 5 documentation is concentrated among senior specialists in southern Germany and northern Italy.
- Legacy line integration complexity:Brownfield pharmaceutical facilities require machinery retrofits that synchronize with existing cartoning and serialization islands without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blister Packaging Machinery Market |
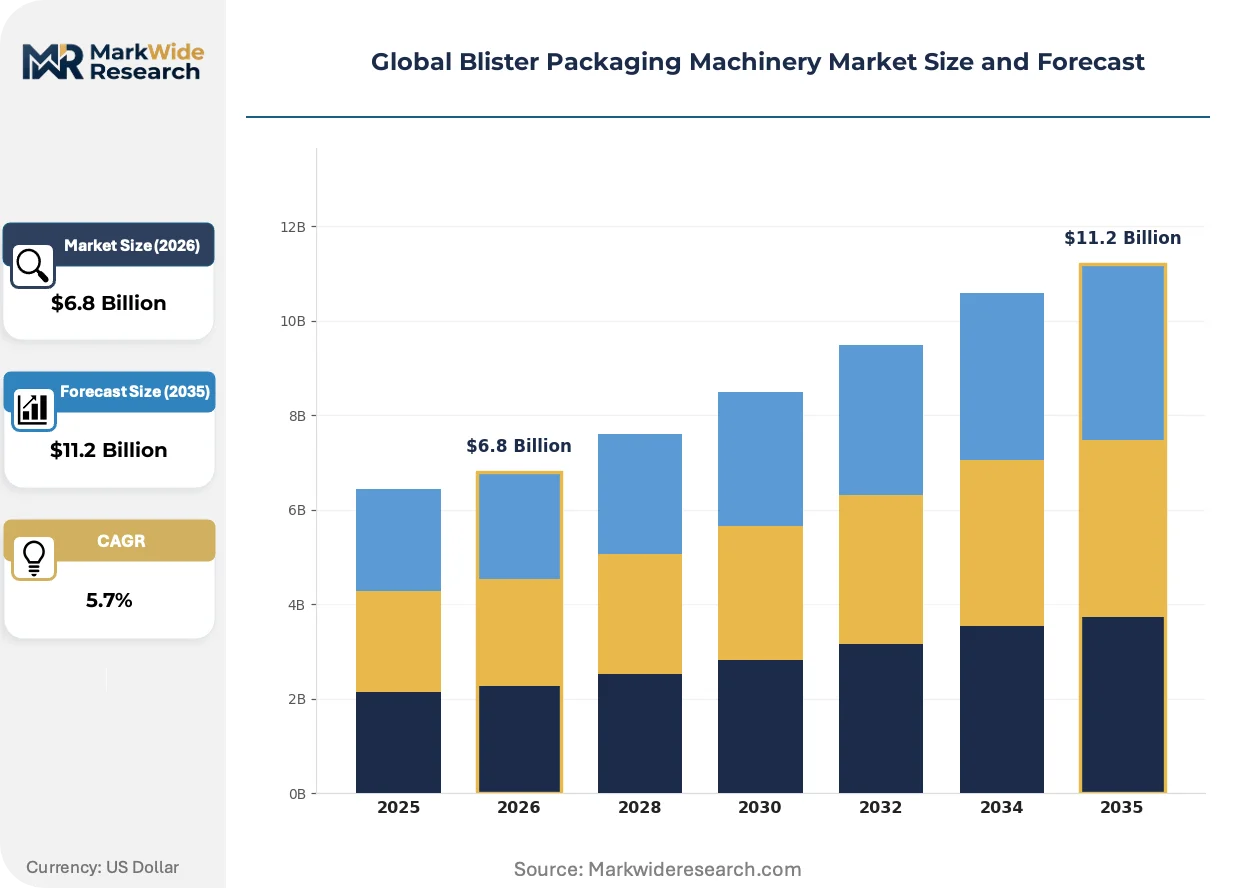
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoforming Machines, Cold Forming Machines, High-Speed Machines, Modified Atmosphere Packaging Machines End User: Pharmaceuticals, Food, Cosmetics, Electronics Technology: Automatic, Semi-Automatic, Manual, Digital Application: Packaging Solutions, Product Display, Unit Dose Packaging, Retail Packaging |
| Companies Covered | Uhlmann Group, IMA Group, Marchesini Group, Romaco Group, Mediseal GmbH, Hoonga Co., Ltd., ACG Pampac, CAM Packaging Machines, Körber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blister Packaging Machinery Market Emerging Trajectories
Digital thread technologies and sustainable material transitions are converging to redefine machinery specifications, with pharmaceutical OEMs now demanding platforms that simultaneously reduce carbon footprint and enable regulatory audit trails.
Modular servo-driven forming stations are hybridizing mechanical and electronic control architectures to enable format changeovers without tool replacement. Mid-sized contract manufacturers in Spain and Poland are adopting these configurations to run multiple SKUs on shared lines. The technology is compressing downtime economics and expanding viable batch size ranges for multi-product facilities.
EMA serialization directives and FDA's DSCSA enforcement timeline are mandating aggregation capabilities at the bundle and case level. Machinery suppliers must now integrate vision systems and database connectivity as standard rather than optional configurations. German and Swiss OEMs are capturing premium positioning by pre-validating these interfaces against major track-and-trace software platforms.
Buying committees are consolidating vendor relationships around full-line integration competence rather than standalone machinery specifications. Pharmaceutical procurement teams in China and India are favoring suppliers offering turnkey validation packages and local spare parts logistics. This behavior is visible most acutely among generic drug manufacturers expanding capacity for US and EU export markets.
Global Blister Packaging Machinery Market Segmentation
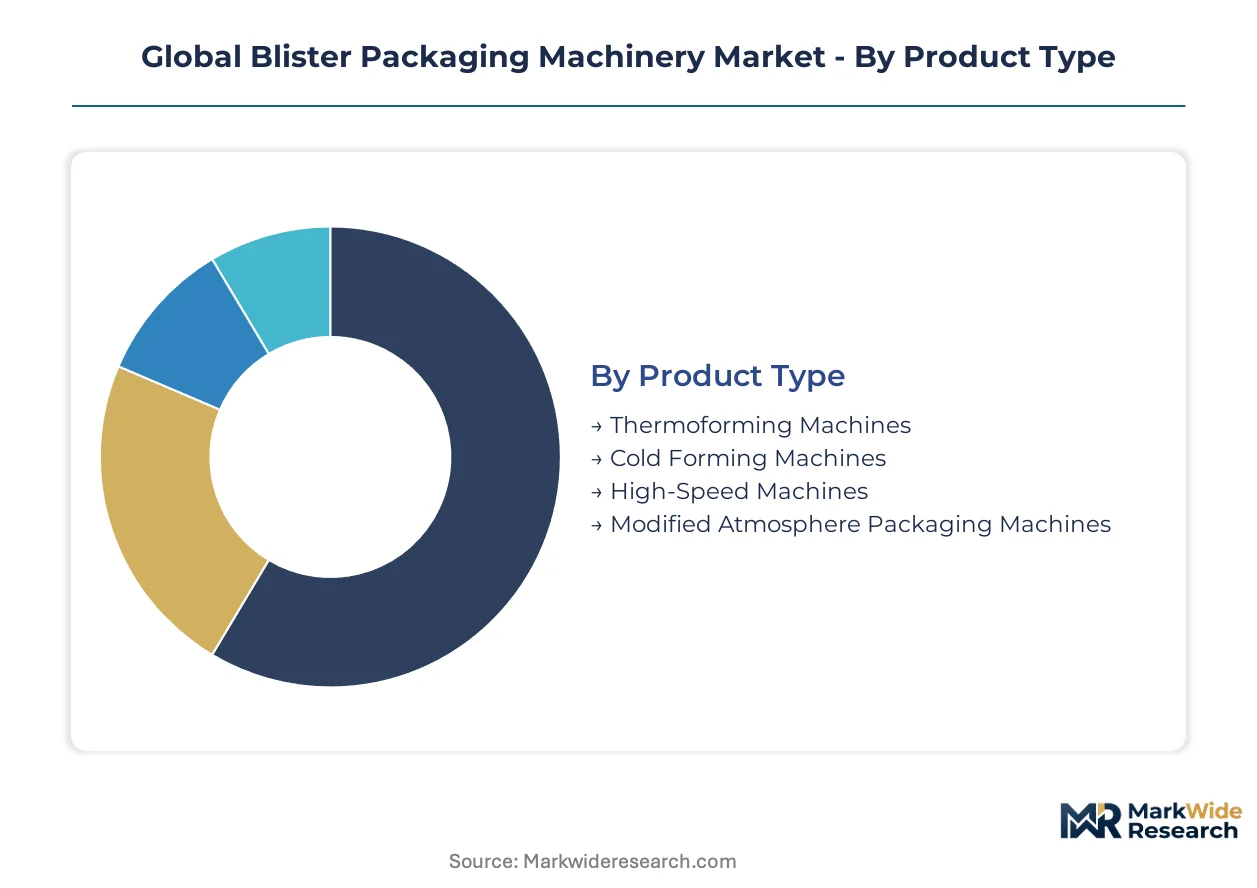
Blister packaging machinery segmentation reveals distinct service intensity patterns across equipment categories. Pharmaceutical OEMs prioritize validation documentation and spare parts availability, creating divergent margin profiles between high-touch and commodity segments.
Product Type:
After-sales service intensity varies sharply across equipment architectures, with cold-forming platforms demanding specialized technician deployment while thermoforming units rely on remote diagnostics.
- Thermoforming Machines:These systems heat and vacuum-form PVC, PET, or PP webs around products at speeds exceeding 1,200 blisters per minute. Demand concentrates in Indian and Chinese generic pharmaceutical corridors where CDSCO and NMPA compliance requirements favor lower tooling costs and rapid format changeovers.
- Cold Forming Machines:Aluminum-barrier systems press-form laminated foil webs without heat, preserving moisture-sensitive biologics. European biotech facilities in Germany and Switzerland drive premium positioning, with EMA stability requirements mandating Swissmedic-level validation documentation that extends sales cycles.
- High-Speed Machines:Continuous-motion architectures achieve outputs above 1,500 blisters per minute for high-volume OTC production in Brazilian and Mexican facilities.
- Modified Atmosphere Packaging Machines:Gas-flush systems extend shelf life for probiotic nutraceuticals, finding niche adoption in Japanese and South Korean health supplement manufacturing.
Thermoforming machines hold the largest share; momentum sits with cold forming equipment.
End User:
Cost tier stratification separates validation-heavy pharmaceutical procurement from price-sensitive food and cosmetic applications.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU MDR traceability mandates force serialization-capable machinery investments. German and Italian OEMs anchor high-value contracts through integrated validation packages and local service networks.
- Food:Modified atmosphere and thermoforming systems package fresh proteins and dairy, with demand clustering in Brazilian and Australian export-oriented processing facilities.
- Cosmetics:Premium skincare blister packs emphasize tamper-evidence and shelf appeal, serving French and Korean beauty brand manufacturing.
- Electronics:Anti-static blister formats protect semiconductors and components, concentrated in Taiwanese and Malaysian electronics assembly corridors.
Pharmaceuticals command premium pricing tiers; cosmetics and food segments expand most quickly in emerging manufacturing clusters.
Technology:
Volume concentration favors automatic lines as labor-cost arbitrage fades against throughput and compliance requirements.
- Automatic:Servo-driven forming, sealing, and cutting stations operate with minimal operator intervention, capturing bulk capital expenditure in Chinese and Indian export-oriented pharma facilities.
- Semi-Automatic:Hybrid configurations suit mid-sized contract manufacturers in Poland and Spain running multiple SKUs on shared equipment.
- Manual:Hand-fed systems persist in artisanal cosmetic and specialty food production where batch sizes preclude automation economics.
- Digital:IIoT-enabled platforms with predictive maintenance and remote diagnostics create recurring revenue streams separate from capital sales.
Automatic technology dominates installed value; digital platforms gain share fastest among OEMs unbundling service contracts.
Application:
Customer type differentiation separates regulated pharmaceutical procurement from retail-driven display packaging.
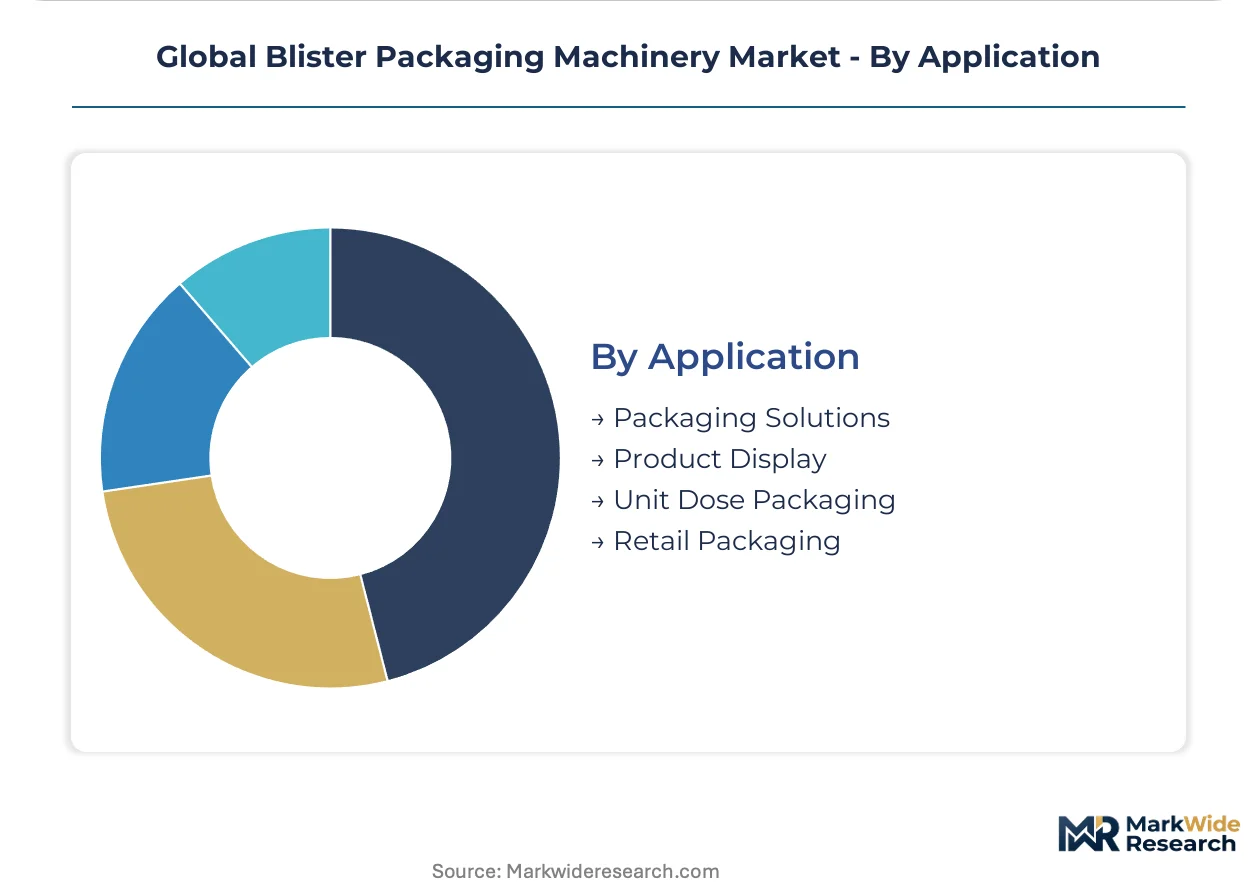
- Packaging Solutions:Integrated forming-cartoning-serialization lines serve high-volume pharmaceutical manufacturing in Germany and the United States.
- Product Display:Clamshell and face-seal formats emphasize shelf visibility for consumer electronics and cosmetics in Japanese and UAE retail markets.
- Unit Dose Packaging:Individual blister cavities enable medication adherence programs and hospital automation, expanding across NHS and Medicare reimbursement systems.
- Retail Packaging:Hang-hole and peg-hook configurations serve mass-market OTC distribution in Brazilian and Indian pharmacy chains.
Packaging solutions capture the largest revenue pool; unit dose applications climb the fastest on adherence program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium machinery pricing in Germany and Switzerland commands 40-60% premiums over functionally comparable equipment from Indian and Chinese fabricators. This asymmetry reflects validation documentation depth, spare parts logistics density, and installed base service penetration rather than mechanical performance alone.
Germany
Domestic pharma OEMs and export-oriented machinery builders drive sustained demand for high-speed thermoforming and cold-forming platforms. EU MDR traceability mandates and FDA 21 CFR Part 11 compliance requirements filter vendor selection toward established German OEMs with pre-validated software interfaces. The Baden-Württemberg and Bavaria corridors concentrate precision engineering talent and GAMP 5 documentation expertise.
China
NMPA alignment with ICH Q9 quality risk management is forcing domestic generic manufacturers to upgrade from basic thermoforming equipment to serialization-capable lines. Production-linked incentive schemes for pharmaceutical exports are expanding packaging capacity in Jiangsu and Zhejiang provinces. Yangtze River Delta clusters are absorbing European validation methodologies to serve FDA-inspected facilities.
India
CDSCO's tightening GMP enforcement and USFDA inspection intensity are compressing replacement cycles for legacy blister lines. The PLI scheme for pharmaceuticals is channeling capital expenditure toward high-speed automatic equipment in Mumbai and Hyderabad manufacturing belts. Contract research and manufacturing organizations are consolidating vendor relationships around turnkey validation packages.
United States
DSCSA enforcement timelines are mandating aggregation capabilities at bundle and case levels, elevating machinery specifications for domestic generic manufacturers. FDA serialization directives disqualify non-compliant vendors from regulated supply chains. New Jersey and North Carolina pharmaceutical corridors are prioritizing track-and-trace integration depth in procurement decisions.
Brazil
ANVISA's progressive alignment with ICH standards is opening export-oriented machinery supply from European OEMs into São Paulo's expanding pharma hub. Domestic manufacturers serving Mercosur markets are upgrading from semi-automatic to automatic lines to meet stability and traceability requirements. The São Paulo state cluster is absorbing validation protocols previously restricted to FDA-regulated facilities.
Global Blister Packaging Machinery Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying forming stations, sealing modules, and vision systems to multiple OEMs. The vendor base stratifies into three tiers: full-line integrators with validation consulting capabilities, modular platform builders optimizing changeover economics, and regional fabricators competing on capital cost. Consolidation pressure concentrates among mid-tier European specialists seeking scale to amortize compliance documentation investments. Geographic expansion and technology licensing represent the dominant competitive vectors as OEMs seek local spare parts logistics in growth markets.
Within the full-line integration tier, Uhlmann Group and Marchesini Group exemplify the validation-heavy service model anchoring high-value contracts across European pharmaceutical corridors. IMA Group occupies a position emphasizing modular platform architectures that reduce changeover times for multi-product facilities. These three entities represent distinct strategic postures: integrated service networks, line-integration consulting extension, and modular equipment standardization respectively.
| Leading Market Players |
|---|
| Uhlmann Group |
| IMA Group |
| Marchesini Group |
| Romaco Group |
| Mediseal GmbH |
| Hoonga Co., Ltd. |
| ACG Pampac |
| CAM Packaging Machines |
| Körber |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Indian and Chinese thermoforming component fabrication is compressing quotation validity periods and forcing European OEMs to extend lead-time premiums. This utilization squeeze simultaneously elevates spot-market pricing for stainless steel servo assemblies and concentrates procurement leverage among fabricators with captive foundry capacity.
Pricing Analysis
The customization-premium spread separates configured-to-order cold-forming platforms from standard thermoforming units by margins reflecting GAMP 5 documentation depth and Swissmedic-level validation. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 21 CFR Part 11 pre-certification status, with German and Swiss OEMs commanding top tiers. Cost compression in economy-tier equipment is intensifying because Indian fabricators are absorbing European validation methodologies. Generic pharmaceutical manufacturers in Mumbai and Hyderabad clusters exhibit highest price sensitivity; biotech facilities in Basel and Munich corridors show lowest.
Supply Chain Analysis
Export-control regimes restricting servo motor and precision motion-controller flows from Germany and Switzerland to certain Asian markets are fragmenting component sourcing strategies. Supply concentrates in southern Germany for forming stations, northern Italy for sealing modules, and Yangtze River Delta clusters for auxiliary electronics. Precision ball screws, vacuum pumps, and HMI panels draw from Japanese and Taiwanese specialists. Single-source vulnerability around German-built servo drives creates chokepoint exposure. Distribution runs through OEM-direct channels for pharmaceutical accounts and regional distributors for food and cosmetic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against flexible pouch and stick-pack formats capturing OTC nutraceutical share where barrier requirements permit lighter containment.
For Market Incumbents: Entrench validation documentation superiority by embedding GAMP 5 expertise into standard platform offerings rather than treating compliance as aftermarket consulting. Acquire Polish or Spanish service operations to compress spare parts logistics density in mid-sized contract manufacturing corridors. Cold-forming equipment specialization insulates against thermoforming commoditization pressure from Asian fabricators. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA-aligned pharmaceutical corridor by pre-validating thermoforming platforms against ICH Q9 quality risk management protocols. Target semi-automatic equipment upgrades among São Paulo generic manufacturers transitioning from Mercosur-only to export-oriented production. Lead with remote diagnostics subscriptions to bypass capital-intensive field service infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across serialization-capable platform development as vision systems and aggregation software become standard rather than optional configurations. Mid-tier European specialists with incomplete validation consulting capabilities represent consolidation targets. Watch FDA DSCSA enforcement intensity as signal for replacement cycle acceleration versus compression.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Documentation Unbundling | GAMP 5 expertise sold separately from hardware creates recurring revenue streams for German OEMs. |
| Remote Diagnostics Platform Launch | Predictive maintenance subscriptions reduce customer total cost of ownership while locking spare parts procurement. |
| Continuous Manufacturing Integration | In-line weight verification and automated rejection systems align blister machinery with real-time release testing lines. |
| Regional Service Hub Expansion | Local spare parts logistics in Mumbai and Hyderabad corridors satisfy CDSCO inspection intensity requirements. |
| Sustainable Material Transition Partnership | Collaboration with bio-based film suppliers addresses pharmaceutical OEM carbon footprint reduction mandates. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical packaging engineers, GMP compliance officers, machinery procurement directors, and aftermarket service managers and refined through secondary validation against FDA 483 inspection observations, EMA manufacturing authorization records, CDSCO GMP compliance reports, and OEM technical documentation. Bottom-up equipment shipment tracking and top-down pharmaceutical capital expenditure analysis were triangulated to anchor volume estimates.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, end-user industry, technology tier, and regional regulatory cluster. CAGRs were derived from installed base replacement cycle analysis and greenfield capacity absorption rates. Forecast inputs incorporated NMPA alignment timelines with ICH standards and PLI scheme disbursement velocity in Indian pharmaceutical corridors.
Stress conditions across stainless steel price volatility, servo motor lead-time extension, and FDA inspection intensity fluctuation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization pace and generic pharmaceutical export growth trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Automated Poly Bagging Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market