
 Liquid Packaging Cartons Market | 2026-2036
Liquid Packaging Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Packaging Cartons Market Intelligence
The capital-intensity divergence between integrated pulp-to-carton producers and converters reliant on external board supply is unwinding competitive stability in liquid packaging cartons. Tetra Pak International S.A. leverages in-house aseptic filling equipment sales to lock in carton demand across dairy chains. SIG Combibloc Group AG anchors its position through regional manufacturing scale in Europe and Asia. Stora Enso competes via backward integration into renewable fiber sourcing.
Liquid packaging cartons are multi-layer paperboard containers, typically comprising 70-80% fiber with aluminum foil and polyethylene barrier layers, formed through roll-fed aseptic forming and sealing processes to preserve shelf-stable beverages without refrigeration. Composites dominate material value capture due to their superior oxygen and light barrier performance, while cardboard segments face margin compression from virgin fiber cost volatility. Dairy leads end-user demand structurally, though beverages represents the fastest-growing application as ambient plant-based drinks expand retail shelf presence.
EU Green Deal packaging mandates and FDA food-contact substance notifications shape product development cycles, with REACH compliance requirements for adhesives and coatings adding formulation complexity for exporters. China's SAMR national food safety standards and GB labeling rules govern market access for imported carton systems. Stakeholders must monitor evolving extended producer responsibility frameworks and fiber traceability certification demands as regulatory compliance becomes a primary vendor selection criterion.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing dairy processors across Germany, France, and the Netherlands to abandon multilayer plastic formats and adopt fiber-based aseptic cartons, rewiring supplier-buyer contracting patterns and capital allocation timelines throughout the value chain.
Growth Catalysts
- Ambient plant-based beverages:Oat, almond, and soy milk brands in China's Yangtze River Delta are converting production lines from PET bottles to carton formats, creating pull for roll-fed aseptic forming equipment.
- REACH compliance mandates:ECHA requirements for adhesive and coating formulations in food-contact applications are accelerating R&D investment in bio-based barrier technologies across European converter networks.
- Extended-shelf-life milk expansion:German dairy cooperatives are installing aseptic filling systems to serve discount retail chains demanding 90-day ambient distribution without cold-chain dependency.
Market Restraints
- Virgin fiber cost volatility:Northern European pulp mills face energy input spikes that transmit directly to liquid packaging board pricing, compressing converter margins during contract renegotiations.
- Aluminum foil supply concentration:Rolling capacity for the 6-7 micron barrier layers concentrates in a handful of European and Asian metallizers, creating single-source vulnerability for mid-tier carton producers.
- Mechanical recycling incompatibility:The polyethylene-aluminum-fiber composite structure resists standard pulping processes, limiting circular economy claims under EU Green Deal verification protocols.
Strategic Opportunities
- Indian ambient juice penetration:FSSAI food safety standards are formalizing carton quality benchmarks, enabling organized beverage brands to displace unorganized PET refill markets in Maharashtra and Karnataka.
- Paperboard barrier innovation:Convergence of aqueous coating technologies and high-barrier fiber formulations promises to eliminate aluminum layers entirely, unlocking home-compostable certification pathways.
- DTC subscription channels:Specialty oat milk brands in California and New York are bypassing traditional retail distribution through direct-to-consumer carton multipacks, demanding smaller format sizes and premium print finishes.
Industry Challenges
- Aseptic filling technician scarcity:The intersection of microbiological validation, hydraulics, and PLC programming creates a narrow labor pool, extending commissioning timelines for new dairy installations.
- Dual certification complexity:FDA food-contact substance notifications and EU 10/2011 plastic regulation compliance must run in parallel for exporters, doubling documentation burdens and testing costs.
- Legacy line retrofit friction:Converters running 1990s-era forming equipment face integration failures with modern quality control sensors and automated changeover systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Packaging Cartons Market |
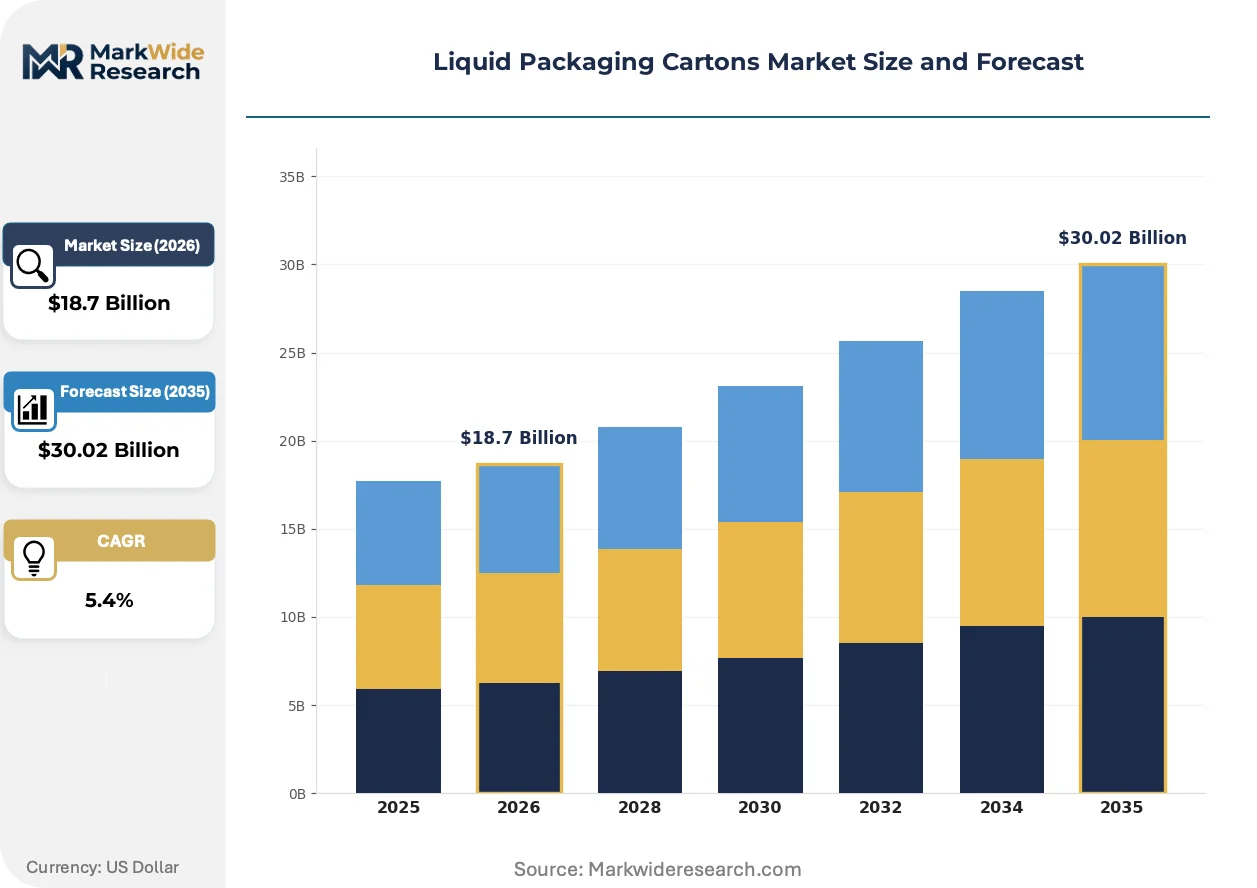
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Aluminum, Composites Closure Type: Screw Cap, Straw, Spout, Pull Tab End User: Dairy, Beverages, Sauces, Personal Care Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale |
| Companies Covered | Tetra Pak International S.A., SIG Combibloc Group AG, Elopak AS, Pactiv Evergreen Inc., Greatview Aseptic Packaging Co. Ltd., Mondi, Nippon Paper Industries Co. Ltd., WestRock Company, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Packaging Cartons Market Strategic Shifts & Innovations
Barrier material science and forming equipment digitization are converging to redefine liquid packaging carton performance standards, while regulatory pressure on recyclability accelerates format experimentation across dairy and beverage categories.
Mono-material polyethylene structures with enhanced oxygen scavenging functionality are decomposing the traditional aluminum-PE-fiber laminate hierarchy. German beverage brands testing these films in chilled juice applications report comparable shelf-life performance at reduced material cost. The technology is decomposing incumbent converter margins by enabling in-house film extrusion and reducing dependency on metallized substrate suppliers.
EU Green Deal packaging mandates require 70% recyclability rates by 2030, forcing carton producers to redesign layer adhesives and eliminate dark pigments that contaminate repulping streams. Dairy processors in Denmark and Sweden are now specifying full-fiber certification from suppliers as a contract prerequisite. The regulation is compressing R&D cycles and privileging vertically integrated pulp-to-carton producers with captive recycling infrastructure.
Retail buyers in China's SAMR-regulated market are consolidating carton procurement through centralized e-commerce platforms, disintermediating traditional distributor networks. Alibaba and JD.com beverage category managers now specify lot-level traceability via QR-coded cartons, shifting quality accountability upstream to converters. This concentration is most visible in ambient soy milk, where three platforms account for the majority of volume placement decisions in tier-one cities.
Liquid Packaging Cartons Market Segmentation
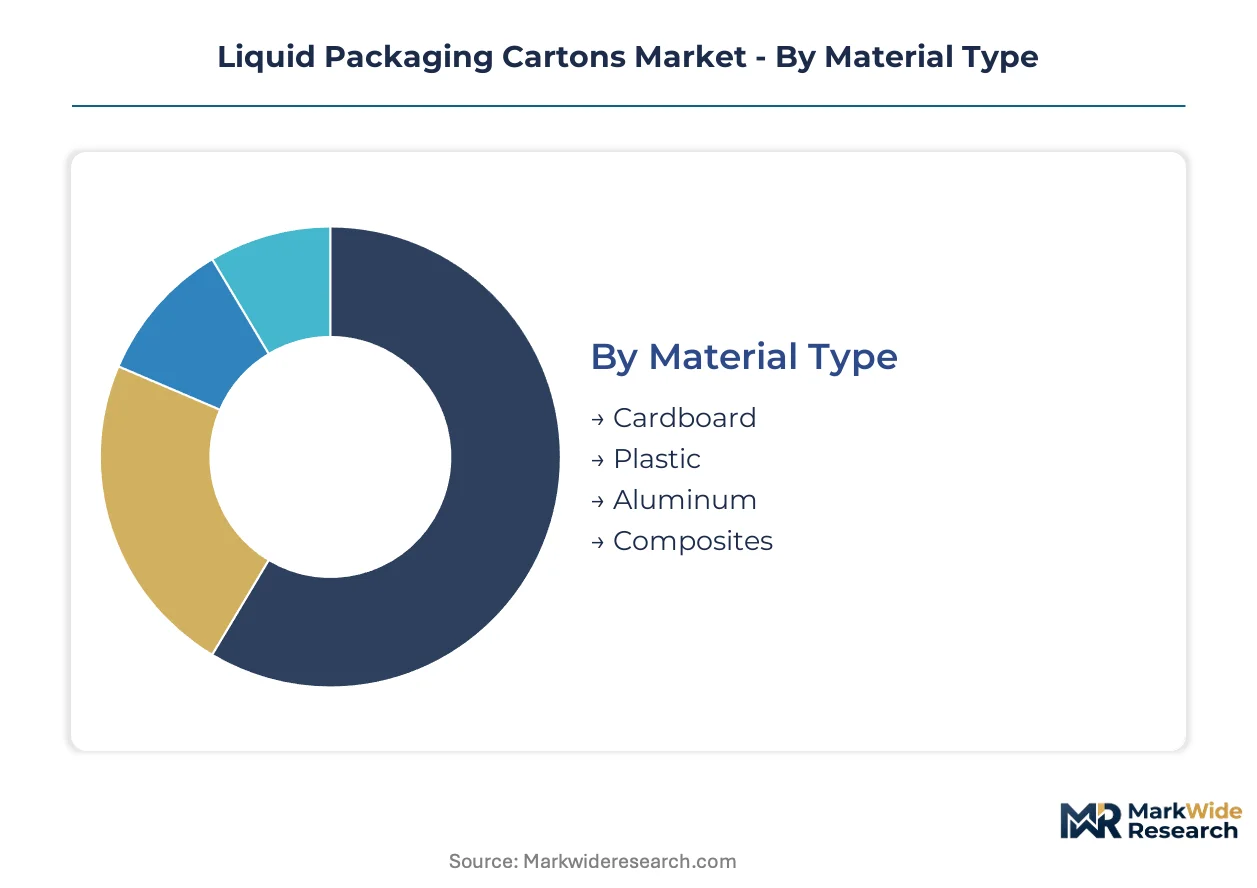
Segmentation in liquid packaging cartons reveals divergent margin structures and regulatory exposure profiles. Material composition determines recyclability compliance costs, while closure engineering shapes filling line capital requirements and brand differentiation potential.
Material Type:
Cardboard and composite segments serve predominantly domestic dairy markets in Germany and the Netherlands, while aluminum-dependent formats concentrate in export-oriented beverage supply chains reaching China's Yangtze River Delta.
- Composites:Multi-layer fiber-aluminum-polyethylene laminates deliver superior oxygen and light barrier performance for ambient shelf-stable distribution. Demand concentrates in China's beverage sector where oat and soy milk brands convert from PET to carton formats under SAMR food safety standards.
- Cardboard:Virgin fiber-based uncoated or single-polyethylene-coated boards serve chilled dairy applications with shorter shelf-life requirements. German dairy cooperatives specify these formats for discount retail chains under EU Packaging and Packaging Waste Regulation mandates, though margin pressure persists from Northern European pulp mill energy cost spikes.
- Plastic:Mono-material polyethylene structures with scavenging functionality are decomposing traditional laminate hierarchies in German chilled juice trials.
- Aluminum:Six to seven micron metallized barrier layers concentrate rolling capacity across limited European and Asian suppliers, creating single-source vulnerability for mid-tier converters.
Composites command the established base. The steepest expansion runs through cardboard as EU Green Deal recyclability mandates accelerate fiber-only certification pathways.
Closure Type:
Engineering complexity and unit economics stratify closure selection, with screw cap and spout formats capturing premium beverage positioning while straw and pull tab segments serve volume dairy and children's product lines.
- Screw Cap:Re-sealable threaded closures enable multi-serve consumption patterns and premium shelf positioning. California and New York specialty oat milk brands specify these for direct-to-consumer subscription multipacks, demanding smaller format sizes and high-definition print finishes.
- Spout:Integrated fitment closures support controlled pouring and on-the-go consumption. Indian organized beverage brands in Maharashtra and Karnataka adopt spout-equipped cartons to displace unorganized PET refill markets as FSSAI quality benchmarks formalize.
- Straw:Pre-attached flexible straws target children's dairy and juice segments with single-serve convenience.
- Pull Tab:Foil membrane tear-open designs minimize material cost in economy-tier ambient milk distribution.
Screw cap configurations anchor premium positioning. Spout adoption is climbing the fastest as ambient plant-based beverage formats expand retail shelf presence.
End User:
Application-driven demand splits between dairy's structural volume dominance and beverages' accelerating growth trajectory, with sauces and personal care representing niche expansion frontiers.
- Dairy:Extended-shelf-life and fresh milk applications consume the majority of aseptic carton volume, with German cooperatives installing filling systems to serve 90-day ambient distribution requirements.
- Beverages:Ambient plant-based drinks and functional juices drive format innovation, with China's Yangtze River Delta beverage brands leading PET-to-carton conversion.
- Sauces:High-acid and retort-stable food products utilize modified barrier specifications for shelf-stable condiment distribution.
- Personal Care:Liquid soap and cosmetic applications represent emerging carton adoption as brands seek plastic-alternative packaging credentials.
Dairy maintains volume leadership. Beverage applications are gaining share fastest through plant-based milk expansion.
Distribution Channel:
Channel structure determines lot-size requirements and traceability specifications, with retail and e-commerce platforms imposing divergent quality accountability frameworks on converters.
- Retail:Traditional supermarket and hypermarket procurement dominates volume placement, with Danish and Swedish dairy processors now specifying full-fiber certification as contract prerequisites.
- E-commerce:Alibaba and JD.com beverage category managers in China consolidate procurement through centralized platforms, mandating QR-coded lot-level traceability that shifts quality accountability upstream to converters.
- Direct Sales:Specialty brand subscription channels demand smaller format multipacks with premium print finishes.
- Wholesale:Institutional and foodservice bulk distribution prioritizes unit cost minimization over format differentiation.
Retail commands the established base. E-commerce is expanding most quickly as platform consolidation rewires supplier-buyer contracting patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany processes extended-shelf-life dairy through aseptic cartons while China converts beverage lines from PET, revealing a split between regulated dairy markets and format-switching beverage economies.
Germany
Dairy cooperatives in Lower Saxony and Bavaria install aseptic filling systems to supply discount retail chains with 90-day ambient milk. The EU Packaging and Packaging Waste Regulation mandates fiber-based formats, accelerating carton procurement timelines. The North Rhine-Westphalia industrial corridor hosts converter operations serving pan-European distribution networks.
China
Beverage brands in the Yangtze River Delta shift oat and soy milk production from PET bottles to carton formats under SAMR national food safety standards. GB labeling rules govern imported carton system approvals, tightening quality accountability. Alibaba and JD.com platforms now consolidate procurement decisions for tier-one city distribution.
India
Organized juice brands in Maharashtra and Karnataka adopt spout-equipped cartons to displace unorganized PET refill markets. FSSAI food safety standards formalize carton quality benchmarks, enabling branded penetration. The Mumbai-Pune industrial belt concentrates converter capacity for western India beverage distribution.
United States
Specialty oat milk brands in California and New York deploy direct-to-consumer subscription multipacks with premium print finishes. FDA food-contact substance notifications shape barrier material selection for plant-based beverages. The Pacific Northwest pulp supply chain feeds West Coast carton board production.
Sweden
Dairy processors specify full-fiber certification from suppliers as contract prerequisites under EU Green Deal recyclability mandates. REACH compliance requirements for adhesives and coatings drive bio-based barrier R&D investment. The Stockholm-Uppsala corridor anchors Nordic converter operations with captive recycling infrastructure.
Liquid Packaging Cartons Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with backward integration into renewable fiber and captive aseptic equipment sales determining competitive stability. The structure rewards players controlling pulp-to-carton production chains while compressing margins for board-dependent converters. Two archetypes dominate: vertically integrated fiber producers and equipment-locked dairy system suppliers. Capacity expansion in Asia and strategic partnerships for barrier technology access represent the primary competitive moves.
Among Switzerland-based integrated leaders, Tetra Pak International S.A. exemplifies the equipment-captive archetype through in-house aseptic filling system sales. SIG Combibloc Group AG occupies a parallel position with regional manufacturing scale across European and Asian markets. Finnish fiber-integrated player Stora Enso represents the upstream-control archetype through renewable fiber sourcing.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| SIG Combibloc Group AG |
| Elopak AS |
| Pactiv Evergreen Inc. |
| Greatview Aseptic Packaging Co. Ltd. |
| Mondi |
| Nippon Paper Industries Co. Ltd. |
| WestRock Company |
| Stora Enso |
| Others |
Cost & Logistics Intelligence
Aluminum foil substitution by aqueous-coated fiber barriers simultaneously redraws raw material sourcing maps and compresses converter margin structures across European and Asian production networks. This material transition fragments established supplier-buyer contracting patterns while creating pricing power for integrated pulp-to-board producers with captive barrier R&D capabilities.
Pricing Analysis
Aseptic filling equipment service contracts and spare parts programs capture lifetime value exceeding original hardware sales for integrated system suppliers. Three-tier pricing structure across premium certified, standard compliance, and economy uncoated board grades stratifies converter offerings, with EU Green Deal full-fiber certification commanding substantial premia over uncertified alternatives. Pricing pressure stems from Northern European pulp mill energy cost volatility transmitting directly to liquid packaging board contract renegotiations. Discount retail chains in Germany exhibit highest price sensitivity, while direct-to-consumer specialty beverage brands in California tolerate premium positioning for smaller format multipacks.
Supply Chain Analysis
Inbound logistics costs from Nordic pulp ports through Rotterdam and Hamburg container terminals shape converter landed cost structures for virgin fiber board. Supply concentrates in Finland, Sweden, and Germany for bleached pulp feedstock, while six-to-seven micron aluminum foil rolling capacity clusters in Germany, Japan, and South Korea. Raw material dependencies rest on Northern European softwood pulp, metallized barrier substrates, and food-grade polyethylene resins. Single-source vulnerability pervades mid-tier converter access to thin-gauge foil metallizers. Distribution runs through pan-European dairy processor networks and China's Alibaba-JD.com platform consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid packaging cartons represent early-cycle expansion as ambient plant-based beverage penetration accelerates format conversion from rigid plastics across China's tier-one cities and India's organized retail corridors.
For Market Incumbents: Consolidate equipment-captive relationships through extended aseptic filling service contracts that lock in carton offtake across German dairy cooperatives. Deepen backward integration into renewable fiber sourcing to defend margin position against pulp cost volatility threatening converter-dependent competitors. Prioritize captive recycling infrastructure investment as EU Green Deal verification protocols harden. For New Entrants and Emerging Players: Aftermarket technical service scarcity for legacy aseptic line retrofits creates immediate white-space opportunity for specialized commissioning and maintenance providers. Target India's Maharashtra and Karnataka juice markets where FSSAI quality formalization displaces unorganized PET refill channels. Pursue platform-native supplier status with Alibaba and JD.com beverage category managers requiring QR-coded traceability capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European converters lacking captive pulp supply and stranded with 1990s-era forming equipment. Five-to-ten year viability hinges on barrier material science convergence eliminating aluminum layers entirely. Monitor aqueous coating technology commercialization milestones as inflection signal for home-compostable certification pathway viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Fiber | Captive pulp supply insulates Stora Enso from Nordic energy cost spikes compressing converter margins. |
| Aseptic Equipment Service Contract Extension | Tetra Pak locks in decade-long carton demand through dairy chain filling system maintenance agreements. |
| Aqueous Barrier Coating Commercialization | Elimination of aluminum layers unlocks EU Green Deal home-compostable certification for Danish dairy processors. |
| Platform-Native Supplier Certification | Alibaba and JD.com traceability mandates shift quality accountability upstream to carton converters. |
| Regional Manufacturing Scale Expansion | SIG Combibloc anchors Asia-Pacific beverage demand through Yangtze River Delta production proximity. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with aseptic filling equipment engineers, dairy procurement directors, beverage brand packaging managers, and converter operations heads; and secondary validation through EU ECHA REACH filings, FDA food-contact substance notifications, SAMR GB standards documentation, and trade flow records from Nordic pulp export registries. Bottom-up volume builds triangulated against top-down industry association capacity estimates.
Across the analysis window, the forecasting framework modeled material type substitution dynamics, closure engineering complexity tiers, end-use application growth differentials, and channel concentration patterns. CAGRs derived from segmented demand builds incorporating dairy extended-shelf-life expansion rates, ambient plant-based beverage line conversion timelines, and e-commerce platform procurement consolidation trajectories. Price elasticity assumptions reflected pulp input cost pass-through coefficients and certification premium capture rates.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation implementation, FDA food-contact notification pathways, and China's SAMR national food safety standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Microwaveable Carton Market
Cartons
Mono Carton Market
Cartons
Litho Laminated Cartons Market
Cartons
Pulp Roll Cradles Market
Cartons
Global Folding Carton Packaging Market
Cartons
Carton Liners Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Tetrahedron Carton Market
Cartons
Beverage Cartons Market
Cartons
Mailers Market
Cartons
Cupcake Box Market
Cartons
XXL Packaging Market
Cartons
Tuck Top Box Market
Cartons
GCC Folding Carton Market
Cartons
Pizza Cartons Market
Cartons
Global Open Top Cartons Market