
 Cupcake Box Market | 2026-2036
Cupcake Box Market Size, Share, and Industry Trends Forecast 2026-2036
Cupcake Box Market Outlook
Direct-to-bakery distribution is tilting toward consolidated procurement platforms that bundle packaging with ingredients. DS Smith leverages its European corrugated network to serve artisanal bakeries with short-run custom jobs. Smurfit Kappa anchors production in recycled containerboard, competing on sustainability credentials against virgin-fiber rivals. WestRock differentiates through automated box-making technology that reduces lead times for regional cupcake chains.
A cupcake box is a rigid or semi-rigid container engineered to protect individual or multi-count baked goods during transport, typically constructed from 200–400 gsm paperboard with grease-resistant interior coatings and die-cut insert slots to prevent lateral movement. Its primary commercial purpose is to extend product presentation quality from bakery counter to consumer destination while enabling brand visibility through printable exterior surfaces. Window Boxes command premium positioning due to their food-display function, though Custom Boxes capture the fastest growth as boutique bakeries demand die-cut apertures, foil stamping, and seasonal motifs. Kraft Paper and Eco-Friendly Materials segments are expanding as ESG procurement policies at supermarket chains displace conventional plastic windows and uncoated virgin board.
The EU Packaging and Packaging Waste Regulation mandates recyclability targets and recycled content thresholds that reshape material selection for exporters serving European bakeries. The FDA maintains direct food-contact safety standards for coatings and adhesives used in US-sold cupcake boxes, while ISO 22000 certification operates as a de facto market-access filter for suppliers to multinational bakery brands. Stakeholders must monitor how rapidly diverging state-level extended producer responsibility laws in California, New York, and Washington fragment compliance requirements for national packaging programs.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitutions across European supply chains, compelling converters to reformulate coatings and eliminate plastic windows ahead of recyclability mandates. This regulatory compression is accelerating R&D investment in barrier-coated paperboard and reshaping procurement specifications for artisanal bakery chains.
Growth Catalysts
- REACH compliance deadlines:European converters are qualifying mineral-oil-free inks and water-based adhesives to meet food-contact migration limits, opening premium positioning for certified suppliers.
- Artisanal bakery expansion:Boutique chains in Germany and France are specifying custom die-cut apertures and seasonal motifs, pulling rigid box volumes upward.
- Window box functionality:Visual merchandising requirements at specialty dessert shops are sustaining demand for food-display packaging despite material cost premiums.
Market Restraints
- Pulp price volatility:Recycled containerboard input costs fluctuate with OCC collection rates, compressing converter margins on short-run custom jobs.
- Coating technical limitations:Current grease-resistant bio-barriers lack the heat tolerance of legacy polyethylene laminates, restricting hot-food applications.
- Substitution to reusable systems:Deposit-return packaging pilots at Scandinavian supermarket chains threaten single-use box volumes in institutional channels.
Strategic Opportunities
- Underpenetrated Poland:Warsaw-based bakery chains are upgrading from generic folding cartons to rigid window boxes, creating white space for regional converters.
- Regulatory tailwind from CSRD:Corporate sustainability reporting mandates are pushing multinational food retailers to document packaging circularity, favoring certified suppliers.
- Digital print convergence:Single-pass inkjet on corrugated is enabling economical runs below five hundred units, matching boutique bakery order patterns.
Industry Challenges
- ISO 22000 certification timelines:Smaller converters face twelve-to-eighteen-month audit backlogs, delaying market access to multinational bakery brands.
- Legacy equipment integration:Automated box-making lines require reconfiguration of existing folder-gluer setups, disrupting production schedules during retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cupcake Box Market |
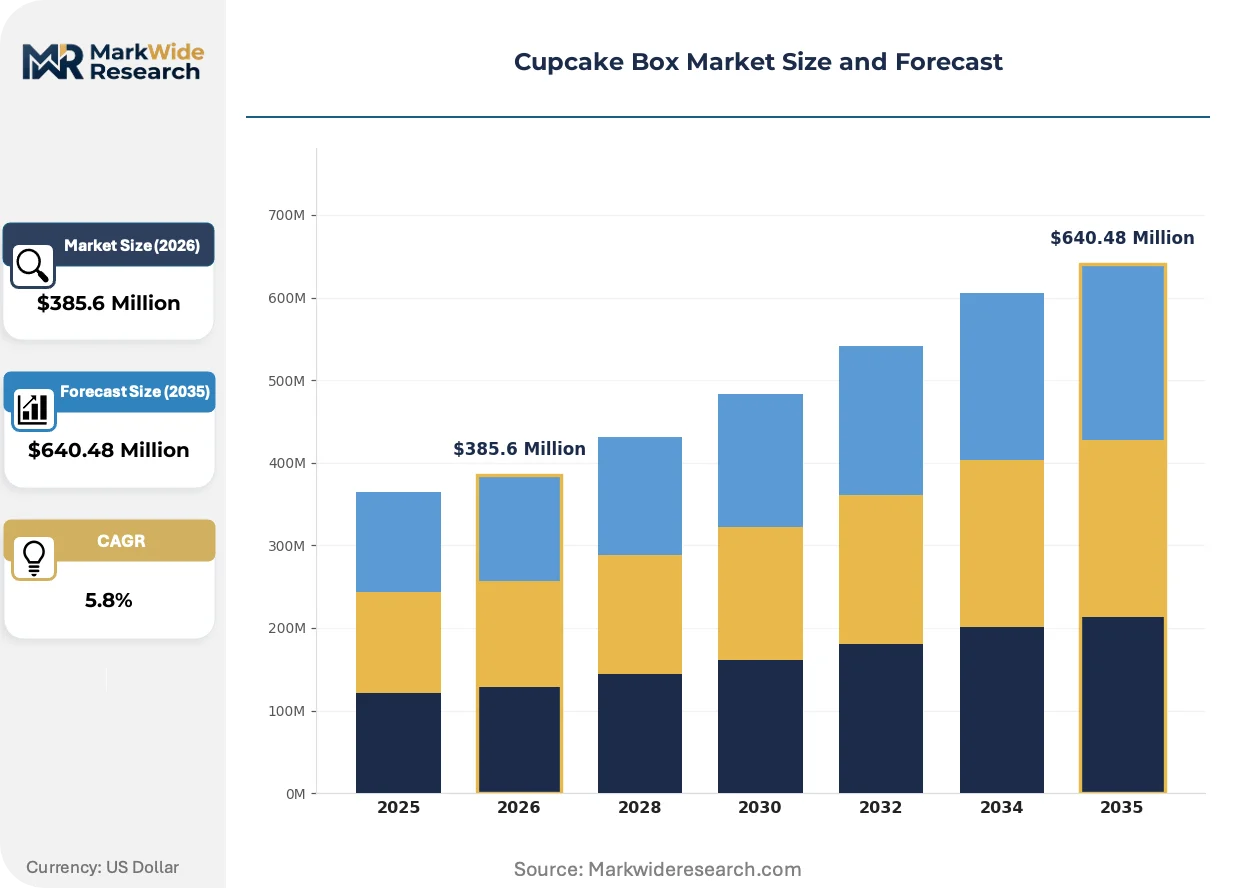
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Boxes, Window Boxes, Custom Boxes, Multi-Pack Boxes Material: Cardboard, Plastic, Kraft Paper, Eco-Friendly Materials Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Wholesale Distributors |
| Companies Covered | Huhtamaki, DS Smith, Smurfit Kappa, Berry Global, Mondi Group, WestRock, Graphic Packaging International, Pactiv Evergreen, International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cupcake Box Market Strategic Shifts
Material science advances and regulatory tightening are converging to redefine performance specifications for food-contact packaging. Converters are racing to commercialize alternatives that satisfy both barrier requirements and end-of-life recyclability.
Water-based barrier coatings with oxygen-scavenging properties are rendering obsolete conventional polyethylene-laminated paperboard in chilled bakery applications. German artisanal chains are qualifying these materials for six-month shelf-life products. The technology is compressing the addressable market for legacy extrusion-coated substrates.
The EU Packaging and Packaging Waste Regulation mandates recyclability targets and recycled content thresholds that reshape material selection for exporters serving European bakeries. Industrial consequence includes disqualification of composite structures from green public procurement. Window box segments are responding with fiber-based transparent films and cellulose windows.
Consolidated procurement platforms are displacing direct-to-bakery distributor relationships across Western Europe. Regional bakery cooperatives are pooling packaging specifications through shared buying groups. This concentration is most visible in France, where procurement federations now represent over thirty percent of artisanal channel volume.
Cupcake Box Market Segmentation
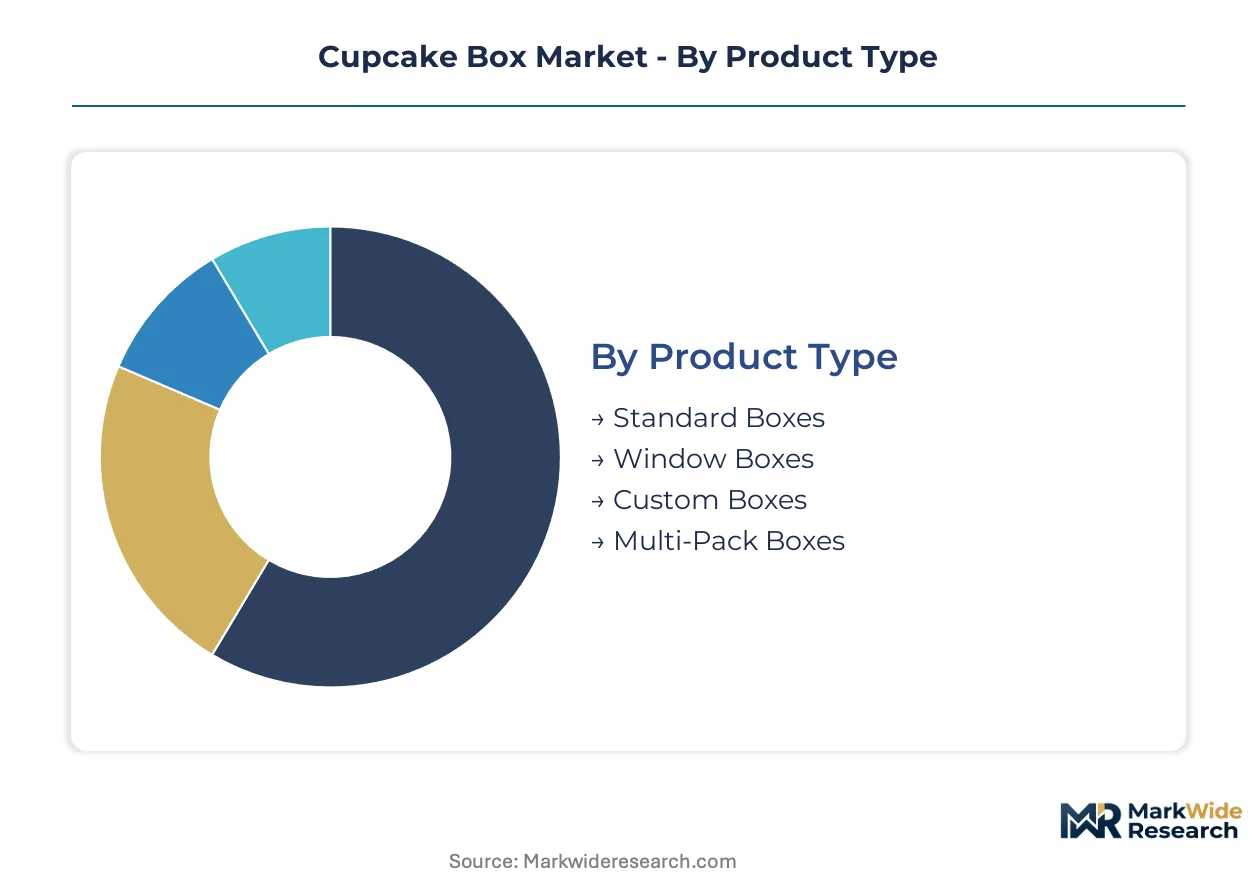
Material compliance mandates and artisanal bakery procurement patterns fragment the Cupcake Box Market into distinct performance tiers. Each dimension—product format, substrate composition, dimensional specification, and channel access—carries divergent margin profiles and certification requirements.
Product Type:
Application requirements dictate structural complexity, from basic transport protection to premium visual merchandising.
- Window Boxes:Die-cut apertures with food-grade transparent films enable counter-to-consumer display continuity. German boutique chains specify these for six-unit assortments despite material cost premiums.
- Custom Boxes:Die-cut apertures, foil stamping, and seasonal motifs support brand differentiation. Artisanal bakery expansion in France and Poland is pulling rigid box volumes upward fastest.
- Standard Boxes:Plain folding cartons serve high-volume supermarket private-label programs with minimal decoration.
- Multi-Pack Boxes:Partitioned interiors protect dozen-count orders for institutional catering and event channels.
Window Boxes hold installed capacity. Custom Boxes is rotating up the share rankings.
Material:
Margin compression from pulp volatility and ESG procurement policies are reweighting substrate selection toward circularity-certified alternatives.
- Kraft Paper:Unbleached virgin fiber delivers structural rigidity with natural aesthetic positioning. Scandinavian supermarket chains specify this for deposit-return pilot programs.
- Eco-Friendly Materials:Barrier-coated recycled paperboard and cellulose-based transparent films satisfy EU Packaging and Packaging Waste Regulation recyclability thresholds. Multinational food retailers document packaging circularity through these substrates.
- Cardboard:Clay-coated recycled containerboard dominates cost-sensitive volume applications with printable exterior surfaces.
- Plastic:Conventional PET and polystyrene windows face disqualification from green public procurement across European institutional channels.
Cardboard holds installed capacity. Eco-Friendly Materials is climbing the fastest.
Size:
Customer occasion type—single impulse purchase versus celebration event—determines dimensional specification frequency.
- Small:Single-unit and two-unit formats align with grab-and-go bakery counter transactions.
- Medium:Four-unit and six-unit configurations balance transport protection with shelf presence for specialty dessert shops.
- Large:Twelve-unit boxes serve family occasion and small office catering segments.
- Extra Large:Twenty-four-unit and bulk formats address event planners and wholesale club channels.
Medium holds installed capacity. Small is gaining share fastest.
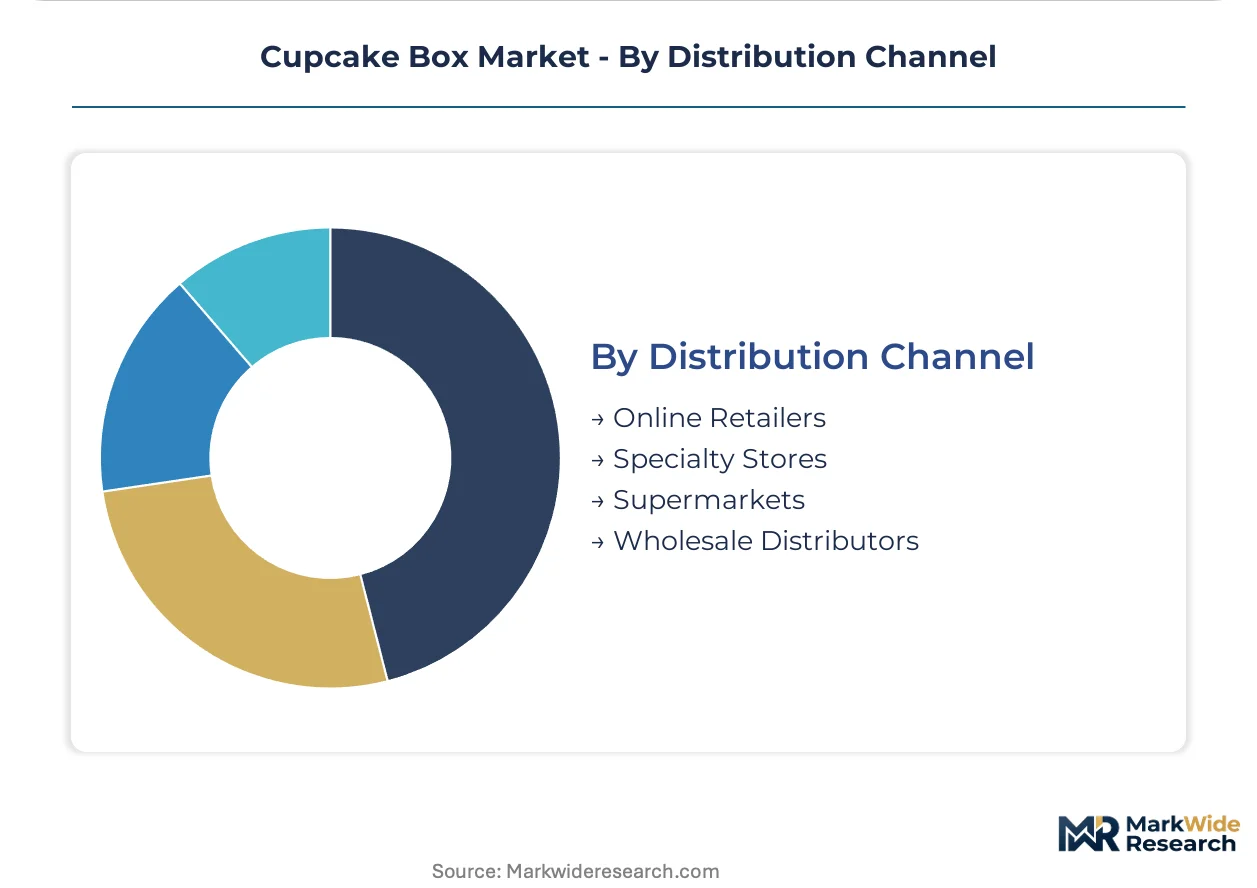
Distribution Channel:
Procurement concentration through consolidated platforms is displacing direct distributor relationships across Western Europe.
- Wholesale Distributors:Bundled packaging-ingredient procurement platforms aggregate artisanal bakery demand. French procurement federations now represent over thirty percent of channel volume.
- Online Retailers:Digital print convergence enables economical runs below five hundred units, matching boutique bakery order patterns with short lead times.
- Specialty Stores:Dedicated packaging suppliers serve premium rigid box specifications for independent bakeries.
- Supermarkets:Centralized private-label programs demand high-volume, low-variation folding cartons with ESG documentation.
Wholesale Distributors holds installed capacity. Online Retailers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation anchors European material compliance, while artisanal bakery expansion and sustainability procurement reshape demand patterns across distinct national markets.
Germany
Artisanal bakery chains in Munich and Berlin are specifying custom rigid window boxes with foil-stamped seasonal motifs. REACH compliance deadlines are compelling converters to qualify mineral-oil-free inks and water-based adhesives for food-contact migration limits. The Baden-Württemberg industrial corridor hosts specialist converters serving boutique chains with short-run digital print capabilities.
France
Procurement federations now aggregate over thirty percent of artisanal channel volume, consolidating packaging specifications across regional bakery cooperatives. The EU Green Deal implementation is accelerating substitution of plastic windows with cellulose-based transparent films in Parisian specialty dessert shops. The Île-de-France region concentrates rigid box demand from premium patisserie chains upgrading presentation standards.
United States
FDA food-contact safety standards for coatings and adhesives maintain strict entry barriers for imported cupcake boxes serving regional bakery chains. State-level extended producer responsibility laws in California, New York, and Washington are fragmenting compliance requirements for national packaging programs. The Pacific Northwest hosts pilot deposit-return packaging trials threatening single-use box volumes in institutional supermarket channels.
Poland
Warsaw-based bakery chains are upgrading from generic folding cartons to rigid window boxes, creating white space for regional converters. The country's national packaging regulator is aligning domestic standards with EU recyclability thresholds ahead of accession-timed harmonization deadlines. The Silesian industrial basin is attracting corrugated investment to serve Central European bakery demand.
United Kingdom
Post-Brexit divergence from EU packaging rules is creating dual compliance burdens for exporters serving both continental and domestic markets. The Environment Agency's extended producer responsibility framework is mandating recycled content documentation for supermarket private-label programs. Greater Manchester and Birmingham host converters balancing short-run custom jobs for independent bakeries against high-volume retail contracts.
Cupcake Box Market Competitive Environment
Integrated packaging conglomerates and regional specialty converters split the market between scale-driven containerboard supply and agile custom fabrication. DS Smith, Smurfit Kappa, and WestRock anchor the consolidated tier with European corrugated networks and automated production assets. Mid-scale converters compete through digital print convergence and rapid turnaround on sub-five-hundred-unit runs. Competitive moves center on sustainability certification stacking and geographic footprint expansion into underpenetrated Central European markets.
Among the integrated packaging groups, DS Smith exemplifies the European network archetype with short-run custom capabilities, while Smurfit Kappa anchors recycled containerboard positioning against virgin-fiber rivals. WestRock occupies the automation-driven tier with box-making technology reducing lead times for regional chains. These three companies represent divergent strategic responses to regulatory compression and artisanal demand fragmentation.
| Leading Market Players |
|---|
| Huhtamaki |
| DS Smith |
| Smurfit Kappa |
| Berry Global |
| Mondi Group |
| WestRock |
| Graphic Packaging International |
| Pactiv Evergreen |
| International Paper |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's container rate volatility compresses converter margins on short-run custom jobs while amplifying price differentiation between boutique bakery orders and supermarket private-label volume. This logistics chokepoint concentrates supply-side power among integrated European corrugated networks that can absorb freight cost swings through backward integration into recycled containerboard production.
Pricing Analysis
The customization-premium spread separates rigid window boxes with foil-stamped seasonal motifs from plain folding cartons by a factor of three to four on per-unit basis. Pricing stratifies across premium certified tiers, standard recycled-content grades, and economy virgin-fiber alternatives, with REACH-compliant mineral-oil-free inks commanding measurable uplifts. Cost compression in the standard tier is intensifying because pulp price volatility feeds directly into converter margins on high-volume supermarket contracts. Boutique bakery cooperatives show least price sensitivity due to brand-positioning requirements, while institutional catering buyers negotiate aggressively on dozen-count multi-pack specifications.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation recyclability thresholds function as de facto export controls on composite structures containing polyethylene-laminated paperboard or conventional plastic windows. Supply concentrates in Germany, France, and Poland, with the Baden-Württemberg and Île-de-France corridors hosting specialist converters for artisanal channels. Raw material flows draw from OCC collection networks, water-based barrier coating formulations, and cellulose-based transparent film substrates. Single-source vulnerability sits with mineral-oil-free ink suppliers facing REACH compliance audit backlogs. Distribution runs through consolidated procurement platforms that bundle packaging with ingredients across French and German bakery cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward procurement federations that now aggregate over thirty percent of artisanal channel volume in France alone, fragmenting pricing power among converters.
For Market Incumbents: Insulate margin position by securing ISO 22000 certification ahead of twelve-to-eighteen-month audit backlogs that currently gate multinational bakery brand access. Accelerate digital print convergence investments to match sub-five-hundred-unit order patterns from boutique chains, defending against agile regional converters exploiting short-run economics. For New Entrants and Emerging Players: Build out rigid window box capabilities in Poland's Silesian industrial basin, where Warsaw-based bakery chains are upgrading from generic folding cartons and regional supply remains thin. Target the online retailer channel with single-pass inkjet technology that enables economical runs below five hundred units, matching boutique bakery procurement patterns without competing on scale against integrated conglomerates. For Investors and Strategic Acquirers: Digital-native converters with certified barrier-coating expertise and short-run production agility represent the most compelling acquisition archetype for exposure to artisanal bakery expansion. Monitor cellulose-based transparent film qualification rates at German boutique chains as the inflection indicator for material substitution velocity away from legacy plastic windows.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coating R&D Investment | Water-based oxygen-scavenging formulations displace polyethylene laminates in chilled bakery applications. |
| Digital Print Infrastructure Deployment | Single-pass inkjet on corrugated matches sub-five-hundred-unit boutique bakery order economics. |
| Certification Stacking Program | ISO 22000 and REACH-compliant mineral-oil-free ink qualifications unlock multinational brand access. |
| Geographic Expansion into Poland | Warsaw bakery chain upgrades from generic folding cartons create white space for rigid window box supply. |
| Procurement Platform Integration | French federation aggregation of thirty percent artisanal volume demands bundled packaging-ingredient capabilities. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bakery chain procurement directors, corrugated converter plant managers, packaging distributor category leads, and sustainability compliance officers at multinational food retailers. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, ECHA REACH substance restriction updates, OCC price indices, and customs data on paperboard trade flows. Bottom-up volume modeling triangulated against top-down market sizing across product type, material composition, and channel dimensions.
Calibration anchored on historical volume trajectories and verified capacity announcements across the analysis window. Segmentation modeling incorporated product format tiers, substrate circularity certifications, dimensional specifications, and procurement channel concentration patterns. CAGR derivation weighted near-term regulatory compression effects against longer-term artisanal bakery expansion trends, with specific inputs from digital print adoption curves and barrier-coating technical qualification timelines.
Practitioners should monitor EU recyclability mandate enforcement intensity and cellulose window film commercialization rates for early signals of material substitution velocity. Forecasts reflect assumptions about REACH compliance deadline adherence and boutique bakery cooperative formation trajectories. Material shifts in extended producer responsibility law fragmentation across US state jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Twist Opening Cartons Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Cartoning Machines Market
Cartons
Tuck Top Box Market
Cartons
Digital Printed Cartons Market
Cartons
Fully Enclosed Cartons Market
Cartons
Reverse Tuck Cartons Market
Cartons
Pizza Cartons Market
Cartons
Pulp Roll Cradles Market
Cartons
Carton Sealer Market
Cartons
Global Printed Cartons Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Global Open Top Cartons Market
Cartons
End Load Cartoning Machine Market
Cartons
Fluted Carton Trays Market
Cartons
Metallized Folding Cartons Market