

Horizontal Cartoning Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Cartoning Machines Market Insights
Integration of servo motor technology with PLC control architectures is reshaping how horizontal cartoning machines achieve speed-accuracy trade-offs in high-volume packaging environments. IMA Group leverages its pharmaceutical specialization to anchor premium positioning in validated cleanroom applications. Marchesini Group competes through integrated line solutions that extend from cartoning through end-of-line palletization. OMORI Machinery dominates Asian export markets with compact footprint designs tailored for contract packaging providers.
Horizontal cartoning machines are intermittent or continuous-motion packaging systems that erect, load, and seal paperboard cartons at speeds ranging from 50 to 600 units per minute, employing rotary or reciprocating mechanisms to handle rigid or flexible product formats across pharmaceutical blister packs, food pouches, and cosmetic containers. Servo driven systems are capturing margin pools in pharmaceutical applications where precise leaflet insertion and serialization compliance justify capital intensity, while pneumatic architectures retain cost advantages in household goods where lower changeover frequency reduces the servo payback case. Automatic technology leads volume shipments among direct brand owners with dedicated production lines, though semi-automatic configurations persist in emerging manufacturing units where labor arbitrage still offsets automation premiums.
FDA validation requirements for pharmaceutical packaging equipment and EU MDR traceability mandates are elevating entry barriers for machinery suppliers without documented qualification protocols, while CE marking and ISO 13849 safety standards govern market access across European manufacturing units. ECHA REACH compliance for lubricants and surface coatings adds material specification constraints that favor established OEMs with supplier audit trails. Stakeholders must weigh captive versus outsourced packaging decisions against evolving serialization deadlines and carbon disclosure obligations that alter total cost of ownership calculations.
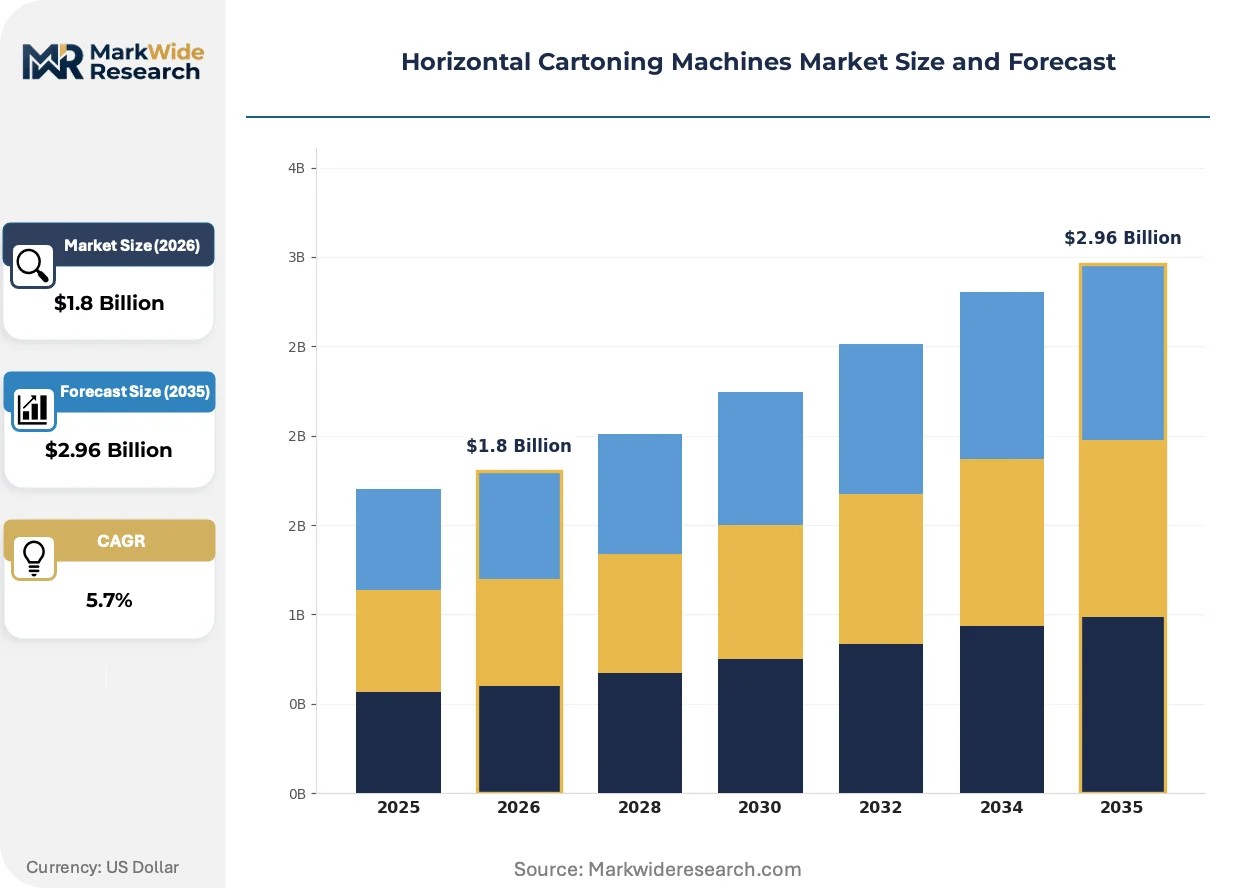
Market Dynamics
Servo-driven motion control architectures are displacing mechanical cam systems across pharmaceutical and food packaging lines, compressing changeover times while elevating capital intensity thresholds for machinery suppliers.
Growth Catalysts
- EU MDR serialization mandates:Pharmaceutical contract packagers in Germany and Italy are retrofitting existing lines with vision-inspection modules to comply with traceability requirements. Equipment validation documentation has become a competitive differentiator for machinery OEMs.
- Food pouch format proliferation:Stand-up and spouted pouch formats in ready-meal and snack categories are forcing cartoning equipment adaptations. Flexible product handling mechanisms now command premium positioning in automated packaging lines.
- Stuttgart machinery cluster concentration:German OEMs benefit from proximity to automotive precision engineering suppliers, enabling rapid prototyping of high-speed carton handling systems for export markets.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for food-grade 316L stainless steel and precision motion components compress margin pools for mid-tier machinery suppliers without captive sourcing.
- Technical limitation in ultra-light carton stocks:Recycled fiberboard below 250 gsm creates jam rates that degrade OEE metrics, constraining sustainable packaging transitions in high-speed pharmaceutical applications.
- REACH compliance friction for lubricants:ECHA substance restrictions on mineral oil-based lubricants force reformulation cycles that extend equipment qualification timelines for European pharmaceutical packagers.
Strategic Opportunities
- India contract packaging underpenetration:Domestic pharmaceutical outsourcing remains below 15% penetration versus 40% in Western Europe, creating white space for modular cartoning systems with localized service networks.
- Cosmetic airless pump convergence:Integration of cartoning with primary filling equipment for premium skincare formats enables line-solution positioning in luxury personal care manufacturing.
- CE marking and ISO 13849 safety upgrade cycles:Machinery replacement demand is accelerating among European manufacturers facing insurer pressure to eliminate pneumatic pinch-point hazards on legacy equipment.
Industry Challenges
- Mechatronics technician scarcity:Servo tuning and PLC programming competencies lag demand across machinery OEMs and end-user maintenance departments, extending commissioning timelines.
- IQ/OQ/PQ documentation burden:Pharmaceutical equipment qualification protocols require 12-18 month validation cycles that strain project cash flows and delay revenue recognition for machinery suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Cartoning Machines Market Trends and Innovations
Digital thread technologies are collapsing the boundary between machine operation and predictive maintenance, enabling remote performance optimization that reconfigures supplier-customer relationships in packaging automation.
Edge computing architectures embedded directly in cartoning machine control cabinets are digitizing vibration and temperature telemetry into actionable maintenance windows. Pharmaceutical manufacturers with validated cleanroom operations are piloting these systems to reduce unplanned downtime during high-value batch runs. The shift is compressing traditional break-fix service contracts toward continuous performance guarantees.
EU MDR Article 10 traceability requirements are forcing serialization hardware integration at the cartoning station rather than downstream. Machinery suppliers must now qualify vision systems and aggregation software as part of the validated equipment package. German pharmaceutical packagers are absorbing these compliance costs fastest, while Italian and Spanish contract manufacturers lag in retrofit timelines.
After-sales service unbundling is fragmenting how packaging lines are financed and maintained. Brand owners in food and cosmetics are separating equipment purchase from performance-based service agreements, transferring uptime risk to OEMs. This pattern is most pronounced among mid-sized German confectionery manufacturers seeking to preserve capital for ingredient sourcing flexibility.
Horizontal Cartoning Machines Market Segmentation
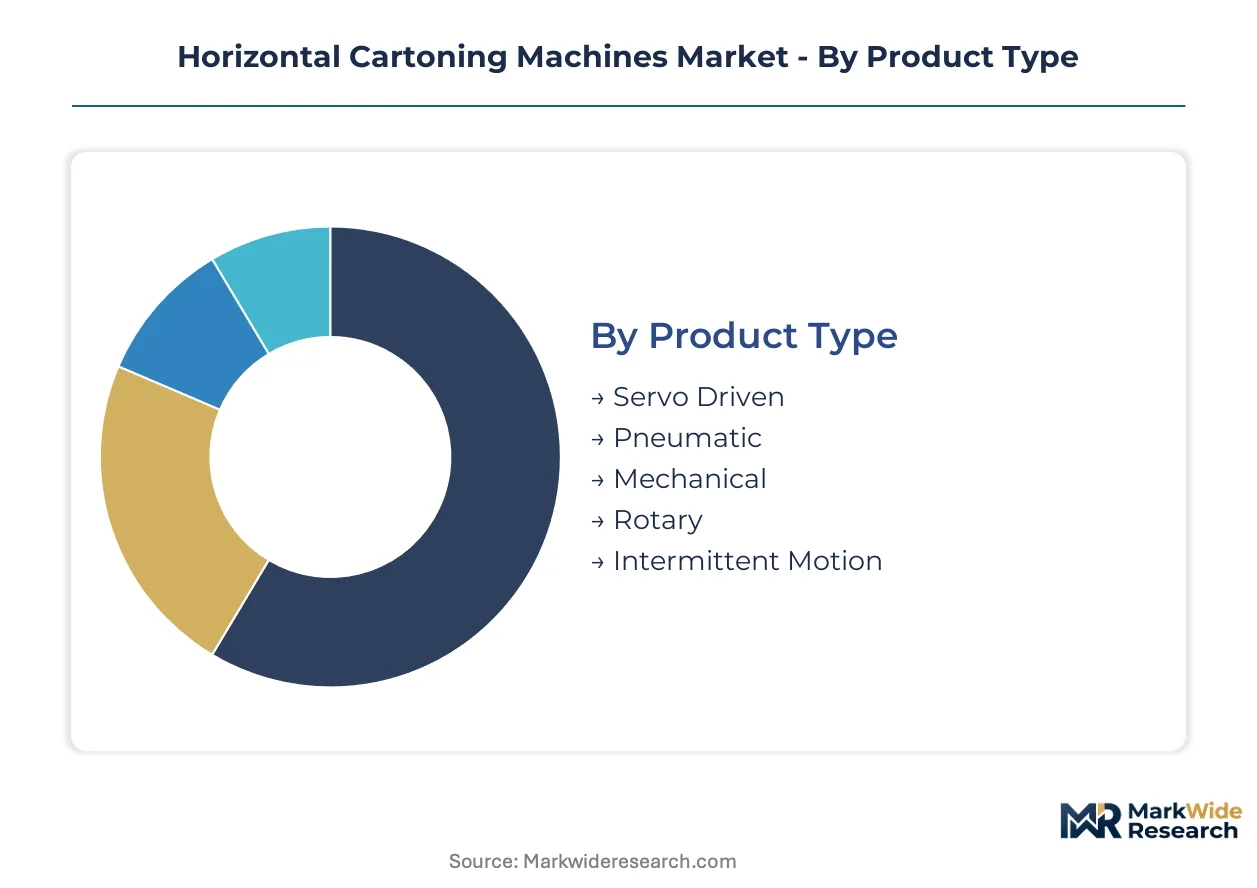
Segmentation in horizontal cartoning machines reveals how technology choices, automation levels, and customer procurement models create distinct competitive arenas. Equipment specifications diverge sharply between validated pharmaceutical lines and high-volume food operations, with regulatory compliance and throughput requirements driving mutually exclusive design priorities.
Product Type:
Mature mechanical architectures coexist with emerging servo-driven platforms as end-users recalculate total cost of ownership against changeover frequency and batch size flexibility.
- Servo Driven:Closed-loop motion control enables sub-millimeter positioning accuracy for leaflet insertion and serialization compliance. Pharmaceutical packagers in Germany absorb premium capital costs to compress format changeover windows below 15 minutes.
- Pneumatic:Compressed air actuation delivers lower first-cost positioning for household goods and bulk food cartoning where changeover frequency remains below weekly cycles. Italian contract manufacturers retain these systems for detergent and cleaning product lines.
- Mechanical:Cam-driven linkages persist in emerging manufacturing units with limited maintenance technician availability and high labor arbitrage.
- Rotary:Continuous-motion drum configurations achieve 600 units per minute in high-volume confectionery applications.
- Intermittent Motion:Reciprocating carton transport accommodates irregular product geometries in cosmetics and personal care formats.
Pneumatic systems retain volume leadership among contract packaging providers; servo driven configurations hold the steepest expansion curve as pharmaceutical serialization mandates propagate.
Technology:
Automation intensity stratifies across customer capital budgets and regulatory exposure, with semi-automatic configurations serving labor-advantaged geographies while fully automatic systems dominate serialized pharmaceutical environments.
- Automatic:Integrated feeding, erecting, loading, and sealing sequences operate without operator intervention. Direct brand owners in food and beverage verticals deploy these lines for 24-hour production schedules.
- Semi-Automatic:Operator-assisted loading stations reduce capital outlay by 40-60% versus fully automatic equivalents. Indian pharmaceutical contract manufacturers favor these configurations where technician scarcity limits maintenance bandwidth.
- Fully Automatic:Complete line integration from upstream primary packaging through downstream case packing eliminates manual touchpoints. German OEMs bundle these systems with performance-based service contracts.
- PLC Control:Programmable logic controllers coordinate multi-axis motion through standardized industrial Ethernet protocols.
- Servo Motor Integration:Distributed drive architectures replace centralized gearboxes with individual motor-per-axis configurations.
Automatic technology commands the installed base among direct brand owners; fully automatic systems are expanding most quickly as serialization hardware integration becomes mandatory.
Application:
End-use sector requirements fragment equipment specifications across contamination control, speed-accuracy trade-offs, and format flexibility demands.
- Pharmaceuticals:FDA 21 CFR Part 11 compliance and EU MDR traceability mandate validated equipment with documented IQ/OQ/PQ protocols. Vision inspection and aggregation modules integrate at the cartoning station.
- Food & Beverages:Stainless steel 316L construction and washdown compatibility address allergen control and microbial sanitation. Ready-meal pouch formats drive demand for flexible product handling mechanisms.
- Cosmetics:Premium airless pump and jar formats require gentle handling and precise leaflet placement for multilingual regulatory labeling.
- Personal Care:Shampoo and conditioner bottle cartoning emphasizes throughput over precision at 400+ units per minute.
- Household Goods:Detergent pods and cleaning wipes tolerate wider dimensional tolerances, favoring pneumatic architectures with lower capital intensity.
Food and Beverages retains volume leadership across installed base; Pharmaceuticals holds the steepest expansion curve as serialization deadlines compress retrofit timelines.
End User Industry:
Procurement concentration diverges between captive manufacturing units seeking line integration and outsourced providers prioritizing format flexibility.
- Direct Brand Owners:Proprietary production lines justify dedicated equipment with customized changeover procedures. German confectionery manufacturers exemplify this pattern with in-house engineering teams.
- Contract Packaging Providers:Multi-customer service models demand rapid format changeover and modular machine configurations. These operators absorb 30-50 format changes monthly.
- Manufacturing Units:Captive packaging operations within integrated pharmaceutical and food companies optimize for single-format long runs.
- Packaging Service Companies:Regional specialists serve mid-tier brands without dedicated packaging infrastructure.
Direct Brand Owners retain volume leadership in absolute machine count; Contract Packaging Providers hold the steepest expansion curve as pharmaceutical outsourcing penetration climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machinery OEMs export servo-driven cartoning systems to pharmaceutical packagers across Western Europe and North America, establishing Stuttgart and Cologne as precision engineering hubs for validated packaging automation.
Germany
Pharmaceutical contract manufacturers in Baden-Württemberg absorb premium capital costs for EU MDR-compliant serialization modules. ECHA REACH substance restrictions on lubricants force reformulation cycles that extend equipment qualification timelines. The Stuttgart machinery cluster leverages proximity to automotive precision suppliers for rapid prototyping of high-speed carton handling systems.
United States
Food and beverage brand owners deploy automatic cartoning lines for 24-hour production schedules across Midwest manufacturing corridors. FDA 21 CFR Part 11 validation requirements elevate entry barriers for machinery suppliers without documented IQ/OQ/PQ protocols. Chicago-area packaging service companies favor modular configurations to accommodate 30-50 monthly format changes.
Italy
Contract packagers in Emilia-Romagna retain pneumatic architectures for detergent and cleaning product lines where weekly changeover frequency limits servo payback cases. CE marking and ISO 13849 safety standards accelerate replacement demand among manufacturers facing insurer pressure. The Bologna-Turin industrial axis concentrates mid-tier machinery suppliers serving pan-European household goods clients.
India
Domestic pharmaceutical outsourcing remains below 15% penetration versus 40% in Western Europe, creating white space for semi-automatic configurations where technician scarcity limits maintenance bandwidth. CDSCO serialization mandates propagate gradually, lagging EU MDR enforcement timelines. Maharashtra and Gujarat host emerging contract packaging providers seeking localized service networks from machinery OEMs.
China
Domestic demand for compact footprint designs concentrates in Yangtze River Delta contract packaging hubs serving export-oriented cosmetic brands. SAMR equipment safety standards and NMPA pharmaceutical packaging regulations tighten compliance requirements for imported machinery. Shanghai-area manufacturers pilot edge computing architectures for predictive maintenance in high-volume confectionery applications.
Horizontal Cartoning Machines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered competitive positions. The vendor base stratifies between integrated line-solution providers and standalone cartoning equipment fabricators. Three archetypes dominate: pharmaceutical-validated specialists, food-volume scale operators, and modular flexibility providers. M&A activity concentrates on vision-inspection and serialization software capabilities, while geographic expansion targets underpenetrated Indian and Southeast Asian contract packaging markets.
Within the pharmaceutical-validated tier, IMA Group and Marchesini Group exemplify machinery OEMs with documented qualification protocols for FDA and EU MDR compliance. OMORI Machinery occupies a position among Asia-Pacific export specialists, representing compact footprint designs tailored for contract packaging providers. These three anchors illustrate how competitive positioning diverges between premium validated systems and volume-optimized configurations.
| Leading Market Players |
|---|
| IMA Group |
| Marchesini Group |
| Mpac Group |
| OMORI Machinery |
| ADCO Packaging Solutions |
| Econocorp |
| Jacob White Packaging |
| Serpa Packaging Solutions |
| OPTIMA packaging group |
| Others |
Pricing and Supply Chain Analysis
EU MDR serialization mandates and REACH lubricant compliance create a dual regulatory chokepoint that widens pricing spreads between validated pharmaceutical systems and standard food-grade configurations while compressing supplier margins through extended qualification timelines.
Pricing Analysis
Servo-driven pharmaceutical systems command 40-60% capital premiums over pneumatic equivalents due to closed-loop positioning accuracy and integrated vision inspection modules. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cleanroom configurations from CE-marked food systems and mechanical cam-driven emerging-market units. Cost compression in mid-tier pneumatic segments intensifies because Italian contract manufacturers face stainless steel 316L price volatility. Contract packaging providers exhibit highest price sensitivity; direct brand owners in German pharmaceutical manufacturing absorb premiums for changeover flexibility.
Supply Chain Analysis
Extended payment terms from German machinery OEMs to Stuttgart-area precision engineering suppliers have become standard practice, with 90-120 day cycles now typical for servo motor and linear actuator procurement. Component sourcing draws from Germany for precision motion systems, Japan for servo drives, and China for food-grade stainless steel fabrication. Single-source vulnerability concentrates in high-resolution vision inspection modules qualified for EU MDR aggregation requirements. Distribution runs through direct OEM sales teams for pharmaceutical validated systems and regional machinery distributors for food and household goods segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horizontal cartoning machinery sits at a technology inflection where servo-driven architectures displace mechanical cams, compressing the window for incumbent repositioning before serialization mandates lock in supplier relationships.
For Market Incumbents: Pre-empt emerging entrant encroachment by acquiring vision-inspection software specialists before EU MDR aggregation requirements harden equipment specifications. Deepen backward integration into servo motor supply chains to offset 316L stainless steel cost volatility and preserve margin pools in pharmaceutical applications. For New Entrants and Emerging Players: Indian pharmaceutical contract packaging underpenetration offers the most penetrable white space for modular semi-automatic configurations with localized service networks. Target Maharashtra and Gujarat manufacturing corridors with technician training partnerships that address mechatronics scarcity and accelerate commissioning timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors pharmaceutical-validated specialists with documented IQ/OQ/PQ protocols over volume-optimized food machinery fabricators. Watch CDSCO serialization mandate propagation timelines as the signal indicating when Indian contract packaging penetration accelerates toward Western European benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Vision System Integration | EU MDR Article 10 mandates serialization hardware qualification at cartoning stations, elevating entry barriers. |
| Servo Drive Acquisition | Backward integration into precision motion components insulates margin pools from 316L stainless steel volatility. |
| Indian Service Network Buildout | Localized technician training addresses mechatronics scarcity and compresses commissioning timelines in underpenetrated markets. |
| Edge Computing Pilot Programs | Predictive maintenance architectures shift service contracts from break-fix toward continuous performance guarantees. |
| REACH-Compliant Lubricant Reformulation | ECHA substance restrictions force qualification cycles that extend project timelines and strain supplier cash flows. |
Research Methodology
Cross-validation between machinery OEM engineering directors and pharmaceutical packaging operations managers anchors the qualitative findings on servo adoption drivers and changeover frequency requirements. Primary interviews with maintenance directors at German confectionery manufacturers, contract packaging procurement leads in Emilia-Romagna, and CDSCO regulatory affairs specialists combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA MDR implementation timelines, and VDMA machinery production statistics. Bottom-up equipment shipment tallies triangulate against top-down pharmaceutical packaging line investment disclosures.
Calibration against historical servo motor penetration curves and pneumatic system replacement cycles shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include motion control architecture, automation intensity, end-use sector regulatory exposure, and geographic manufacturing cluster concentration. CAGRs derive from equipment shipment momentum analysis adjusted for qualification timeline delays and serialization mandate enforcement schedules. Forecast inputs incorporate ECHA REACH substance restriction implementation phases and stainless steel 316L price trajectory assumptions.
Practitioners should monitor CDSCO serialization mandate propagation and EU MDR enforcement consistency for early signals of regional demand acceleration or delay. Forecasts reflect documented assumptions about regulatory timeline adherence and input cost stabilization. Macroeconomic deviation, regulatory enforcement variance, or servo motor supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.