
 Shaped Liquid Cartons Market | 2026-2036
Shaped Liquid Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Shaped Liquid Cartons Market Outlook
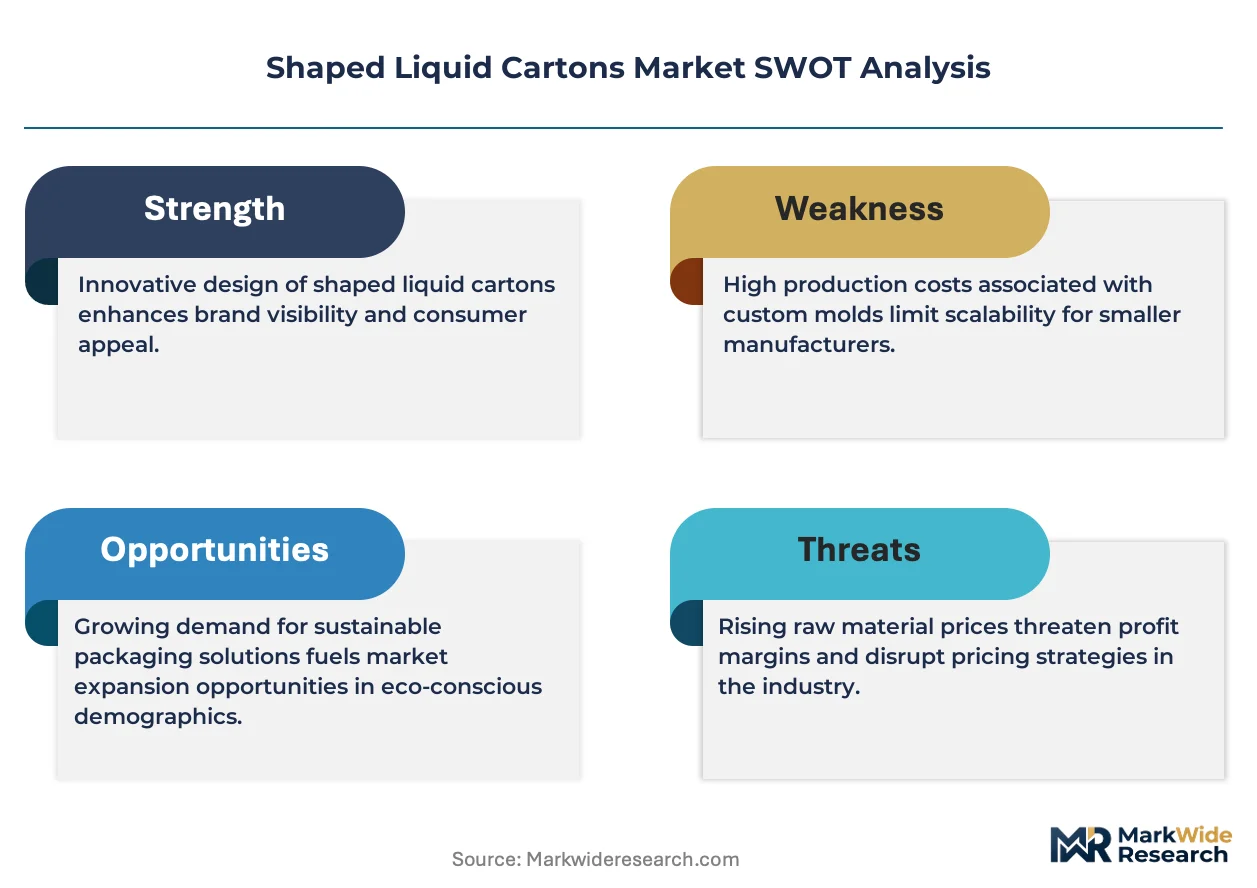
Asset-light leasing models for aseptic filling equipment are narrowing the capital barrier for mid-sized dairy processors. Tetra Pak International S.A. leverages its captive financing arm to lock in long-term filling-line contracts. SIG Combibloc Group Ltd. anchors its competitiveness through pre-sterilized carton blank supply agreements that reduce customer working capital needs. Elopak AS differentiates via regional production hubs that cut logistics exposure for Scandinavian beverage brands.
Shaped liquid cartons are paperboard-based containers with polyethylene and aluminum barrier layers, thermoformed or pre-creased into non-cylindrical profiles to maximize pallet density and retail shelf presence. The gable-top format retains dominance in fresh dairy due to established cold-chain infrastructure and consumer familiarity. Brick-shaped cartons capture growth in ambient beverages, where rectangular geometry optimizes transport cube utilization. Composite material configurations command attention from regulators and recyclers because the bonded layers complicate standard paper-pulp recovery processes.
FDA food-contact substance notifications and EU REACH compliance on polyethylene coatings shape material choices for exporters serving both jurisdictions. The EU Green Deal's packaging recyclability targets and state-level extended producer responsibility laws in California and New York pressure converters to redesign layer structures. Stakeholders must monitor whether chemical recycling infrastructure for multilayer laminates matures fast enough to outpace regulatory bans on non-recyclable formats.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing dairy and beverage processors to redesign multilayer carton structures, accelerating investment in chemical recycling partnerships and mono-material alternatives before recyclability mandates take full effect.
Growth Catalysts
- Extended Shelf-Life Milk Demand:Dairy processors in Germany and France are adopting shaped cartons for ambient distribution, reducing cold-chain dependency and expanding retail reach into convenience stores.
- REACH Compliance on Barrier Coatings:The EU's chemical safety framework is pushing converters toward polyethylene formulations that maintain oxygen barriers while improving recyclability certification.
- California EPR Laws:State-level extended producer responsibility legislation is compelling North American brands to source shaped cartons with verified post-consumer recycled content thresholds.
Market Restraints
- Aluminum Layer Volatility:Fluctuating commodity prices for the foil barrier component squeeze converter margins and complicate long-term supply agreements with dairy processors.
- Multilayer Bonding Complexity:The irreversible adhesion between paperboard, polyethylene, and aluminum layers prevents standard pulping recovery, limiting recyclability claims under EU Green Deal targets.
- Substitution by PET Bottles:rPET packaging with improved barrier coatings captures share in ambient beverages where transport efficiency outweighs shelf-presence advantages of brick formats.
Strategic Opportunities
- India Beverage Expansion:Urban retail modernization in Mumbai and Delhi creates demand for shelf-ready gable-top cartons among domestic juice and flavored milk brands.
- Chemical Recycling Infrastructure:Pyrolysis and solvolysis capacity buildout in the Netherlands and Belgium promises to process multilayer laminates into feedstock for new barrier films.
- Direct-to-Store Distribution:E-commerce grocery platforms in South Korea are specifying shaped cartons with optimized cube efficiency for automated fulfillment center handling.
Industry Challenges
- Aseptic Filling Technician Shortage:Specialized knowledge of hydrogen peroxide sterilization and sterile zone maintenance remains concentrated among veteran operators, constraining line expansion timelines.
- Legacy Equipment Retrofit Costs:Converting existing cylindrical-forming filling lines to handle pre-creased shaped blanks requires mechanical redesigns that extend commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaped Liquid Cartons Market |
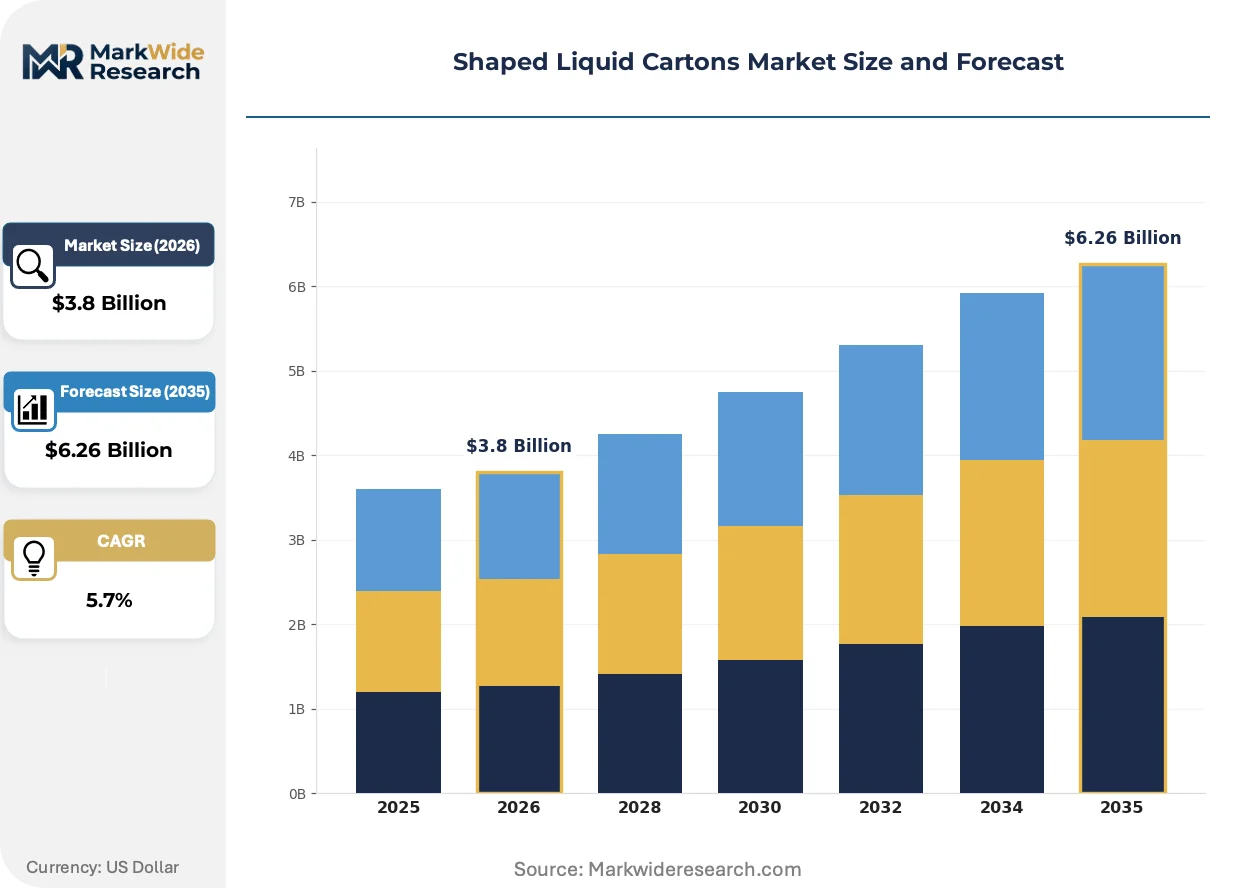
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gable Top, Brick, Flat, Cube Material: Paperboard, Plastic, Aluminum, Composite End Use: Dairy, Beverages, Sauces, Soups Size: 200ml, 500ml, 1L, 2L |
| Companies Covered | Tetra Pak International S.A., SIG Combibloc Group Ltd., Elopak AS, Greatview Aseptic Packaging Company Limited, Pactiv Evergreen Inc., Nippon Paper Industries Co., Ltd., Mondi Group, Evergreen Packaging LLC, Adam Pack S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaped Liquid Cartons Market Strategic Shifts
Material science breakthroughs and regulatory pressure on recyclability are converging to reshape how converters engineer barrier layers and how brands specify packaging formats across ambient and chilled categories.
Fiber-based barrier coatings derived from lignin and nanocellulose are replacing aluminum foil in pilot production lines for oxygen-sensitive beverages. SIG Combibloc and Elopak are validating these formulations with Nordic juice processors seeking mono-material certification. The elimination of metal layers is rendering obsolete the hydropulping separation equipment currently standard at European paper mills.
EU Green Deal packaging recyclability targets are mandating design-for-recycling principles across all member states by 2030. The regulation requires measurable recycled content quotas and standardized labeling that discloses material composition to consumers. Ambient beverage brands exporting to Germany and France are reformulating layer structures to secure EPR fee reductions and retail listing approval.
Retail chains in Germany and the Netherlands are consolidating supplier bases around filling-line partners who guarantee volume commitments and packaging innovation roadmaps. Aldi and Lidl are replacing transactional spot purchasing with multi-year framework agreements that lock in shaped carton supply for private-label dairy. This concentration of procurement authority is squeezing regional converters without integrated filling equipment leasing capabilities.
Shaped Liquid Cartons Market Segmentation
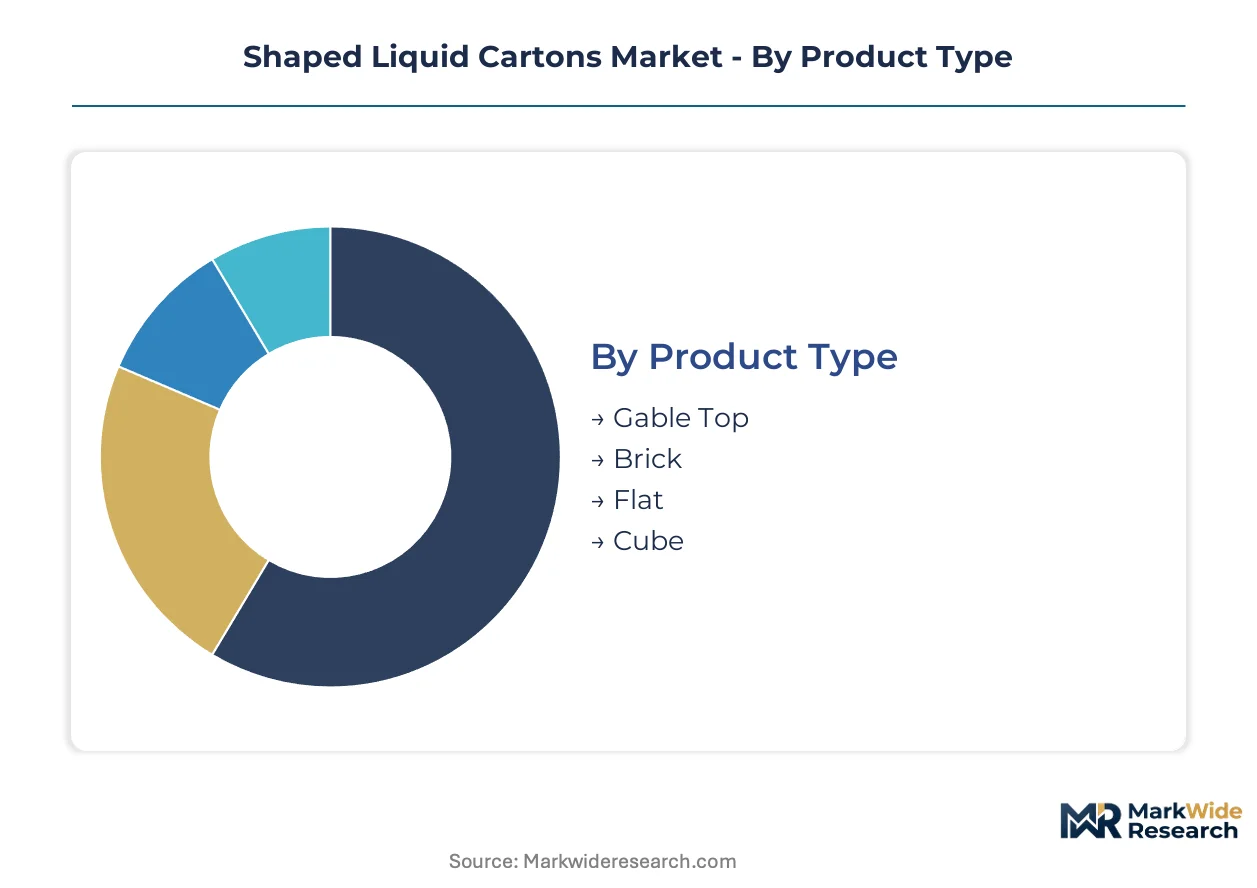
Shaped liquid carton specifications vary dramatically across product lifecycles, with ambient formats commanding longer production runs and fresh dairy cartons cycling faster due to cold-chain velocity. Understanding segment turnover patterns reveals where converter capacity binds and where equipment leasing generates recurring revenue.
Product Type:
Gable-top formats turn inventory fastest in chilled dairy networks, while brick cartons sit longer in ambient distribution pipelines before consumption.
- Gable Top:Pre-creased paperboard with polyethylene-coated interior forms the classic peaked roof profile. German and French retail chains specify this format for fresh milk where established cold-chain infrastructure supports rapid stock rotation and consumer familiarity drives repeat purchase.
- Brick:Rectangular thermoformed profiles maximize pallet cube density for ambient beverages. Demand concentrates in extended-shelf-life milk and juice categories where transport efficiency outweighs shelf-presence considerations in convenience store channels.
- Flat:Low-profile rectangular cartons optimize retail shelf facing for single-serve beverages. South Korean e-commerce grocers specify this geometry for automated fulfillment center handling efficiency.
- Cube:Equal-dimension packaging targets premium positioning and display differentiation. Nordic juice processors trial this format for organic product lines seeking visual distinction in refrigerated cases.
Gable top dominates installed base. Brick is where expansion concentrates.
Material:
Barrier performance requirements and recyclability mandates stratify material choices across cost tiers, with composite laminates commanding premium positioning and mono-material alternatives gaining regulatory preference.
- Paperboard:Bleached or natural kraft pulp forms the structural substrate, typically 300-400 gsm. Dairy processors in Germany prioritize FSC-certified sources to meet Aldi and Lidl sustainability procurement frameworks.
- Plastic:High-density polyethylene and bio-based alternatives serve niche applications. Indian beverage brands experiment with plant-derived polymers to differentiate in Mumbai and Delhi urban retail modernization.
- Aluminum:6-9 micron foil layers provide oxygen and light barriers for sensitive contents. Volatile commodity pricing complicates long-term supply agreements between converters and dairy processors.
- Composite:Bonded multilayer structures combining paperboard, polyethylene, and aluminum dominate ambient shelf-stable categories. EU Green Deal recyclability targets pressure redesign toward separable layer configurations.
Composite layers dominate current volume. Paperboard mono-material trials are climbing the fastest.
End Use:
Application-specific barrier requirements and distribution temperature regimes segment demand by operational intensity, with dairy commanding the most stringent cold-chain specifications.
- Dairy:Fresh and extended-shelf-life milk, cream, and cultured products drive format standardization. French processors adopt shaped cartons for ambient distribution to expand convenience store reach without refrigerated logistics.
- Beverages:Juice, plant-based drinks, and functional beverages span chilled and ambient segments. California EPR laws compel North American brands to verify post-consumer recycled content thresholds.
- Sauces:Viscous condiments and cooking bases require modified barrier properties. REACH compliance on polyethylene coatings shapes material selections for exporters serving EU and US jurisdictions simultaneously.
- Soups:Retort-compatible multilayer structures withstand thermal processing. Chemical recycling infrastructure buildout in the Netherlands and Belgium targets laminate recovery from this demanding application.
Dairy anchors converter capacity planning. Beverages are expanding most quickly.
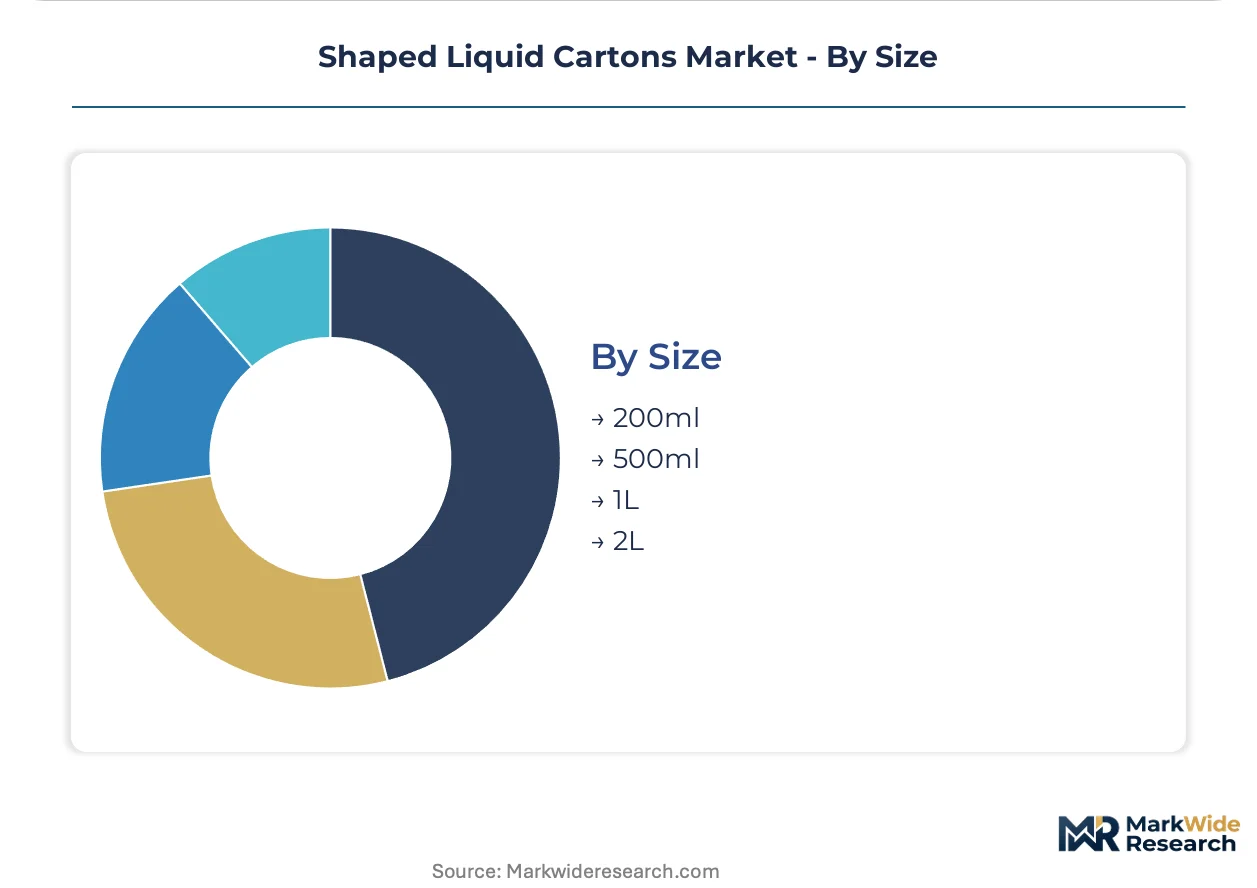
Size:
Volume segmentation reflects consumption occasion fragmentation, with single-serve formats cycling through retail faster and family sizes tying up working capital longer in household pantries.
- 200ml:Single-serve portioning targets on-the-go consumption and institutional channels. South Korean convenience retailers specify this format for automated vending and grab-and-go placement.
- 500ml:Mid-size positioning bridges individual and small-household needs. Indian flavored milk brands adopt this capacity for urban retail modernization in Delhi and Mumbai.
- 1L:Standard household sizing dominates European fresh dairy. German retail chains prioritize this format for private-label milk within multi-year framework agreements.
- 2L:Family and foodservice bulk formats optimize per-unit packaging economics. Dutch supermarket operators specify this size for value-positioned ambient juice in warehouse-style formats.
1L commands the largest installed base. 200ml is where premium positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retail chains and Indian beverage brands concentrate shaped liquid carton procurement authority, while regulatory pressure from the EU Green Deal and California EPR laws reshape material specifications across export corridors.
Germany
Aldi and Lidl drive demand through multi-year framework agreements for private-label dairy. The EU Packaging and Packaging Waste Regulation tightens recyclability mandates for multilayer containers. Bavarian dairy processors expand ambient distribution networks using extended-shelf-life formats to reach convenience stores without refrigerated logistics.
France
French processors adopt brick-shaped cartons for ambient milk distribution, reducing cold-chain dependency. REACH compliance on polyethylene barrier coatings shapes material selections for exporters serving dual EU-US jurisdictions. The Paris basin hosts reformulation trials for fiber-based barrier coatings targeting mono-material certification.
India
Urban retail modernization in Mumbai and Delhi creates demand for gable-top cartons among domestic juice and flavored milk brands. The FSSAI regulates food-contact materials for aseptic packaging applications. Maharashtra-based beverage brands experiment with plant-derived polymers to differentiate in modern trade channels.
United States
California EPR laws compel North American brands to verify post-consumer recycled content thresholds in shaped carton sourcing. The FDA governs food-contact substance notifications for polyethylene coatings. Pacific Northwest dairy cooperatives pilot chemical recycling partnerships to process multilayer laminates into barrier film feedstock.
South Korea
E-commerce grocery platforms specify flat-profile cartons optimized for automated fulfillment center handling. The MFDS regulates aseptic packaging standards for extended-shelf-life beverages. Seoul Capital Area convenience retailers drive single-serve 200ml format adoption for vending and grab-and-go placement.
Shaped Liquid Cartons Market Competitive Environment
Channel-controlling players compete with product-specialist players across a consolidated supplier base where equipment leasing capabilities determine contract lock-in. Three archetypes dominate: integrated filling-line lessors with captive financing arms, pre-sterilized blank suppliers reducing customer working capital needs, and regional production hub operators cutting logistics exposure. Strategic moves center on chemical recycling partnerships for multilayer recovery and mono-material barrier coating validation.
Among Switzerland-based integrated packaging groups, Tetra Pak International S.A. exemplifies the equipment-leasing archetype through captive financing structures. SIG Combibloc Group Ltd. represents the pre-sterilized supply model, while Elopak AS anchors the regional hub strategy for Scandinavian market proximity. These three occupy positions across distinct competitive vectors without overlapping core capabilities.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| SIG Combibloc Group Ltd. |
| Elopak AS |
| Greatview Aseptic Packaging Company Limited |
| Pactiv Evergreen Inc. |
| Nippon Paper Industries Co., Ltd. |
| Mondi Group |
| Evergreen Packaging LLC |
| Adam Pack S.A. |
| Others |
Value Chain & Pricing Dynamics
Bavarian production clusters anchor European converter capacity, with Tetra Pak's captive financing arm and SIG's pre-sterilized blank networks concentrating supply-side leverage. This geographic concentration grants integrated players pricing power over mid-sized dairy processors seeking equipment leasing terms, while aluminum foil volatility and REACH compliance costs feed downstream into contract renegotiations.
Pricing Analysis
Certification level (EU Green Deal recyclability grade, FDA food-contact tier) creates the primary spread between premium and standard supply tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with volume scale and after-sales service bundling as secondary differentiation drivers. Cost compression in the economy tier is intensifying because rPET substitution erodes brick-carton share in ambient beverages. Private-label dairy processors at Aldi and Lidl show highest price sensitivity, while premium organic juice brands absorb certification premiums with minimal volume pushback.
Supply Chain Analysis
Contract-manufacturing concentration rests with Tetra Pak International S.A., SIG Combibloc Group Ltd., and Elopak AS, which collectively control aseptic filling-line deployment across Western Europe. Geographic supply concentration centers on Germany, Sweden, and the Netherlands, with secondary capacity in France and India. Raw material dependencies draw from FSC-certified Nordic paperboard, high-density polyethylene resin, and 6-9 micron aluminum foil. Single-source vulnerability in aluminum foil supply exposes converters to commodity price swings. Distribution runs through dairy processor co-manufacturing agreements and retail chain direct procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aseptic filling technician knowledge remains concentrated among veteran operators, constraining line expansion timelines and creating captive value for equipment-leasing incumbents with training infrastructure.
For Market Incumbents: Build switching-cost moats through multi-year framework agreements that bundle equipment leasing with exclusive pre-sterilized blank supply. Expand chemical recycling partnerships in the Netherlands and Belgium to secure EPR fee reductions before EU Green Deal mandates tighten. Defend against rPET substitution by validating fiber-based barrier coatings with Nordic juice processors seeking mono-material certification. For New Entrants and Emerging Players: Build out regional production hubs in Maharashtra and Delhi to capture Indian beverage modernization demand with localized logistics. Target the 200ml single-serve format for South Korean e-commerce grocers, where automated fulfillment specifications favor flat-profile geometry. Penetrate through plant-derived polymer differentiation that addresses FSSAI compliance while signaling sustainability to urban retail buyers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated filling-line lessors with captive financing arms, where long-term contracts lock in decade-spanning equipment service income. Prioritize acquisition targets with established chemical recycling feedstock agreements or validated mono-material barrier formulations. Watch for inflection in pyrolysis capacity buildout rates across Benelux, which would signal multilayer laminate recovery economics crossing threshold viability.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis capacity in Netherlands and Belgium unlocks EPR fee reductions for multilayer laminates. |
| Mono-Material Barrier Validation | Fiber-based lignin coatings from Nordic trials secure EU Green Deal recyclability certification. |
| Regional Hub Expansion | Scandinavian production proximity cuts logistics exposure for Elopak's beverage brand customers. |
| Equipment Leasing Scale-Up | Tetra Pak's captive financing arm locks in long-term filling-line contracts with mid-sized processors. |
| Pre-Sterilized Blank Supply Agreement | SIG Combibloc reduces customer working capital needs through just-in-time blank delivery. |
Study Parameters
Desk research of EU regulatory filings, FSSAI food-contact notifications, and dairy processor annual disclosures preceded structured interviews with aseptic filling-line operators, packaging procurement managers at Aldi and Lidl, chemical recycling plant engineers, and barrier coating R&D directors. Secondary validation drew from SEC filings of publicly listed converters, REACH compliance databases, and trade customs data for aluminum foil and paperboard imports. Bottom-up capacity estimates from individual production facilities were triangulated against top-down demand projections from retail chain procurement volumes.
Assumptions held fixed across the modeling period include EU Green Deal recyclability targets achieving full enforcement, chemical recycling infrastructure maturing at announced capacity buildout rates, and aluminum foil supply remaining concentrated among current smelter networks. Segmentation dimensions modeled encompass product format (gable-top, brick, flat, cube), material configuration (composite multilayer, mono-material trials), end-use application (dairy, beverages, sauces, soups), and regional regulatory cluster (EU REACH, FDA, FSSAI, MFDS). CAGRs were derived from logistic adoption curves fitted to historical format penetration data, cross-referenced with dairy processor capex disclosure patterns.
Stress conditions across aluminum price volatility bands, chemical recycling capacity delays, and rPET barrier coating performance breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and would require revision upon structural shifts in EPR fee structures or breakthroughs in fiber-based oxygen barrier performance. Quarterly review of pyrolysis plant commissioning announcements, dairy processor equipment lease renewal rates, and FSSAI food-contact material approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Cupcake Box Market
Cartons
Reverse Tuck Cartons Market
Cartons
Litho Laminated Cartons Market
Cartons
Digital Folding Cartons Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Africa Folding Carton Market
Cartons
Global Printed Cartons Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Tetrahedron Carton Market
Cartons
Liquid Packaging Cartons Market
Cartons
Fluted Carton Trays Market
Cartons
Pick and Place Carton Packers Market
Cartons
Global Hand Carton Sealers Market
Cartons
Metallized PET Cartons Market
Cartons
Folding Cartons Market