
 Japan Contract Development and Manufacturing Organization Market | 2026-2036
Japan Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Contract Development and Manufacturing Organization Market Intelligence
Biologics manufacturing expertise is redrawing competitive boundaries across the Japanese CDMO sector. Fujifilm Corporation leverages its deep film-processing heritage to dominate cell-culture media and bioreactor operations. CMIC Holdings Co., Ltd. anchors its position through integrated clinical-to-commercial service bundles spanning development and manufacturing. Takeda Pharmaceutical Company Limited sustains captive CDMO capacity while selectively opening surplus biologics suites to external biotech partners.
A Contract Development and Manufacturing Organization provides outsourced pharmaceutical development, scale-up, and commercial production services encompassing process design, analytical validation, and regulatory-compliant manufacturing under cGMP standards. The primary purpose centers on enabling drug sponsors to access specialized bioprocessing infrastructure without capital-intensive facility construction. Clinical Trials and Analytical Testing services command premium pricing due to PMDA documentation stringency and extended validation cycles. Advanced Therapies within the Product Type dimension represent the fastest-expanding margin pool, driven by cell and gene therapy sponsors lacking in-house aseptic processing capabilities.
PMDA guidelines, JIS quality benchmarks, and METI industrial policy collectively shape facility certification requirements and cross-border data acceptance protocols for Japanese CDMOs. These frameworks elevate compliance costs but simultaneously filter out lower-capability operators, tightening effective supply. Stakeholders must monitor how PMDA's evolving regenerative medicine review standards redistribute demand between domestic biologics suites and imported capacity.
Market Dynamics
PMDA's regenerative medicine review pathway reforms are compressing sponsor timelines and forcing CDMOs to reconfigure biologics suites for accelerated batch release. This regulatory velocity is redrawing capacity allocation across the Kanto manufacturing corridor.
Growth Catalysts
- Cell Therapy Commercialization:Allogeneic CAR-T sponsors lacking aseptic processing infrastructure are contracting dedicated suites at Japanese CDMOs to bypass facility construction delays.
- METI Industrial Policy:Domestic biologics manufacturing incentives are steering foreign biotech sponsors toward Japanese CDMO partnerships over Singaporean or South Korean alternatives.
- Kanto Facility Density:Proximity between Tokyo clinical trial sites and Kanagawa manufacturing plants reduces logistics friction for temperature-sensitive biologics.
Market Restraints
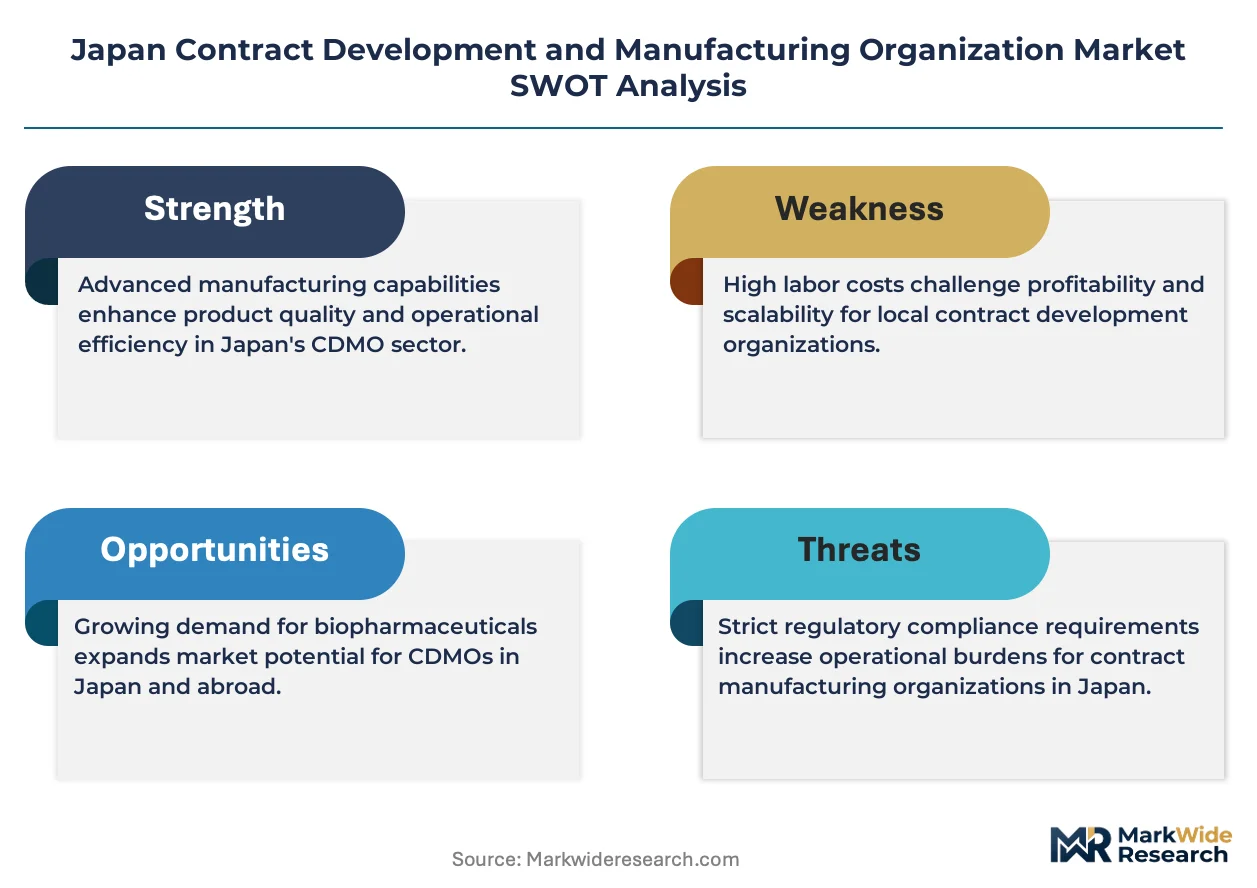
- Single-Use System Costs:Bioreactor bags and sterile connectors imported from European suppliers expose Japanese CDMOs to euro-yen volatility and extended lead times.
- PMDA Documentation Stringency:Extended analytical validation cycles for novel biologics compress effective capacity utilization rates below comparable FDA-regulated facilities.
- Domestic Talent Pool Constraints:Aseptic processing specialists and cell culture scientists command premium wages in the Tokyo metropolitan labor market.
Strategic Opportunities
- Kansai Biotech Corridor:Osaka and Kyoto prefectures host underutilized pharmaceutical infrastructure suitable for viral vector manufacturing expansion.
- PMDA Sakigake Designation:Expedited review status for regenerative therapies creates demand for companion CDMO services with dedicated regulatory affairs support.
- Digital Twin Integration:Convergence of process analytical technology with AI-driven batch prediction enables remote process optimization for overseas sponsors.
Industry Challenges
- Qualification Timeline Compression:Equipment and facility qualification under JIS Q 9001 and PMDA GMP standards requires 18-24 months, misaligning with sponsor accelerated approval schedules.
- Legacy ERP Integration:CDMOs acquiring smaller manufacturing sites face data harmonization friction between proprietary batch record systems and sponsor enterprise platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Contract Development and Manufacturing Organization Market |
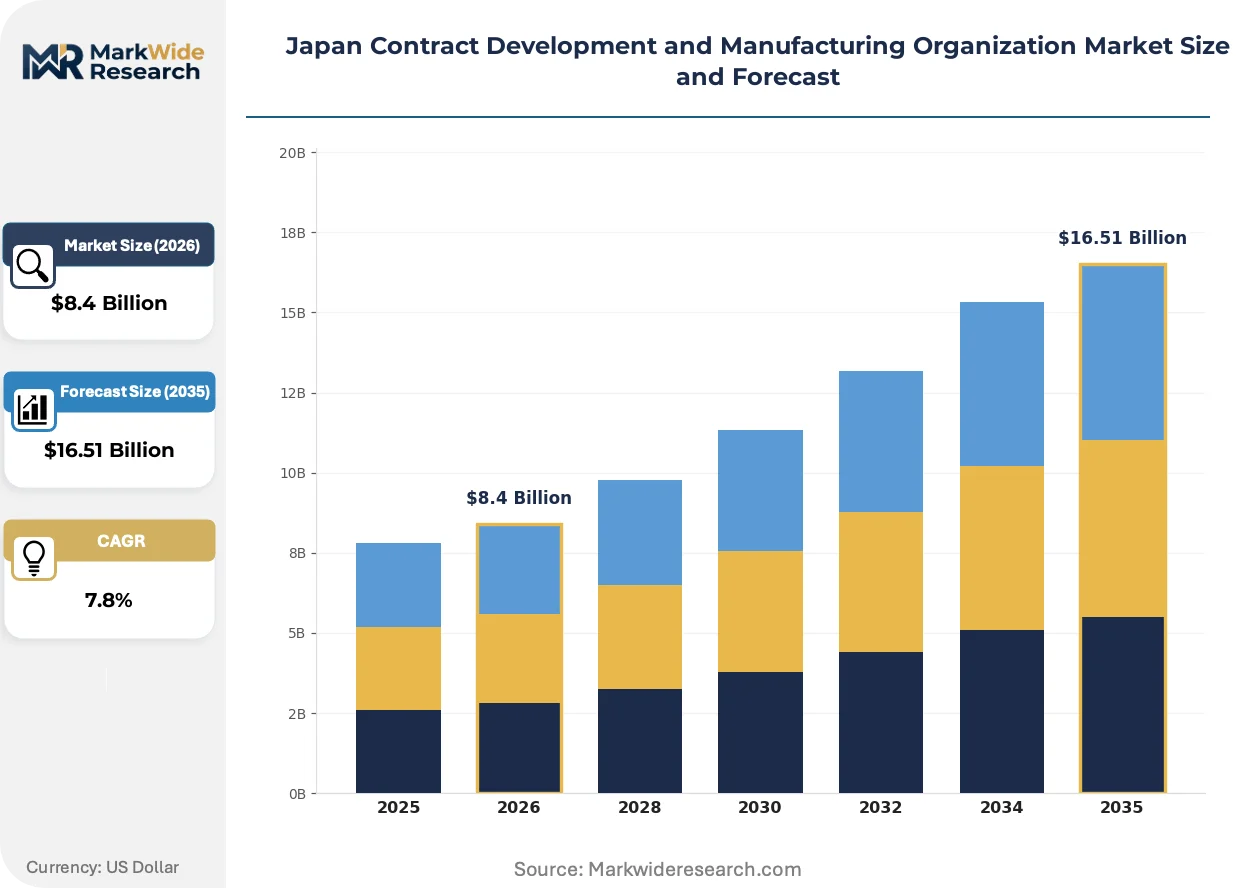
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Clinical Trials, Analytical Testing, Packaging Services End User: Pharmaceutical Companies, Biotech Firms, Medical Device Manufacturers, Research Institutions Technology: APIs, Biologics, Formulations, Aseptic Processing Product Type: Sterile Products, Oral Medications, Injectable Solutions, Advanced Therapies |
| Companies Covered | Takeda Pharmaceutical Company Limited, Astellas Pharma Inc., Fujifilm Corporation, Daiichi Sankyo Company, Limited, Chugai Pharmaceutical Co., Ltd., Otsuka Pharmaceutical Co., Ltd., Mitsubishi Tanabe Pharma Corporation, Eisai Co., Ltd., CMIC Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Contract Development and Manufacturing Organization Market Strategic Shifts & Innovations
Continuous bioprocessing architectures are displacing traditional fed-batch paradigms across Japanese biologics manufacturing. This shift is compressing facility footprints while elevating real-time release testing capabilities.
Single-use bioreactor technology is fragmenting the traditional stainless-steel infrastructure investment model. Mid-cap biotech sponsors are adopting 2000L disposable systems for Phase III commercial readiness without committing to fixed-tank capital. This flexibility is compressing the minimum viable scale for profitable CDMO operations and enabling distributed manufacturing networks across multiple Japanese prefectures.
PMDA's 2023 revision to regenerative medicine quality and safety guidelines is mandating enhanced viral safety testing for cell therapy products. Japanese CDMOs are reconfiguring quality control laboratories to accommodate next-generation sequencing-based adventitious agent detection. The advanced therapies segment is absorbing these compliance costs through premium pricing for dedicated suite access.
Biotech procurement functions are consolidating vendor relationships toward integrated clinical-to-commercial partnerships. Sponsors are displacing transactional project-based contracts with multi-year capacity reservation agreements spanning development, analytical, and commercial manufacturing. This preference shift is most visible among Tokyo-headquartered venture-backed cell therapy developers seeking regulatory continuity from first-in-human through commercial launch.
Japan Contract Development and Manufacturing Organization Market Segmentation
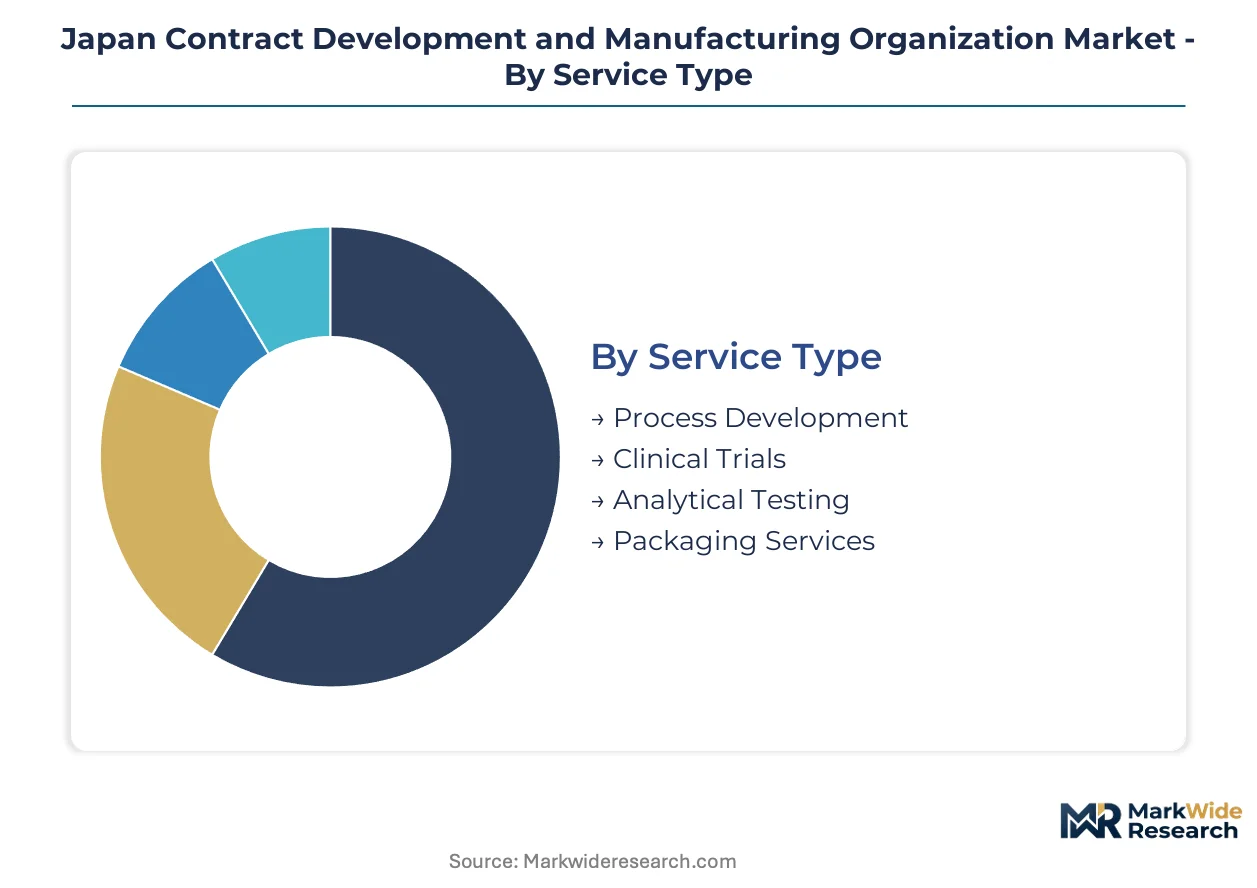
Japanese CDMO procurement flows through distinct service channels shaped by PMDA regulatory pathways and sponsor risk tolerance. Each segment category maps to specific facility certifications, batch release timelines, and geographic clustering across the Kanto manufacturing corridor.
Service Type:
Process development contracts flow through early-phase discovery partnerships, while commercial manufacturing locks into dedicated suite arrangements with multi-year capacity commitments.
- Process Development:Cell line optimization and upstream scale-up services anchor early-phase sponsor relationships. Tokyo-based biotech ventures concentrate demand here to compress IND-to-clinic timelines under PMDA consultation frameworks.
- Clinical Trials:Phase I-III manufacturing and comparator drug sourcing command premium pricing due to JIS Q 9001 documentation stringency. Kanagawa facilities capture the bulk of this demand through proximity to Tokyo clinical trial sites.
- Analytical Testing:Method validation and stability studies for PMDA submission packages.
- Packaging Services:Serialization and cold-chain labeling for commercial distribution.
By volume, Analytical Testing leads. By growth pace, Process Development is ahead.
End User:
Cost tier stratification separates multinational pharmaceutical sponsors from capital-constrained domestic biotech ventures seeking flexible contracting structures.
- Pharmaceutical Companies:Large-cap sponsors deploy captive-to-outsourced hybrid models, reserving Japanese CDMO capacity for overflow biologics production. Takeda and Astellas anchor this tier with multi-suite commitments across Kanto facilities.
- Biotech Firms:Venture-backed cell therapy developers lacking in-house aseptic infrastructure drive the steepest expansion trajectory. Allogeneic CAR-T sponsors in Tokyo's Shibuya and Toranomon clusters contract dedicated cleanroom suites.
- Medical Device Manufacturers:Combination product developers seeking drug-device integration services.
- Research Institutions:Academic spinouts requiring GMP bridging studies for translational programs.
Pharmaceutical Companies dominate contract value. Biotech Firms are expanding most quickly.
Technology:
Application focus determines facility investment profiles, with biologics suites requiring 3-5x capital intensity versus small-molecule API operations.
- APIs:Active pharmaceutical ingredient synthesis and regulatory starting material production. Osaka-based chemical synthesis specialists retain share in this mature segment despite margin compression.
- Biologics:Mammalian cell culture and microbial fermentation at commercial scale. Fujifilm's Kanagawa bioreactor complex processes monoclonal antibodies for both domestic and export markets under PMDA-FDA mutual recognition protocols.
- Formulations:Solid dosage and liquid fill-finish operations for oral and parenteral products.
- Aseptic Processing:Sterile filling and lyophilization for temperature-sensitive biologics.
APIs retain volume leadership. Biologics is gaining share fastest.
Product Type:
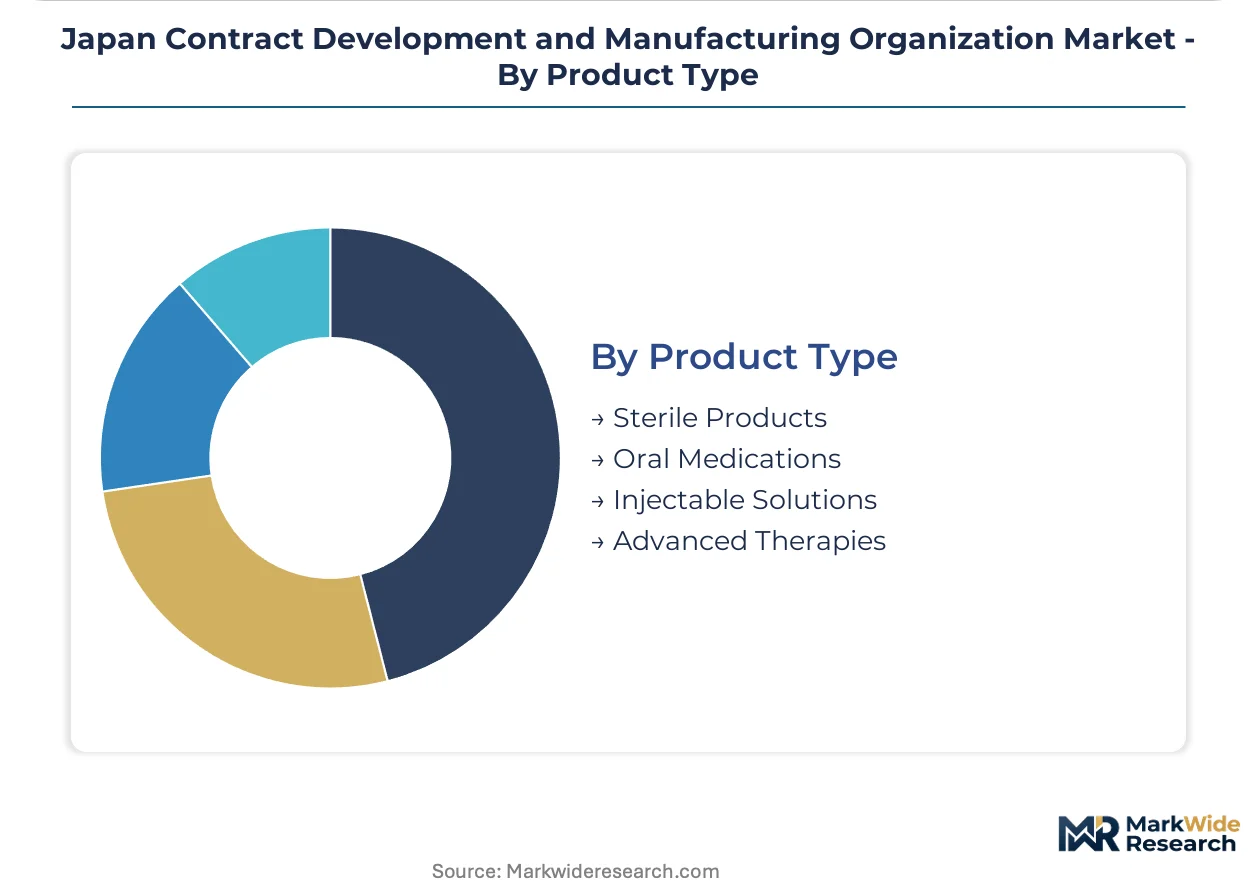
Margin concentration tracks regulatory complexity, with advanced therapies commanding dedicated suite premiums against commoditized oral medication contracts.
- Sterile Products:Parenteral formulations requiring terminal sterilization or aseptic processing. Yokohama facilities specialize in ophthalmic and inhalation sterile products for the domestic hospital market.
- Advanced Therapies:Cell and gene therapy products mandating viral safety testing under PMDA's revised regenerative medicine guidelines. CMIC Holdings and Fujifilm have reconfigured QC laboratories for next-generation sequencing-based adventitious agent detection to serve this segment.
- Oral Medications:Tablet and capsule manufacturing for established pharmaceutical portfolios.
- Injectable Solutions:Prefilled syringes and vial presentations for biologic drugs.
Oral Medications lead by volume. Advanced Therapies shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic biotech sponsors in Japan contract CDMO services for full clinical-to-commercial continuity, whereas foreign sponsors typically reserve Japanese capacity for PMDA-aligned regulatory bridging and Asia-Pacific distribution. This consumption-mix differential concentrates high-complexity biologics work in Kanto while channeling overflow small-molecule production to regional partners.
Kanto
Tokyo and Kanagawa prefectures host the densest cluster of pharmaceutical R&D facilities and CDMO manufacturing sites in Japan. METI industrial policy steers foreign biotech sponsors toward Japanese partnerships over Singaporean or South Korean alternatives. Fujifilm's Kanagawa bioreactor complex processes monoclonal antibodies for both domestic and export markets under PMDA-FDA mutual recognition protocols.
Kansai
Osaka and Kyoto prefectures host underutilized pharmaceutical infrastructure suitable for viral vector manufacturing expansion. PMDA's 2023 revision to regenerative medicine quality and safety guidelines is mandating enhanced viral safety testing for cell therapy products. Osaka-based chemical synthesis specialists retain share in the mature API segment despite margin compression.
Chubu
Nagoya anchors central Japan's medical device and combination product manufacturing corridor. JIS quality benchmarks shape facility certification requirements for sterile processing operations. Aichi prefecture's automotive heritage is cross-pollinating into precision manufacturing capabilities for drug-device integration services.
Kyushu
Fukuoka and surrounding prefectures are developing biotech infrastructure to capture overflow demand from capacity-constrained Kanto facilities. PMDA's evolving regenerative medicine review standards are redistributing demand between domestic biologics suites and imported capacity. Regional universities are spinning out academic programs requiring GMP bridging studies for translational research.
Tohoku
Sendai and northern prefectures maintain legacy pharmaceutical manufacturing sites with potential for biologics suite retrofitting. METI domestic biologics manufacturing incentives are extending to underutilized regional assets. Miyagi prefecture's reconstruction-era industrial development zones offer tax-advantaged locations for CDMO facility investment.
Japan Contract Development and Manufacturing Organization Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Japanese CDMO market. The upper tier commands multi-suite capacity commitments spanning development through commercial manufacturing. Three archetypes dominate: diversified industrial conglomerates with film-processing heritage, pharmaceutical majors operating captive-to-hybrid models, and clinical-focused service integrators. Capacity reservation agreements and regulatory affairs bundling represent the dominant competitive moves as sponsors seek continuity from first-in-human through commercial launch.
Within the integrated industrial tier, Fujifilm Corporation and CMIC Holdings Co., Ltd. exemplify contrasting strategic positions. Fujifilm leverages deep manufacturing heritage to anchor bioreactor operations and cell-culture media supply. CMIC occupies a clinical-to-commercial service integration position spanning development and manufacturing. Takeda Pharmaceutical Company Limited represents the pharmaceutical-major archetype, sustaining captive capacity while selectively opening surplus biologics suites to external partners.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Astellas Pharma Inc. |
| Fujifilm Corporation |
| Daiichi Sankyo Company, Limited |
| Chugai Pharmaceutical Co., Ltd. |
| Otsuka Pharmaceutical Co., Ltd. |
| Mitsubishi Tanabe Pharma Corporation |
| Eisai Co., Ltd. |
| CMIC Holdings Co., Ltd. |
| Others |
Cost & Logistics Intelligence
PMDA GMP certification requirements gate both facility qualification timelines and the premium pricing tiers that dedicated biologics suites command. METI industrial policy steers foreign sponsors toward domestic partnerships, compressing price competition for JIS-compliant capacity while elevating documentation-heavy service bundles.
Pricing Analysis
Long-term capacity reservation agreements dominate sponsor-CDMO contracting, displacing transactional project-based structures as biotech procurement consolidates vendor relationships. Price differentiation rests on suite certification grade and regulatory affairs bundling, with PMDA-aligned documentation support commanding substantial premiums. Cost compression in small-molecule API manufacturing intensifies as Osaka-based chemical synthesis specialists compete on scale. Venture-backed cell therapy developers in Tokyo show least price sensitivity, prioritizing regulatory continuity over per-batch economics.
Supply Chain Analysis
Extended lead times for single-use bioreactor bags and sterile connectors from European suppliers strain inventory planning across Kanto manufacturing facilities. Japanese CDMOs draw from German and American precision equipment vendors, alongside domestic cell-culture media producers anchored in Kanagawa. Euro-yen volatility creates single-source vulnerability for disposable bioprocessing components. Distribution runs through temperature-controlled logistics networks linking Tokyo clinical trial sites to Kanagawa commercial manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japanese CDMO market functions as a defensive-moat arena where PMDA regulatory entrenchment creates formidable switching costs for sponsors seeking clinical-to-commercial continuity.
For Market Incumbents: Fortify multi-suite capacity commitments across the Kanto corridor to capture overflow demand from Takeda and Astellas captive facilities. Deepen backward integration into cell-culture media production to offset euro-denominated single-use system exposure. PMDA documentation stringency threatens margin compression; invest in dedicated regulatory affairs bundling to sustain premium pricing.
For New Entrants and Emerging Players: Viral vector manufacturing capacity gaps in the Kansai biotech corridor represent the most penetrable white-space target, with Osaka and Kyoto prefectures hosting underutilized pharmaceutical infrastructure. Allogeneic CAR-T sponsors lacking aseptic processing capabilities offer a concentrated entry point. Position through PMDA Sakigake Designation companion services to differentiate from established Kanto operators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use bioreactor deployments, enabling mid-scale distributed manufacturing networks without fixed-tank commitments. Target clinical-to-commercial service integrators with established PMDA consultation frameworks. Monitor PMDA regenerative medicine review pathway reforms as the critical inflection signal for capacity reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Suite Capacity Reservation | Locks in sponsor relationships spanning IND through commercial launch under PMDA continuity. |
| Regulatory Affairs Bundling | Compresses sponsor timeline risk by embedding PMDA consultation expertise within manufacturing contracts. |
| Single-Use Technology Adoption | Reduces fixed-capital requirements while enabling rapid suite reconfiguration for cell therapy campaigns. |
| Kansai Corridor Expansion | Captures viral vector demand from Kyoto-Osaka academic spinouts requiring GMP bridging capacity. |
| Digital Twin Integration | Enables remote process optimization for overseas sponsors through AI-driven batch prediction convergence. |
Research Approach
Desk research of PMDA submission databases, METI industrial policy white papers, and JIS certification registries preceded structured interviews with biologics manufacturing executives, regulatory affairs directors at CDMOs, and procurement leads at Tokyo-headquartered cell therapy ventures. Secondary validation drew from pharmaceutical trade customs data, facility inspection records, and sponsor pipeline disclosures. Bottom-up capacity utilization modeling triangulated against top-down sponsor spending pattern analysis.
Variance decomposition across service type, technology platform, and prefecture-level geographic clustering shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level capacity expansion trajectories and sponsor contract value intensities. Modeled inputs incorporated bioreactor scale-up economics, PMDA review timeline distributions, and single-use system cost curves.
Forecasts assume regulatory continuity in PMDA and METI regimes; material shifts in regenerative medicine review standards or domestic manufacturing incentives would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market