
 Radiopharmaceutical Synthesizer Market | 2026-2036
Radiopharmaceutical Synthesizer Market Size, Share, and Industry Trends Forecast 2026-2036
Radiopharmaceutical Synthesizer Market Analytics
Belgian cyclotron engineering capacity is broadening as IBA leverages its proton therapy heritage to dominate high-field cyclotron supply for tracer production. Elysia sustains specialized positioning in compact, hospital-deployable synthesis modules that reduce radiopharmaceutical turnaround times. Advanced Cyclotron Systems anchors North American manufacturing scale through its distributed cyclotron network serving regional radiopharmacy hubs.
A radiopharmaceutical synthesizer is an automated or semi-automated electromechanical system that performs radiochemical synthesis under controlled temperature, pressure, and shielding conditions to produce diagnostic or therapeutic radioisotopes for patient administration. These systems typically integrate HPLC purification, sterile filtration, and quality control sensors to yield single-patient doses of fluorine-18 or gallium-68 labeled compounds for molecular imaging. Modular synthesizer platforms command premium positioning due to their flexibility across multiple tracer protocols and reduced facility footprint requirements. Automated systems are displacing manual synthesis workflows in diagnostic centers where technician radiation exposure limits and batch reproducibility standards are tightening. Oncology applications absorb the dominant share of installed capacity, though neurology imaging for Alzheimer's biomarker distribution is gaining fastest adoption among research institutions.
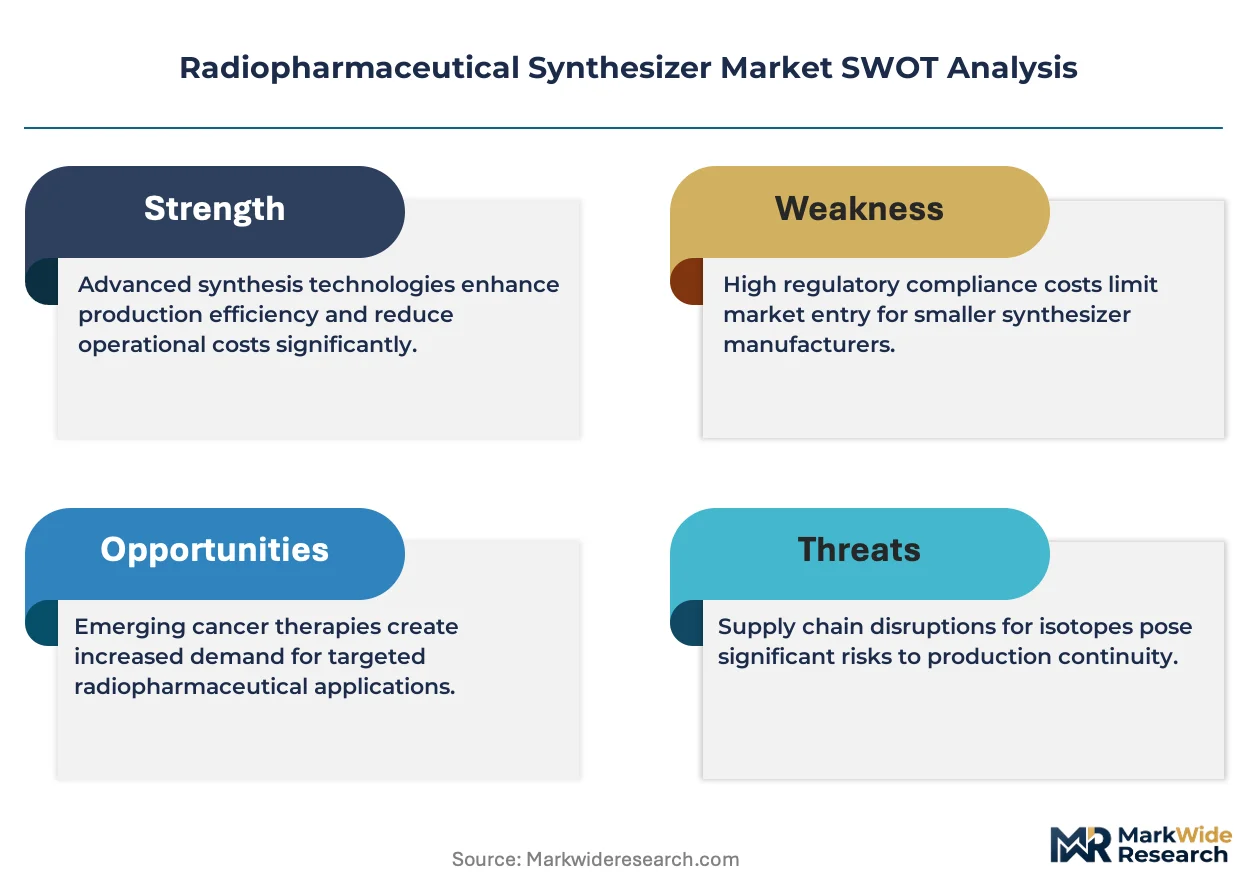
The FDA enforces current good manufacturing practice standards under 21 CFR Part 212 for PET drug production, compelling synthesizer manufacturers to embed process analytical technology and electronic batch records. EMA's Annex 1 revision on sterile medicinal products extends contamination control requirements to aseptic radiopharmaceutical synthesis environments, reshaping equipment validation protocols across European installations. ISO 13485 quality management systems and IEC 60601 electrical safety standards govern device design for clinical deployment. Stakeholders must weigh cyclotron versus generator-based sourcing strategies against evolving reimbursement codes for theranostic procedures.
Market Dynamics
Automated synthesis platforms are compressing radiopharmaceutical production timelines while FDA and EMA quality mandates force hardware redesigns around process analytical technology integration.
Growth Catalysts
- Theranostic reimbursement expansion:Medicare coverage for prostate cancer imaging agents is widening hospital capital budgets for tracer production infrastructure.
- 21 CFR Part 212 enforcement:The FDA's current good manufacturing practice mandate for PET drugs is accelerating replacement cycles for legacy manual synthesis equipment.
- Cyclotron infrastructure densification:Regional radiopharmacy hubs in Germany and Japan are installing satellite synthesis modules to reduce cold chain logistics burdens.
Market Restraints
- High-purity precursor dependency:Fluorine-18 and gallium-68 precursor supply concentrates among three European specialty chemical suppliers, creating input vulnerability.
- Cyclotron capital intensity:Hospital-based proton accelerator installations require concrete shielding and regulatory licensing that extends facility commissioning by eighteen to thirty-six months.
- Technician radiation exposure limits:OSHA and national occupational safety caps on annual dose accumulation constrain batch throughput in manual synthesis workflows.
Strategic Opportunities
- Generator-based isotope sourcing:Strontium-82/rubidium-82 and germanium-68/gallium-68 generators are eliminating cyclotron dependency for cardiac and neuroendocrine imaging in mid-tier hospitals.
- Neurology biomarker protocols:Tau and amyloid PET tracers for Alzheimer's staging are creating dedicated synthesis lines at academic medical centers in the United States and Japan.
- EMA Annex 1 revision:The European sterile medicinal products directive is mandating isolator technology upgrades that favor modular synthesizer platforms with integrated containment.
Industry Challenges
- Radiochemist talent scarcity:The specialized skill set combining synthetic chemistry, radiation safety, and quality systems is concentrating at major academic centers, constraining regional radiopharmacy staffing.
- Multi-trainer equipment validation:Synthesizer platforms supporting fluorine-18, gallium-68, and copper-64 protocols require protocol-specific analytical method transfers that extend commissioning timelines.
- Legacy LIMS integration:Electronic batch record systems from established synthesizer vendors often lack API compatibility with hospital enterprise resource planning platforms, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiopharmaceutical Synthesizer Market |
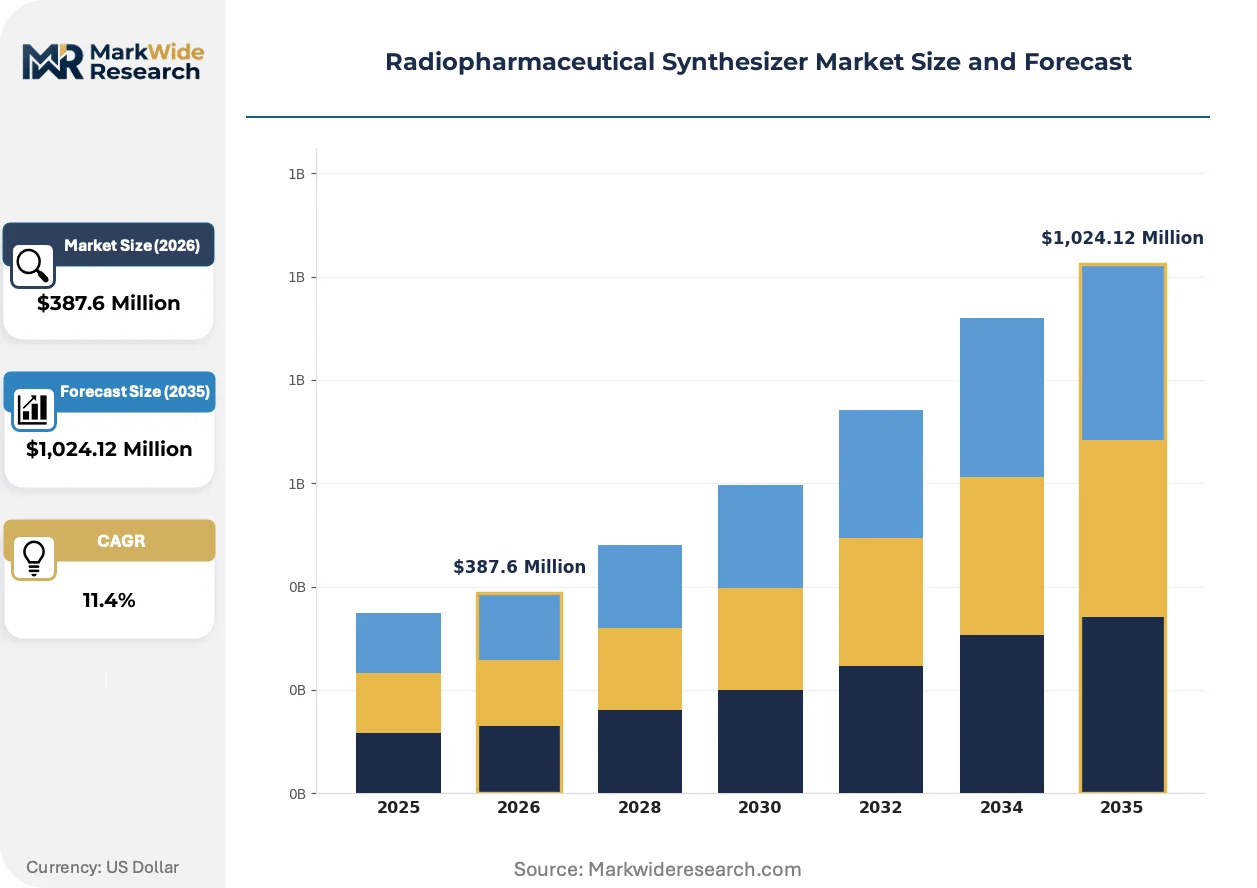
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generator-Based, Liquid Scintillation, Modular Synthesizer, Cold Kit End User: Hospitals, Research Institutions, Diagnostic Centers, Clinics Technology: Cyclotron, Nuclear Reactor, Automated Systems, Manual Systems Application: Oncology, Cardiology, Neurology, Infection Imaging |
| Companies Covered | IBA, Elysia, Advion, Advanced Cyclotron Systems, JSC Isotope, Lantheus Medical Imaging, LabLogic Systems, NorthStar Medical Technologies, Mercurius Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiopharmaceutical Synthesizer Market Evolving Landscape
Microfluidic reaction chambers and continuous flow chemistry are displacing conventional batch synthesis architectures, enabling tracer production at reduced volumes and higher specific activities for precision dosing applications.
Disposable cassette systems are electrifying radiochemical synthesis workflows by eliminating cross-contamination risks between sequential tracer batches. Major cancer centers in the United States are adopting single-use fluidic manifolds for same-day gallium-68 DOTATATE production. This architecture is compressing facility decontamination cycles from hours to minutes while reducing technician radiation exposure.
The FDA's 2023 guidance on process analytical technology for PET drug manufacturing is mandating real-time release testing capabilities in new synthesizer installations. Equipment vendors are embedding UV, radio-HPLC, and pH sensors directly into synthesis manifolds. European installations under EMA oversight are responding fastest, with German university hospitals leading validation of integrated quality control modules.
Hospital procurement departments are unbundling synthesizer hardware from consumable supply agreements, reversing the historical bundled service model. Academic medical centers in Japan are negotiating separate precursor sourcing contracts to secure multi-vendor price leverage. This pattern is most pronounced in Tokyo and Osaka metropolitan areas where cyclotron network density creates supplier choice.
Radiopharmaceutical Synthesizer Market Segmentation
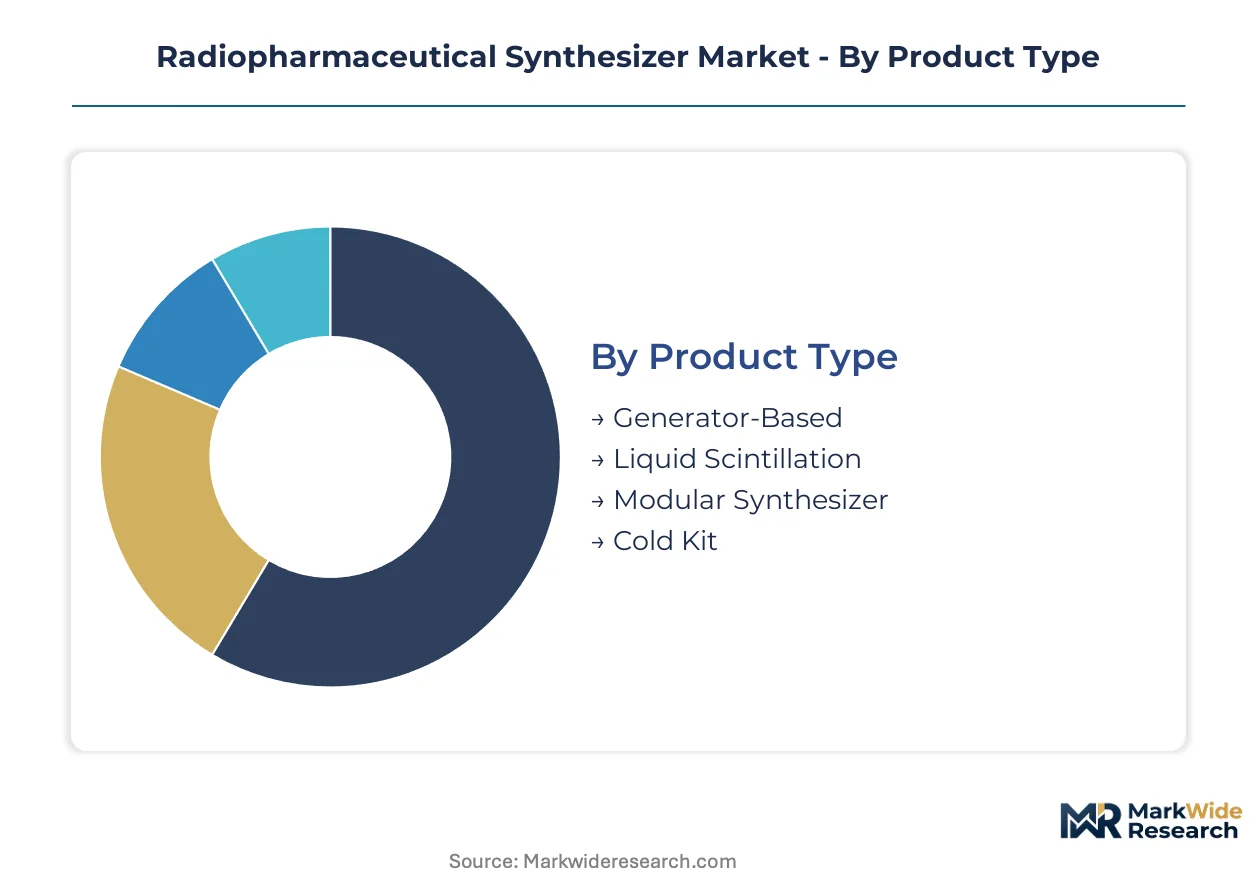
Radiopharmaceutical synthesizer segmentation reveals how capital allocation splits between cyclotron-dependent infrastructure and generator-based alternatives. Procurement patterns diverge sharply across end-use settings, with hospital nuclear medicine departments prioritizing automation while academic centers retain manual synthesis capacity for research flexibility.
Product Type:
Technical specification tiers separate high-throughput cyclotron-integrated platforms from compact generator-fed units.
- Modular Synthesizer:These platforms integrate HPLC purification, sterile filtration, and quality control sensors within a single shielded enclosure. Demand concentrates at German university hospitals and Tokyo metropolitan cancer centers where multi-tracer protocols require rapid reconfiguration between fluorine-18 and gallium-68 production runs.
- Generator-Based:Self-contained strontium-82/rubidium-82 and germanium-68/gallium-68 systems eliminate cyclotron dependency through parent-daughter isotope decay chains. Mid-tier US hospitals in secondary metropolitan areas are deploying these units to bypass concrete shielding requirements and eighteen-to-thirty-six-month licensing timelines.
- Liquid Scintillation:Benchtop radioactivity measurement systems support quality control verification in smaller diagnostic facilities.
- Cold Kit:Pre-formulated non-radioactive precursor vials enable technetium-99m labeling for cardiac stress testing in high-volume clinics.
Mature deployment sits with modular synthesizers. Newer deployment is concentrated in generator-based systems.
End User:
Capital intensity and regulatory burden create distinct procurement profiles across institutional settings.
- Hospitals:Academic medical centers with in-house cyclotron infrastructure represent the anchor installed base. These facilities operate under FDA 21 CFR Part 212 and EMA Annex 1 compliance frameworks, driving replacement demand toward integrated process analytical technology.
- Research Institutions:National laboratories and university radiochemistry departments maintain manual synthesis workflows for novel tracer development. Funding from the National Institutes of Health and Japan Agency for Medical Research and Development sustains capacity expansion for tau and amyloid PET biomarker programs.
- Diagnostic Centers:Freestanding imaging facilities rely on regional radiopharmacy supply chains rather than on-site production.
- Clinics:Small-volume outpatient settings purchase unit doses from commercial distributors.
Volume leadership belongs to hospitals. Fastest capability expansion is occurring at research institutions.
Technology:
Isotope sourcing strategy determines hardware selection and facility infrastructure requirements.
- Cyclotron:Proton accelerators producing fluorine-18, carbon-11, and nitrogen-13 require concrete shielding bunkers and specialized HVAC systems. IBA in Belgium and Advanced Cyclotron Systems in Canada dominate supply to major oncology centers.
- Automated Systems:Robotic synthesis platforms with disposable cassettes are displacing manual workflows where OSHA technician dose limits constrain batch throughput. German installations under EMA oversight are leading validation of integrated quality control modules.
- Nuclear Reactor:Molybdenum-99 production for technetium-99m generators depends on aging research reactor infrastructure.
- Manual Systems:Legacy hot cell configurations persist in budget-constrained settings and specialized research applications.
Established capacity centers on cyclotron technology. Fastest installation growth is occurring in automated systems.
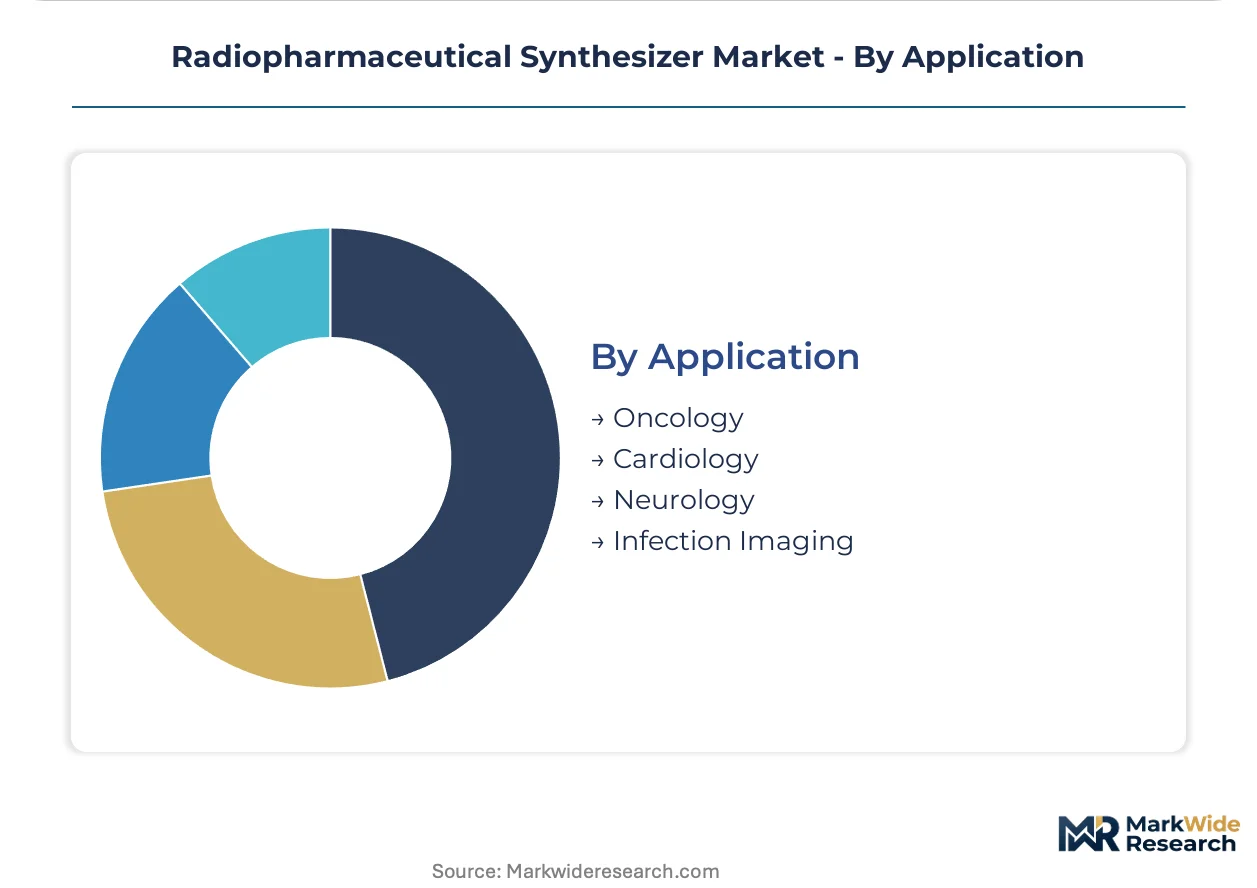
Application:
Clinical indication drives tracer selection and synthesizer protocol configuration.
- Oncology:Fluorine-18 FDG for glucose metabolism imaging and gallium-68 DOTATATE for neuroendocrine tumor detection absorb the dominant share of production capacity. Medicare reimbursement expansion for prostate cancer imaging agents is widening hospital capital budgets in the United States.
- Neurology:Tau and amyloid PET tracers for Alzheimer's staging are creating dedicated synthesis lines at academic medical centers. Japanese institutions are prioritizing these capabilities for aging population diagnostics.
- Cardiology:Rubidium-82 myocardial perfusion imaging supports high-throughput stress testing in US hospital networks.
- Infection Imaging:Fluorine-18 fluorodeoxyglucose applications in prosthetic joint infection detection represent a niche indication.
Revenue concentration remains with oncology. Steepest expansion trajectory is occurring in neurology biomarker protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cyclotron infrastructure density and precursor supply networks anchor radiopharmaceutical synthesizer deployment across three continents. Belgium's high-field accelerator engineering feeds German hospital networks, while Japanese metropolitan clusters drive Asia-Pacific adoption.
United States
Medicare reimbursement expansion for prostate cancer imaging agents is widening hospital capital budgets for tracer production infrastructure. The FDA enforces 21 CFR Part 212 current good manufacturing practice standards, compelling process analytical technology integration. Academic medical centers in Boston and Houston operate the densest cyclotron networks for same-day gallium-68 DOTATATE production.
Germany
University hospitals in Munich and Heidelberg are validating integrated quality control modules for multi-tracer protocols. EMA Annex 1 revision on sterile medicinal products mandates isolator technology upgrades favoring modular synthesizer platforms. The Rhine-Ruhr and Bavarian clusters concentrate Europe's highest installed density of automated synthesis systems.
Japan
Aging population diagnostics are accelerating tau and amyloid PET tracer synthesis line deployment for Alzheimer's staging. METI funding through the Japan Agency for Medical Research and Development sustains capacity expansion at national university hospitals. Tokyo and Osaka metropolitan areas host the densest cyclotron networks in Asia-Pacific, enabling same-day patient dosing.
Belgium
IBA leverages proton therapy heritage to dominate high-field cyclotron supply for tracer production across European hospital networks. The country's national pharmaceutical regulator enforces EMA-aligned sterile manufacturing standards. Louvain-la-Neuve anchors continental engineering capacity for compact accelerator systems serving regional radiopharmacy hubs.
Canada
Advanced Cyclotron Systems anchors North American manufacturing scale through distributed cyclotron networks serving regional radiopharmacy hubs. Health Canada aligns PET drug oversight with FDA 21 CFR Part 212 frameworks, streamlining cross-border equipment validation. Vancouver and Toronto metropolitan clusters concentrate the country's hospital-based synthesis capacity for fluorine-18 FDG production.
Radiopharmaceutical Synthesizer Market Competitive Landscape
Global majors compete with regional champions across cyclotron engineering and synthesis module specialization. The vendor base separates into three tiers: integrated proton therapy accelerators, compact hospital-deployable systems, and generator-based alternatives eliminating cyclotron dependency. Belgian and Canadian engineering houses occupy distinct positions in high-field versus distributed manufacturing scale. Competitive dynamics center on M&A for precursor supply control and strategic partnerships for disposable cassette technology licensing.
Within the high-field accelerator tier, IBA and Advanced Cyclotron Systems exemplify divergent geographic anchoring strategies. Elysia occupies a specialized position in compact synthesis modules. These three names represent the spectrum from proton therapy heritage to regional manufacturing scale to hospital-deployable miniaturization, illustrating how engineering origin and facility footprint requirements segment competitive positioning across the installed base.
| Leading Market Players |
|---|
| IBA |
| Elysia |
| Advion |
| Advanced Cyclotron Systems |
| JSC Isotope |
| Lantheus Medical Imaging |
| LabLogic Systems |
| NorthStar Medical Technologies |
| Mercurius Health |
| Others |
Value Network & Pricing Analysis
Hospital procurement departments unbundling synthesizer hardware from consumable supply agreements are forcing vendors to restructure pricing models and exposing precursor sourcing costs to direct negotiation pressure. This shift reverses historical bundled service models and compresses margins on equipment-only contracts while amplifying price transparency across the installed base.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier vendors from standard equipment suppliers in hospital capital procurement. Pricing stratifies across premium, standard, and economy tiers based on process analytical technology integration depth and FDA 21 CFR Part 212 compliance certification. Cost compression in standard-tier modular synthesizers is intensifying because Japanese academic medical centers are consolidating procurement through GPO contracts. Research institutions exhibit lowest price sensitivity due to NIH and Japan Agency for Medical Research and Development grant funding, while mid-tier US hospitals in secondary metropolitan areas face acute capital constraint.
Supply Chain Analysis
Direct-to-hospital channels handle academic medical center demand, while regional radiopharmacy hubs in Germany and Japan feed distributed diagnostic networks through centralized production. Fluorine-18 and gallium-68 precursor supply concentrates in Belgium, Germany, and the Netherlands, drawing from three European specialty chemical suppliers. Equipment manufacturing is anchored in Belgium and Canada, with cyclotron engineering capacity tethered to IBA's Louvain-la-Neuve facilities and Advanced Cyclotron Systems' Vancouver-Toronto corridor. Single-source vulnerability in high-purity precursor supply creates input risk exposure. Distribution runs through specialized radiopharmaceutical logistics partners with cold chain certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 212 enforcement has erected a cost-of-compliance barrier that favors incumbent vendors with validated quality systems and electronic batch record capabilities, creating a moat that capital-constrained entrants cannot cross without substantial regulatory investment.
For Market Incumbents: Extend process analytical technology integration into next-generation synthesis platforms to capture replacement cycles at German university hospitals and Tokyo cancer centers. Backward integration into precursor supply through strategic partnerships with Belgian and Dutch specialty chemical houses will defend margin position against unbundled procurement pressure. EMA Annex 1 revision on sterile medicinal products represents a regulatory shift that rewards early isolator technology adopters. For New Entrants and Emerging Players: Begin with generator-based system deployment targeting mid-tier US hospitals in secondary metropolitan areas where cyclotron capital intensity blocks incumbent expansion. Neurology biomarker protocols for tau and amyloid PET tracers at academic medical centers in Japan offer the most penetrable application segment. A reimbursement strategy aligned with Medicare coverage expansion for prostate cancer imaging agents provides the essential go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors disposable cassette technology specialists with validated single-use fluidic manifold platforms. Long-term viability centers on five-to-ten-year contracts with regional radiopharmacy hubs requiring automation to meet OSHA technician dose limits. Acquisition targets should demonstrate EMA-compliant isolator integration. The signal to watch is FDA guidance on real-time release testing mandating sensor-embedded synthesis manifolds.| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Integration | FDA 21 CFR Part 212 compliance accelerates hospital replacement demand for sensor-embedded platforms. |
| Disposable Cassette Technology Licensing | Single-use fluidic manifolds reduce decontamination cycles and technician radiation exposure at US cancer centers. |
| Backward Integration into Precursor Supply | Captive supply of fluorine-18 and gallium-68 precursors defends margins against unbundled procurement. |
| EMA Annex 1 Isolator Validation | German university hospitals prioritize modular synthesizers with integrated containment for sterile compliance. |
| Reimbursement Strategy Alignment | Medicare coverage expansion for prostate cancer imaging widens hospital capital budgets for tracer infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cyclotron engineering directors, nuclear medicine department heads, hospital procurement managers, radiopharmacy operations leads, and regulatory affairs specialists at FDA and EMA were combined with secondary validation from FDA 510(k) submissions, EMA medical device registration databases, hospital capital expenditure disclosures, and cyclotron installation records. Bottom-up equipment shipment tracking and top-down healthcare infrastructure spending analysis were triangulated to establish market sizing.
Data-stream reconciliation across cyclotron installation databases, precursor import records, and hospital procurement contract disclosures informed the analytical framework. Segmentation modeling spanned product type, end user, technology, and application dimensions across the projection horizon. CAGRs were derived from installed base expansion rates and replacement cycle analysis. Forecast inputs incorporated cyclotron infrastructure densification timelines and reimbursement code expansion patterns for theranostic procedures.
Underlying measurement precision varies by segment; modular synthesizer and automated system categories carry tighter precision than manual system and cold kit segments due to more transparent equipment registration pathways. Forecasts reflect assumptions about EMA Annex 1 implementation timelines and Medicare reimbursement expansion velocity. Supply concentration in European precursor production and radiochemist talent scarcity represent specific risk factors that could revise outlooks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Small Molecule CDMO Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Radiosynthesis Equipment Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Medication Dispenser Market