
 Dialysis Disposable Devices Market | 2026-2036
Dialysis Disposable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Dialysis Disposable Devices Market Intelligence
Revenue from high-flux dialyzers and biocompatible bloodline sets is tilting the profit pool away from conventional low-flux products. Fresenius Medical Care leverages its vast dialysis center network to promote its proprietary disposables. Baxter International Inc. specializes in peritoneal and home dialysis solutions, creating a distinct market niche. Nipro Corporation sustains its position through large-scale manufacturing and a broad product portfolio.
Dialysis disposable devices are single-use medical products for extracorporeal blood purification in renal replacement therapy. These components, such as dialyzers containing thousands of polysulfone hollow fibers, remove toxins and waste from the blood. Among product types, dialyzers command the largest share, while hemodialysis remains the principal application. However, the home dialysis application segment shows the most significant expansion.
Stringent approvals from the U.S. FDA, compliance with the EU's Medical Device Regulation (MDR), and clearance from China's NMPA govern market entry. These regulatory frameworks enforce strict biocompatibility and sterility standards, shaping product development and material sourcing. The key challenge for manufacturers will be aligning product innovation with evolving reimbursement policies for home and continuous therapies.
Market Dynamics
The structural shift toward home-based care models is the central force shaping the dialysis disposable devices market. This transition away from centralized clinics alters requirements for product design, packaging, sterilization, and supply chain logistics to support individual patient use.
Growth Catalysts
- Favorable Reimbursement Policies:Government initiatives and updated reimbursement schedules in countries like the United States are actively promoting the adoption of home hemodialysis and peritoneal dialysis, directly boosting demand for associated disposable kits.
- Aging Demographics:The rising prevalence of chronic kidney disease (CKD) and end-stage renal disease (ESRD), particularly within the aging populations of developed nations such as Germany and Japan, expands the fundamental patient base requiring renal replacement therapy.
- Material Science Advances:The development and broader use of advanced biocompatible polymers, such as modified polysulfone and polyethersulfone for dialyzer membranes, enhance device performance, reduce inflammatory responses, and improve patient safety.
Market Restraints
- High Input Material Costs:Volatility in the price of medical-grade polymers, specifically the polysulfone used for hollow fiber membranes, directly impacts the manufacturing cost structure of dialyzers and can compress supplier margins.
- Regulatory Approval Hurdles:Stringent and lengthy clearance processes from regulatory bodies, including the U.S. FDA and compliance with the EU's Medical Device Regulation (MDR), create significant barriers to entry and delay the launch of innovative products.
- Concentrated Supplier Base:The global supply of critical components like hollow fiber membranes is concentrated among a small number of manufacturers, creating potential bottlenecks and supply chain vulnerabilities for device assemblers.
Strategic Opportunities
- Underpenetrated Geographic Markets:Expanding access to dialysis in large, developing economies across Latin America and Southeast Asia, where CKD incidence is rising, represents a significant opportunity for market entry and volume growth.
- Wearable Artificial Kidney Systems:The development of next-generation portable and wearable dialysis devices creates a new market segment for miniaturized, highly specialized disposables, moving beyond current home dialysis formats.
- Eco-Friendly Materials:Innovating with biodegradable or recyclable polymers for device components and packaging addresses growing environmental concerns over medical waste, offering a key point of differentiation for environmentally conscious healthcare providers.
Industry Challenges
- Patient Training and Adherence:Ensuring patients and caregivers are adequately trained to manage home dialysis safely and effectively is a major operational challenge that can impact therapy outcomes and device utilization rates.
- Complex Home Logistics:Managing a decentralized supply chain to deliver sterile, often temperature-sensitive disposables to thousands of individual homes on a just-in-time basis requires sophisticated logistical capabilities.
- Sterilization and Biocompatibility Compliance:Maintaining consistent adherence to global standards like ISO 10993 for biocompatibility across a diverse and geographically dispersed manufacturing footprint presents an ongoing compliance challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dialysis Disposable Devices Market |
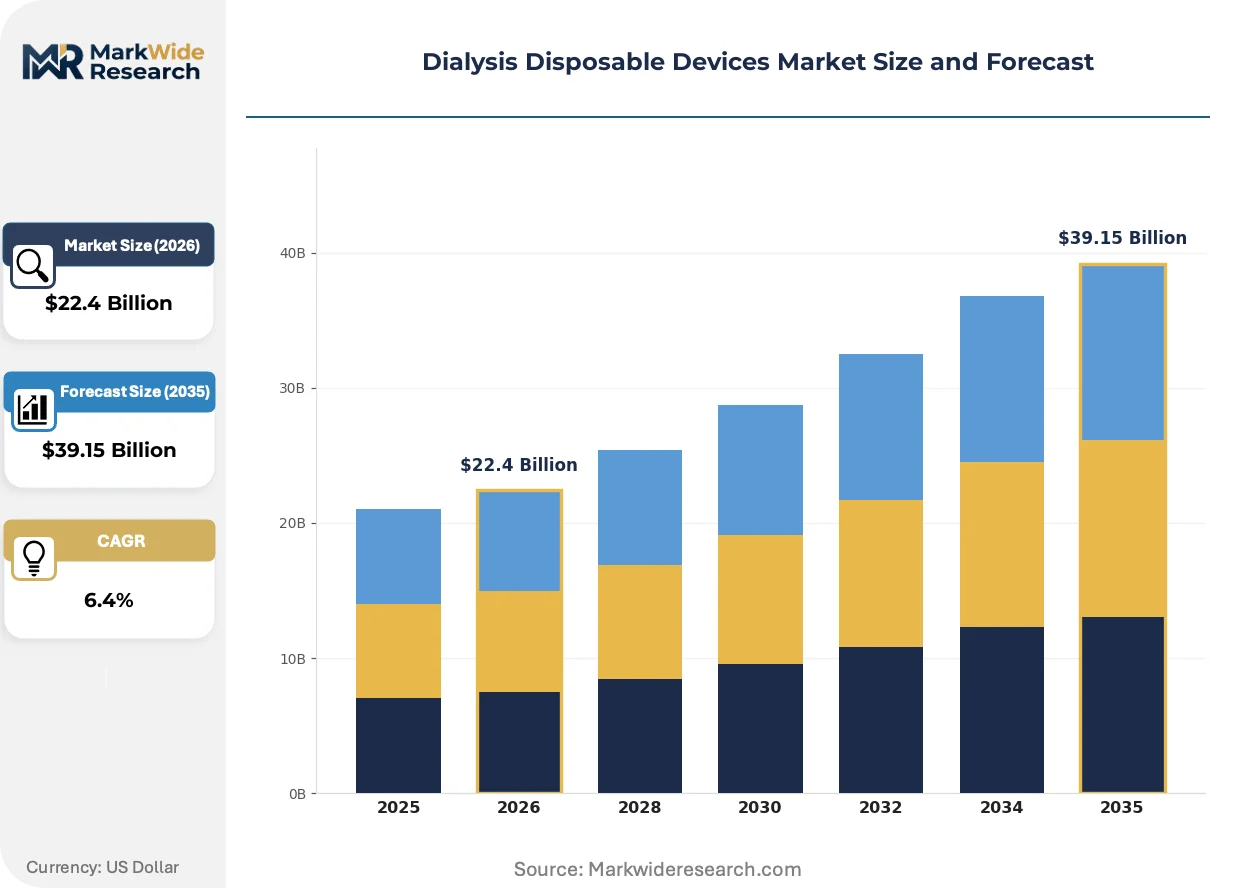
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $39.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialyzer, Bloodline Set, Catheter, Concentrates Application: Hemodialysis, Peritoneal Dialysis, Continuous Renal Replacement Therapy, Home Dialysis End User: Dialysis Centers, Ambulatory Surgical Centers, Nephrology Clinics, Home Care Providers Technology: Hollow Fiber, Flat Sheet, High Flux, Low Flux |
| Companies Covered | Nipro Corporation, JMS Co. Ltd., Baxter International Inc., Toray Medical Co. Ltd., Asahi Kasei Medical Co. Ltd., B. Braun Melsungen AG, Nikkiso Co. Ltd., Becton Dickinson and Co., Fresenius Medical Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dialysis Disposable Devices Market Strategic Shifts & Innovations
Product innovation is increasingly focused on enhancing the safety, convenience, and data connectivity of disposables for home use. This decentralization of care is compelling manufacturers to rethink device design, regulatory strategy, and the end-user experience beyond the traditional clinical environment.
Smart disposables with embedded sensors and RFID tags allow for automated tracking of usage and treatment parameters. Home dialysis providers are adopting this technology to improve patient safety and inventory management. This connectivity is virtualizing the clinical oversight process, enabling remote monitoring of adherence and reducing the necessity of frequent in-person appointments.
The European Union's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance. This forces manufacturers to generate more extensive data to prove the safety and performance of disposables. High-risk devices like dialyzers sold in Germany and France face the most intense scrutiny, compelling investment in new clinical trials for re-certification.
Provider networks are increasingly favoring bundled purchasing agreements that combine capital equipment with a guaranteed supply of proprietary disposables. This model displaces standalone procurement of individual components like bloodlines or dialyzers. The shift is most advanced in consolidated healthcare systems, notably in the United States and parts of Western Europe.
Dialysis Disposable Devices Market Segmentation
The segmentation analysis provides granular insights into the diverse components and therapeutic environments driving the dialysis disposable devices market. Understanding these distinct segments illuminates varying demand patterns, technological preferences, and operational shifts across the renal care continuum. This detailed breakdown highlights areas of established market dominance and emerging growth.
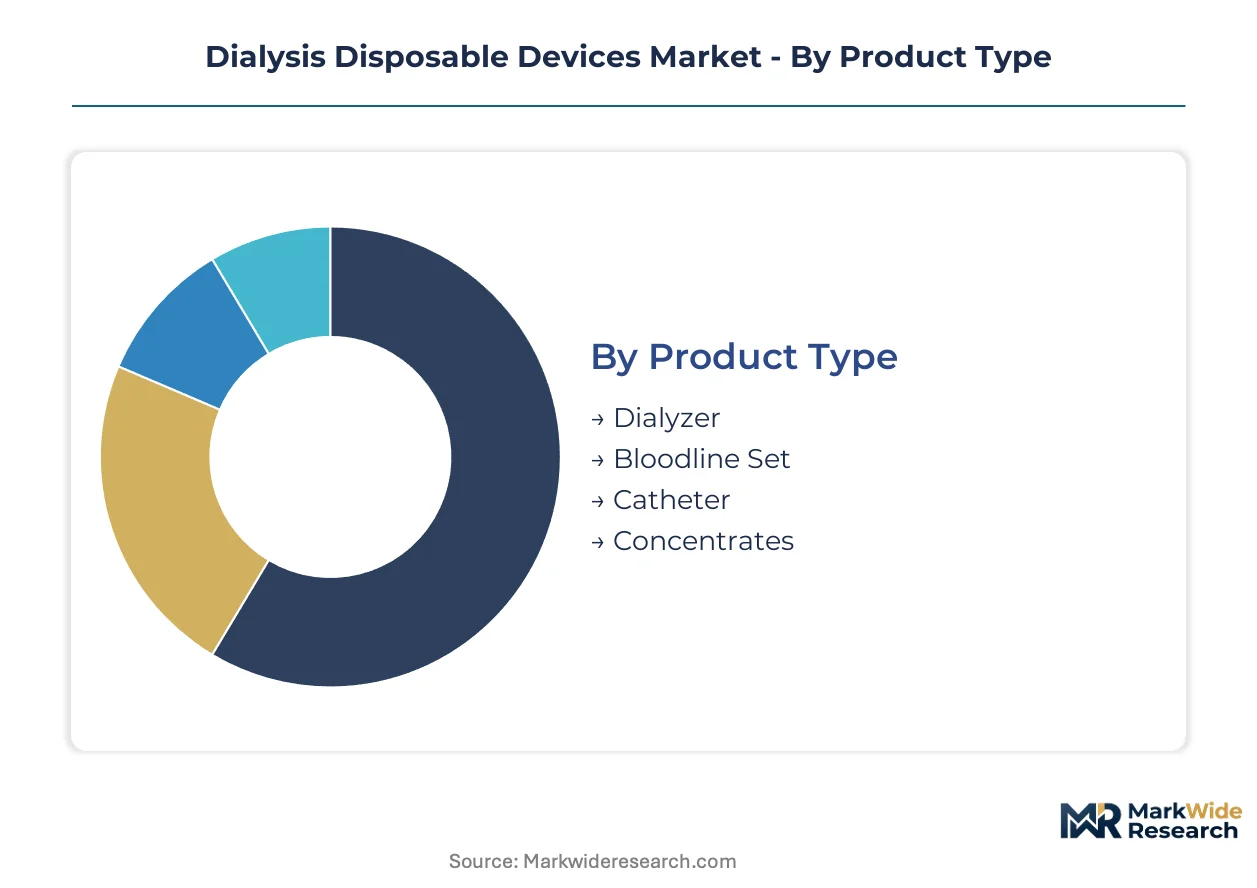
Product Type:
The product type segmentation delineates the essential components required for extracorporeal blood purification, reflecting a broad use-case spectrum from filtration to blood circuit management.
- Dialyzer:These devices are central to renal replacement therapy, containing thousands of polysulfone hollow fibers that remove toxins from the blood. Demand concentrates in developed nations like Germany and Japan due to high chronic kidney disease rates.
- Bloodline Set:These disposable circuits connect the patient to the dialyzer, facilitating blood flow and preventing contamination. Biocompatible bloodline sets are gaining preference for enhancing patient safety and reducing adverse reactions.
- Catheter:Catheters provide vascular access for dialysis, ranging from temporary central venous catheters to permanent tunneled catheters.
- Concentrates:Dialysis concentrates are specialized solutions used to prepare the dialysate, adjusting electrolyte and mineral levels for effective treatment.
Established volume favors Dialyzers; emerging adoption favors advanced Biocompatible Bloodline Sets.
Application:
The application segment illustrates how disposable devices are utilized across different renal replacement therapy modalities, categorized by patient volume and therapeutic approach.
- Hemodialysis:This is the principal application, involving the use of an external machine to filter blood, primarily conducted in dialysis centers. Demand for associated disposables is robust due to the large existing patient base requiring regular treatment.
- Home Dialysis:This application segment is expanding most quickly, driven by favorable reimbursement policies and a structural shift towards home-based care models. Specialized disposables for home use require different packaging and logistics.
- Peritoneal Dialysis:Peritoneal dialysis uses the patient's abdominal lining to filter blood, typically performed at home, with Baxter International Inc. specializing in solutions.
- Continuous Renal Replacement Therapy:CRRT is a slow, continuous form of dialysis used for critically ill patients in intensive care units.
Traditional clinical settings drive Hemodialysis device consumption, while Home Dialysis platforms are experiencing the steepest expansion trajectory.
End User:
This segmentation reflects the diverse institutional and individual customer types procuring dialysis disposable devices, each with distinct procurement processes and logistical requirements.
- Dialysis Centers:These specialized facilities represent the largest end-user group, providing in-center hemodialysis treatments. Fresenius Medical Care leverages its network to promote proprietary disposables within these centers.
- Home Care Providers:This segment includes organizations and individuals supporting patients undergoing dialysis in their own homes. The shift towards home-based care models is increasing demand for tailored product designs and supply chain solutions.
- Ambulatory Surgical Centers:ASCs may perform minor procedures related to dialysis access, driving demand for specific disposable surgical kits.
- Nephrology Clinics:These clinics primarily focus on diagnosing and managing kidney disease, often referring patients for dialysis and requiring diagnostic disposables.
Large-scale procurement by Dialysis Centers sustains market volume, whereas Home Care Providers represent a significant growth area for decentralized product delivery.
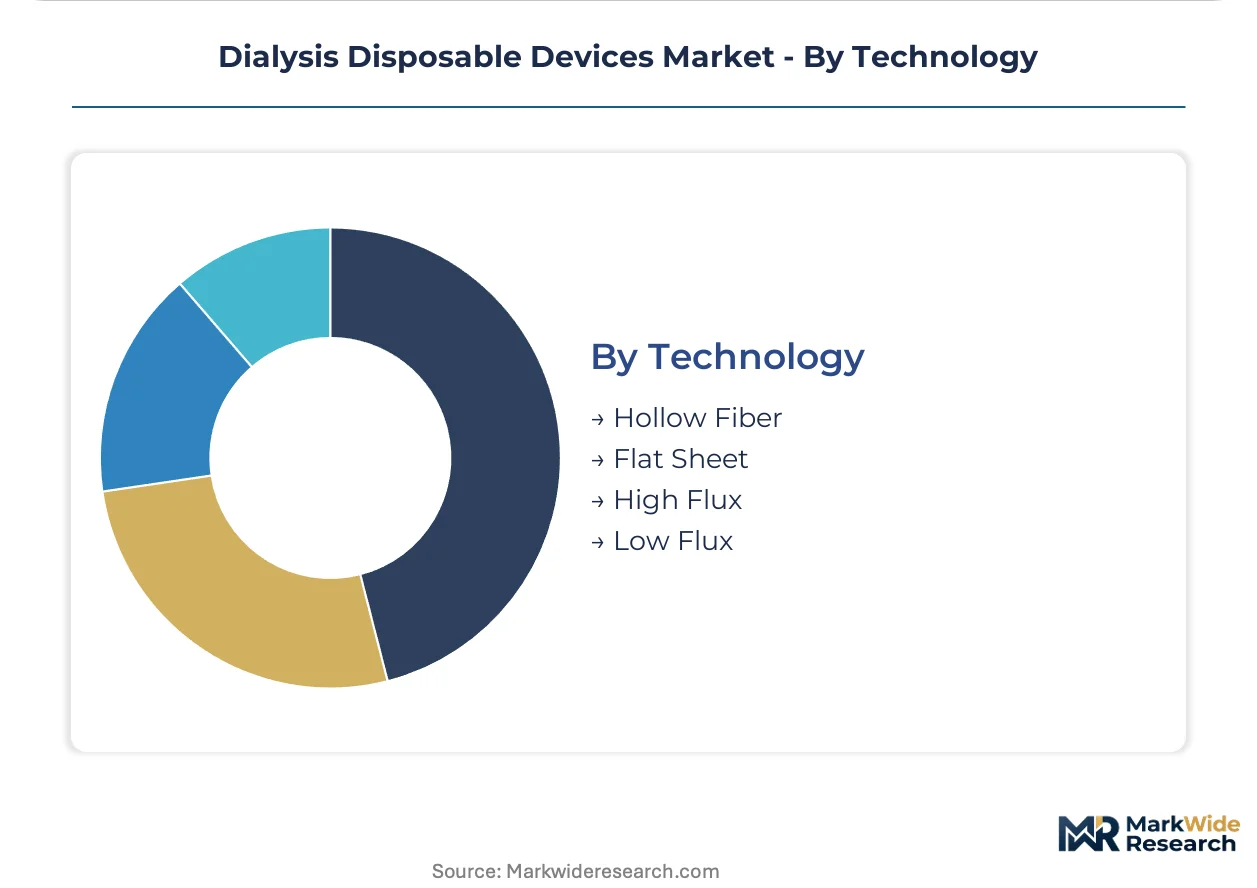
Technology:
The technology segment differentiates disposable devices based on their underlying design and performance characteristics, influencing product efficacy and manufacturer profit margins.
- High Flux:High-flux dialyzers feature larger pore sizes in their membranes, allowing for more efficient removal of larger molecular weight toxins. Revenue from these products is tilting the profit pool away from conventional offerings.
- Hollow Fiber:This technology forms the core of most dialyzers, utilizing thousands of tiny, semi-permeable hollow fibers for blood filtration. Advanced biocompatible polymers enhance performance and patient safety.
- Flat Sheet:Flat sheet dialyzers use layers of membrane sheets, offering an alternative design though less common than hollow fiber.
- Low Flux:Low-flux dialyzers have smaller membrane pores, primarily removing smaller molecules. These are conventional products now experiencing reduced profit pool contribution.
High Flux technologies are capturing greater value, while Low Flux products remain a foundational but lower-margin segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for dialysis disposables varies significantly; buyers in established markets prioritize advanced features and patient safety, while emerging economies often focus on cost-effectiveness and accessibility. This dichotomy influences product development and supply chain strategies across different regions. Regulatory frameworks also play a critical role in shaping market dynamics and product availability.
United States
The United States experiences robust demand for home dialysis disposables, driven by favorable reimbursement policies and a growing preference for decentralized care models. The U.S. FDA's stringent approval processes influence product innovation and market entry for new devices. Major medical device clusters in California and Massachusetts foster research and development for advanced disposable technologies.
Germany
Germany's aging population and high chronic kidney disease rates sustain consistent demand for dialyzers and biocompatible bloodline sets. Compliance with the EU's Medical Device Regulation (MDR) is paramount for market access and product certification. The Rhine-Main region, particularly around Frankfurt, hosts significant medical technology manufacturing and research facilities.
Japan
High prevalence of end-stage renal disease among an elderly demographic ensures consistent demand for renal replacement therapy consumables. The Pharmaceuticals and Medical Devices Agency (PMDA) enforces stringent approval and post-market surveillance standards. Tokyo and Osaka remain key hubs for medical device production and distribution networks.
China
Expanding healthcare infrastructure and a rising middle class are increasing access to dialysis treatment across China. The National Medical Products Administration (NMPA) regulates product approvals and quality control for imported and domestically produced devices. Manufacturing centers in the Yangtze River Delta and Pearl River Delta are expanding production capacity for disposables.
India
The underserved patient population and rising chronic kidney disease incidence create substantial volume growth opportunities for basic and mid-range dialysis disposables. The Central Drugs Standard Control Organization (CDSCO) oversees medical device regulations and approval pathways. Major medical device distribution networks often originate from cities like Mumbai and Chennai.
Dialysis Disposable Devices Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure for dialysis disposable devices. Large multinational corporations and specialized manufacturers represent the primary strategic archetypes. These players engage in strategic partnerships to expand their product portfolios and pursue geographic expansion into underpenetrated markets.
Specialists in comprehensive renal care solutions, such as Fresenius Medical Care, leverage extensive clinical networks to promote proprietary disposables. Baxter International Inc. occupies a distinct position, focusing on peritoneal and home dialysis solutions globally. Japanese manufacturer Nipro Corporation anchors the market with its large-scale manufacturing capabilities and broad product portfolio across various disposable types.
| Leading Market Players |
|---|
| Nipro Corporation |
| JMS Co. Ltd. |
| Baxter International Inc. |
| Toray Medical Co. Ltd. |
| Asahi Kasei Medical Co. Ltd. |
| B. Braun Melsungen AG |
| Nikkiso Co. Ltd. |
| Becton Dickinson and Co. |
| Fresenius Medical Care |
| Others |
Cost & Logistics Intelligence
Polysulfone hollow fiber manufacturing capacity utilization significantly influences both supplier behavior and pricing posture within the dialysis disposable devices market. This utilization level directly impacts production costs and the ability of manufacturers to meet fluctuating global demand.
Pricing Analysis
Consumables and recurring supplies represent the primary revenue tier driving lifetime value in this market. The dominant pricing model is a hybrid of per-unit transactional sales and contract-based long-term offtake agreements with large dialysis centers. Price differentiation stems from the quality grade of biocompatible polymers and the certification level, such as stringent EU MDR compliance. Pricing pressure originates from bundled purchasing agreements favored by consolidated healthcare systems. Home care providers exhibit higher price sensitivity compared to large-volume dialysis centers.
Supply Chain Analysis
Regulatory restrictions on medical-grade polymer exports can limit material flows for dialysis disposables. Geographic supply concentrates in Germany, Japan, and China for key components and finished devices. The market draws from raw material dependencies including polysulfone, polyethersulfone, and specialized medical-grade plastics. A structural risk involves single-source vulnerability for advanced hollow fiber membranes. Distribution runs through direct sales channels to major dialysis centers and specialized logistics networks for home care providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dialysis Disposable Devices Market presents a service-attach opportunity, with home dialysis disposables representing a recurring-revenue layer expanding faster than traditional capital equipment. This structural shift creates distinct strategic pathways for market participants.
For Market Incumbents:
Harden existing clinical network relationships by offering comprehensive bundled solutions that integrate capital equipment with proprietary disposables. Invest in advanced biocompatible materials R&D to maintain a performance edge and meet stringent regulatory requirements like EU MDR. Defend market share against emerging home care solutions by expanding specialized logistics for decentralized delivery. Consolidate production capacity in key manufacturing hubs to optimize cost structures.
For New Entrants and Emerging Players:
Build out specialized product portfolios targeting the rapidly expanding home dialysis application segment. Focus on eco-friendly materials for device components and packaging to differentiate offerings in environmentally conscious markets. Target underpenetrated geographic markets across Latin America and Southeast Asia, where CKD incidence is rising. Develop user-friendly designs that simplify patient training and improve adherence for home-based therapies.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upward across home dialysis disposables and smart device integration, signaling increased investment requirements. The long-term viability of this market remains strong, driven by aging demographics and chronic kidney disease prevalence. Identify acquisition targets specializing in miniaturized disposables for wearable artificial kidney systems. Monitor reimbursement policy changes for continuous therapies as a key inflection indicator for market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Home Dialysis Logistics | Ensures timely delivery of sterile disposables to individual patients. |
| Invest in Biocompatible Polymer R&D | Enhances dialyzer performance and patient safety for advanced therapies. |
| Pursue NMPA/CDSCO Certifications | Unlocks volume growth in China and India's expanding healthcare markets. |
| Develop Smart Disposable Integration | Improves remote monitoring and inventory management for home care. |
| Form Bundled Purchasing Alliances | Secures long-term supply contracts with major dialysis center networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase. Interviews included nephrologists, hospital procurement managers, home care coordinators, and medical device engineers. Secondary validation leveraged U.S. FDA filings, EU Medical Device Regulation guidance documents, and NMPA product registers. This approach combined bottom-up data from product sales with top-down market sizing for comprehensive analysis.
The analytical framework calibrates market projections over the forecast period by segmenting across product type, application, end user, and technology. Compound annual growth rates were derived from historical trends and projected demand drivers like chronic kidney disease prevalence rates. Industry-specific forecast inputs included home dialysis adoption forecasts and material science advancements in polymer technology.
Practitioners should monitor reimbursement policy changes and major technological breakthroughs in renal replacement therapy for early signals of market shifts. Forecasts reflect assumptions regarding regulatory stability and supply chain consistency. Material shifts in home care reimbursement schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Bathroom and Toilet Assist Devices Market
Medical Devices
Spinal Traction Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Embolization Plugs Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Global Photobiostimulation Market