
 Global Fill Finish Manufacturing Market | 2026-2036
Global Fill Finish Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fill Finish Manufacturing Market Foresight
Asset-light contract manufacturing partnerships are tilting competitive dynamics toward firms that can scale without heavy capital deployment. Syntegon Technology GmbH leverages its integrated isolator and barrier system portfolio to anchor high-containment aseptic lines for cytotoxic biologics. Catalent Inc sustains global network density through multi-site redundancy across North American and European fill-finish campuses. Stevanato Group SpA differentiates via vertical integration from glass primary packaging through to final assembly and inspection equipment.
Fill finish manufacturing encompasses the terminal sterile processing, container closure, and quality verification stages that transform bulk drug substance into finalized pharmaceutical dosage forms ready for distribution. The process demands ISO 5 cleanroom environments, validated depyrogenation cycles, and container integrity testing to ensure product sterility and stability across shelf life. Syringes and vials dominate product type volumes, though cartridges are gaining structural share as self-injection platforms expand in biologics administration. Aseptic filling technology leads technology category value pools, while blow-fill-seal formats compete in ophthalmic and respiratory liquid segments where polymer barrier properties offset glass fragility.
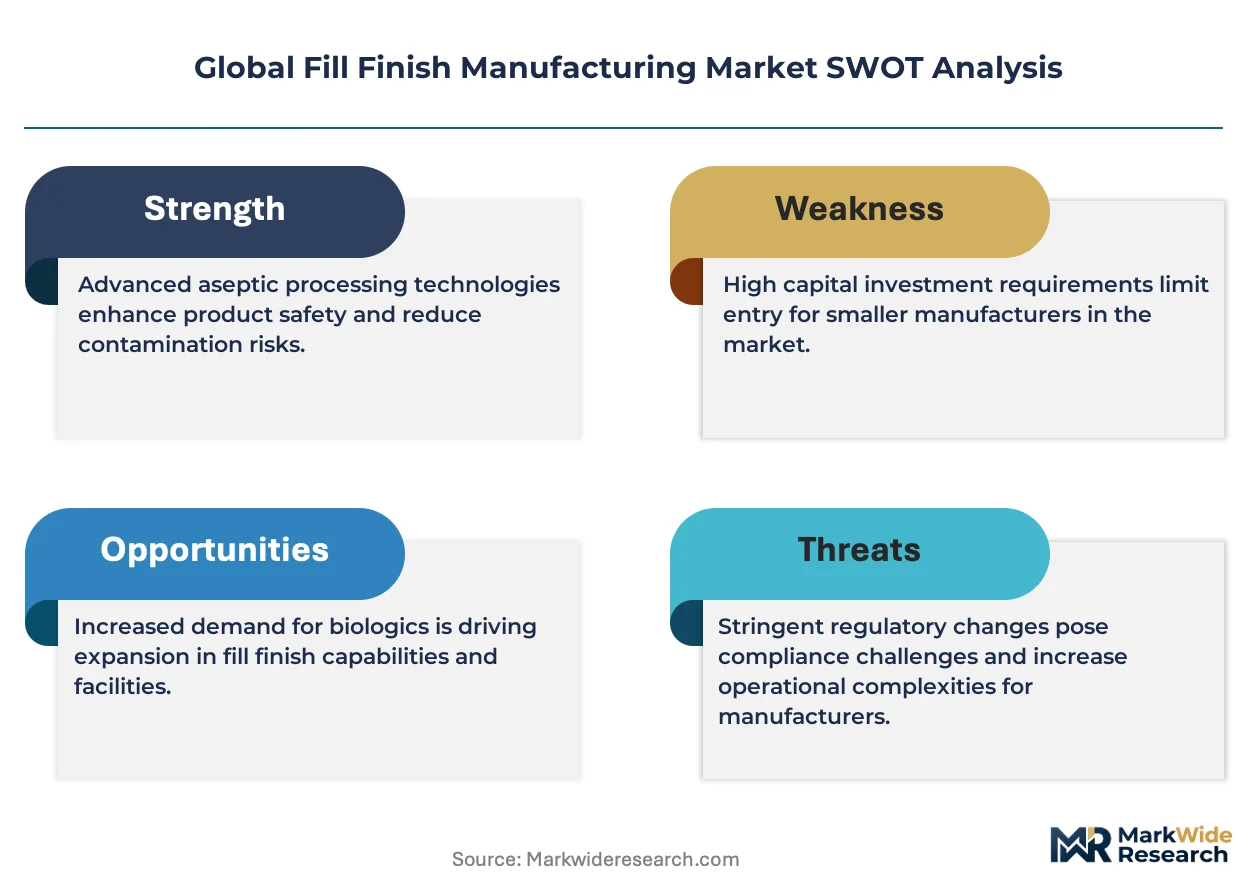
FDA sterility guidance, EMA Annex 1 revisions, and ISO 14644 cleanroom classification standards collectively elevate capital barriers and validation rigor for new market entrants. The EU AI Act and MDR traceability requirements are extending data integrity mandates from fill-finish execution systems through to serialized supply chain handoffs. Stakeholders must monitor how regulatory convergence on single-use technologies versus stainless steel reuse protocols reshapes equipment procurement cycles and facility retrofit priorities.
Market Dynamics
Automated isolator systems and single-use aseptic technologies are compressing batch cycle times while FDA and EMA sterility guidance tightens validation protocols. This dual pressure is forcing capital redeployment toward flexible manufacturing architectures that can pivot between biologics modalities without full facility requalification.
Growth Catalysts
- EMA Annex 1 Revisions:The updated sterile manufacturing guidance mandates enhanced barrier isolation and continuous monitoring systems, accelerating equipment replacement cycles across European fill-finish campuses.
- Monoclonal Antibody Pipeline Expansion:Oncology and immunology biologics in late-stage development require high-containment aseptic processing capacity that existing stainless steel infrastructure cannot safely accommodate.
- German Machinery Cluster Density:Concentrated specialized equipment manufacturing around Stuttgart and Ravensburg creates supplier proximity advantages for European pharmaceutical producers seeking rapid line commissioning.
Market Restraints
- High-Purity Stainless Steel Supply Concentration:Premium-grade 316L and 904L alloys for filling pumps and vessels source primarily from Austrian and Swedish specialty mills, creating input cost volatility and extended lead times.
- Cleanroom Construction Cost Escalation:ISO 5 certification requirements for viable and non-viable particle monitoring drive capital intensity per square meter to levels that deter mid-scale facility investments.
- Blow-Fill-Seal Polymer Substitution:Advanced polymer barrier technologies for ophthalmic liquids compete directly with glass vial formats in segments where break resistance outweighs oxygen ingress concerns.
Strategic Opportunities
- India CDMO Capacity Gap:Domestic biologics manufacturing expansion under PLI scheme incentives outpaces local fill-finish infrastructure, creating demand for technology transfer partnerships and turnkey isolator line deployments.
- Cell and Gene Therapy Aseptic Requirements:Personalized medicine autologous processes demand closed-system filling technologies that conventional batch equipment cannot support, opening specialized equipment niches.
- EU MDR Traceability Mandates:Serialized container closure and automated inspection data integration requirements favor suppliers offering combined mechanical and digital compliance platforms.
Industry Challenges
- Aseptic Processing Specialist Shortage:Qualified personnel capable of isolator operation, media fill validation, and environmental monitoring are concentrated among incumbent operators, constraining new facility staffing.
- Legacy System Integration Friction:Brownfield sites running 1990s-era filling lines face prohibitive retrofit costs to achieve current FDA sterility guidance compliance, forcing build-vs-replace decisions.
- Single-Use Supply Chain Reconfiguration:Dependence on proprietary connector and manifold configurations from limited qualified suppliers creates vulnerability when demand surges disrupt polymer resin allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fill Finish Manufacturing Market |
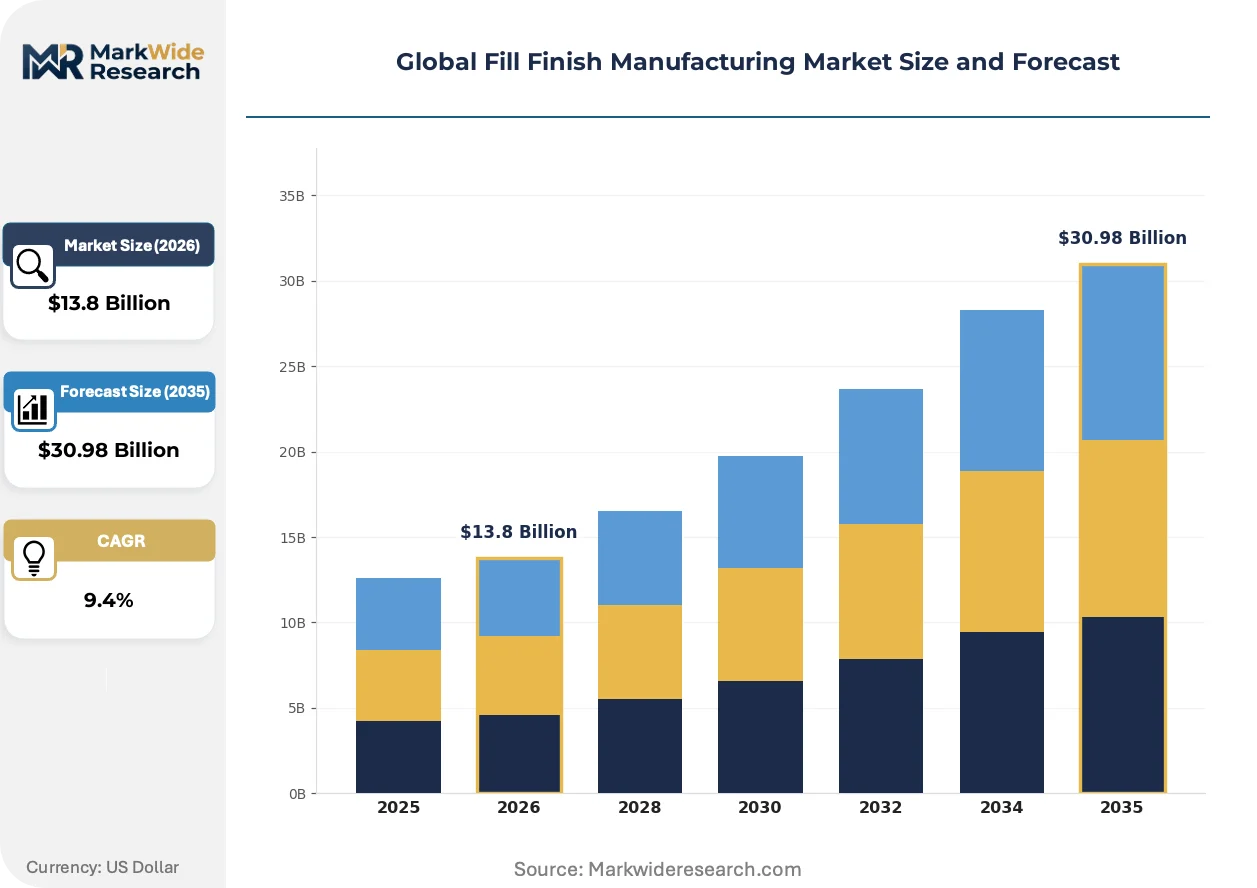
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $30.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Ampoules, Cartridges, Bottles Technology: Lyophilization, Aseptic Filling, Blow-Fill-Seal, Cold Chain, Automated Inspection Application: Vaccines, Biologics, Oncology, Ophthalmology, Dermatology End User: Contract Manufacturing Organizations, Pharmaceutical Companies, Biotechnology Firms, Research Institutes |
| Companies Covered | Syntegon Technology GmbH, IMA Industria Macchine Automatiche SpA, Becton Dickinson and Company, West Pharmaceutical Services Inc, Stevanato Group SpA, Gerresheimer AG, Catalent Inc, Groninger and Co GmbH, Schott AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fill Finish Manufacturing Market Shifts & Advancements
Digital process analytical technology and modular facility design are converging to enable rapid product changeover in multi-modal biologics manufacturing. This transformation is compressing traditional validation timelines while elevating data integrity requirements across production networks.
Isolator-based restricted access barrier systems are hybridizing conventional cleanroom architecture with robotic material handling to eliminate human intervention during critical aseptic operations. Biologics manufacturers in Switzerland and the United States are adopting these configurations for cytotoxic antibody-drug conjugates. The technology is hybridizing competitive positioning between stainless steel and single-use platforms by enabling faster product switches without full line decontamination cycles.
EMA Annex 1 revisions and FDA sterility guidance updates are mandating continuous viable particle monitoring and enhanced barrier qualification protocols. These requirements are extending commissioning timelines and elevating documentation burdens for new facility approvals. Small-molecule sterile injectable producers in Italy and Spain are responding by consolidating production into fewer, higher-capacity lines rather than distributing across multiple mid-scale sites.
Biologics developers are unbundling fill-finish execution from bulk drug substance manufacturing, creating specialized CDMO relationships focused solely on terminal sterile processing. This procurement pattern concentrates volume with operators offering multi-site redundancy and regulatory filing support across FDA, EMA, and PMDA jurisdictions. The shift is most visible among mid-cap biotech firms in Massachusetts and California lacking capital for captive aseptic infrastructure.
Global Fill Finish Manufacturing Market Segmentation
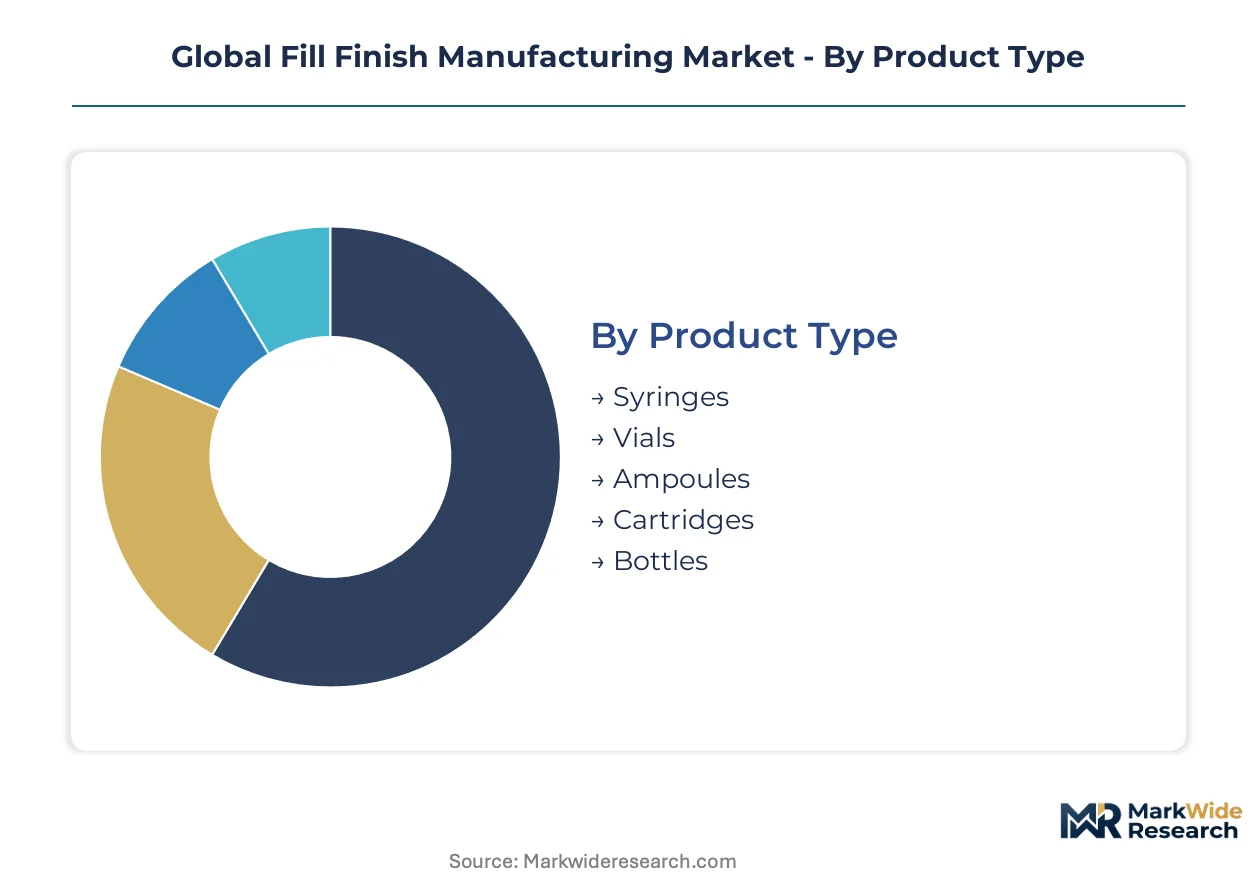
Fill-finish manufacturing segments diverge sharply in equipment lifecycle, validation complexity, and service attachment rates. Understanding these structural differences illuminates where capital deployment concentrates and which technology platforms command premium pricing.
Product Type:
After-sales service intensity varies dramatically across container formats, with precision-machined glass systems requiring sustained technical support versus polymer alternatives demanding less field intervention.
- Syringes:Pre-sterilized, ready-to-use syringe formats integrate staked needles, Luer locks, and safety mechanisms requiring dedicated filling line tooling. Demand clusters in Massachusetts and California biotech corridors where self-injection biologics for multiple sclerosis and rheumatoid arthritis dominate development pipelines. FDA combination product regulations elevate validation documentation burdens for these systems.
- Vials:Borosilicate glass vials in 2R to 50R formats remain the workhorse for monoclonal antibody storage, with Type I glass chemistry specified for pH-sensitive biologics. German pharmaceutical producers around Stuttgart leverage regional supplier proximity for rapid line changeover between vial sizes.
- Ampoules:Single-dose glass ampoules serve cost-sensitive generic injectables in Indian and Brazilian markets where break-open administration suits acute care settings.
- Cartridges:Pen-injector cartridges gain traction in diabetes and obesity drug delivery, with rubber plunger compatibility testing driving formulation-specific procurement.
- Bottles:Large-volume parenteral bottles support irrigation fluids and dialysis solutions, with blow-molded polymer formats displacing glass in hospital pharmacy compounding.
Syringes holds the largest share; momentum sits with cartridges.
Technology:
Capital intensity and margin structure differentiate these platforms, with lyophilization commanding the highest installed base service revenue per unit.
- Lyophilization:Freeze-drying systems stabilize thermolabile biologics through sublimation-based moisture removal, requiring validated shelf temperature mapping and chamber qualification protocols. Swiss and German CDMOs anchor specialized capacity for antibody-drug conjugates where protein integrity depends on precise cycle control.
- Aseptic Filling:Isolator-based filling lines execute sterile filtration to final container closure under ISO 5 unidirectional airflow, with robotic arm integration eliminating human intervention during critical operations. EMA Annex 1 revisions mandate continuous viable particle monitoring, accelerating equipment replacement cycles across European facilities.
- Blow-Fill-Seal:Polymer extrusion and aseptic forming in continuous cycles suits ophthalmic and respiratory liquids where container barrier properties outweigh oxygen ingress sensitivity.
- Cold Chain:Temperature-controlled filling environments preserve mRNA and cell therapy viability, with liquid nitrogen backup systems adding redundancy for ultra-low temperature requirements.
- Automated Inspection:Machine vision systems detect particulate contamination and cosmetic defects at production speeds exceeding manual capability, with AI-enabled classification reducing false rejection rates.
Aseptic filling anchors current revenue pools; automated inspection is climbing the fastest.
Application:
Regulatory pathway complexity and batch size economics shape technology selection across therapeutic categories.
- Vaccines:High-volume fill-finish for pandemic preparedness requires surge-capable multi-dose vial lines, with fill accuracy specifications tighter than standard sterile injectables to ensure dose uniformity.
- Biologics:Monoclonal antibodies and fusion proteins demand single-use aseptic technologies that minimize cross-contamination risk between campaigns. Massachusetts biotech firms unbundle fill-finish execution from bulk manufacturing, concentrating procurement with CDMOs offering FDA-EMA-PMDA regulatory filing support.
- Oncology:Cytotoxic antibody-drug conjugates require high-containment isolator systems with negative pressure gradients and vaporized hydrogen peroxide decontamination cycles.
- Ophthalmology:Sterile eye drops and intraocular injections prioritize endotoxin control and particulate limits below USP <789> thresholds, with blow-fill-seal formats competing against traditional glass.
- Dermatology:Topical sterile preparations for wound care and aesthetic applications favor smaller batch sizes with flexible line configurations.
Biologics commands dominant volume share; oncology shows steepest expansion trajectory.
End User:
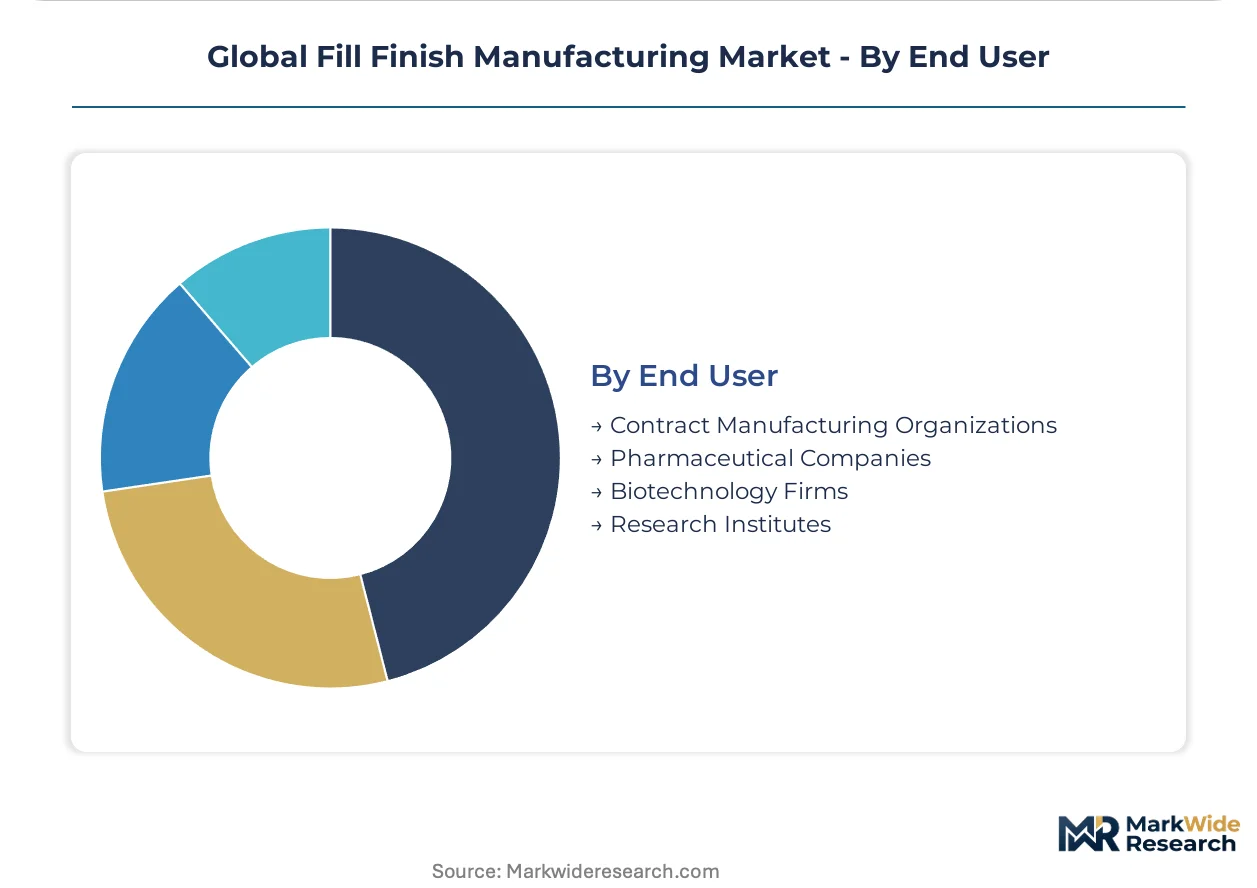
Procurement authority and technical sophistication vary substantially across buyer categories, with CMOs optimizing for asset utilization and pharma companies prioritizing supply security.
- Contract Manufacturing Organizations:CDMOs aggregate demand across multiple sponsor programs, justifying multi-modal flexible lines that pivot between biologics modalities without full facility requalification. Catalent and similar operators sustain network density through North American and European campus redundancy.
- Pharmaceutical Companies:Large pharma retains captive fill-finish capacity for blockbuster products while outsourcing pipeline assets, creating hybrid procurement patterns. German producers leverage Stuttgart-Ravensburg machinery clusters for rapid line commissioning.
- Biotechnology Firms:Mid-cap biotech lacks capital for captive aseptic infrastructure, driving specialized relationships with fill-finish-focused CDMOs. California and Massachusetts developers concentrate here.
- Research Institutes:Academic and government laboratories require small-batch clinical trial material production, with isolator-based modular systems serving early-phase investigational programs.
Contract Manufacturing Organizations represent the largest demand pool; biotechnology firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in fill-finish equipment tilt toward surplus positions in Germany and Switzerland, while the United States and India run structural deficits in specialized isolator systems. Capital deployment patterns concentrate where regulatory stringency and biologics pipeline density intersect.
United States
Massachusetts and California biotech corridors drive monoclonal antibody fill-finish demand. FDA sterility guidance updates mandate enhanced barrier isolation, accelerating equipment replacement cycles. Greater Boston hosts specialized CDMO campuses serving mid-cap developers lacking captive aseptic infrastructure.
Germany
Stuttgart-Ravensburg machinery clusters anchor European pharmaceutical equipment supply. EMA Annex 1 revisions drive continuous monitoring system adoption across Baden-Württemberg production networks. Syntegon Technology and Groninger maintain specialized equipment manufacturing concentration serving regional fill-finish operators.
Switzerland
Swissmedic oversight and antibody-drug conjugate specialization concentrate high-containment aseptic demand. Lyophilization capacity for thermolabile biologics clusters around Basel and Zürich. Domestic CDMOs anchor specialized freeze-drying infrastructure for cytotoxic therapies.
India
PLI scheme incentives accelerate domestic biologics manufacturing expansion. CDSCO regulatory alignment with FDA and EMA standards enables technology transfer partnerships for isolator line deployment. Maharashtra and Gujarat pharmaceutical zones outpace local fill-finish infrastructure capacity.
Japan
PMDA filing requirements sustain premium equipment procurement for biologics export markets. Osaka-Tokyo pharmaceutical production networks prioritize automated inspection integration. Domestic machinery specialists serve regional fill-finish operators with localized validation support.
Global Fill Finish Manufacturing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in glass, polymer, and precision-machined subsystems. Market structure consolidates around multi-site CDMOs and integrated machinery portfolios, with mid-scale equipment fabricators occupying fragmented niches. Three archetypes dominate: full-line integrators with isolator-barrier combinations; verticalized packaging-to-assembly specialists; and modular component suppliers enabling rapid line reconfiguration. Competitive moves concentrate on geographic redundancy investments and regulatory filing support capabilities across FDA-EMA-PMDA jurisdictions.
Among German-based platform integrators, Syntegon Technology GmbH and Groninger and Co GmbH exemplify machinery cluster concentration around Stuttgart-Ravensburg. Stevanato Group SpA represents vertical integration from primary glass through final inspection equipment. These three anchors illustrate how geographic proximity to pharmaceutical production networks and control over critical subsystem supply shapes competitive positioning in high-containment aseptic processing.
| Leading Market Players |
|---|
| Syntegon Technology GmbH |
| IMA Industria Macchine Automatiche SpA |
| Becton Dickinson and Company |
| West Pharmaceutical Services Inc |
| Stevanato Group SpA |
| Gerresheimer AG |
| Catalent Inc |
| Groninger and Co GmbH |
| Schott AG |
| Others |
Supply & Pricing Matrix
Single-source dependency on Austrian and Swedish specialty mills for 316L and 904L stainless steel alloys compresses pricing spreads between premium isolator systems and standard aseptic lines while forcing buyers into long-term offtake commitments to secure allocation. This feedstock bottleneck simultaneously widens tier gaps for equipment with validated material certificates and reshapes procurement toward vertically integrated machinery builders with captive metallurgical partnerships.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers based on FDA-EMA-PMDA certification grade and after-sales service bundling. Price differentiation hinges on isolator barrier class and robotic integration density, with Massachusetts biotech firms showing highest sensitivity to upfront capital outlay and German pharmaceutical producers least sensitive due to regional machinery cluster proximity. Cost compression in mid-tier aseptic filling lines is intensifying because CDMOs aggregate volume across multiple sponsor programs and demand rapid line reconfiguration without full requalification.
Supply Chain Analysis
High-purity stainless steel feedstock draws from Austrian and Swedish specialty mills, while precision-machined filling pumps and isolator barrier systems source primarily from Germany and Switzerland. Borosilicate glass vials and polymer resin for single-use manifolds rest on German and Italian primary packaging suppliers. Single-source vulnerability concentrates in proprietary connector configurations from limited qualified vendors. Distribution runs through machinery builders with integrated validation support rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EMA Annex 1 and FDA sterility guidance updates erect capital barriers that protect incumbent positions through extended commissioning timelines and documentation burdens that new entrants cannot easily replicate.
For Market Incumbents: Entrench position by deepening isolator-barrier integration portfolios and expanding multi-site redundancy across North American and European campuses to capture biologics developers unbundling fill-finish from bulk manufacturing. Prioritize certification investment for EU MDR traceability mandates and AI-enabled automated inspection platforms to outpace stainless steel infrastructure retrofit cycles at legacy competitors. For New Entrants and Emerging Players: Modular isolator line deployments for India's PLI scheme biologics expansion represent the most penetrable entry point, with Maharashtra and Gujarat pharmaceutical zones outpacing local fill-finish infrastructure capacity. Cell and gene therapy closed-system filling technologies for personalized medicine autologous processes offer specialized equipment niches where conventional batch equipment cannot compete. Lead with turnkey technology transfer partnerships rather than standalone hardware sales. For Investors and Strategic Acquirers: Platform integrators with combined mechanical and digital compliance platforms command durable positioning as serialized container closure mandates extend data integrity requirements from execution systems through supply chain handoffs. Watch for inflection when CDMO consolidation accelerates among mid-cap operators unable to fund isolator line replacement cycles under tightened EMA Annex 1 protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Line Replacement Cycle | EMA Annex 1 revisions force equipment upgrades across European fill-finish campuses. |
| Multi-Site Redundancy Expansion | CDMOs aggregate sponsor demand across FDA-EMA-PMDA jurisdictions for supply security. |
| Automated Inspection Integration | AI-enabled machine vision reduces false rejection rates in high-speed aseptic operations. |
| Single-Use Technology Partnership | Proprietary connector configurations lock in polymer resin allocation during demand surges. |
| Lyophilization Capacity Buildout | Swiss and German CDMOs anchor specialized freeze-drying for antibody-drug conjugates. |
Research Methodology
Initial hypotheses were tested against primary input from aseptic processing specialists, CDMO operations directors, pharmaceutical regulatory affairs leads, and machinery procurement managers at biologics developers, then refined through secondary validation against FDA 483 inspection observations, EMA GMP inspection reports, ISO 14644 cleanroom certification databases, and SEC filings from listed CDMO operators. Bottom-up equipment shipment data and top-down pharmaceutical capital expenditure surveys were triangulated to anchor volume estimates.
Demand-supply balance across the analysis window was modeled through segmentation by product type, technology platform, therapeutic application, and end-user procurement archetype, with CAGRs derived from equipment replacement cycle timing under regulatory guidance updates and biologics pipeline progression rates. Forecast inputs incorporated isolator adoption curves, single-use technology penetration trajectories, and regional machinery cluster capacity utilization.
Stress conditions across stainless steel alloy price volatility, cleanroom construction cost escalation, and qualified personnel availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against CDMO capacity expansion announcements and pharmaceutical capital commitment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market