
 Air Fluidized Therapy Beds Market | 2026-2036
Air Fluidized Therapy Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Air Fluidized Therapy Beds Market Outlook
Germany is fragmenting the European supply base for air fluidized therapy beds as domestic manufacturers expand capacity to serve aging demographics across Central Europe. Hill-Rom leverages its vertical integration in critical care surfaces to sustain pricing power in hospital procurement channels. Stryker Corporation anchors its position through R&D intensity in automated pressure redistribution technologies. Arjo AB competes by specializing in bariatric and mobility-integrated configurations for rehabilitation centers.
Air fluidized therapy beds employ ceramic bead or silicone-coated microsphere media suspended by heated forced air to reduce interface pressure below capillary closure thresholds, typically maintaining surface temperatures between 30°C and 35°C to promote perfusion in immobilized patients. Full-body beds dominate installed base value in acute care settings where continuous immersion therapy is required for Stage III and IV pressure injuries, while low-air loss mattresses capture faster growth in home care transitions where cost and caregiver training constraints apply. Electric and hybrid technology segments concentrate margin pools as automated pressure mapping and microclimate control justify premium positioning against manual alternatives.
FDA 510(k) clearance requirements for therapeutic surfaces shape product development timelines and clinical evidence burdens for manufacturers seeking hospital contracts, while Medicare's Hospital-Acquired Condition Reduction Program directly ties reimbursement penalties to pressure ulcer incidence rates that drive procurement of certified surfaces. The EU Medical Device Regulation imposes stricter post-market surveillance and clinical evaluation obligations on beds marketed in Europe, elevating compliance costs for non-EU manufacturers. Stakeholders must monitor how evolving value-based payment models weigh capital equipment costs against readmission penalties when specifying therapeutic surface protocols.
Market Dynamics
The Air Fluidized Therapy Beds Market is experiencing structural compression as Medicare's Hospital-Acquired Condition Reduction Program tightens reimbursement penalties tied to pressure ulcer incidence, forcing acute care facilities to prioritize certified therapeutic surfaces over conventional alternatives.
Growth Catalysts
- Medicare Bundled Payment Models:US hospitals face readmission penalties for pressure injuries, accelerating procurement of FDA-cleared fluidized therapy surfaces in acute care settings.
- Silicone-Coated Microsphere Media:Advanced bead materials reduce interface pressure below capillary closure thresholds, improving perfusion outcomes for Stage III and IV wound patients.
- Central European Aging Demographics:Germany's expanding long-term care infrastructure drives regional capacity investments for bariatric and mobility-integrated bed configurations.
Market Restraints
- Ceramic Bead Supply Concentration:Specialized microsphere manufacturing clusters in Germany and Japan create input vulnerability for non-integrated bed producers.
- FDA 510(k) Clinical Evidence Burdens:Extended clearance timelines for therapeutic surfaces delay hospital contract eligibility and compress R&D returns.
- Low-Air Loss Mattress Substitution:Cost-constrained home care transitions increasingly favor simpler pressure redistribution technologies over full fluidized systems.
Strategic Opportunities
- Home Care Channel Expansion:Post-acute discharge protocols in the United States create demand for portable fluidized therapy units with reduced caregiver training requirements.
- EU Medical Device Regulation Post-Market Surveillance:Stricter clinical evaluation obligations elevate compliance barriers for non-EU manufacturers, opening share for EU-based producers.
- Automated Pressure Mapping Convergence:Integration of real-time sensor arrays with microclimate control systems enables premium positioning against manual alternatives.
Industry Challenges
- Biomedical Equipment Technician Shortages:Specialized maintenance skills for heated forced-air systems limit deployment velocity in rural long-term care facilities.
- Legacy EMR Integration Complexity:Pressure mapping data standards vary across hospital information systems, complicating automated documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Fluidized Therapy Beds Market |
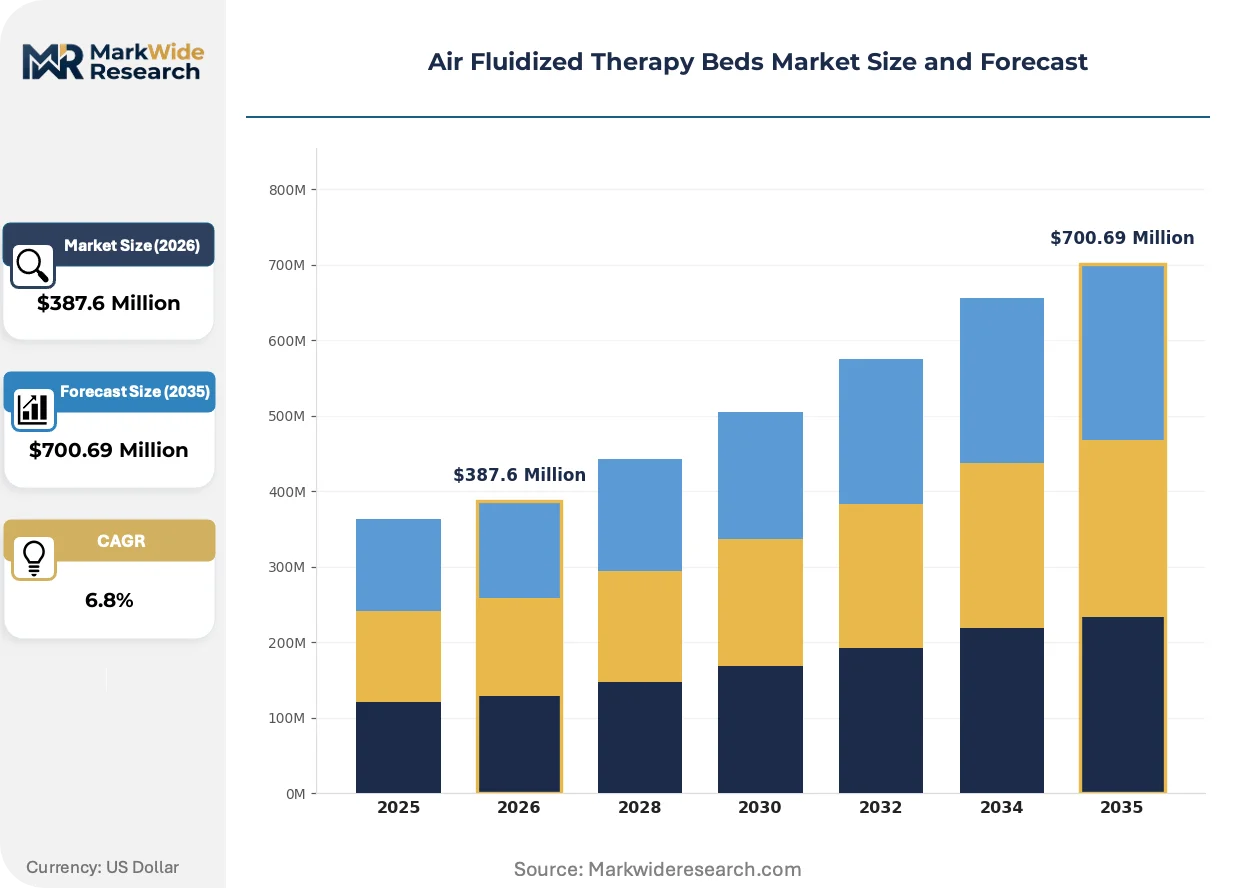
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Body Beds, Trolley Type, Low-Air Loss Mattresses, Custom Beds End User: Hospitals, Rehabilitation Centers, Home Care, Long-term Care Facilities Technology: Electric, Manual, Hybrid, Automated Application: Pressure Ulcer Treatment, Post-Surgery Care, Burn Treatment, Palliative Care |
| Companies Covered | Hill-Rom, Stryker Corporation, Arjo AB, Invacare Corporation, Savion Industries, LINET Group SE, Medline Industries, Drive DeVilbiss Healthcare, Joerns Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Fluidized Therapy Beds Market Strategic Shifts
Automation and intelligent surface technologies are restructuring competitive advantage in therapeutic beds, as sensor-enabled microclimate control separates premium offerings from commodity pressure redistribution products.
Microprocessor-controlled pressure mapping is collapsing the distinction between reactive and preventive wound care protocols. Acute care facilities in the United States are adopting these systems at accelerated replacement cycles. The technology is collapsing capital equipment procurement into integrated service contracts that bundle hardware, monitoring, and outcomes accountability.
The EU Medical Device Regulation imposes stricter post-market surveillance obligations on therapeutic surface manufacturers marketing in Europe. Clinical evaluation documentation requirements now extend across the full product lifecycle rather than pre-market clearance alone. German and French hospital procurement channels are responding by demanding extended warranty terms and real-world performance data from suppliers.
Acute care facilities are consolidating vendor relationships through multi-year therapeutic surface agreements that unbundle equipment from disposable component supply. Group purchasing organizations in the United States are replacing transactional procurement with standardized performance specifications. This concentration is most visible in integrated delivery networks spanning multiple states, where centralized sourcing committees specify certified surfaces across all affiliated facilities.
Air Fluidized Therapy Beds Market Segmentation
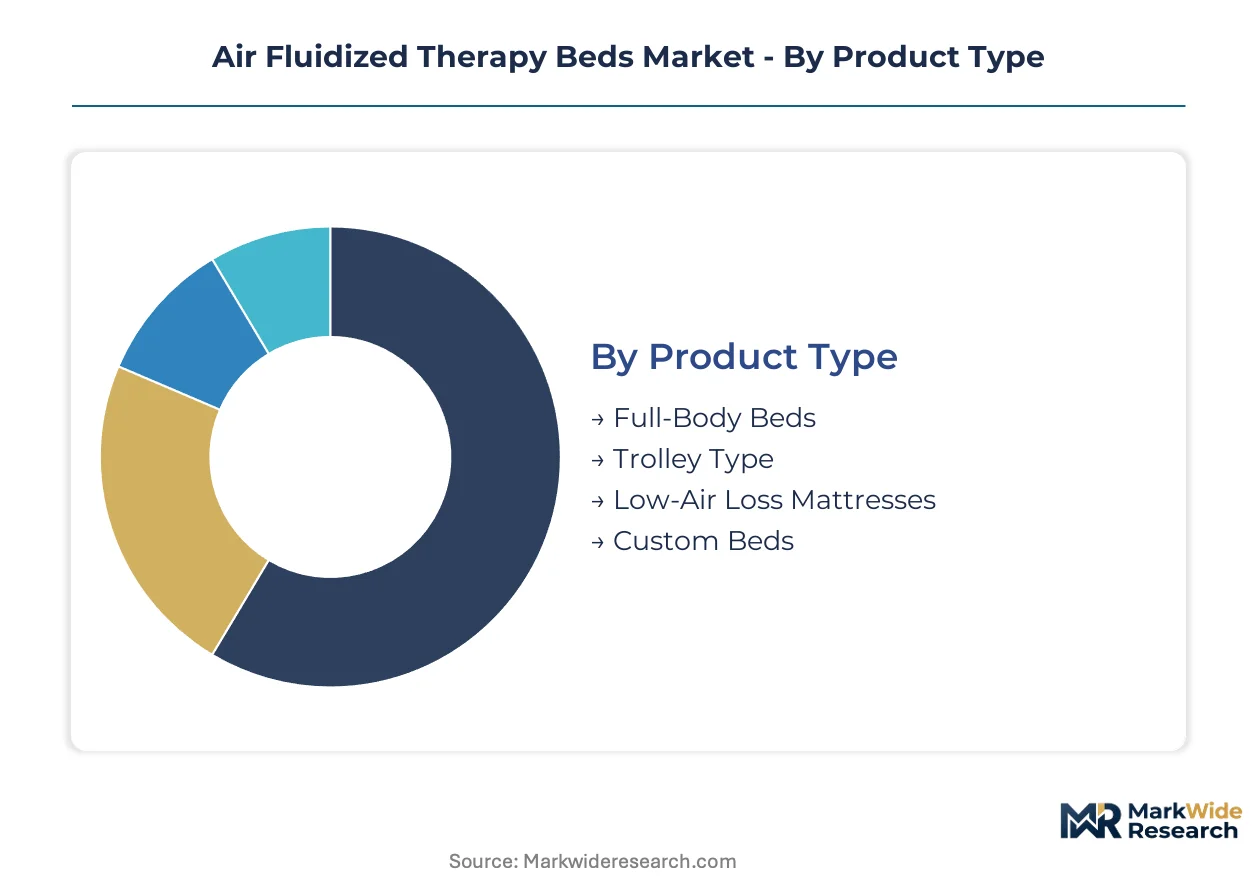
Segmentation in air fluidized therapy beds reflects divergent clinical workflows and capital deployment strategies across acute and post-acute environments. Product configurations range from capital-intensive full-body installations to portable trolley units, while end-user requirements vary sharply between intensive wound care protocols and transitional home settings.
Product Type:
Use-case spectrum spans continuous immersion therapy for immobilized patients through mobile interventions for staged wound management.
- Full-Body Beds:Ceramic bead or silicone-coated microsphere media suspended by heated forced air maintains interface pressure below capillary closure thresholds. Acute care facilities in the United States deploy these for Stage III and IV pressure injuries under Medicare Hospital-Acquired Condition penalty frameworks.
- Low-Air Loss Mattresses:Alternating air cell construction with microclimate management captures faster expansion in post-acute discharge protocols where cost constraints and caregiver training limitations apply. Home care transitions in Germany favor these for bariatric patient mobility.
- Trolley Type:Compact fluidized surface units mounted on transport frames serve operating room and emergency department applications requiring intermittent therapy.
- Custom Beds:Bariatric and mobility-integrated configurations address specialized rehabilitation center requirements for patient egress and ingress.
Established volume favors full-body beds; emerging adoption favors low-air loss mattresses.
End User:
Customer type concentration determines service intensity and procurement channel structure.
- Hospitals:Integrated delivery networks in the United States specify FDA-cleared therapeutic surfaces through centralized sourcing committees spanning multi-state affiliations. Bundled payment models tie readmission penalties to pressure ulcer incidence, accelerating replacement cycles.
- Long-term Care Facilities:Central European aging demographics drive regional capacity investments for bariatric configurations. Germany's expanding LTC infrastructure absorbs increasing unit volumes as post-acute lengths of stay extend.
- Rehabilitation Centers:Mobility-integrated bed specifications dominate procurement for patient functional recovery protocols.
- Home Care:Portable fluidized therapy units with reduced caregiver training requirements gain traction under US post-acute discharge mandates.
Hospital procurement concentrates margin pools; home care channels are climbing the fastest.
Technology:
Automation intensity separates premium positioning from commodity alternatives.
- Electric:Microprocessor-controlled pressure mapping with real-time sensor arrays enables automated pressure redistribution. Acute care facilities adopt these at accelerated replacement cycles under outcomes-accountable service contracts.
- Hybrid:Combined manual and automated control systems balance capital cost with clinical functionality for mid-tier procurement budgets.
- Manual:Basic pneumatic adjustment mechanisms serve cost-constrained long-term care facilities with limited biomedical technician staffing.
- Automated:Fully autonomous pressure mapping with EMR-integrated documentation workflows commands premium positioning in academic medical centers.
Electric systems anchor current installed value; automated configurations show steepest expansion trajectory.
Application:
Clinical indication severity dictates surface specification and reimbursement pathway.
- Pressure Ulcer Treatment:Stage III and IV wound protocols require continuous immersion therapy with perfusion-maintaining temperature control between 30°C and 35°C. Medicare reimbursement policies for specialized surfaces tighten product certification requirements.
- Burn Treatment:Microclimate-controlled surfaces reduce shear forces on grafted tissue in specialized burn centers.
- Post-Surgery Care:Prophylactic pressure redistribution for immobilized surgical patients prevents hospital-acquired conditions.
- Palliative Care:Comfort-focused configurations prioritize pressure relief over active wound healing in end-of-life settings.
Pressure ulcer applications dominate revenue concentration; palliative care represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ceramic bead and silicone-coated microsphere manufacturing clusters in Germany and Japan create input dependencies that reshape procurement geography for therapeutic surface producers worldwide.
United States
Medicare's Hospital-Acquired Condition Reduction Program ties reimbursement penalties directly to pressure ulcer incidence rates, compelling integrated delivery networks to specify FDA-cleared fluidized therapy surfaces. The FDA 510(k) clearance pathway imposes clinical evidence burdens that extend product development timelines for therapeutic surface manufacturers. Hospital procurement committees in the Northeast Corridor and California concentrate multi-state sourcing decisions for certified surfaces.
Germany
Central European aging demographics drive expanding long-term care infrastructure investments for bariatric and mobility-integrated bed configurations. The EU Medical Device Regulation imposes stricter post-market surveillance and clinical evaluation obligations on therapeutic surface manufacturers marketing in Europe. Domestic producers in North Rhine-Westphalia and Bavaria are expanding capacity to serve regional demand across Central Europe.
Japan
PMDA regulatory frameworks for therapeutic medical devices shape product registration requirements for pressure redistribution surfaces entering the Japanese market. METI industrial policy supports advanced materials manufacturing for healthcare applications including specialized microsphere production. Industrial clusters in the Kanto region around Tokyo maintain concentrated expertise in precision ceramic component fabrication.
United Kingdom
NHS England procurement frameworks for pressure ulcer prevention equipment influence specification standards across acute and community care settings. MHRA post-Brexit regulatory autonomy modifies conformity assessment procedures for therapeutic surfaces relative to EU MDR requirements. Academic medical centers in London and the Southeast pilot automated pressure mapping technologies for integrated wound care protocols.
France
ANSM medical device oversight combines with national pressure ulcer prevention guidelines to shape hospital procurement of certified therapeutic surfaces. The country's hospital system modernization programs incorporate advanced wound care equipment into facility renovation budgets. Medical technology industrial activity concentrates in Île-de-France and the Auvergne-Rhône-Alpes region around specialized rehabilitation equipment suppliers.
Air Fluidized Therapy Beds Market Competitive Environment
Integrated critical care equipment conglomerates and specialized rehabilitation surface manufacturers split the market into distinct capability tiers. Three to five multinational conglomerates with diversified medical device portfolios anchor hospital procurement channels through bundled service contracts. Mid-cap specialists concentrate on bariatric configurations and mobility-integrated designs for long-term care segments. Competitive dynamics center on backward integration into microsphere media production and geographic expansion into Central European long-term care markets.
Among US-based medical technology conglomerates, Hill-Rom and Stryker Corporation exemplify the integrated critical care equipment archetype through their positioning in hospital procurement channels. Stryker Corporation represents R&D-intensive investment in automated pressure redistribution technologies. Arjo AB, a Swedish publicly traded company, occupies the specialized rehabilitation equipment tier with its focus on bariatric and mobility-integrated configurations. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning across acute care versus post-acute market segments.
| Leading Market Players |
|---|
| Hill-Rom |
| Stryker Corporation |
| Arjo AB |
| Invacare Corporation |
| Savion Industries |
| LINET Group SE |
| Medline Industries |
| Drive DeVilbiss Healthcare |
| Joerns Healthcare |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in German ceramic bead manufacturing is elevating input costs for non-integrated bed producers while tightening pricing discipline among vertically integrated hospital suppliers. This utilization squeeze propagates through procurement channels as Medicare reimbursement frameworks force facilities toward premium-certified surfaces.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across therapeutic surface procurement, separating FDA-cleared immersion beds from uncertified alternatives. Three-tier pricing stratifies across premium automated systems, standard electric configurations, and manual economy beds. Cost compression in the manual tier is intensifying because long-term care facilities face biomedical technician staffing shortages. Hospital procurement committees show least price sensitivity due to bundled payment penalty exposure, while home care channels exhibit highest sensitivity amid caregiver training constraints.
Supply Chain Analysis
Extended payment terms from German and Japanese microsphere suppliers are squeezing working capital for non-integrated bed manufacturers competing in hospital channels. Ceramic bead and silicone-coated microsphere production clusters in Germany, Japan, and select US industrial corridors anchor upstream supply. Specialized bead media and heated forced-air blower assemblies constitute critical component dependencies. Single-source vulnerability concentrates around precision ceramic fabrication expertise in the Kanto region. Distribution runs through group purchasing organizations and integrated delivery network sourcing committees in acute care, with direct-to-facility logistics for post-acute segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States, where multi-state sourcing committees extract standardized performance terms across affiliated hospitals.
For Market Incumbents: Entrench hospital procurement relationships through multi-year service contracts bundling equipment, disposables, and outcomes accountability. Backward integration into silicone-coated microsphere production hedges against German supply concentration. Prioritize automated pressure mapping R&D to defend margin position against low-air loss mattress substitution in post-acute transitions. For New Entrants and Emerging Players: Pursue portable fluidized therapy configurations for US home care discharge protocols, where regulatory certification barriers are lower and caregiver training constraints create white space. Target bariatric mobility-integrated designs for Germany's expanding long-term care infrastructure. Lead with simplified user interfaces and reduced maintenance requirements as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-contract-anchored incumbents with hospital GPO relationships, suggesting superior cash flow quality versus transactional equipment vendors. Five-to-ten year viability favors automated technology platforms with EMR integration capabilities. Monitor FDA 510(k) clearance velocity and Medicare Hospital-Acquired Condition penalty rate adjustments as inflection signals for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microsphere Media | Captive supply of ceramic beads insulates against German input cost volatility. |
| FDA 510(k) Clearance Investment | Certification unlocks hospital procurement eligibility under Medicare penalty frameworks. |
| Home Care Channel Expansion | Portable configurations address US post-acute discharge mandate demand. |
| Automated Pressure Mapping Development | Sensor-enabled surfaces command premium positioning in academic medical centers. |
| EU MDR Compliance Infrastructure | Post-market surveillance capabilities secure access to German and French hospital procurement. |
Study Parameters
Initial hypotheses were tested against primary input from hospital procurement directors, biomedical equipment technicians, long-term care facility administrators, and GPO contracts managers and refined through secondary validation. FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU Medical Device Regulation guidance documents anchored secondary sourcing. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across acute and post-acute environments.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by product configuration, end-user facility type, automation technology tier, and clinical application severity. CAGRs derived from replacement cycle analysis, demographic expansion trajectories, and reimbursement policy elasticity. Medicare penalty rate adjustments and EU MDR implementation timelines constituted key forecast inputs.
Sensitivities concentrate around FDA clearance timeline extensions, ceramic bead supply disruptions, and Medicare bundled payment model revisions. Forecasts reflect documented assumptions regarding regulatory stability and reimbursement continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Autoclaves Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
ECG Equipment Market