
 Fill-Finish Pharmaceutical Contract Manufacturing Market | 2026-2036
Fill-Finish Pharmaceutical Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Fill-Finish Pharmaceutical Contract Manufacturing Market Intelligence
Premium sterile fill-finish capacity for complex biologics is decoupling from commodity small-molecule packaging on price, qualification timelines, and regulatory burden. Catalent Inc. leverages integrated development-to-commercial platforms across North American and European sites. Vetter Pharma International anchors its position through dedicated prefilled syringe and cartridge expertise for self-administration therapies.
Fill-finish pharmaceutical contract manufacturing encompasses the sterile transfer of bulk drug substance into final primary containers—vials, syringes, ampoules, or cartridges—followed by capping, labeling, and secondary packaging under ISO 5 aseptic conditions, with processes validated to prevent microbial, particulate, and pyrogen contamination. Lyophilization services command premium positioning as freeze-dried formulations extend shelf stability for temperature-sensitive biologics. Biotech firms represent the fastest-growing end-user segment, driven by virtual and mid-cap companies lacking captive manufacturing infrastructure.
FDA enforces current Good Manufacturing Practice through sterile drug product guidance, while EMA's Annex 1 revision mandates enhanced barrier isolation and contamination control strategy documentation for European facilities. The EU AI Act introduces algorithmic quality-system requirements for automated visual inspection systems used in release testing. Stakeholders must monitor regulatory divergence between FDA and EMA on continuous manufacturing acceptance for aseptic processing, as this will reshape capital deployment priorities for new capacity.
Market Dynamics
Specialized aseptic capacity for complex biologics is fragmenting into tiered qualification levels, with FDA and EMA divergence on continuous manufacturing acceptance forcing CDMOs into parallel validation investments rather than unified platforms.
Growth Catalysts
- EMA Annex 1 Revision:The 2022 update mandates isolator-based filling lines and real-time environmental monitoring, accelerating facility upgrade cycles across European contract manufacturers.
- Monoclonal Antibody Pipeline Expansion:Virtual biotech firms without captive infrastructure are outsourcing 100% of sterile manufacturing, concentrating demand at qualified CDMOs.
- Switzerland-Germany Cluster Density:Specialized Basel-Baden-Württemberg corridor facilities capture European biopharma innovators requiring rapid tech transfer.
Market Restraints
- Stainless Steel Equipment Lead Times:Isolator-integrated filling line delivery extends beyond 24 months, constraining capacity expansion velocity for mid-tier CDMOs.
- WFI Generation Energy Costs:Water-for-injection systems consume 40% of facility utilities, with European natural gas price volatility compressing margin structures.
- Single-Use Supply Concentration:Bioprocess bag and connector sourcing depends on three dominant polymer suppliers, creating input vulnerability.
Strategic Opportunities
- India CDSCO Pathway Acceleration:Emerging domestic biologics innovators lack qualified local fill-finish partners, creating first-mover positioning for EU-GMP-certified Indian facilities.
- Cell and Gene Therapy Viral Vector Integration:CDMOs combining bulk drug substance with sterile finishing under one quality system capture integrated program awards.
- EU AI Act Visual Inspection Mandate:Automated defect detection algorithm validation requirements favor technology-forward contract manufacturers with embedded data science capabilities.
Industry Challenges
- Aseptic Processing Technician Scarcity:ISO 5 gowning, media fill participation, and environmental monitoring expertise commands 35% wage premiums, constraining shift expansion.
- Legacy LIMS Integration Friction:Paper-based batch records and standalone equipment software resist ERP connectivity, delaying real-time release initiatives.
- Multi-Product Facility Contamination Control:Campaign changeover validation for cytotoxic and non-cytotoxic sequences extends downtime and occupies QA resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fill-Finish Pharmaceutical Contract Manufacturing Market |
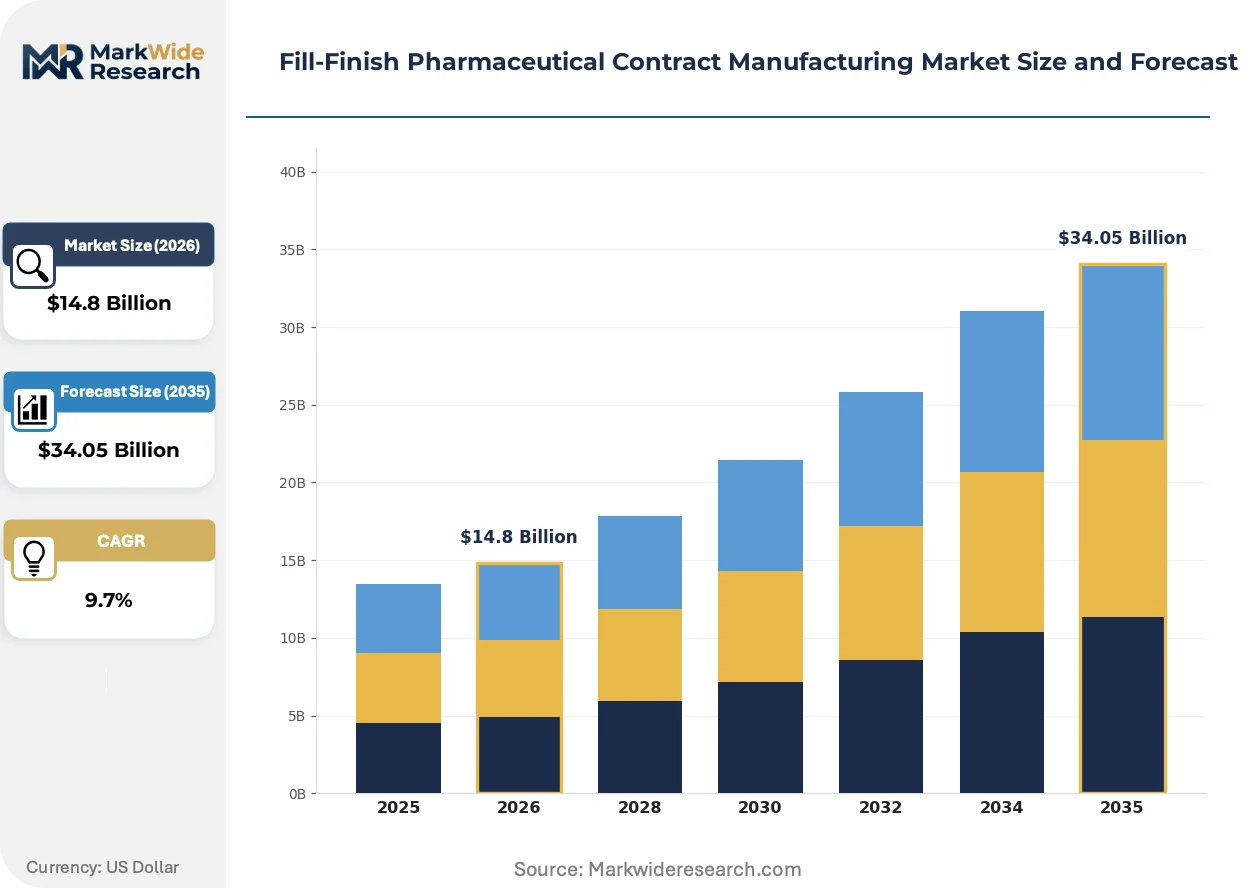
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Liquid Fill, Lyophilization, Packaging, Quality Control Container Type: Syringes, Vials, Ampoules, Cartridges Delivery Mode: Self-Administration, Hospital Use, Clinical Trials, Commercial Distribution End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Others |
| Companies Covered | Baxter BioPharma Solutions, Boehringer Ingelheim BioXcellence, Catalent Inc., Piramal Pharma Solutions, Recipharm AB, Lonza Group, Fresenius Kabi, Grand River Aseptic Manufacturing, Vetter Pharma International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fill-Finish Pharmaceutical Contract Manufacturing Market Strategic Shifts & Innovations
Robotic aseptic processing and isolator-based containment are compressing human intervention points, while regulatory algorithmic quality requirements reshape automated inspection investments across the value chain.
Closed-system robotic filling arms are eliminating glove-port interventions in vial and syringe processing. Mid-cap biotech sponsors specify isolator-integrated robotics in 60% of new Request for Proposals. The technology is integrating small-batch flexibility with commercial-scale throughput, collapsing the traditional gap between clinical and commercial facility designs.
EMA's Annex 1 revision enforces contamination control strategy documentation and barrier technology deployment. European facilities face capital requalification timelines of 18-36 months for legacy open Restricted Access Barrier Systems. High-potency cytotoxic and antibody-drug conjugate programs are migrating to dedicated isolator suites, segmenting the CDMO landscape by containment capability tier.
Biotech procurement teams are consolidating supplier relationships from multi-site fragmented awards to single-source integrated development-to-commercial partnerships. Virtual companies prioritize CDMOs offering regulatory submission support and commercial packaging under one master service agreement. This concentration is most pronounced in Massachusetts and California clusters, where sponsor-CDMO geographic proximity accelerates tech transfer and batch release cycles.
Fill-Finish Pharmaceutical Contract Manufacturing Market Segmentation
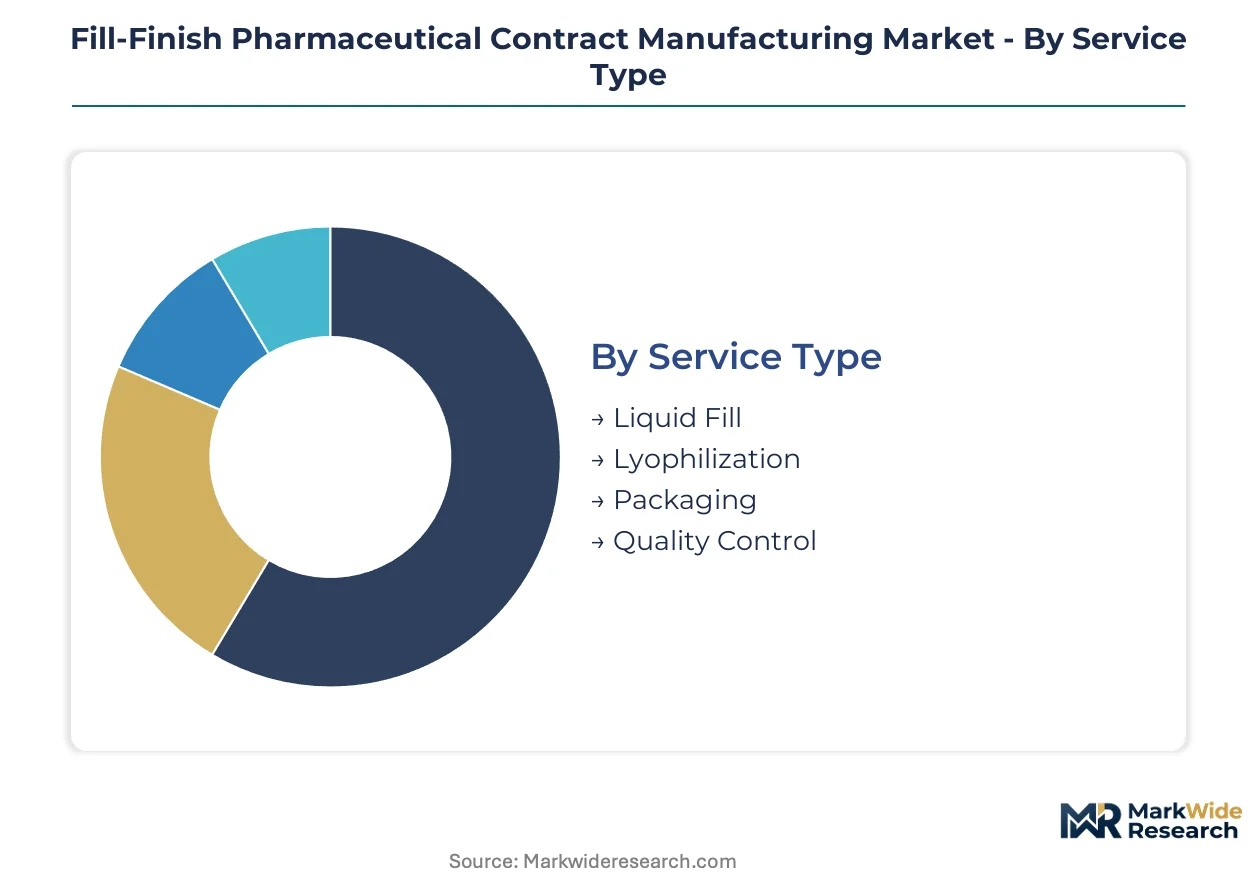
Fill-finish procurement decisions pivot on containment technology compatibility, batch size flexibility, and regulatory pathway alignment. Sponsor firms segment supplier selection across service depth, container format, and end-user infrastructure requirements.
Service Type:
CDMO selection criteria prioritize technical capability depth and integrated quality system coverage over unit cost.
- Liquid Fill:Aseptic transfer of sterile drug product into primary containers under ISO 5 conditions with real-time fill weight verification. Demand concentrates at multi-site CDMOs serving Massachusetts and California biotech clusters where rapid tech transfer cycles compress development timelines.
- Lyophilization:Freeze-drying services for temperature-sensitive biologics requiring validated shelf-life extension. European facilities in Switzerland and Germany capture premium positioning as EMA Annex 1 mandates isolator-integrated lyophilization lines with enhanced contamination control documentation.
- Packaging:Secondary packaging, labeling, and serialization for commercial distribution compliance.
- Quality Control:Release testing, environmental monitoring, and automated visual inspection services.
Volume sits with liquid fill operations; growth tilts toward lyophilization as biologics pipelines expand.
Container Type:
Container selection tracks administration setting, patient population, and compatibility with automated filling platforms.
- Syringes:Prefilled syringes eliminate dose preparation errors in hospital and self-administration settings. Vetter Pharma International anchors European demand through dedicated syringe expertise, while Catalent Inc. scales North American capacity for chronic disease therapies requiring home injection.
- Vials:Glass and polymer vials remain the default for multi-dose formulations and clinical trial supplies. CDMOs with isolator-based vial filling lines command qualification premiums as FDA sterile drug product guidance tightens particulate contamination thresholds.
- Ampoules:Single-dose glass containers for emergency and anesthetic applications.
- Cartridges:Pen-injector compatible formats for diabetes and growth hormone therapies.
Syringe volume dominates commercial awards; cartridge demand climbs fastest alongside self-injection device proliferation.
Delivery Mode:
Delivery setting determines batch size, packaging complexity, and regulatory documentation burden.
- Self-Administration:Prefilled syringes and auto-injectors for chronic disease management in home settings. Demand clusters at CDMOs combining device assembly with sterile filling under single quality systems.
- Hospital Use:Multi-dose vials and infusion bags for acute care administration.
- Clinical Trials:Small-batch sterile manufacturing with adaptive packaging for investigator-sponsored studies. Virtual biotech firms lacking captive infrastructure outsource 100% of clinical fill-finish, concentrating awards at qualified partners with rapid batch release capabilities.
- Commercial Distribution:Full-scale production with serialization and aggregation for market supply.
Commercial distribution carries volume weight; self-administration formats expand most quickly as therapy portfolios shift toward chronic disease management.
End User:
End-user type shapes contract structure, risk allocation, and technical service intensity.
- Pharmaceutical Companies:Large-cap sponsors with established quality systems and multi-product portfolios. These buyers negotiate master service agreements spanning development through commercial phases, prioritizing CDMOs with redundant manufacturing sites.
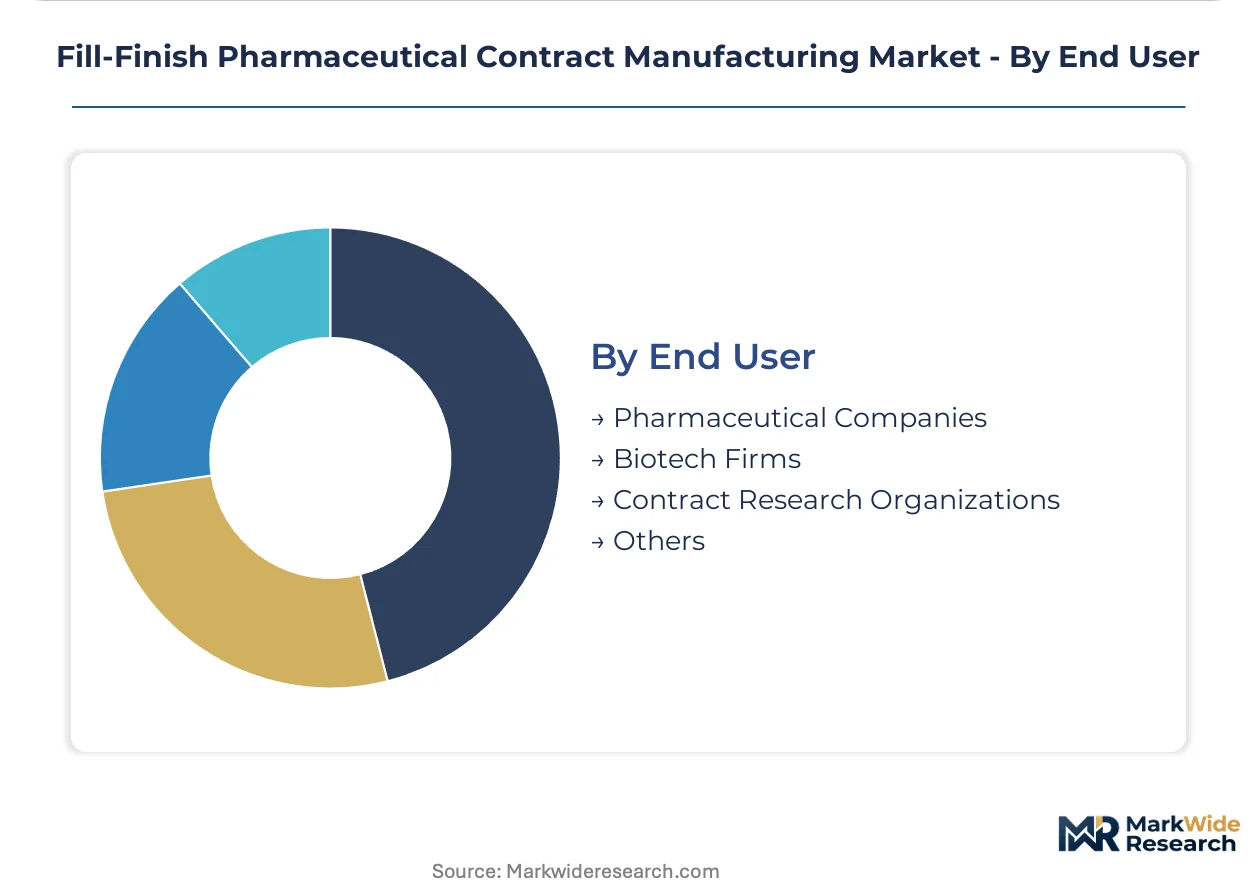
- Biotech Firms:Virtual and mid-cap companies without captive manufacturing infrastructure. This segment outsources 100% of sterile operations, driving fastest expansion at CDMOs offering integrated regulatory submission support and commercial packaging.
- Contract Research Organizations:Clinical service providers extending into manufacturing partnerships.
- Others:Government stockpile programs, academic institutions, and emerging market innovators.
Pharmaceutical companies anchor contract value; biotech firms gain share fastest as monoclonal antibody pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Basel-Baden-Württemberg corridor anchors sterile fill-finish capacity concentration, with Switzerland and southwestern Germany hosting specialized CDMO clusters serving European biopharma innovators. Facility investments concentrate where regulatory alignment, technical workforce density, and sponsor proximity intersect.
United States
Massachusetts and California biotech clusters drive outsourcing demand from virtual companies lacking captive infrastructure. FDA sterile drug product guidance tightens particulate contamination thresholds for aseptic processing. Greater Boston CDMOs capture rapid tech transfer contracts through geographic proximity to sponsor R&D headquarters.
Germany
Baden-Württemberg facilities serve European monoclonal antibody pipelines requiring EMA Annex 1 compliant isolator-based filling lines. The 2022 Annex 1 revision mandates real-time environmental monitoring and contamination control strategy documentation. Stuttgart-Heidelberg corridor CDMOs command qualification premiums for legacy facility upgrades.
Switzerland
Basel-region contract manufacturers anchor European demand for prefilled syringe and cartridge formats in self-administration therapies. Swissmedic alignment with EMA standards enables seamless cross-border regulatory submissions for biologics sponsors. The city-state's pharmaceutical heritage concentrates specialized aseptic technician expertise.
India
Domestic biologics innovators lack qualified local fill-finish partners, creating positioning opportunities for EU-GMP-certified Indian facilities. CDSCO pathway acceleration for biosimilar approvals expands demand for sterile manufacturing capacity. Hyderabad and Mumbai CDMO clusters invest in isolator technology to capture first-mover advantage.
United Kingdom
Post-Brexit regulatory divergence from EMA Annex 1 creates parallel validation requirements for UK facilities serving European sponsors. MHRA maintains sterile manufacturing standards while negotiating mutual recognition agreements. Southeast England CDMOs face capital requalification decisions on barrier technology investments.
Fill-Finish Pharmaceutical Contract Manufacturing Market Key Industry Players
Capital-heavy producers compete with asset-light designers across tiered qualification levels, with facility ownership separating integrated platform operators from technology-licensed service providers. The vendor base concentrates around three strategic archetypes: multi-site integrated CDMOs with development-to-commercial platforms, specialized container-format specialists with dedicated isolator suites, and regional mid-tier facilities competing on speed-to-batch. Dominant competitive moves include isolator-integrated capacity expansion and strategic partnerships combining bulk drug substance with sterile finishing under unified quality systems.
Within the integrated-platform tier, Catalent Inc. and Lonza Group exemplify multi-continental operators with redundant manufacturing sites spanning North American and European regulatory jurisdictions. Vetter Pharma International occupies a specialized position as a family-owned German entity focused on prefilled syringe and cartridge expertise. Piramal Pharma Solutions represents the emerging-market expansion archetype, with Indian-origin CDMOs investing in EU-GMP certification to capture biologics outsourcing from domestic innovators.
| Leading Market Players |
|---|
| Baxter BioPharma Solutions |
| Boehringer Ingelheim BioXcellence |
| Catalent Inc. |
| Piramal Pharma Solutions |
| Recipharm AB |
| Lonza Group |
| Fresenius Kabi |
| Grand River Aseptic Manufacturing |
| Vetter Pharma International |
| Others |
Cost & Logistics Intelligence
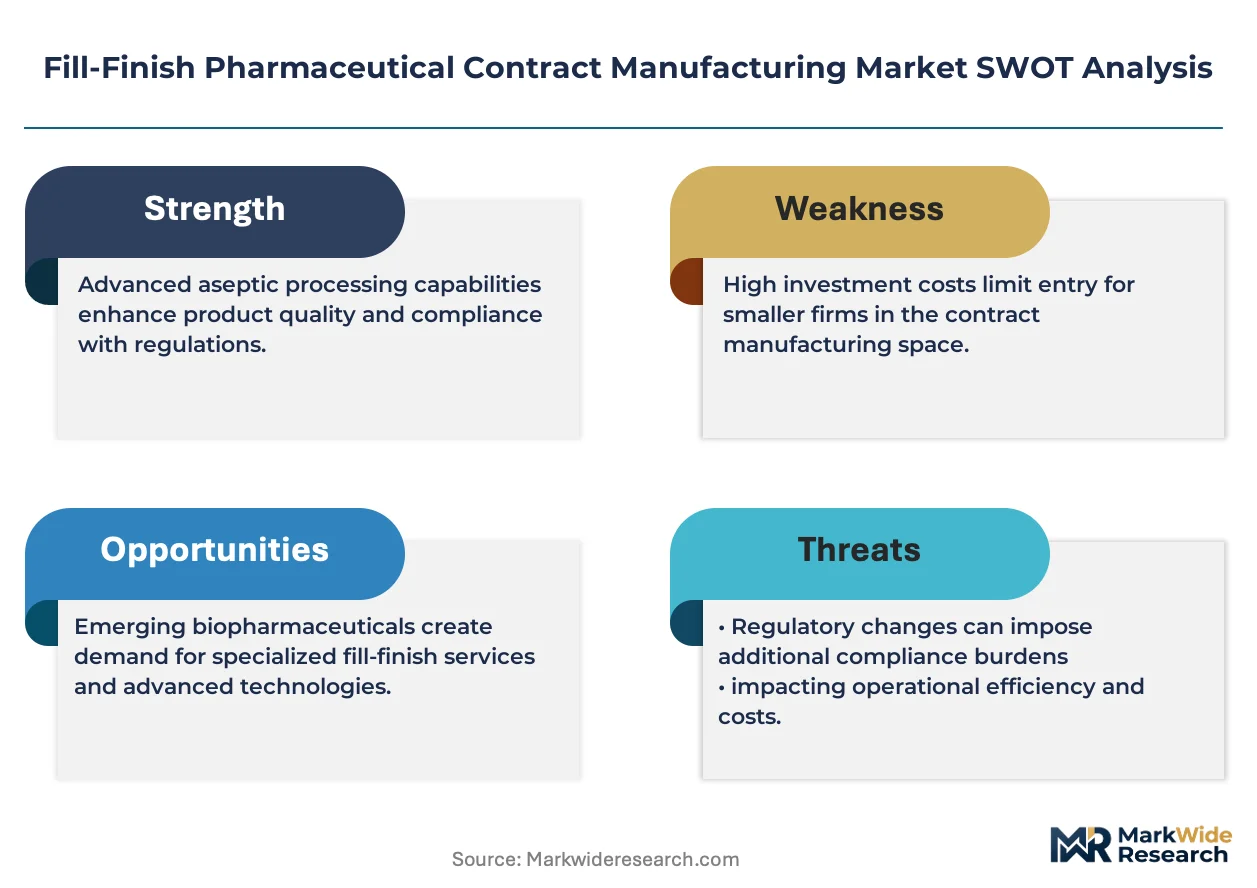
EMA Annex 1 contamination control mandates gate both qualified supply access and premium-tier pricing power, forcing sponsor firms toward EU-GMP-certified CDMOs with isolator-integrated capacity while compressing margins at legacy open-RABS facilities unable to document enhanced barrier validation.
Pricing Analysis
Yield-guaranteed throughput contracts anchor value-based pricing for commercial-scale biologics programs, with isolator-integrated lines commanding 40-60% premiums over open-restricted systems due to EMA Annex 1 compliance documentation and reduced contamination risk. Three-tier pricing structure across premium, standard, and economy levels segments by containment technology grade and regulatory pathway alignment. Cost compression in mid-tier stainless steel capacity is intensifying because European energy price volatility elevates WFI generation expenses. Virtual biotech firms show highest price sensitivity, while large-cap pharmaceutical companies prioritize redundant site qualification over unit economics.
Supply Chain Analysis
Single-use bioprocess assembly supply rests on German, American, and Japanese specialty polymer producers for isolator-compatible film and connector components. Stainless steel filling line fabrication draws from Swiss, German, and Italian precision engineering clusters. Single-source vulnerability concentrates in gamma-irradiated bag supply for aseptic fluid transfer. Distribution runs through qualified cold-chain logistics providers with GDP-certified European hub networks serving sponsor quality systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into bulk drug substance manufacturing is accelerating as CDMOs capture integrated program awards combining upstream cell culture with downstream sterile finishing under unified quality systems.
For Market Incumbents: Extend isolator-integrated capacity across redundant North American and European sites to defend against emerging Indian CDMOs with EU-GMP certification. Deepen backward integration into single-use assembly manufacturing to reduce polymer supply concentration risk. Prioritize automated visual inspection algorithm development before EU AI Act validation requirements harden competitive moats. For New Entrants and Emerging Players: The premium-to-economy pricing gap in clinical-scale isolator services creates positioning space for EU-GMP-certified Indian facilities serving domestic biologics innovators. Target Hyderabad and Mumbai corridor CDMO clusters where CDSCO pathway acceleration expands biosimilar fill-finish demand. Lead with rapid tech transfer capabilities and regulatory submission support bundled under master service agreements. For Investors and Strategic Acquirers: FDA-EMA divergence on continuous manufacturing acceptance is the leading indicator that parallel validation investments will reshape capital deployment priorities for new capacity. Focus acquisition screening on mid-tier CDMOs with isolator technology deployed but underutilized, positioned for sponsor consolidation toward integrated partners. Watch EMA Annex 1 requalification completion rates as inflection signal for European facility pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Integrated Capacity Expansion | EMA Annex 1 compliance documentation commands qualification premiums from biologics sponsors. |
| Backward Integration into Single-Use Assembly | Captive polymer component supply reduces input vulnerability from three-dominant-supplier concentration. |
| Automated Visual Inspection Algorithm Development | EU AI Act quality-system requirements favor CDMOs with embedded data science capabilities. |
| Cell and Gene Therapy Viral Vector Integration | Unified bulk substance and sterile finishing quality systems capture integrated program awards. |
| EU-GMP Certification in Indian Facilities | CDSCO pathway acceleration for biosimilars expands addressable market for qualified domestic CDMOs. |
Research Approach
FDA sterile drug product guidance documents, EMA Annex 1 revision filings, and ClinicalTrials.gov protocol registrations formed the secondary backbone, cross-referenced with primary interviews involving drug development executives, regulatory affairs leads, aseptic processing technicians, and CDMO procurement managers. Bottom-up facility capacity assessments and top-down sponsor outsourcing spend estimates were triangulated against customs data for isolator-integrated filling line imports.
Historical trendline analysis of sterile manufacturing capacity deployment and sponsor outsourcing ratios informed projection modeling across service type, container format, delivery mode, and end-user segmentation dimensions. CAGRs were derived from slope-adjusted growth trajectory fitting. Forecast inputs incorporated monoclonal antibody pipeline maturation rates and EMA Annex 1 requalification timelines for legacy European facilities.
Inputs from EMA inspection databases and CDSCO approval registries were available through the study window; gaps in private CDMO utilization rates introduce uncertainty bands around capacity absorption forecasts. Regulatory divergence between FDA and EMA on continuous manufacturing acceptance, Indian CDSCO pathway acceleration velocity, and European natural gas price stabilization warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market