
 Pharmaceutical Incubators Market | 2026-2036
Pharmaceutical Incubators Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Incubators Market Analytics
Bioprocess engineering talent scarcity is collapsing expansion timelines for incubator operators across major biotech hubs. Thermo Fisher Scientific leverages its integrated life sciences platform to anchor incubator partnerships with bundled equipment and consumables supply. Eppendorf competes through specialized bioreactor and cell culture workflow expertise embedded in incubator lab design. Panasonic Healthcare sustains geographic dominance in Asia-Pacific incubator installations through localized service networks and regulatory compliance support.
Pharmaceutical incubators constitute structured innovation ecosystems providing wet laboratory infrastructure, regulatory guidance, and venture access to early-stage drug development ventures, typically maintaining temperature-controlled cell culture suites with specifications ranging from standard 37°C mammalian incubation to specialized hypoxic conditions for stem cell propagation. The technology dimension shows biologics and gene therapy segments commanding premium infrastructure investment due to vector manufacturing complexity and biosafety level requirements, while small molecule incubation retains volume leadership through lower capital barriers. The business model segmentation reveals equity-based structures capturing upside from successful portfolio companies, whereas fee-for-service arrangements dominate in university-affiliated incubators seeking sustainable operating revenue without dilution risk.
FDA cGMP guidelines and EMA's ATMP framework shape incubator capital planning by mandating segregated production pathways for advanced therapy medicinal products, directly inflating buildout costs for gene therapy-dedicated facilities. ISO 14644 cleanroom classifications and USP <797> sterile compounding standards further constrain facility design, filtering out undercapitalized operators. BIS certification requirements in India and NMPA registration pathways in China create divergent compliance burdens for incubator networks pursuing multi-continental portfolio support. Stakeholders must weigh regulatory jurisdiction arbitrage against talent cluster concentration when selecting incubator locations for portfolio companies targeting accelerated IND timelines.
Market Dynamics
Gene therapy manufacturing complexity is compressing incubator facility economics, forcing operators to choose between specialized vector production capabilities and diversified small-molecule portfolios. The FDA's accelerated approval pathways for breakthrough therapies have intensified capital deployment into GMP-compliant wet lab infrastructure, particularly around established biotech clusters where venture capital access and academic research proximity create self-reinforcing startup ecosystems.
Growth Catalysts
- ATMP Framework Expansion:EMA's adaptive pathways for advanced therapy medicinal products are pulling incubator investment toward segregated production corridors for cell and gene therapy ventures.
- Biologics Startup Concentration:Boston and San Francisco clusters concentrate venture capital deployment, creating localized demand spikes for temperature-controlled cell culture suites with hypoxic condition capabilities.
- Academic Research Proximity:University-affiliated incubators leverage institutional IP transfer pipelines to reduce early-stage drug development timeline risk for portfolio companies.
Market Restraints
- Specialized Equipment Cost Structure:Biosafety level 3 containment infrastructure and ISO 14644 cleanroom classifications inflate facility buildout costs beyond undercapitalized operator thresholds.
- Bioprocess Engineering Talent Scarcity:The finite supply of cell culture workflow specialists across major hubs collapses expansion timelines for incubator operators seeking qualified technical staff.
- Regulatory Jurisdiction Arbitrage Friction:Divergent NMPA registration pathways in China and BIS certification requirements in India fragment incubator network economics for multi-continental portfolio support.
Strategic Opportunities
- Asia-Pacific Localized Service Networks:Underpenetrated incubator infrastructure in South Korea and Singapore offers first-mover positioning for operators with regional regulatory compliance expertise.
- AI-Driven Facility Optimization:Convergence of machine learning with bioprocess monitoring enables predictive maintenance models that reduce wet lab downtime and extend equipment lifecycle value.
- Equity-Based Upside Capture:Fee-for-service university incubators face dilution risk aversion, creating white space for independent operators structuring portfolio company equity participation.
Industry Challenges
- GMP Certification Timeline Compression:USP sterile compounding standards and FDA cGMP guideline implementation cycles strain incubator cash flow during pre-revenue facility validation phases.
- Vector Manufacturing IP Complexity:Licensing negotiations for lentiviral and AAV production platforms introduce legal friction that delays gene therapy startup onboarding into incubator ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Incubators Market |
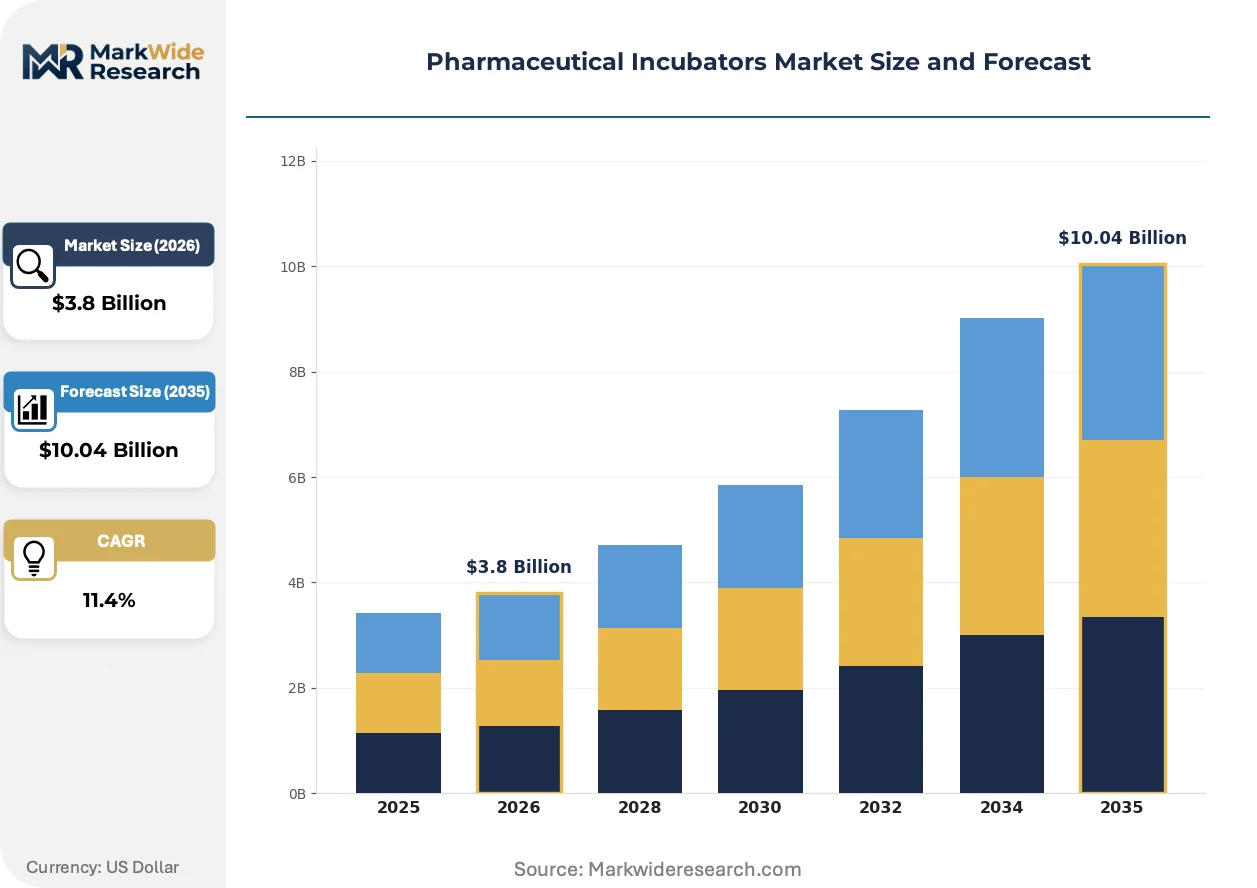
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Mentorship, Funding, Networking Business Model: Equity-Based, Fee-for-Service, Grant-Funded, Hybrid Model Technology: Biologics, Small Molecules, Gene Therapy, Nanotechnology End User: Startups, Research Institutions, Corporations, Non-Profits |
| Companies Covered | Thermo Fisher Scientific, GE Healthcare, Panasonic Healthcare, Memmert GmbH, Hettich Lab Technology, VWR, Natus Medical Incorporated, BINDER, Eppendorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Incubators Market Evolving Landscape
Modular cleanroom architectures are compressing facility deployment timelines for gene therapy-dedicated incubator space. Single-use bioreactor systems and closed processing workflows are displacing stainless steel infrastructure as the dominant capital configuration, enabling faster product changeover and reduced cross-contamination risk in multi-tenant environments.
Single-use bioprocessing technologies eliminate cleaning validation requirements between campaigns, reducing downtime for viral vector manufacturing suites. Gene therapy ventures are adopting these disposable systems at accelerating pace to preserve limited cash runway. This shift is displacing fixed equipment amortization models that previously dominated incubator operator capital planning, forcing new pricing structures around consumables bundling rather than facility rental.
REACH chemical safety registrations and EMA's evolving guidance on starting material qualification are tightening supply chain documentation requirements for European incubator tenants. These frameworks compel facility operators to implement enhanced vendor audit trails and raw material qualification protocols. Small molecule incubation segments in Germany and Switzerland are responding by consolidating procurement relationships with pre-qualified chemical suppliers to reduce regulatory inspection exposure.
Startup procurement patterns are fragmenting away from bundled equipment-service contracts toward unbundled, best-of-breed vendor selection. Early-stage ventures now separately negotiate consumables supply, equipment maintenance, and regulatory consulting relationships to preserve operational flexibility. This behavior is most visible in United States coastal clusters where venture capital availability supports higher administrative overhead tolerance for multi-vendor management.
Pharmaceutical Incubators Market Segmentation
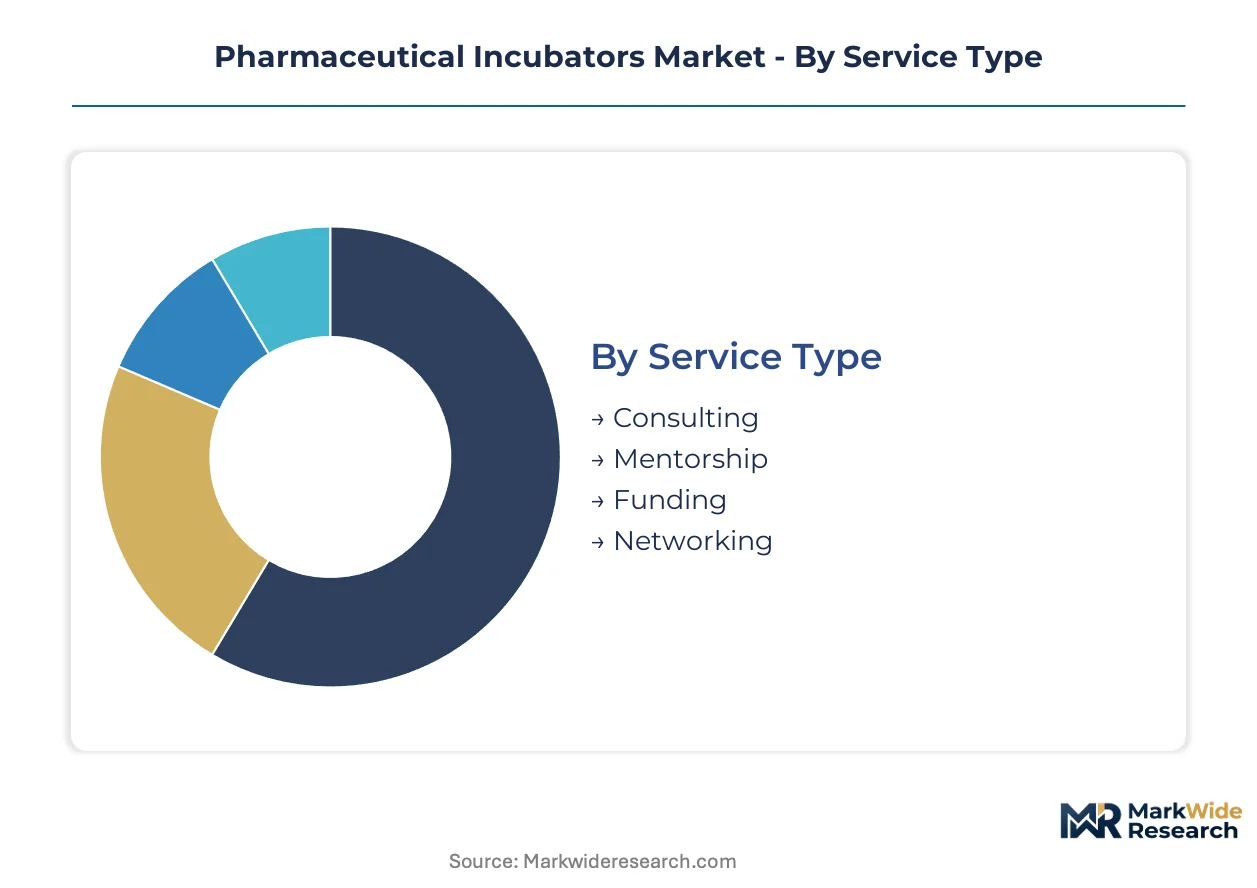
Pharmaceutical incubators segment across service delivery, commercial structure, therapeutic focus, and tenant profile. Each dimension shapes capital deployment, pricing architecture, and partnership strategy for facility operators.
Service Type:
Margin pools concentrate in high-touch advisory services where incubator operators capture equity upside or premium fees.
- Consulting:Regulatory strategy and IP navigation services command premium pricing from gene therapy ventures facing complex IND pathways. Boston and San Francisco clusters show concentrated demand for FDA pre-submission guidance bundled with wet lab access.
- Funding:Direct capital deployment and investor introduction services generate carried interest for equity-based incubators. The segment attracts independent operators seeking portfolio company upside rather than sustainable operating revenue.
- Mentorship:Experienced biotech executive networks reduce early-stage failure rates through structured advisory programs.
- Networking:Event programming and corporate partnership facilitation supports tenant business development with lower marginal cost.
Consulting holds installed capacity. Funding is rotating up the share rankings.
Business Model:
Cost tier differentiation separates capital-light university affiliates from independent operators bearing full facility economics.
- Equity-Based:Operators take ownership stakes in portfolio companies, aligning incentives with long-term venture success. This structure demands substantial balance sheet capacity during pre-revenue facility validation phases.
- Fee-for-Service:Predictable rental revenue dominates university-affiliated incubators seeking sustainable operations without dilution risk. The model sacrifices upside capture for lower volatility.
- Grant-Funded:Government and foundation capital subsidizes facility buildout in designated innovation zones.
- Hybrid Model:Blended structures combine base rental with success fees or warrant coverage.
Fee-for-Service anchors university ecosystems. Equity-Based is climbing the fastest among independent operators.
Technology:
Application complexity drives infrastructure specification and tenant qualification requirements.
- Gene Therapy:Viral vector manufacturing demands BSL-2+ containment, segregated air handling, and specialized equipment suites. EMA's ATMP framework and FDA breakthrough therapy pathways intensify capital deployment into GMP-compliant corridors for these ventures.
- Biologics:Mammalian cell culture workflows require temperature-controlled suites with hypoxic condition capabilities for stem cell propagation. The segment commands premium infrastructure investment due to biosafety and contamination control requirements.
- Small Molecules:Lower capital barriers sustain volume leadership in incubator tenancy despite slower growth trajectories.
- Nanotechnology:Drug delivery platform development occupies specialized characterization and formulation space.
Small Molecules maintains tenancy volume. Gene Therapy is gaining share fastest on specialized infrastructure demand.
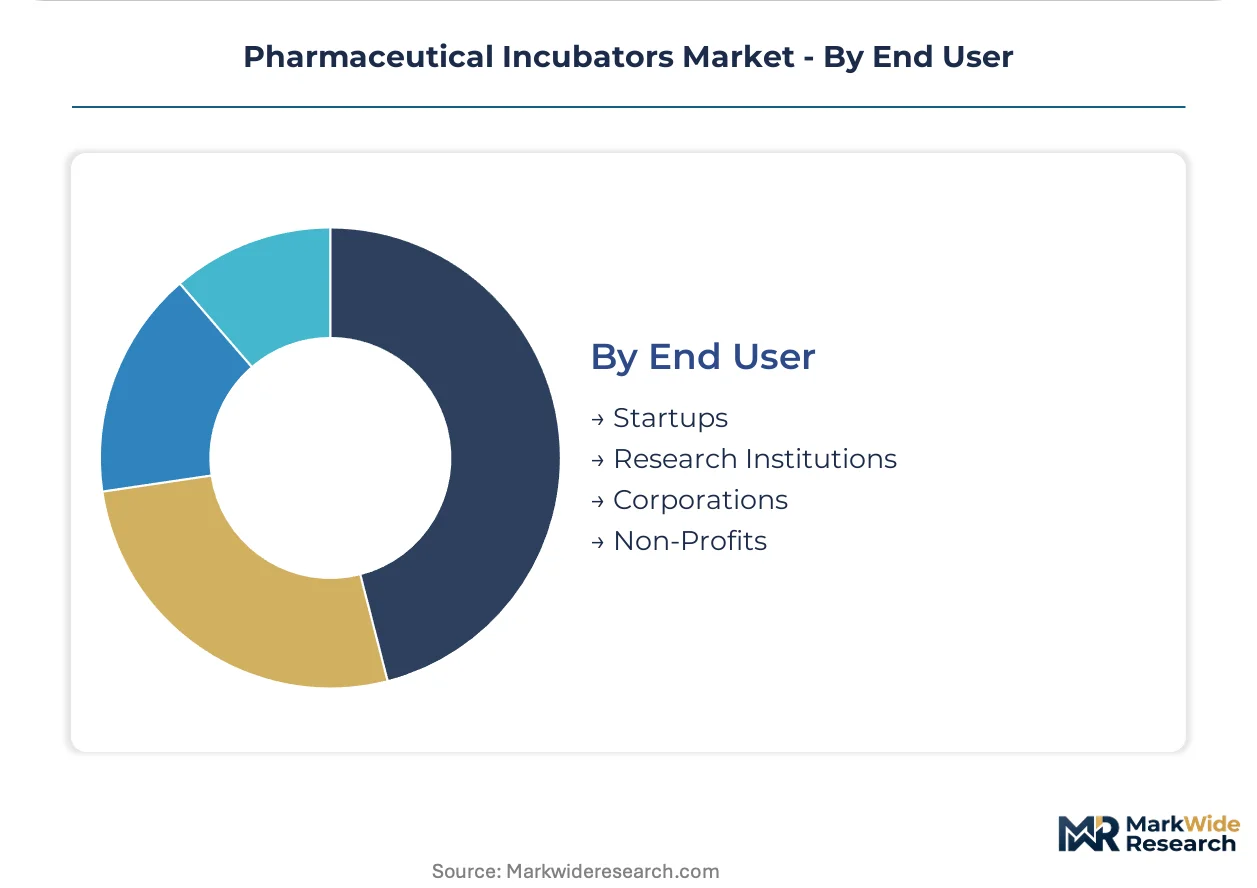
End User:
Customer type determines contract structure, technical support intensity, and retention economics.
- Startups:Venture-backed biotech ventures concentrate demand in Boston and San Francisco clusters where academic proximity and capital access create self-reinforcing ecosystems. These tenants drive specialized infrastructure requirements for cell and gene therapy manufacturing.
- Research Institutions:University spinouts leverage institutional IP transfer pipelines and subsidized facility access.
- Corporations:Big pharma innovation outposts seek external R&D access with lower capital commitment.
- Non-Profits:Disease foundation research programs occupy dedicated therapeutic focus facilities.
Startups dominate specialized suite demand. Corporations are expanding footprint in external innovation models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP guidelines and breakthrough therapy designation pathways anchor the United States as the dominant geography for pharmaceutical incubator investment, with venture capital deployment concentrating around established biotech clusters where academic research proximity accelerates startup formation timelines.
United States
Venture-backed biologics startups drive specialized infrastructure demand for temperature-controlled cell culture suites with hypoxic condition capabilities. FDA accelerated approval pathways intensify capital deployment into GMP-compliant wet lab corridors. Boston and San Francisco anchor self-reinforcing ecosystems where Thermo Fisher Scientific and Eppendorf maintain equipment supply partnerships with incubator operators.
Germany
REACH chemical safety registrations and EMA's ATMP framework tighten supply chain documentation requirements for European incubator tenants. Eppendorf's specialized bioreactor expertise embeds in regional lab design standards. The Rhine-Ruhr and Munich clusters concentrate gene therapy ventures seeking segregated production pathways for advanced therapy medicinal products.
Switzerland
Swissmedic's stringent regulatory framework for biologics manufacturing elevates facility compliance costs for incubator operators. The Basel biotech corridor leverages proximity to Novartis and Roche innovation outposts. Gene therapy startups concentrate around the country's precision medicine infrastructure and established pharmaceutical talent pools.
China
NMPA registration pathways for innovative biologics create divergent compliance burdens for multi-continental incubator networks. Panasonic Healthcare sustains geographic dominance through localized service networks and regulatory compliance support. Shanghai and Suzhou biotech parks attract domestic cell therapy ventures seeking segregated viral vector manufacturing suites.
Singapore
Underpenetrated incubator infrastructure offers first-mover positioning for operators with regional regulatory expertise. The country's national pharmaceutical regulator maintains alignment with FDA and EMA standards to facilitate multi-jurisdictional clinical trial pathways. Biopolis and one-north clusters concentrate stem cell and regenerative medicine ventures requiring specialized containment infrastructure.
Pharmaceutical Incubators Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pharmaceutical incubator equipment supply. Thermo Fisher Scientific leverages its integrated life sciences platform to anchor incubator partnerships with bundled equipment and consumables supply. Eppendorf competes through specialized bioreactor and cell culture workflow expertise embedded in incubator lab design. Panasonic Healthcare sustains geographic dominance in Asia-Pacific installations through localized service networks. Competitive moves concentrate on strategic partnerships with facility operators and technology licensing for single-use bioprocessing systems.
Among integrated life sciences conglomerates, Thermo Fisher Scientific and GE Healthcare occupy positions as full-stack platform providers spanning equipment, consumables, and regulatory consulting services. Eppendorf exemplifies the specialized workflow tier with embedded bioprocess engineering expertise. Panasonic Healthcare anchors the Asia-Pacific regional specialist archetype. Memmert GmbH and BINDER represent precision temperature control specialists serving cleanroom classification requirements. Hettich Lab Technology and VWR occupy distribution and technical service positions linking manufacturers to incubator facility operators.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| GE Healthcare |
| Panasonic Healthcare |
| Memmert GmbH |
| Hettich Lab Technology |
| VWR |
| Natus Medical Incorporated |
| BINDER |
| Eppendorf |
| Others |
Value Network & Pricing Analysis
Capacity reservation agreements with single-use bioreactor manufacturers lock in both equipment access and consumables pricing visibility for incubator operators navigating volatile resin costs. These multi-year contracts tether facility economics to polymer supply chains concentrated in petrochemical corridors while insulating tenants from spot-market volatility in filtration membrane procurement.
Pricing Analysis
Long-term offtake structures dominate equipment procurement, with bundled consumables contracts commanding premium positioning over unbundled rental arrangements. Price differentiation hinges on ISO 14644 cleanroom certification tier and GMP compliance grade, with BSL-3 containment suites capturing substantial premiums over standard mammalian cell culture space. Cost compression in small-molecule incubation segments is intensifying because venture-backed startups are extending cash runway through shared facility models. Academic spinouts exhibit highest price sensitivity due to grant-funded budget constraints, whereas gene therapy ventures prioritize technical capability over rental economics.
Supply Chain Analysis
Specialized filtration membrane production concentrates in Germany, the United States, and Japan, creating chokepoint vulnerability for viral vector manufacturing workflows. Raw material dependencies span pharmaceutical-grade stainless steel, single-use polymer resins, and precision temperature control components. Single-source vulnerability runs through AAV plasmid suppliers qualified under FDA starting material guidelines. Distribution runs through regional equipment-service integrators who bundle installation validation with ongoing technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical incubators market constitutes a high-growth disruption propelled by FDA breakthrough therapy pathways compressing IND-to-clinic timelines. EMA's ATMP framework expansion intensifies specialized infrastructure demand beyond current supply capacity.
For Market Incumbents: Compound equipment-service bundling advantages through backward integration into consumables manufacturing, neutralizing margin erosion from unbundled procurement trends among coastal cluster startups. Fortify GMP certification pipelines against emerging independent operators lacking pre-revenue validation capital. Prioritize talent retention in bioprocess engineering roles where scarcity collapses expansion timelines. For New Entrants and Emerging Players: AI-driven predictive maintenance services represent an under-served layer where incumbent equipment vendors lack workflow-specific expertise. Penetrate South Korea and Singapore incubator infrastructure gaps through localized regulatory compliance partnerships rather than direct facility construction. Pursue equity-based structures in university-affiliated ecosystems where fee-for-service models dominate and dilution aversion creates white space. For Investors and Strategic Acquirers: Capital is best deployed toward independent operators with validated GMP corridors and established venture capital networks in Boston or San Francisco clusters. Long-term viability over the coming decade rests on vector manufacturing IP positioning and ATMP regulatory track records. Monitor FDA pre-submission meeting volumes as an inflection indicator for incubator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Cleanroom Deployment | Compressed facility timelines enable faster gene therapy-dedicated suite activation in high-rent biotech clusters. |
| Single-Use Bioprocessing Transition | Disposable systems eliminate cleaning validation burdens between viral vector campaigns, preserving tenant cash runway. |
| Equity-Based Restructuring | Ownership stakes align incubator operators with portfolio company success beyond rental revenue stability. |
| Asia-Pacific Regulatory Localization | NMPA and MFDS compliance expertise unlocks underpenetrated incubator demand in Shanghai and Seoul biotech parks. |
| AI-Driven Facility Optimization | Predictive maintenance models reduce wet lab downtime and extend bioreactor lifecycle value for multi-tenant environments. |
Research Methodology
Desk research of FDA 483 inspection observations, EMA ATMP qualification databases, and venture capital deployment records preceded structured interviews with incubator facility operators, bioprocess engineering directors, and regulatory affairs consultants. Primary fieldwork with equipment manufacturers and university technology transfer officers was cross-validated against SEC filings from publicly traded life sciences conglomerates and trade association capacity surveys. Bottom-up facility buildout cost modeling was triangulated against top-down venture funding flow analysis.
Variance decomposition across service type, business model, technology segment, and end-user category shaped analytical framework construction throughout the forecast period. CAGRs were derived from facility capacity expansion pipelines, tenant occupancy trajectories, and equipment procurement backlogs. Treatment modality complexity and regional regulatory cluster stringency served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA cGMP and EMA ATMP regimes; material policy shifts would require re-modeling of facility validation timelines and capital deployment patterns. Practitioners should keep alternative scenarios live as NMPA registration pathway harmonization and BIS certification evolution in India reshape multi-continental incubator economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Cryogenic Ampoules Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market