
 GCC Medical Gloves Market | 2026-2036
GCC Medical Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Medical Gloves Market Foresight
Malaysian nitrile producers is rebalancing GCC supply chains after pandemic-era shortages exposed inventory fragility. Top Glove Corporation Berhad leverages its integrated rubber-to-glove manufacturing to sustain price competitiveness across Gulf ports. Paul Hartmann AG anchors its regional position through sterile surgical glove specialization for European-standard operating theaters. Salalah Medical Supplies Mfg. Co. LLC competes on proximity, operating its Oman-based facility to reduce lead times to UAE and Saudi buyers.
GCC medical gloves are disposable barrier devices manufactured from latex, nitrile, vinyl, neoprene, or polyethylene, typically tested to ASTM D6319 or EN 455 standards for tensile strength and viral penetration resistance, designed to prevent pathogen transmission between healthcare workers and patients. Nitrile formulations now dominate hospital procurement due to latex allergy prevalence and superior chemical resistance during chemotherapy handling. Laboratory work and surgical procedures represent the fastest-expanding application segments as Gulf governments expand diagnostic infrastructure and specialized surgery capacity. Sterile packs command premium positioning in tertiary hospitals, while bulk packs penetrate price-sensitive clinic channels.
The Saudi Food and Drug Authority enforces medical device marketing authorization aligned with Gulf Standardization Organization benchmarks, compelling foreign manufacturers to establish local authorized representatives. The UAE Ministry of Health and Prevention mandates compliance with ISO 13485 quality management systems for all imported medical gloves entering federal health facilities. Stakeholders must monitor evolving Gulf Standardization Organization harmonization timelines, as unified technical regulations across Saudi Arabia, UAE, Kuwait, Qatar, Bahrain, and Oman will reshape certification costs and market access requirements.
Market Dynamics
SFDA marketing authorization requirements are compressing import timelines for foreign manufacturers while Gulf Standardization Organization harmonization creates a dual-track compliance burden across Saudi Arabia and the UAE.
Growth Catalysts
- Surgical Volume Expansion:Hospital procurement in Riyadh and Jeddah corridors is accelerating as tertiary facilities expand specialized surgery capacity and consolidate purchasing power.
- SFDA Registration Mandate:Tightened medical device marketing authorization is forcing foreign manufacturers to establish local authorized representatives, creating captive distribution networks.
- Nitrile Formulation Superiority:Latex allergy prevalence in Gulf healthcare workforces is displacing natural rubber with nitrile alternatives in chemotherapy handling and surgical applications.
Market Restraints
- Butadiene Price Volatility:Nitrile polymer feedstock costs fluctuate with petrochemical crude linkages, compressing margin stability for converters without backward integration into rubber production.
- Malaysian Supply Concentration:Pandemic-era inventory fragility exposed GCC dependence on Port Klang and Tanjung Pelepas shipment corridors, creating single-point vulnerability.
- GSO Harmonization Friction:Divergent implementation timelines across Saudi Arabia, UAE, Kuwait, Qatar, Bahrain, and Oman multiply certification costs for multi-market entrants.
Strategic Opportunities
- Oman Proximity Advantage:Salalah-based manufacturing reduces lead times to UAE and Saudi buyers, creating regional hub potential for East African re-export.
- Sterile Surgical Premiumization:European-standard operating theater specifications in Dubai Healthcare City and King Faisal Specialist Hospital create demand for certified sterile packs.
- Diagnostic Infrastructure Buildout:Government laboratory expansion programs in Qatar and Kuwait are opening specialized chemical-resistant glove segments beyond hospital channels.
Industry Challenges
- ISO 13485 Certification Timelines:UAE Ministry of Health and Prevention mandates quality management system compliance for federal health facility entry, extending market access cycles.
- Inventory Reconfiguration Complexity:Post-pandemic safety stock normalization requires working capital redeployment while demand volatility persists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Medical Gloves Market |
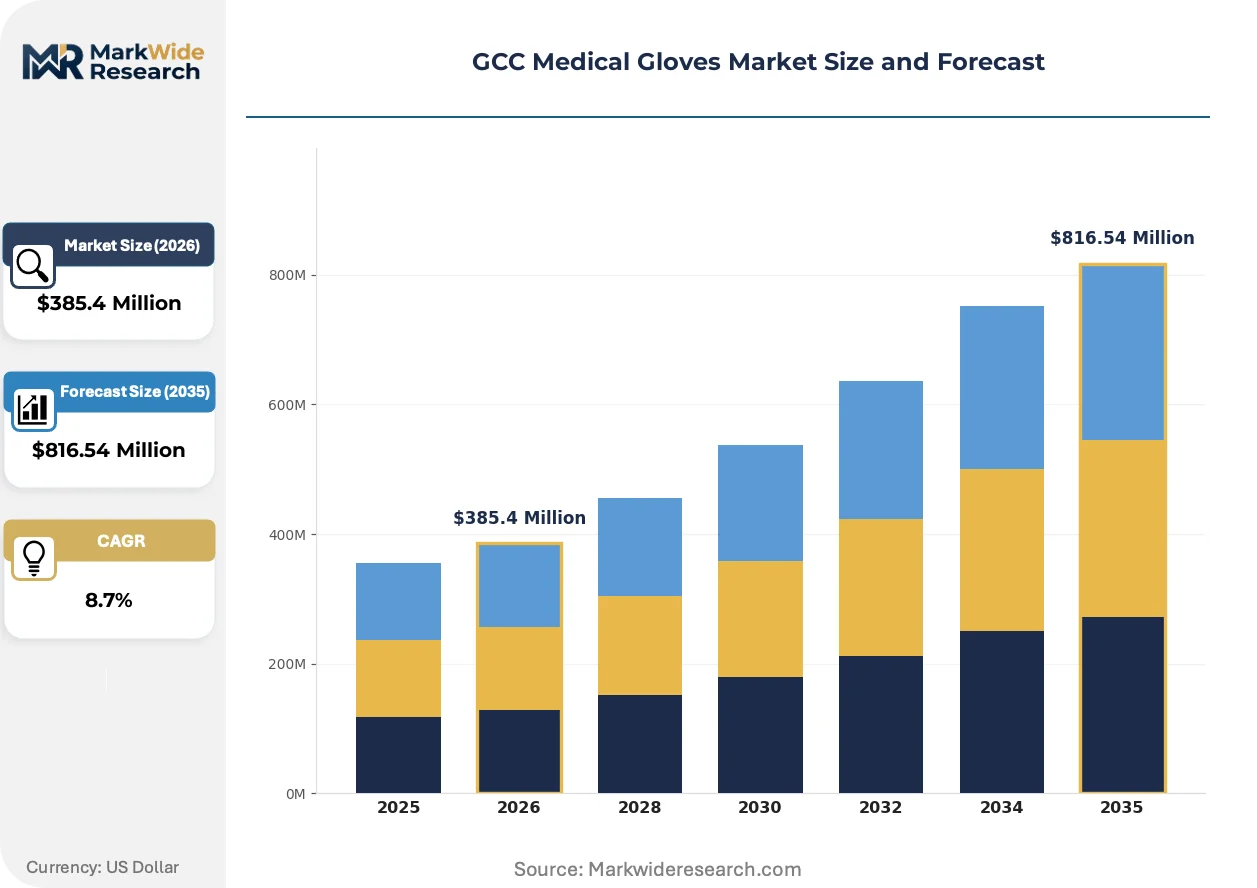
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Latex, Nitrile, Vinyl, Neoprene, Polyethylene Application: Surgical Procedures, Laboratory Work, Emergency Services, Dental Care, Veterinary Practices End User: Hospitals, Diagnostic Centers, Clinics, Pharmacies, Research Institutes Packaging Type: Boxes, Cartons, Dispensers, Bulk Packs, Sterile Packs |
| Companies Covered | Deeko Bahrain, NAFA Enterprises Ltd, Paul Hartmann AG, Salalah Medical Supplies Mfg. Co. LLC, Top Glove Corporation Berhad, Hotpack Packaging Industries LLC, United Medical Industries, Ansell Healthcare, Falcon Pack, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Medical Gloves Market Shifts & Advancements
Material science advances and regulatory convergence are reshaping product specifications while procurement centralization alters channel economics across Gulf health systems.
Chloroprene-neoprene hybrid formulations are converging with nitrile dominance in chemical protection segments. Saudi oncology centers and Dubai pharmaceutical manufacturing facilities are adopting these alternatives for extended-duration chemotherapy compounding. The technology is converging with existing nitrile supply chains, forcing compounders to dual-source polymer inputs or risk specification exclusion.
Gulf Standardization Organization technical regulation harmonization is compressing national divergence in medical device standards. SFDA and UAE Ministry of Health and Prevention are aligning inspection protocols, reducing duplicate audit burdens for multi-market suppliers. Sterile surgical glove categories face the steepest compliance acceleration as unified EN 455 and ASTM D6319 benchmarking takes effect.
Centralized purchasing consortia in Saudi Arabia's National Unified Procurement Company are consolidating volume negotiation power. Independent distributors and clinic-level buying are losing share to framework agreements covering Riyadh-Jeddah corridor hospitals. The concentration is most visible in tertiary hospital networks where single-source contracts now govern multi-year glove supply.
GCC Medical Gloves Market Segmentation
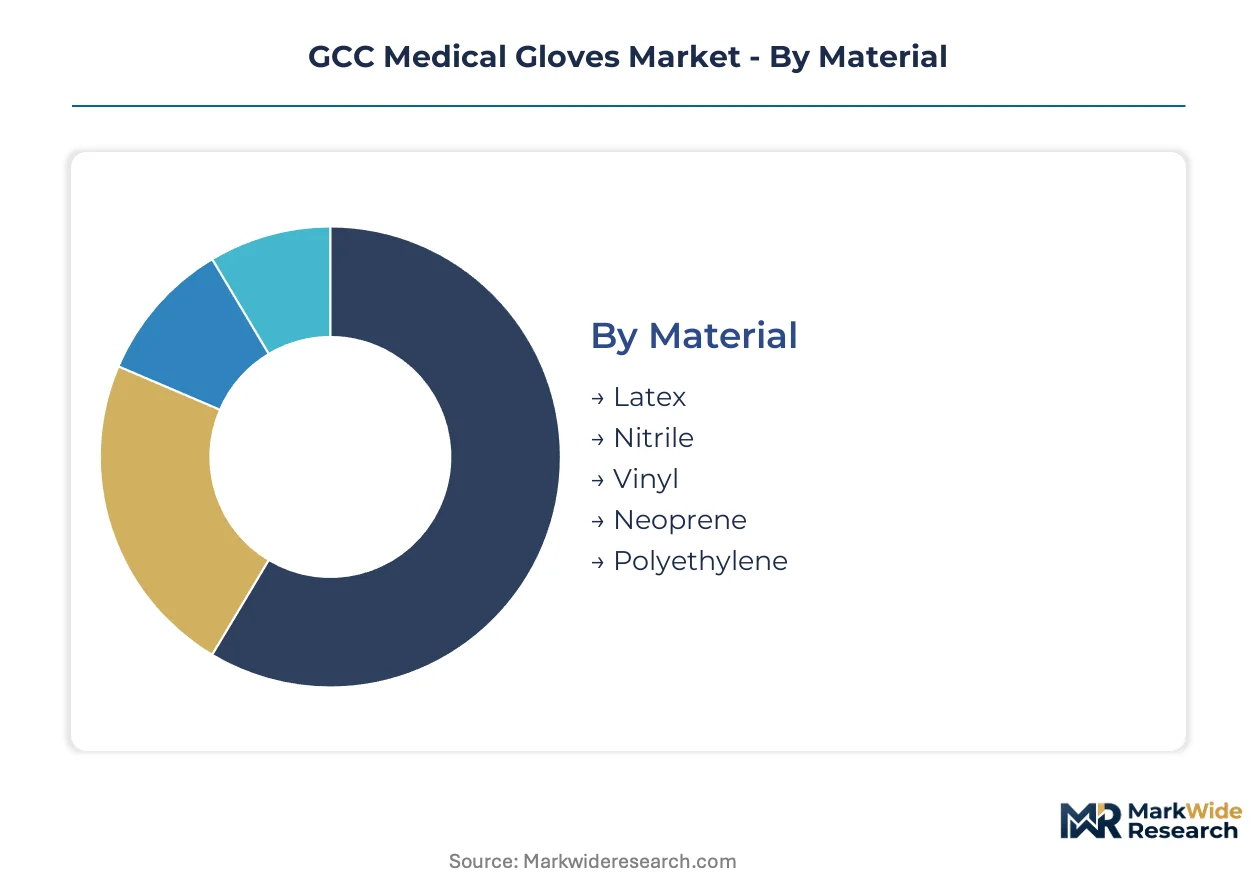
GCC procurement officers segment glove purchases across material chemistry, clinical setting, and sterility requirements. Each dimension carries distinct pricing power and compliance burdens that shape supplier selection.
Material:
Cost sensitivity and allergy profiles differentiate buyers across this category.
- Nitrile:Acrylonitrile-butadiene copolymer delivers puncture resistance and chemical protection superior to natural rubber. Saudi Arabia's King Faisal Specialist Hospital and UAE's Cleveland Clinic Abu Dhabi specify nitrile for oncology compounding and surgical suites, displacing latex as workforce allergy testing expands.
- Latex:Natural rubber from Hevea brasiliensis provides tactile sensitivity and elasticity prized in microsurgery. Demand concentrates in Dubai's private dental networks where powder-free processing addresses protein allergy concerns, though procurement volumes are compressing as nitrile prices normalize.
- Vinyl:Polyvinyl chloride formulations serve cost-constrained outpatient settings with minimal chemical exposure risk. Kuwait's primary health centers deploy vinyl for routine examinations where barrier duration stays under fifteen minutes.
- Neoprene:Chloroprene polymer withstands extended solvent contact in pharmaceutical manufacturing. Qatar's Ras Laffan industrial zone facilities specify neoprene for chemical handling beyond standard nitrile tolerance thresholds.
- Polyethylene:Cast film construction offers lowest-unit-cost protection for food handling and non-sterile logistics. Bahrain's clinic supply chains utilize polyethylene for inventory movement and waste management protocols.
Volume sits with nitrile; growth tilts toward neoprene as industrial chemical protection expands.
Application:
Procedure complexity and infection risk stratify glove specifications across clinical environments.
- Surgical Procedures:Sterile, anatomically curved designs with textured fingertips enable precision instrument control. Riyadh's National Guard Hospital and Jeddah's King Abdulaziz University Hospital drive consumption as cardiac and orthopedic surgery volumes climb.
- Laboratory Work:Extended-cuff nitrile resists permeation by reagents and biological specimens. Qatar's Sidra Medicine and Kuwait's Dasman Diabetes Institute are expanding diagnostic infrastructure, opening specialized chemical-resistant segments.
- Emergency Services:Rapid-donning ambidextrous designs prioritize speed over precision in trauma settings. UAE National Ambulance procurement frameworks specify high-visibility colors for contamination tracking.
- Dental Care:Thin-gauge latex and nitrile balance tactile feedback with splash protection. Dubai's private dental cluster consumes volume through group purchasing organizations serving specialty practices.
- Veterinary Practices:Heavy-duty nitrile withstands animal bites and zoonotic pathogen exposure. Oman's agricultural ministry veterinary stations represent emerging demand as livestock health programs expand.
Surgical applications command premium positioning; laboratory work is expanding most quickly as Gulf governments build diagnostic capacity.
End User:
Scale and compliance sophistication separate institutional buyers from fragmented retail channels.
- Hospitals:Tertiary facilities with centralized procurement power negotiate multi-year framework agreements. Saudi Arabia's National Unified Procurement Company consolidates Riyadh-Jeddah corridor volumes, compressing distributor margins.
- Diagnostic Centers:Specialized phlebotomy and imaging facilities require consistent quality with moderate volume. Dubai Health Authority-licensed laboratories are expanding as medical tourism infrastructure matures.
- Clinics:Independent primary care practices purchase through wholesale distributors with limited negotiating leverage. Price sensitivity dominates as reimbursement rates compress operational budgets.
- Pharmacies:Over-the-counter and prescription dispensing drives small-format pack demand. Kuwait's retail pharmacy chains stock consumer-grade vinyl for household first-aid applications.
- Research Institutes:Contamination-controlled environments mandate certified sterile supplies with full traceability. King Abdullah University of Science and Technology biosecurity protocols specify lot-level documentation.
Hospital procurement anchors volume concentration; diagnostic centers are gaining share fastest as outpatient testing displaces inpatient procedures.
Packaging Type:
Usage velocity and sterility requirements determine format economics across the supply chain.
- Sterile Packs:Individually wrapped pairs with ethylene oxide or gamma irradiation certification command 3-4x pricing multiples. European-standard operating theaters in Dubai Healthcare City and Saudi tertiary facilities mandate this specification.
- Bulk Packs:Loose gloves in inner bags of 50-100 units penetrate price-sensitive high-volume channels. Clinic and dental group purchasing organizations favor this format for working capital efficiency.
- Boxes:Standard 100-unit dispensers dominate hospital ward stocking and retail pharmacy shelves. UAE Ministry of Health and Prevention federal facility tenders specify box quantities for inventory parity.
- Cartons:Master shipping containers of 10-20 boxes enable efficient freight consolidation from Port Jebel Ali and King Abdulaziz Port to regional distribution centers.
- Dispensers:Wall-mounted acrylic or stainless steel holders reduce cross-contamination in high-traffic clinical areas. Infection control committees in Qatar's Hamad Medical Corporation mandate dispenser installation standards.
Bulk packs capture highest unit velocity; sterile packs generate steepest margin expansion as surgical complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian nitrile producers anchor GCC supply chains through Port Klang and Tanjung Pelepas corridors, while domestic manufacturing in Oman and Bahrain reshapes regional logistics. Saudi Arabia and the UAE concentrate procurement power through centralized health system consolidation.
Saudi Arabia
King Faisal Specialist Hospital and National Guard Hospital in Riyadh drive surgical glove consumption as cardiac and orthopedic volumes climb. The Saudi Food and Drug Authority enforces medical device marketing authorization requiring local authorized representatives for foreign manufacturers. The Riyadh-Jeddah corridor concentrates purchasing through the National Unified Procurement Company, consolidating tertiary hospital volumes.
United Arab Emirates
Dubai Healthcare City and Cleveland Clinic Abu Dhabi specify European-standard sterile packs for oncology compounding and surgical suites. The Ministry of Health and Prevention mandates ISO 13485 quality management system compliance for all federal health facility tenders. Jebel Ali port serves as the primary import gateway, with distribution networks radiating to northern emirates.
Oman
Salalah Medical Supplies Mfg. Co. LLC operates its domestic facility to reduce lead times to UAE and Saudi buyers. The country's national pharmaceutical regulator aligns with Gulf Standardization Organization benchmarks for medical device registration. Salalah's port infrastructure positions the city as a regional hub for East African re-export markets.
Qatar
Sidra Medicine and Hamad Medical Corporation are expanding diagnostic infrastructure, opening specialized chemical-resistant glove segments. The national health authority requires dispenser installation standards for infection control in high-traffic clinical areas. Ras Laffan industrial zone facilities specify neoprene for chemical handling beyond standard nitrile tolerance thresholds.
Kuwait
Dasman Diabetes Institute and primary health centers split demand between laboratory-grade nitrile and cost-constrained vinyl for routine examinations. The Ministry of Health procurement frameworks favor box quantities for inventory parity across clinic networks. Retail pharmacy chains stock consumer-grade vinyl for household first-aid applications.
GCC Medical Gloves Market Competitive Landscape
Global majors compete with regional champions across material integration and proximity-to-market dimensions. Malaysian producers with backward rubber integration anchor volume supply, while European specialists capture sterile surgical premiums. Gulf-based manufacturers compete on logistics speed. The competitive arena splits between integrated polymer producers, sterile specialization houses, and regional fabricators. Capacity expansion and certification acceleration represent the dominant competitive moves as Gulf Standardization Organization harmonization tightens.
Within the regional proximity tier, Salalah Medical Supplies Mfg. Co. LLC exemplifies logistics-driven positioning through its Oman-based operations. Top Glove Corporation Berhad and Paul Hartmann AG occupy distinct archetype positions—Malaysian volume integration versus European sterile specialization. Deeko Bahrain represents Gulf-based manufacturing seeking to compress import lead times. These three anchors illustrate the strategic segmentation between rubber-integrated supply, premium sterile certification, and regional logistics optimization.
| Leading Market Players |
|---|
| Deeko Bahrain |
| NAFA Enterprises Ltd |
| Paul Hartmann AG |
| Salalah Medical Supplies Mfg. Co. LLC |
| Top Glove Corporation Berhad |
| Hotpack Packaging Industries LLC |
| United Medical Industries |
| Ansell Healthcare |
| Falcon Pack |
| Others |
Supply & Pricing Matrix
National Unified Procurement Company framework agreements in Saudi Arabia are compressing distributor margins and forcing suppliers to unbundle sterile certification costs from base glove pricing. This procurement consolidation compels manufacturers to absorb compliance expenses or surrender volume to integrated competitors with captive rubber production.
Pricing Analysis
Service bundling separates sterile pack premiums from bulk format commoditization across Gulf hospital tenders. Three-tier pricing structure across premium sterile, standard examination, and economy vinyl levels tracks certification grade and volume scale. Pricing pressure stems from butadiene feedstock volatility tethered to petrochemical crude linkages. Clinic-level buyers exhibit highest price sensitivity, while tertiary hospital procurement committees prioritize compliance reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Saudi Arabia's National Unified Procurement Company and UAE Ministry of Health and Prevention require manufacturers to qualify backup production lines. Malaysian nitrile production, Omani regional fabrication, and European sterile specialization anchor GCC supply. Raw material dependencies center on acrylonitrile and butadiene monomers, natural rubber latex, and chloroprene polymer. Single-source vulnerability concentrates in Port Klang shipment corridors. Distribution runs through Jebel Ali and King Abdulaziz Port consolidation to regional health system distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into acrylonitrile-butadiene rubber production is emerging as the decisive competitive lever as feedstock volatility erodes converter margins.
For Market Incumbents: Anchor market position through SFDA marketing authorization acceleration and sterile surgical certification depth. Defend against Malaysian volume players by locking multi-year framework agreements with National Unified Procurement Company before GSO harmonization raises compliance barriers. Prioritize ISO 13485 maintenance to satisfy UAE federal facility mandates.
For New Entrants and Emerging Players: Launch via diagnostic center specialization targeting Qatar's Sidra Medicine and Kuwait's Dasman Diabetes Institute expansion programs. Penetrate the laboratory chemical-resistant segment where specification requirements favor nimble compounders over bulk nitrile producers. Deploy Oman-based logistics to compress lead times for East African re-export qualification.
For Investors and Strategic Acquirers: Re-rating potential sits with sterile surgical specialists given GSO harmonization compression of duplicate audit burdens. Long-term viability favors manufacturers with polymer integration or regional proximity assets. Monitor Gulf Standardization Organization unified technical regulation implementation velocity as the critical inflection signal for certification cost normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Production | Captive acrylonitrile-butadiene supply insulates margins from butadiene volatility linked to crude benchmarks. |
| SFDA Marketing Authorization Acceleration | Local authorized representative establishment secures Saudi hospital procurement eligibility before competitor qualification. |
| Sterile Surgical Certification Investment | European-standard EN 455 and ASTM D6319 benchmarking captures premium positioning in Dubai Healthcare City. |
| Oman Regional Hub Development | Salalah port proximity reduces lead times to UAE and Saudi buyers while enabling East African re-export. |
| Diagnostic Infrastructure Partnership | Laboratory expansion programs in Qatar and Kuwait open specialized chemical-resistant glove segments beyond hospital channels. |
Research Methodology
Trade databases, Gulf Standardization Organization technical regulations, and hospital procurement records formed the secondary backbone for this analysis. Primary interviews with biomedical engineers, GPO contracts managers, regulatory affairs specialists at SFDA and MOHAP, and nitrile compounder technical directors validated demand assumptions. Bottom-up volume modeling across material chemistry, clinical application, and end-user tiers triangulated with top-down healthcare expenditure allocation.
Historical trendline analysis of surgical volume expansion, import shipment corridors through Port Klang and Jebel Ali, and framework agreement award patterns informed the projection framework. Segmentation dimensions modeled include material formulation, sterility requirement, packaging format, and health system tier across the analysis window. CAGRs were derived from elasticity-adjusted consumption trajectories incorporating SFDA registration timelines and GSO harmonization schedules.
Butadiene price volatility, GSO implementation divergence across member states, and Malaysian supply concentration are the dominant revision risks to the outlook. Deviation in any of these vectors would shift the projection materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
South America Syringe Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Hospital Gowns Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Global Syringe Market
Medical Supplies
Smear Mask Market
Medical Supplies
Medical Swabs Market