
 Healthcare Contract Research Organization Market | 2026-2036
Healthcare Contract Research Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Contract Research Organization Market Intelligence
Asset-light operating models and strategic leasing of trial infrastructure are reshaping competitive dynamics in the CRO sector. IQVIA leverages its integrated data science platform to anchor large real-world evidence contracts. Labcorp sustains dominance through captive laboratory networks that accelerate patient sample turnaround. ICON plc differentiates via therapeutic specialization in oncology and rare disease protocols.
A Healthcare Contract Research Organization delivers outsourced clinical development services spanning trial design, site management, biostatistics, and regulatory submission support, operating under Good Clinical Practice guidelines and 21 CFR Part 11 electronic records standards to generate evidence for drug and device approvals. Clinical Trials commands the largest service-type revenue pool while Regulatory Affairs captures above-average margins as complexity intensifies. Patient Recruitment Platforms represents the fastest-expanding technology segment as decentralized trial formats reduce geographic barriers to enrollment.
FDA enforces stringent data integrity standards under 21 CFR Part 11 that compel CROs to maintain validated electronic systems, while EMA's Clinical Trial Regulation harmonizes submission protocols across EU member states and reshapes cross-border study execution. Sponsors must monitor how FDA's evolving guidance on decentralized trials and EMA's accelerated assessment pathways alter site selection and technology investment priorities.
Market Dynamics
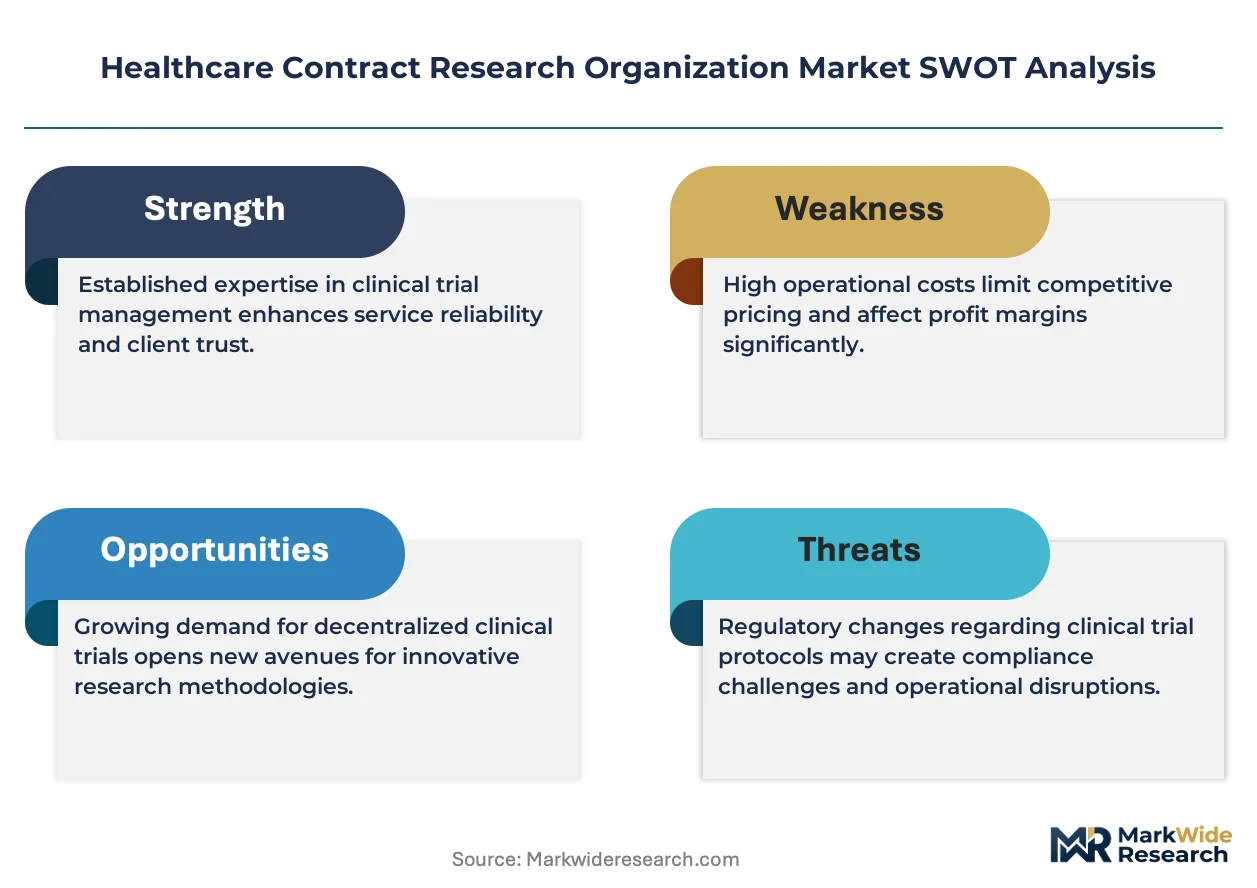
Decentralized trial formats are compressing site selection timelines and forcing CROs to rebuild infrastructure around direct-to-patient logistics rather than traditional site networks. FDA guidance on decentralized elements and EMA's Clinical Trial Regulation together mandate validated electronic systems that reshape capital allocation across the sector.
Growth Catalysts
- EMA Clinical Trial Regulation:Harmonized submission protocols across EU member states reduce administrative duplication for cross-border studies. Sponsors consolidate vendor relationships to exploit streamlined assessment pathways.
- Real-world evidence integration:Payers and regulators now accept supplementary RWE for label expansions. CROs with integrated data science capabilities capture expanded service scopes from biopharma sponsors.
- Oncology protocol complexity:Adaptive trial designs and biomarker stratification require specialized biostatistical expertise. Academic medical centers in the United States and Germany outsource increasing portions of study execution to specialized partners.
Market Restraints
- Qualified investigator scarcity:Principal investigators with FDA inspection histories command premium compensation. Site activation delays extend study timelines in competitive therapeutic areas.
- Single-source laboratory dependence:Central lab services concentrate among three global providers. Sponsors face pricing leverage asymmetry and limited redundancy for critical biomarker analysis.
- 21 CFR Part 11 compliance burden:Validated electronic data capture systems require continuous software qualification. Smaller CROs struggle with sustained IT infrastructure investment.
Strategic Opportunities
- Asia-Pacific site expansion:Regulatory harmonization through ASEAN and China's NMPA reforms enable multi-country protocols. Patient access accelerators attract oncology and rare disease sponsors seeking enrollment velocity.
- Direct-to-patient logistics:Home nursing and mobile health technologies converge with wearable biosensors. CROs can capture value previously retained by specialty pharmacy distributors.
- EU Green Deal alignment:Sustainable clinical trial guidelines incentivize reduced patient travel and digital consent processes. Early adopters differentiate in EMA tender evaluations.
Industry Challenges
- Biostatistician recruitment:Advanced degree holders with adaptive design expertise remain scarce. CROs compete with technology firms for quantitative talent.
- Legacy EDC integration:Sponsor-mandated systems often lack API connectivity with modern patient engagement platforms. Custom interface development consumes project margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Contract Research Organization Market |
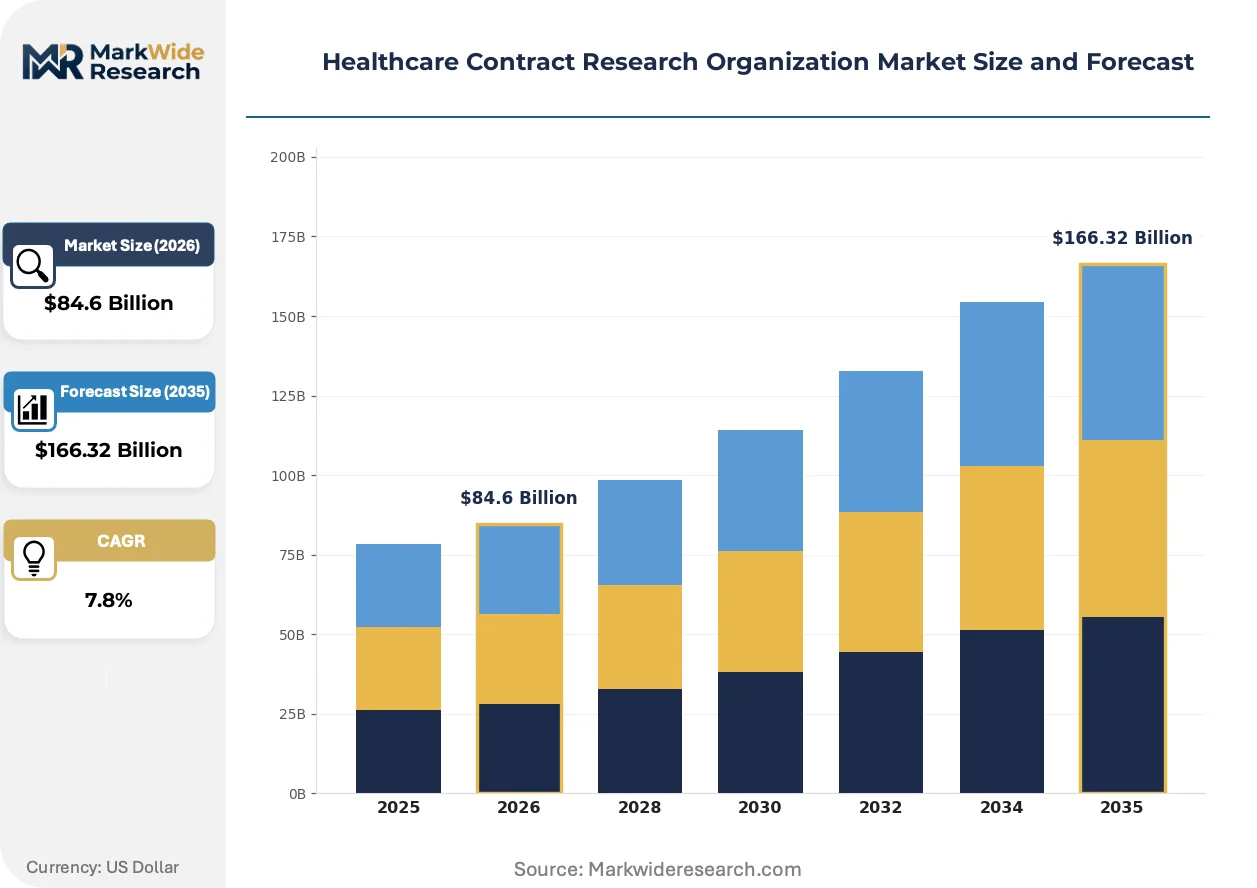
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $166.32 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Trials, Data Management, Regulatory Affairs, Bioanalytical Services End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Medical Device Manufacturers Technology: EHR Systems, Clinical Trial Management Systems, Data Analytics, Patient Recruitment Platforms Application: Oncology, Cardiovascular, Neurology, Rare Diseases |
| Companies Covered | IQVIA, Labcorp, ICON plc, Parexel International, Thermo Fisher Scientific, Syneos Health, Charles River Laboratories, Medpace, Fortrea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Contract Research Organization Market Strategic Shifts & Innovations
Technology convergence between remote monitoring devices and cloud-based data platforms is collapsing traditional site-centric trial models. Regulatory bodies on both sides of the Atlantic are codifying standards that validate these operational shifts.
Artificial intelligence-driven patient matching algorithms are digitizing enrollment forecasting and reducing screen-failure rates. Mid-sized biopharma sponsors in the United States are deploying these tools for phase II oncology studies. The compression of enrollment timelines is digitizing competitive positioning among CROs vying for fixed-scope contracts.
FDA's evolving guidance on decentralized clinical trial elements is mandating risk-based quality management systems for remote data collection. European sponsors executing US protocols must dual-validate systems against 21 CFR Part 11 and EMA expectations. Oncology and rare disease studies with dispersed patient populations face the steepest compliance adaptation requirements.
Sponsor procurement teams are unbundling full-service contracts into functional components—site management, data management, and biostatistics awarded separately. Large pharmaceutical companies in Germany and Switzerland now run competitive tenders for each workstream. This disaggregation is most visible in late-phase studies where sponsor internal capabilities cover protocol design and regulatory strategy.
Healthcare Contract Research Organization Market Segmentation
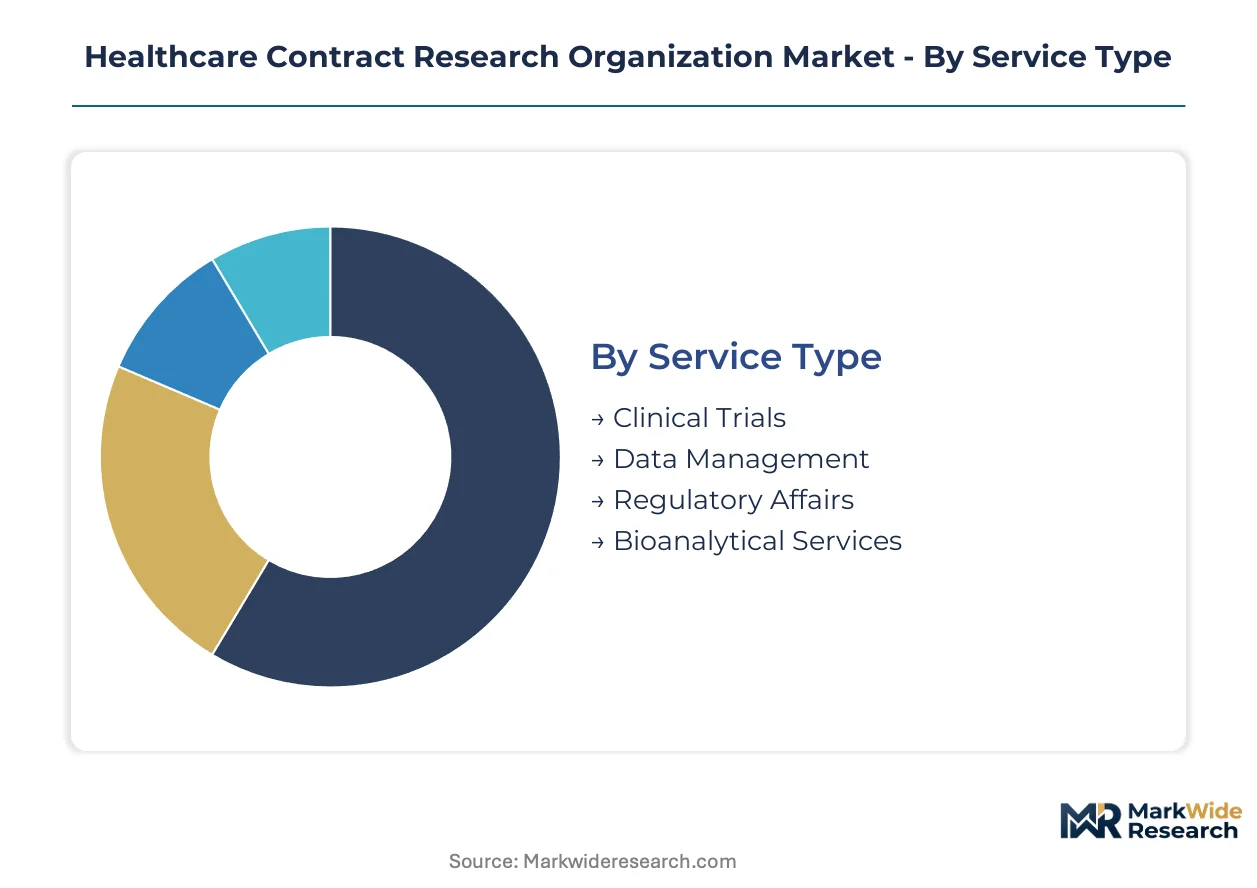
Service specialization and technology deployment patterns determine margin capture in the CRO sector. Sponsors select vendors based on therapeutic expertise depth and regulatory track record rather than geographic coverage alone.
Service Type:
Cost tier differentiation separates high-touch advisory services from standardized operational execution.
- Clinical Trials:Comprehensive protocol execution encompassing site activation, patient monitoring, and safety surveillance. Pharmaceutical sponsors in the United States and Germany concentrate spending here for phase III oncology studies where enrollment velocity determines competitive positioning.
- Regulatory Affairs:Submission strategy, dossier compilation, and agency negotiation support. Biotechnology firms navigating FDA's accelerated approval pathways and EMA's priority medicines designation drive premium pricing for specialized regulatory expertise.
- Data Management:Electronic data capture architecture and database lock management.
- Bioanalytical Services:Pharmacokinetic sample analysis and biomarker quantification.
Clinical Trials holds installed capacity. Regulatory Affairs is rotating up the share rankings.
End User:
Customer type dictates contract structure complexity and payment term negotiations.
- Pharmaceutical Companies:Large-cap sponsors with internal clinical operations capabilities outsource selective functions—typically patient recruitment and biostatistics—while retaining protocol design and regulatory strategy. These buyers unbundle contracts into discrete workstreams to optimize vendor selection.
- Biotechnology Firms:Venture-backed developers lacking internal infrastructure purchase full-service partnerships spanning trial design through submission. FDA breakthrough therapy designations and EMA's PRIME eligibility compress timelines and intensify demand for integrated CRO relationships.
- Academic Institutions:Investigator-initiated studies with limited commercial budgets.
- Medical Device Manufacturers:PMA and 510(k) pathway submissions with distinct evidentiary requirements.
Pharmaceutical Companies anchor volume concentration. Biotechnology Firms represent the steepest expansion trajectory.
Technology:
Application maturity separates legacy infrastructure investments from emerging platform adoption.
- Patient Recruitment Platforms:AI-driven patient matching algorithms and decentralized trial logistics. Mid-sized oncology sponsors deploy these tools to compress enrollment timelines and reduce screen-failure rates in dispersed rare disease populations.
- Clinical Trial Management Systems:Integrated project oversight, budget tracking, and milestone management. Large pharmaceutical sponsors mandate specific CTMS vendors, forcing CROs to maintain multi-platform compatibility and absorb integration costs.
- EHR Systems:Site-level electronic health record extraction for real-world evidence generation.
- Data Analytics:Predictive modeling and safety signal detection capabilities.
Clinical Trial Management Systems dominates current deployment. Patient Recruitment Platforms is climbing the fastest.
Application:
Volume concentration and protocol sophistication create divergent service requirements across therapeutic areas.
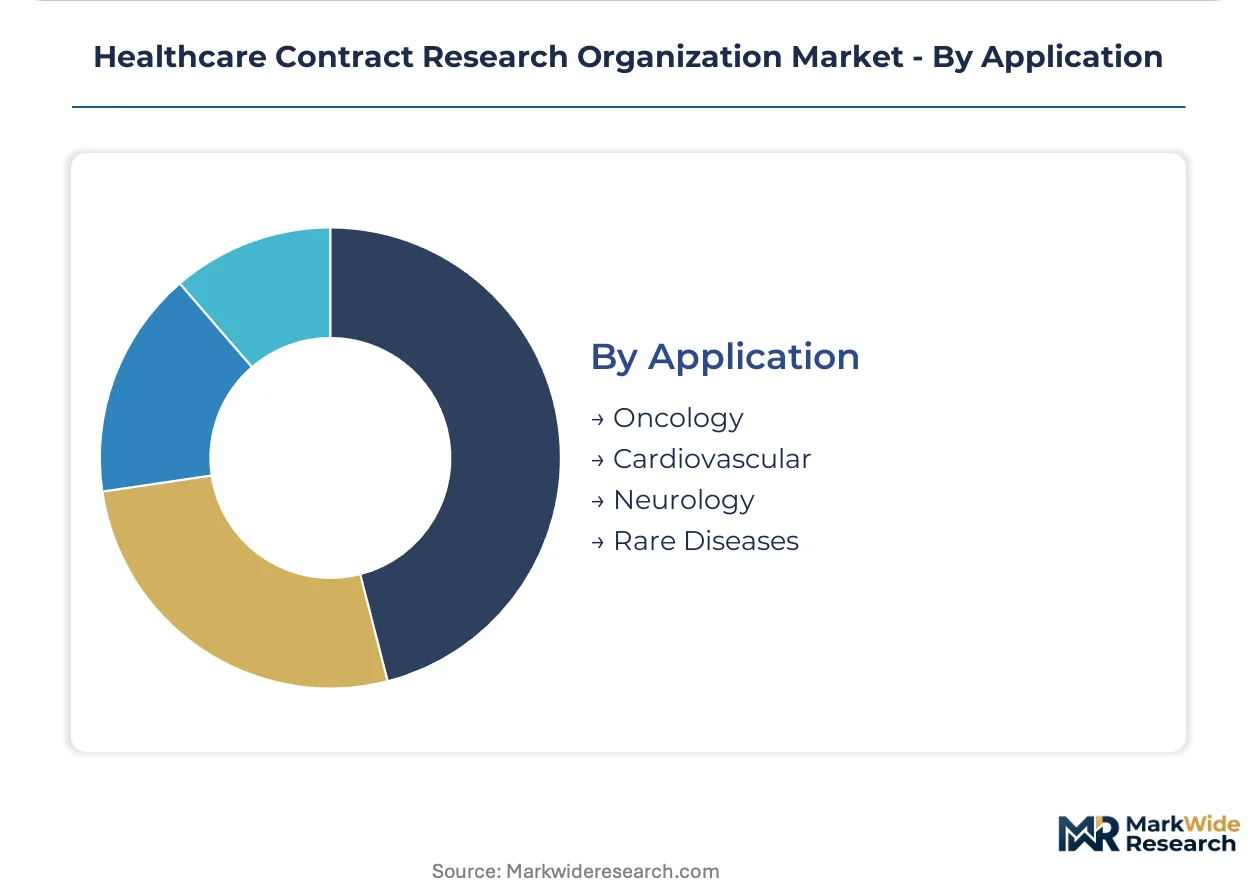
- Oncology:Adaptive trial designs, biomarker stratification, and combination therapy protocols. Academic medical centers in the United States and Germany outsource execution to specialized partners as protocol complexity exceeds internal biostatistical capacity.
- Rare Diseases:Small patient populations dispersed across geographies necessitate multi-country recruitment and direct-to-patient logistics. EMA's centralized procedure and FDA's orphan drug incentives align regulatory timelines for sponsors pursuing simultaneous submissions.
- Cardiovascular:Large outcome studies with established endpoints and mature site networks.
- Neurology:Subjective endpoints and lengthy follow-up periods requiring specialized rater training.
Oncology commands the largest addressable spend. Rare Diseases is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's decentralized trial guidance and EMA's Clinical Trial Regulation are reshaping where sponsors allocate study budgets. National reimbursement policies and regulatory harmonization initiatives determine site selection velocity across major markets.
United States
Biopharma sponsors concentrate phase III oncology spending where principal investigators with FDA inspection histories command premium compensation. The FDA's evolving guidance on decentralized elements mandates validated electronic systems that smaller CROs struggle to maintain. Boston and San Francisco anchor specialized site networks for rare disease protocols.
Germany
Academic medical centers in Munich and Heidelberg outsource execution as adaptive trial complexity exceeds internal biostatistical capacity. EMA's centralized procedure harmonizes submission protocols across EU member states. The country's national pharmaceutical regulator enforces stringent data integrity standards that favor established CRO partnerships.
China
NMPA reforms enable multi-country protocols through regulatory harmonization with ASEAN frameworks. Patient access accelerators in Shanghai and Beijing attract oncology sponsors seeking enrollment velocity. The national medical products administration tightens electronic records standards that compel validated system investments.
United Kingdom
Biotechnology firms navigating EMA's priority medicines designation compress timelines through integrated CRO relationships. London's concentration of venture-backed developers drives full-service partnership demand. The Medicines and Healthcare products Regulatory Agency aligns with FDA expectations on real-world evidence acceptance.
Switzerland
Large pharmaceutical companies in Basel run competitive tenders for unbundled workstreams covering site management and biostatistics. Swissmedic maintains rigorous inspection standards that validate CRO quality systems. The country's regulatory track record attracts sponsors pursuing simultaneous FDA and EMA submissions.
Healthcare Contract Research Organization Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered vendor base. Consolidation pressure concentrates among full-service providers while mid-sized firms carve therapeutic niches. Three archetypes dominate: integrated data science platforms, captive laboratory networks, and therapeutic specialization boutiques. M&A activity and strategic technology licensing represent the dominant competitive moves as sponsors disaggregate contracts into functional components.
Within the integrated platform tier, IQVIA exemplifies data science anchoring for real-world evidence contracts. Labcorp occupies a position tied to captive laboratory infrastructure that accelerates sample turnaround. ICON plc represents therapeutic specialization archetypes focused on oncology and rare disease protocols. These three entities illustrate how competitive positioning diverges across service model architectures rather than geographic coverage alone.
| Leading Market Players |
|---|
| IQVIA |
| Labcorp |
| ICON plc |
| Parexel International |
| Thermo Fisher Scientific |
| Syneos Health |
| Charles River Laboratories |
| Medpace |
| Fortrea |
| Others |
Cost & Logistics Intelligence
Boston's concentration of academic medical centers and principal investigators with FDA inspection histories creates asymmetric pricing leverage for site activation services. CROs competing for oncology and rare disease protocols absorb premium investigator compensation costs that cascade into project-based fee structures.
Pricing Analysis
Certification level (FDA-grade 21 CFR Part 11 validation) creates the primary spread between premium and standard service tiers. Project-based pricing dominates, with biotechnology firms purchasing full-service partnerships and pharmaceutical companies unbundling into discrete workstreams. Price differentiation rests on therapeutic specialization depth and regulatory track record rather than geographic coverage. Cost compression in mid-tier data management services is intensifying because sponsor-mandated legacy EDC systems lack API connectivity. Biotechnology firms with compressed timelines exhibit lowest price sensitivity; academic institutions with limited commercial budgets anchor the economy tier.
Supply Chain Analysis
Extended payment terms from large pharmaceutical sponsors strain CRO working capital, with supply-chain finance facilities emerging as a competitive differentiator. Service delivery concentrates in the United States, Germany, and China, where regulatory harmonization enables multi-country protocol execution. Biostatistical talent and validated electronic data capture systems constitute critical input dependencies. Single-source laboratory dependence among three global providers creates pricing leverage asymmetry. Distribution runs through direct sponsor-CRO relationships with limited intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of principal investigators with FDA inspection histories and adaptive design biostatisticians concentrates competitive advantage among firms with established talent pipelines. This capability scarcity rewards early investment in specialized expertise development.
For Market Incumbents: Entrench dominance by acquiring boutique oncology and rare disease specialists before valuation multiples adjust to scarcity premiums. Expand captive laboratory networks in the United States and Germany to reduce single-source dependence risk. Accelerate 21 CFR Part 11 compliance infrastructure investments to widen the competitive moat against smaller CROs.
For New Entrants and Emerging Players: Build out Asia-Pacific site networks in China and ASEAN markets where regulatory harmonization enables multi-country protocols with lower investigator cost structures. Target rare disease patient recruitment platforms as the most penetrable segment, leveraging decentralized trial formats to bypass established site networks. Pursue direct-to-patient logistics partnerships with home nursing providers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because sponsor procurement teams are systematically disaggregating full-service contracts into functional components, creating roll-up opportunities for specialized data management and biostatistics boutiques. Monitor FDA guidance evolution on decentralized trial elements as the critical signal for technology investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Therapeutic Specialization Acquisition | Captures premium pricing in oncology and rare disease protocols where adaptive designs exceed internal sponsor capacity. |
| Decentralized Trial Infrastructure Buildout | Aligns with FDA guidance on direct-to-patient logistics and EMA's EU Green Deal sustainability incentives. |
| Real-World Evidence Platform Integration | Secures expanded service scopes as FDA and EMA accept supplementary RWE for label expansions. |
| Asia-Pacific Site Network Expansion | Exploits NMPA reforms and ASEAN harmonization to capture enrollment velocity in dispersed patient populations. |
| Validated EDC System Investment | Addresses 21 CFR Part 11 compliance burden that smaller competitors struggle to sustain. |
Research Approach
A standing panel of drug development executives, regulatory affairs leads, site activation managers, and biostatistics directors provided ongoing calibration across the research process. Primary interviews with CRO procurement officers and sponsor vendor management teams combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and GPO contract databases. Bottom-up service-type segmentation triangulated against top-down sponsor spending pattern analysis.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions covering service type, end user archetype, technology deployment, and therapeutic application. CAGRs derived from sponsor pipeline analysis and regulatory submission velocity trends. Forecast inputs incorporated investigator availability indices and decentralized trial adoption curves.
Stress conditions across qualified investigator scarcity, 21 CFR Part 11 compliance cost escalation, and EMA centralized procedure timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and sponsor outsourcing propensity. Macroeconomic contraction, abrupt regulatory guidance reversal, or disruptive trial technology breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
US Clinical Trials Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Esource and Clinical Trials Market