
 Online Doctor Consultation Market | 2026-2036
Online Doctor Consultation Market Size, Share, and Industry Trends Forecast 2026-2036
Online Doctor Consultation Market Outlook
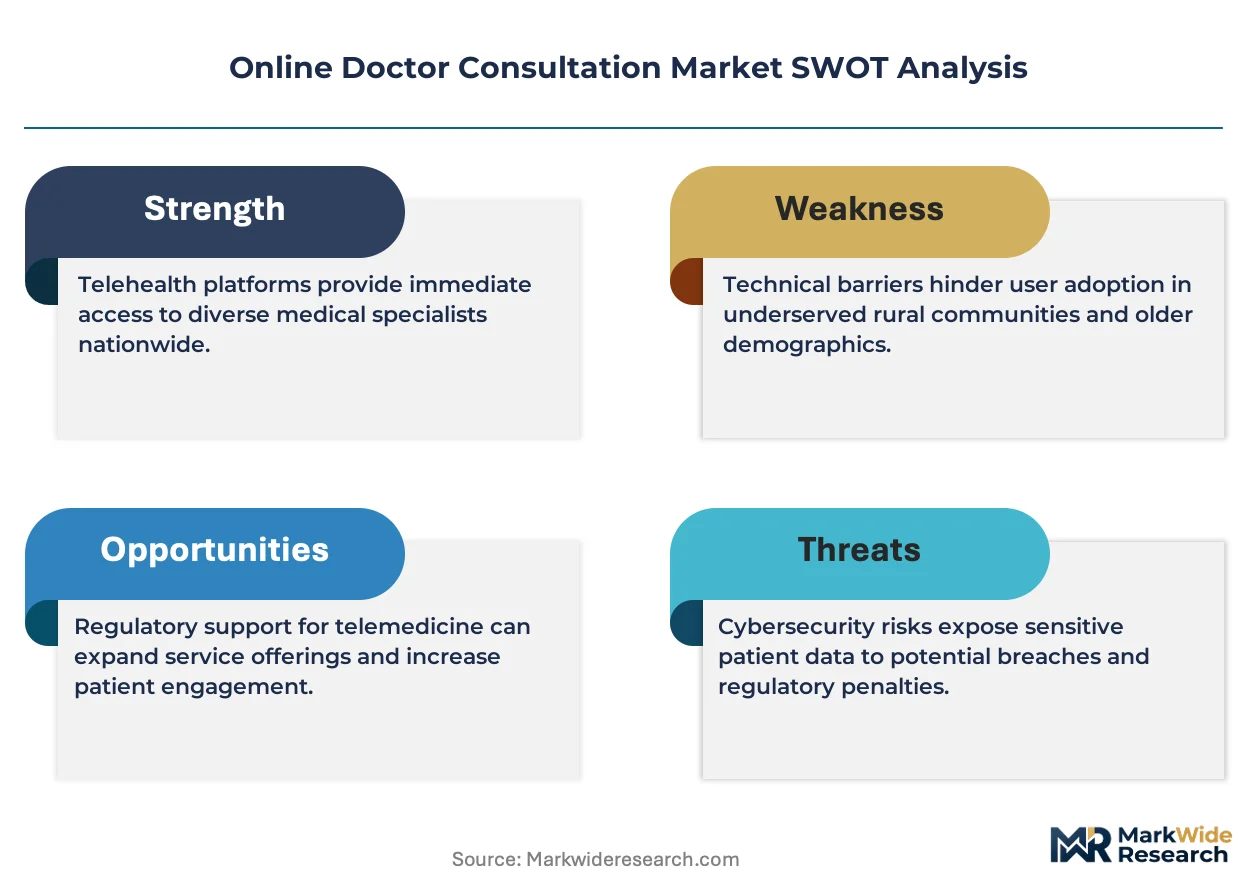
Cloud-native microservices architecture is fragmenting the traditional monolithic telemedicine stack into interoperable, API-driven components. Teladoc Health leverages its enterprise channel control to anchor large employer contracts. Amwell sustains R&D intensity through its hybrid care platform investments. Practo dominates South Asian markets with localized payment and pharmacy integrations.
Online doctor consultation denotes real-time or asynchronous remote clinical interaction between licensed physicians and patients via encrypted digital channels, typically requiring bandwidth above 1 Mbps for video and HL7 FHIR compliance for health record exchange. Its primary commercial purpose is to extend primary and specialty care access while reducing facility overhead and patient travel burden. Video consultations occupy the largest revenue pool due to reimbursement parity with in-person visits across major markets, while AI-based solutions represent the fastest-expanding technology segment as automated triage and clinical decision support reduce physician time per encounter. Mobile applications capture disproportionate volume in emerging markets where smartphone penetration exceeds fixed broadband availability.
FDA oversight of Software as a Medical Device (SaMD) and HIPAA security rule enforcement by the Office for Civil Rights shape platform validation requirements and data architecture in the United States. India's Ministry of Health telemedicine practice guidelines and the Digital Information Security in Healthcare Act framework govern cross-border data flows and prescriber verification standards. Stakeholders must monitor evolving state-level licensure reciprocity agreements and AI diagnostic liability rulings that will determine scalable operating models.
Market Dynamics
Cloud-native microservices architecture is fragmenting the traditional monolithic telemedicine stack into interoperable, API-driven components, forcing vendors to rebuild data pipelines around HL7 FHIR standards and real-time interoperability.
Growth Catalysts
- HIPAA Security Rule enforcement:The Office for Civil Rights mandates encryption standards that validate enterprise procurement decisions, accelerating platform upgrades among hospital systems seeking compliance certainty.
- Chronic disease management protocols:Medicare reimbursement parity for remote patient monitoring creates durable revenue streams for platforms serving elderly populations with diabetes and cardiovascular conditions.
- Smartphone-first infrastructure:Mobile penetration exceeding fixed broadband in India and Brazil drives asynchronous consultation volume through localized payment integrations.
Market Restraints
- State-level licensure fragmentation:Absence of interstate reciprocity agreements forces physicians to maintain multiple licenses, inflating operational overhead for multi-state platforms.
- Cybersecurity insurance cost escalation:Ransomware targeting health records has doubled premiums for telemedicine operators, compressing margins in competitive employer contract bidding.
- Diagnostic liability uncertainty:Courts have not established clear standards for AI-assisted misdiagnosis, chilling investment in automated triage algorithms.
Strategic Opportunities
- Rural primary care deserts:Federally Qualified Health Centers in the United States seek turnkey telemedicine partnerships to meet access mandates without capital-intensive facility construction.
- AI-physician workflow convergence:Natural language processing automating clinical documentation reduces encounter time, enabling volume scaling without proportional headcount expansion.
- Digital pharmacy integration:Direct-to-patient medication fulfillment through e-prescription networks captures pharmacy benefit margin and improves adherence tracking.
Industry Challenges
- HL7 FHIR implementation talent scarcity:Health informatics specialists capable of mapping legacy EHR schemas to modern interoperability standards command premium compensation, constraining development velocity.
- Multi-jurisdiction data residency compliance:India's Digital Information Security in Healthcare Act and state-level privacy laws require fragmented server architectures, complicating unified platform operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Doctor Consultation Market |
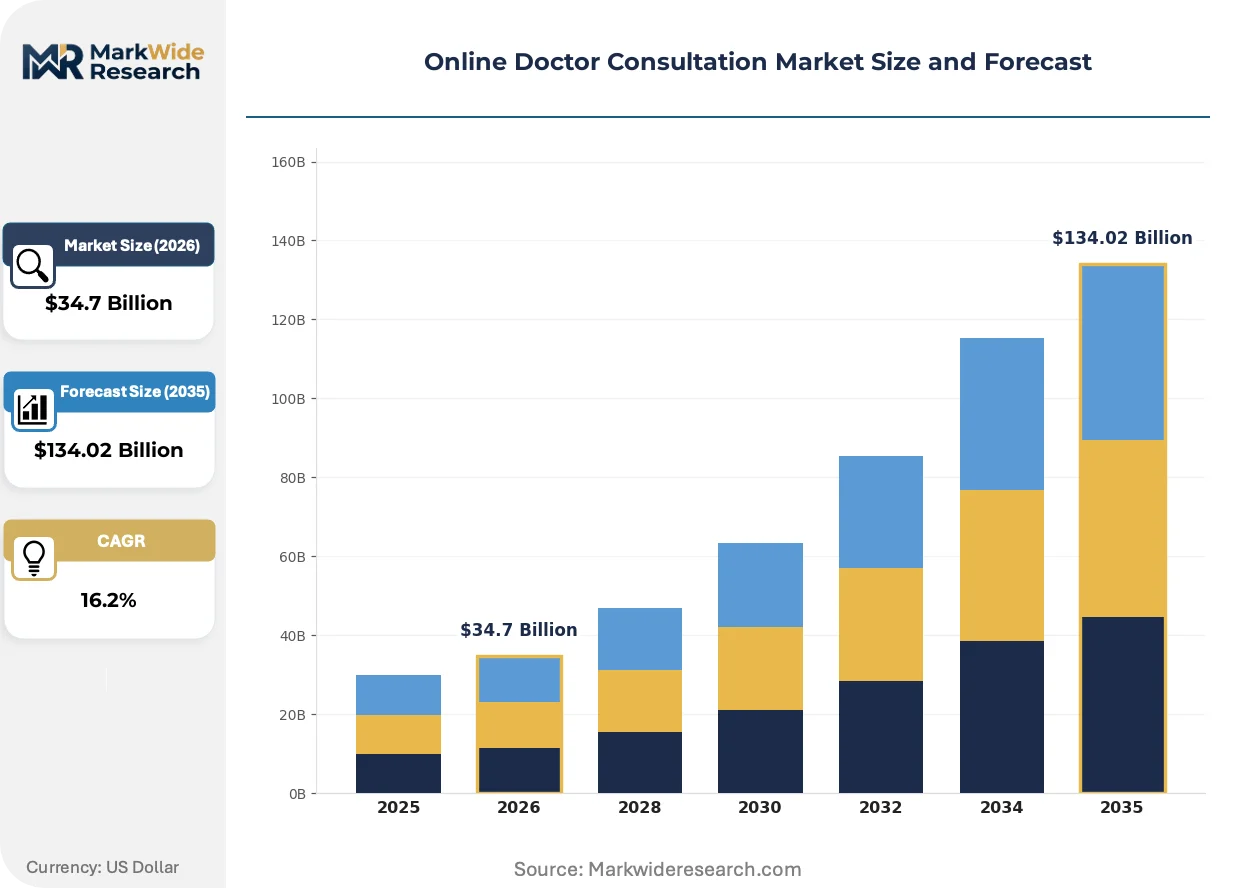
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $134.02 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Consultations, Chat Consultations, Email Consultations, Mobile App Consultations End User: Individuals, Corporates, Insurance Providers, Healthcare Systems Technology: Telemedicine Platforms, Mobile Applications, Wearable Devices, AI-Based Solutions Delivery Mode: On-Demand Consultations, Scheduled Consultations, Integrated Care Programs, Referral Services |
| Companies Covered | Practo, Doxy.me, Teladoc Health, Updox, HealthTap, Amwell, Sesame Care, PlushCare, Doctor on Demand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Doctor Consultation Market Strategic Shifts
Distributed clinical computing models are collapsing the distinction between synchronous video encounters and asynchronous diagnostic workflows, redefining where and how care delivery occurs.
Edge computing infrastructure is virtualizing the locus of clinical data processing. Hospital systems and ambulatory networks are deploying localized inference engines to reduce latency for real-time diagnostic imaging and vital sign streaming. This architecture shift is virtualizing the traditional data center dependency, enabling point-of-care decision support without persistent cloud connectivity.
The EU AI Act's risk classification framework for medical decision support systems is forcing platform developers to restructure algorithm validation protocols. High-risk diagnostic applications now require conformity assessment by notified bodies before CE marking, extending commercialization timelines. European health systems are responding by prioritizing lower-risk administrative automation while awaiting regulatory clarity on clinical AI deployment.
Employer-sponsored health benefits are consolidating vendor relationships around integrated care navigation platforms. Large self-insured employers are replacing point-solution contracts with single-vendor arrangements spanning telemedicine, behavioral health, and chronic condition coaching. This concentration is most pronounced among Fortune 500 manufacturers with unionized workforces seeking to simplify benefits administration and reduce employee confusion.
Online Doctor Consultation Market Segmentation
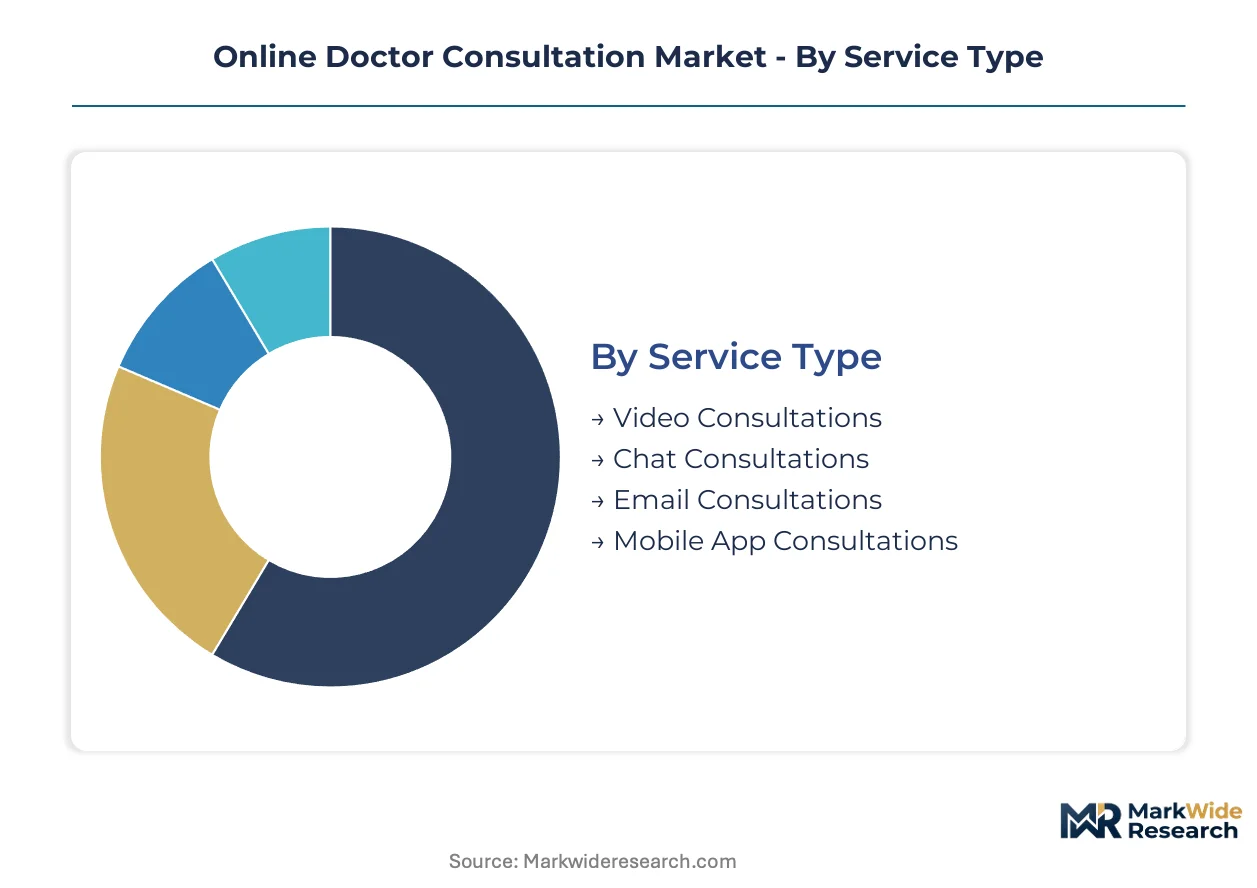
Segmentation in online doctor consultation reveals how reimbursement parity, infrastructure constraints, and clinical workflow requirements fragment revenue pools across interaction modes and customer types. Platform architecture and go-to-market strategy diverge sharply across these dimensions.
Service Type:
After-sales service intensity varies dramatically across consultation formats, with video encounters requiring real-time technical support and asynchronous channels demanding persistent record management.
- Video Consultations:Synchronous encounters over encrypted channels demand bandwidth above 1 Mbps and HL7 FHIR-compliant health record exchange. Medicare reimbursement parity with in-person visits in the United States drives hospital system procurement, though rural broadband gaps constrain deployment.
- Chat Consultations:Text-based asynchronous exchanges through secure messaging protocols enable triage automation and pharmacy integration. India and Brazil show concentrated volume where smartphone penetration exceeds fixed broadband availability and localized payment systems reduce friction.
- Email Consultations:Store-and-forward clinical correspondence suited for non-urgent dermatology and radiology second opinions.
- Mobile App Consultations:Native application interfaces capturing disproportionate emerging market volume through integrated scheduling and prescription fulfillment.
Video Consultations holds the largest share; momentum sits with Mobile App Consultations.
End User:
Cost tier stratification separates enterprise contracts with dedicated account management from individual subscriptions with self-service onboarding.
- Individuals:Direct-to-consumer subscriptions and pay-per-visit arrangements. Price sensitivity concentrates demand in basic chat tiers, though chronic disease patients show willingness to pay premium rates for continuous care relationships.
- Corporates:Employer-sponsored health benefits consolidating around integrated care navigation platforms. Fortune 500 manufacturers with unionized workforces favor single-vendor arrangements spanning telemedicine, behavioral health, and chronic condition coaching to simplify benefits administration.
- Insurance Providers:Payers embedding consultation access into policy benefits to reduce emergency department utilization.
- Healthcare Systems:Hospitals and Federally Qualified Health Centers deploying turnkey partnerships to meet access mandates without capital-intensive facility construction.
Healthcare Systems dominates procurement volume; Corporates shows the steepest expansion trajectory as employer benefit consolidation accelerates.
Technology:
Application maturity separates established telemedicine infrastructure from experimental AI deployment facing diagnostic liability uncertainty.
- Telemedicine Platforms:Cloud-native microservices architecture fragmenting traditional monolithic stacks into interoperable, API-driven components. HL7 FHIR implementation talent scarcity constrains development velocity as health informatics specialists command premium compensation.
- Mobile Applications:Smartphone-first interfaces dominating India and Brazil where asynchronous consultation volume flows through localized payment integrations.
- Wearable Devices:Continuous vital sign streaming enabling remote patient monitoring reimbursement under Medicare chronic disease management protocols.
- AI-Based Solutions:Natural language processing automating clinical documentation and triage algorithms. FDA oversight of Software as a Medical Device and unclear malpractice standards for AI-assisted misdiagnosis chill investment despite encounter time reduction potential.
Telemedicine Platforms anchors current infrastructure spending; AI-Based Solutions is gaining share fastest as regulatory frameworks crystallize.
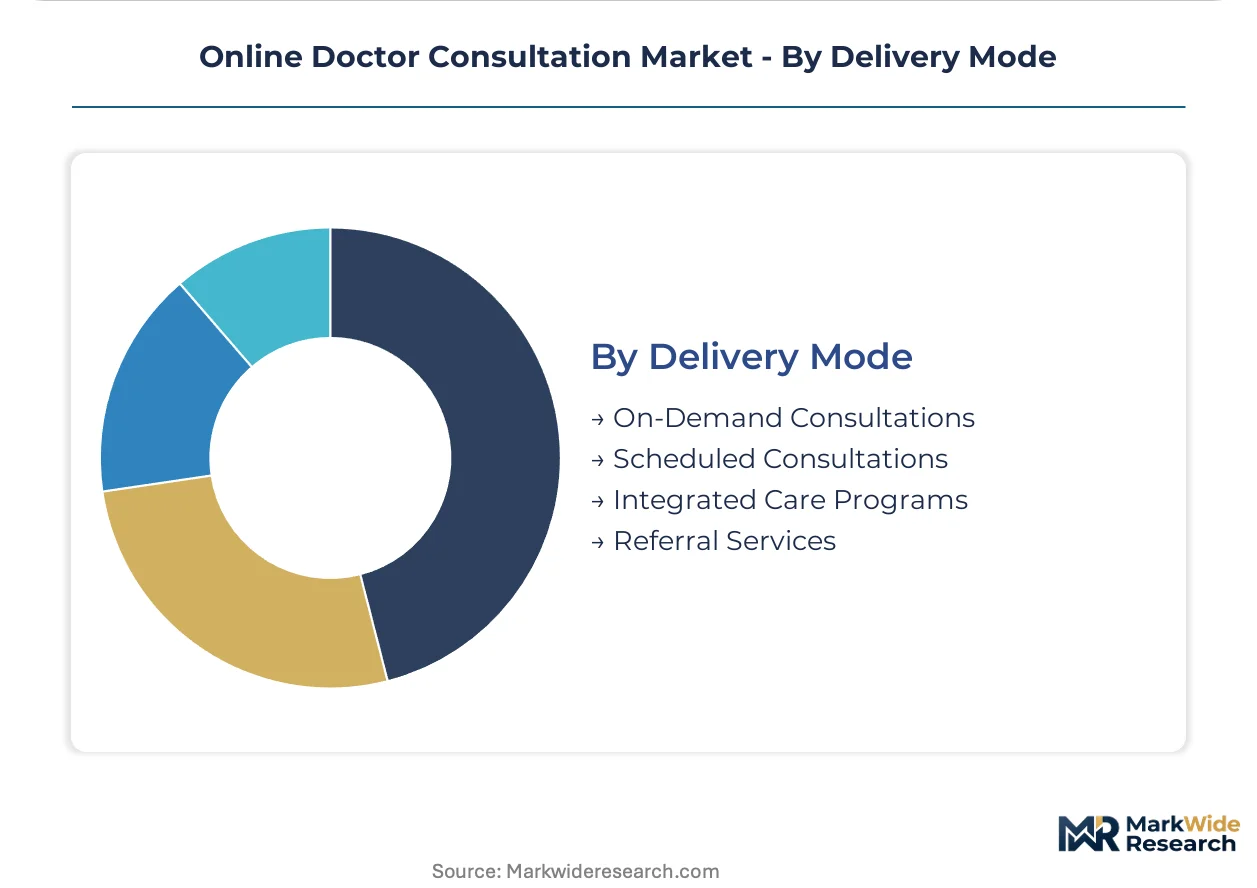
Delivery Mode:
Volume concentration distinguishes episodic on-demand encounters from recurring revenue embedded in longitudinal care programs.
- On-Demand Consultations:Immediate access scheduling for acute symptom triage and urgent medication refills. Cybersecurity insurance cost escalation from ransomware targeting health records compresses margins in competitive employer contract bidding.
- Scheduled Consultations:Appointment-based specialty visits replicating traditional clinic workflows for dermatology, psychiatry, and chronic disease follow-up.
- Integrated Care Programs:Bundled telemedicine, remote monitoring, and coaching for diabetes and cardiovascular conditions. Medicare reimbursement parity creates durable revenue streams serving elderly populations.
- Referral Services:Platform-mediated handoffs to in-person specialty and surgical care capturing navigation fees.
Scheduled Consultations maintains the largest patient volume; Integrated Care Programs climbs fastest as value-based payment models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports telemedicine platform architecture and physician network management expertise to Southeast Asian and African markets seeking smartphone-first healthcare delivery models. Brazilian operators license compliance frameworks to Portuguese-speaking African nations. The United States channels enterprise-grade security protocols and reimbursement infrastructure to Canadian and Australian hospital systems.
United States
Employer-sponsored benefit consolidation and Medicare reimbursement parity for remote patient monitoring drive procurement volume among Fortune 500 manufacturers and Federally Qualified Health Centers. HIPAA Security Rule enforcement by the Office for Civil Rights mandates encryption standards that validate enterprise procurement decisions. The Dallas-Fort Worth metroplex anchors several hospital system telemedicine command centers processing multi-state consultation networks.
India
Smartphone penetration exceeding fixed broadband availability concentrates asynchronous consultation volume through localized payment integrations and pharmacy fulfillment networks. The Ministry of Health's telemedicine practice guidelines and Digital Information Security in Healthcare Act govern cross-border data flows and prescriber verification standards. Bengaluru's health technology cluster houses engineering operations for multiple platforms serving South Asian and Middle Eastern markets.
Brazil
Mobile-first infrastructure and localized payment systems reduce friction for primary care access in urban peripheries and northern interior states. ANVISA oversight of Software as a Medical Device and state-level privacy laws shape platform validation requirements for diagnostic algorithms. São Paulo's health technology corridor concentrates engineering talent and physician network operations serving Portuguese-speaking markets across Latin America and Africa.
Germany
EU AI Act risk classification frameworks for medical decision support systems force restructuring of algorithm validation protocols before CE marking. The Digital Healthcare Act reimbursement pathways for video consultations drive hospital system procurement of integrated care navigation platforms. Berlin's health informatics cluster specializes in HL7 FHIR implementation services for European hospital networks modernizing legacy EHR architectures.
United Kingdom
NHS England's integrated care board procurement frameworks consolidate vendor relationships around single-platform arrangements spanning telemedicine and chronic condition management. MHRA oversight of Software as a Medical Device and GDPR health data processing requirements shape data residency architectures. London's health technology district anchors operations for platforms serving NHS contracts and private insurance channels across Commonwealth markets.
Online Doctor Consultation Market Competitive Environment
Channel-controlling players compete with product-specialist players across employer, payer, and health system procurement channels. The market structure shows moderate consolidation around enterprise contract anchors with persistent fragmentation in direct-to-consumer subscription tiers. Two strategic archetypes dominate: integrated care navigation platforms bundling multiple service lines, and point-solution specialists optimizing single-modality encounter efficiency. Competitive moves concentrate on strategic partnerships with pharmacy benefit managers and geographic expansion through regulatory licensing rather than vertical integration.
Within the integrated platform tier, Teladoc Health and Amwell occupy positions exemplifying enterprise channel control through employer and health system relationships. Practo anchors the South Asian market archetype with localized payment and pharmacy network integration. These three entities represent distinct geographic and business model specializations rather than direct overlapping competition.
| Leading Market Players |
|---|
| Practo |
| Doxy.me |
| Teladoc Health |
| Updox |
| HealthTap |
| Amwell |
| Sesame Care |
| PlushCare |
| Doctor on Demand |
| Others |
Value Chain & Pricing Dynamics
Bengaluru's health technology engineering cluster anchors cloud-native platform development capacity, concentrating specialized HL7 FHIR talent scarcity that amplifies downstream pricing power for compliant telemedicine infrastructure vendors serving hospital systems and enterprise employers.
Pricing Analysis
Cost-plus contracts with Medicare reimbursement rate indexation dominate enterprise procurement between hospital systems and integrated platform vendors. Three-tier pricing structure across enterprise, mid-market, and individual subscription levels separates dedicated account management from self-service onboarding tiers. Pricing pressure stems from cybersecurity insurance premium escalation compressing margins in competitive employer contract bidding. Individual direct-to-consumer subscribers exhibit highest price sensitivity, while Fortune 500 manufacturers with unionized workforces demonstrate lowest sensitivity due to benefits administration simplification priorities.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk for edge computing hardware and semiconductor components essential to localized clinical inference engines. Component sourcing concentrates in Taiwan, South Korea, and China for server-grade processors and encryption modules. Raw material dependencies span gallium nitride for power efficiency, specialized optical sensors for remote monitoring peripherals, and rare earth elements for magnetic components in wearable devices. Distribution runs through cloud service provider marketplaces and direct OEM relationships with hospital system procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Online doctor consultation represents a high-growth disruption propelled by Medicare reimbursement parity for remote patient monitoring, a regulatory inflection that restructured chronic disease management economics and hospital system procurement priorities.
For Market Incumbents: Harden enterprise channel control through exclusive pharmacy benefit manager partnerships that lock in formulary integration and medication fulfillment revenue streams. Deepen defensive moats by acquiring HL7 FHIR implementation specialists to accelerate legacy EHR interoperability timelines before talent scarcity intensifies. Prioritize HIPAA Security Rule pre-certification investments to validate procurement decisions among risk-averse hospital systems.
For New Entrants and Emerging Players: Rural primary care deserts in the United States present the most penetrable white-space target, where Federally Qualified Health Centers seek turnkey telemedicine partnerships without capital-intensive facility construction. Brazil's northern interior states and India's tier-2 cities offer secondary expansion corridors with smartphone-first infrastructure and localized payment integration requirements. Pursue white-label platform licensing to established regional pharmacy chains as the fastest go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-physician workflow convergence specialists with regulatory pre-clearance momentum over pure-play video infrastructure vendors facing commoditization. Long-term viability across the projection horizon rests on platforms capturing integrated care program revenue under value-based payment models rather than episodic consultation fees. Monitor FDA Software as a Medical Device enforcement patterns and state-level licensure reciprocity agreements as critical inflection indicators for scalable operating model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR Implementation Partnership | Accelerates hospital system EHR interoperability timelines and reduces talent scarcity constraints. |
| Pharmacy Benefit Manager Integration | Captures medication adherence data and secures formulary placement for chronic disease protocols. |
| Medicare Reimbursement Strategy | Validates remote patient monitoring claims under chronic disease management billing codes. |
| Edge Computing Infrastructure Deployment | Reduces diagnostic imaging latency for rural broadband-constrained consultation networks. |
| EU AI Act Conformity Assessment | Enables CE marking for clinical decision support algorithms in European health system procurement. |
Study Parameters
Operator-level perspectives from telemedicine platform executives, hospital purchasing committee chairs, biomedical informatics directors, and pharmacy benefit manager contracting specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FDA Software as a Medical Device filings, CMS Medicare reimbursement databases, hospital GPO contract repositories, and hyperscaler healthcare cloud capex disclosures. Bottom-up encounter volume modeling and top-down enterprise contract value triangulation calibrated market sizing across service type and end user segments.
Scenario-bracketing framed the analytical approach across the projection horizon, with baseline, accelerated adoption, and regulatory constraint pathways testing sensitivity to interstate licensure reciprocity timing and AI diagnostic liability rulings. Segmentation dimensions modeled encompassed consultation modality, end user archetype, technology deployment pattern, and geographic regulatory cluster. CAGRs derived from encounter volume elasticity to reimbursement parity expansion and smartphone penetration thresholds. Industry-specific forecast inputs included Medicare remote patient monitoring billing code utilization rates and HL7 FHIR implementation pipeline data from health system modernization disclosures.
Practitioners should monitor state-level licensure reciprocity agreement momentum, AI-assisted misdiagnosis liability precedent, and cybersecurity insurance market capacity for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
North America Telemedicine Market
Telemedicine
Stroke Telemedicine Services Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
GCC Telemedicine Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Telemedicine Service Market
Telemedicine
Telepathology Service Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Tele-Care Market
Telemedicine
Telehealth Services Market
Telemedicine
Telemedicine Cart Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Global Telehealth Market