
 Japan Concrete Conditioner Market | 2026-2036
Japan Concrete Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Concrete Conditioner Market Insights
JIS A 6204 certification for concrete admixtures is redrawing competitive boundaries among domestic suppliers. BASF Japan Ltd. leverages its technical service network to sustain specification relationships with major general contractors. Sika AG anchors its position through localized manufacturing and direct technical support to infrastructure projects. MAPEI Japan Ltd. competes via specialized repair-system bundling that integrates conditioners with complementary products.
Concrete conditioners comprise chemical formulations—typically silicate-based densifiers, lithium compounds, or acrylic resins—applied to hardened concrete surfaces to reduce porosity, increase abrasion resistance, and extend service life in high-traffic industrial environments. The treatment penetrates capillary structures to form insoluble calcium silicate hydrates, creating a permanent bond that eliminates dusting and eases maintenance cycles. Liquid conditioners dominate specification-driven commercial projects where applicator certification and warranty terms carry weight, while powder conditioners serve cost-sensitive repair works where on-site mixing flexibility matters. Decorative finishes represent the fastest-growing application segment as retail and hospitality developers prioritize aesthetic concrete surfaces.
METI's energy efficiency standards for commercial buildings and JIS quality benchmarks shape product development priorities, pushing manufacturers toward low-VOC formulations and extended durability claims. The Ministry of Land, Infrastructure, Transport and Tourism (MLIT) maintenance protocols for public infrastructure create recurring demand through scheduled repair cycles. Stakeholders must monitor how upcoming revisions to Japan's Building Standards Act affect material approval pathways and specification timelines.
Market Dynamics
METI's tightening JIS A 6204 certification requirements are compressing supplier margins while elevating technical barriers, forcing domestic formulators to invest in low-VOC R&D or exit specification-driven commercial segments entirely.
Growth Catalysts
- Industrial Flooring Modernization:Japanese automotive and logistics facilities are specifying densifier-treated concrete to withstand heavy forklift traffic and reduce maintenance downtime in high-throughput distribution centers.
- JIS A 6204 Compliance Mandate:The revised standard's stricter performance benchmarks for abrasion resistance and chloride permeability are disqualifying uncertified imports from public infrastructure tenders.
- Greater Tokyo Commercial Buildout:Kanto region developers are integrating decorative concrete finishes into retail and hospitality projects, creating specification pull for lithium-silicate conditioners with aesthetic compatibility.
Market Restraints
- Petrochemical Input Volatility:Acrylic resin and silicate precursor costs fluctuate with naphtha cracking margins, compressing formulator margins on fixed-price municipal contracts.
- Applicator Skill Concentration:Certified installation crews cluster in Osaka and Nagoya, creating bottlenecks for rural infrastructure projects requiring warranty-backed application.
- Epoxy Coating Substitution:Thin-film epoxy systems offer faster cure times and color flexibility, displacing conditioners in time-sensitive warehouse renovations.
Strategic Opportunities
- Kyushu Industrial Corridor:Semiconductor fabrication plant construction around Kumamoto is generating demand for ultra-clean, dust-free concrete surfaces in cleanroom-adjacent facilities.
- MLIT Scheduled Maintenance Cycles:The Ministry's ten-year bridge and tunnel rehabilitation protocols create recurring, predictable demand for repair-grade powder conditioners.
- Digital Specification Platforms:General contractors are migrating material selection to centralized procurement portals, enabling direct technical engagement between manufacturers and project engineers.
Industry Challenges
- JIS Certification Timeline Compression:Revised testing protocols for low-VOC formulations extend approval cycles by eight to twelve months, delaying product launches.
- Legacy Concrete Assessment Complexity:Conditioner performance depends on substrate moisture content and existing contamination, requiring specialized diagnostic capabilities that smaller applicators lack.
- Cross-Supplier Warranty Coordination:Bundled repair systems integrating conditioners with complementary products create liability fragmentation when failures occur.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Concrete Conditioner Market |
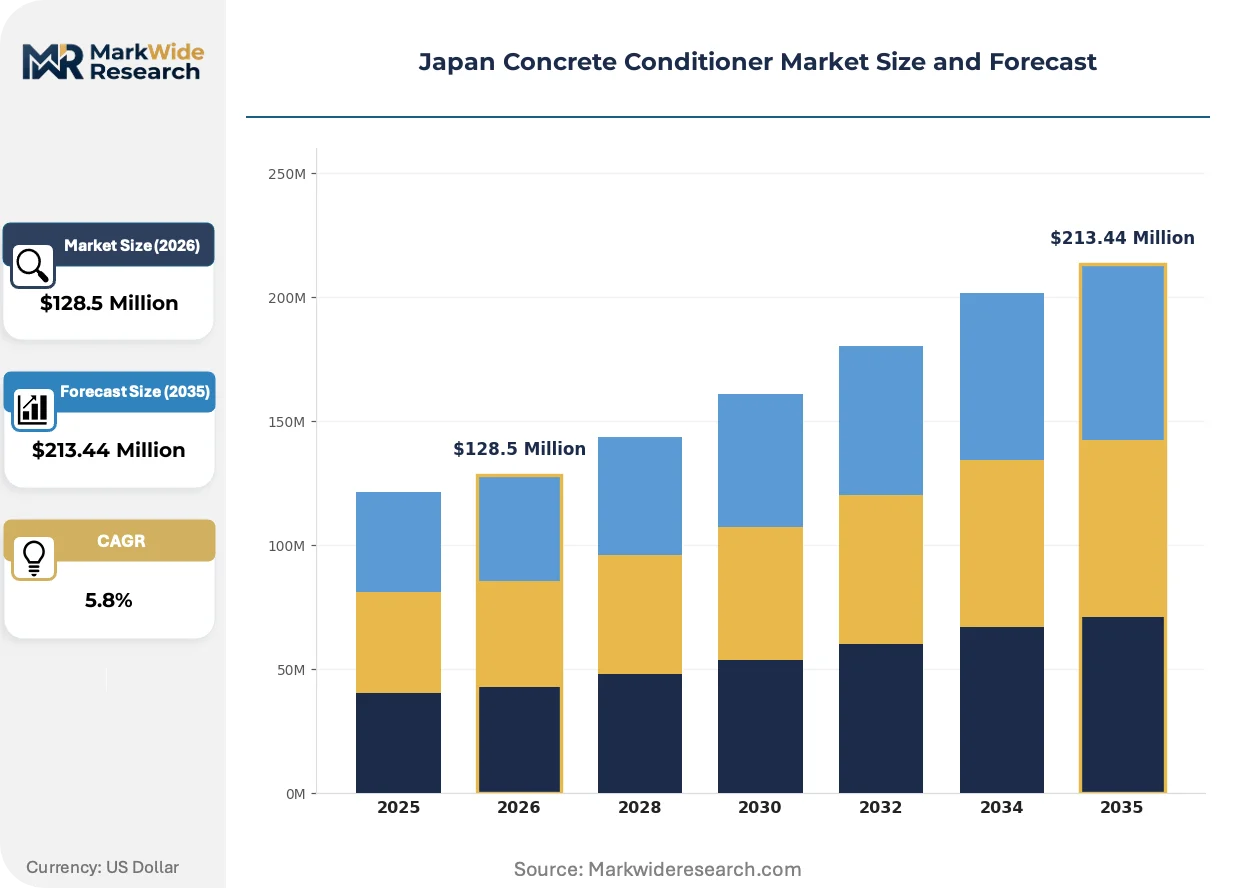
| Market Size in 2026 | $128.5 Million |
| Market Size in 2035 | $213.44 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Treatments, Additives, Liquid Conditioners, Powder Conditioners End User: Construction Companies, Contractors, DIY Enthusiasts, Homeowners Application: Industrial Flooring, Pavements, Repair Works, Decorative Finishes Distribution Channel: Online Sales, Retail Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | BASF Japan Ltd., PPG Industries, MAPEI Japan Ltd., The Sherwin-Williams Company, 3M Company, Sika AG, Nippon Paint Holdings Co., Mapei SpA, Fosroc International Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Concrete Conditioner Market Trends and Innovations
Formulation chemistry and application methodology are converging around sustainability mandates and precision diagnostics, reshaping how suppliers demonstrate value beyond basic surface hardening.
Nano-scale lithium silicate dispersions are penetrating deeper into concrete capillaries than conventional sodium or potassium formulations, achieving permanent densification with reduced material volume. Pharmaceutical cleanroom contractors in Saitama Prefecture are specifying these advanced chemistries for contamination-sensitive environments. The technology is miniaturizing application equipment requirements, enabling handheld sprayer deployment in confined mechanical rooms.
METI's 2024 amendments to the Act on the Rational Use of Energy mandate low-VOC content thresholds for commercial building materials, directly affecting conditioner formulation specifications. Manufacturers must reformulate solvent-based acrylic carriers or forfeit eligibility for government-subsidized retrofit projects. Prefectural housing authorities in Kanagawa and Chiba are rejecting non-compliant products from public tender shortlists.
Asset owners are unbundling material procurement from application services, engaging conditioners directly through distributor channels rather than general contractor markups. This disintermediation compresses distributor margins while demanding enhanced technical support capabilities. Industrial facility managers in Aichi Prefecture's automotive belt are driving this shift, leveraging established relationships with maintenance supply houses.
Japan Concrete Conditioner Market Segmentation
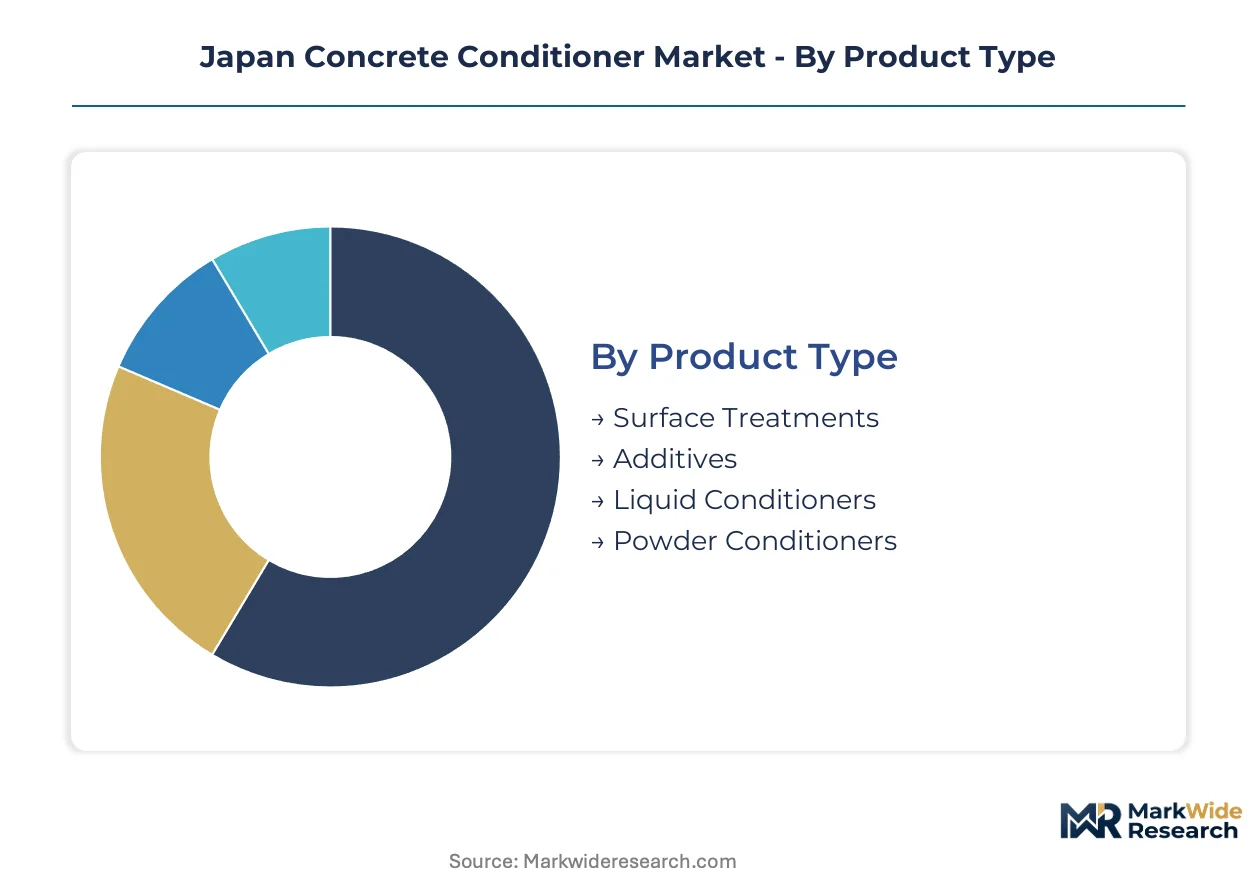
Channel configuration determines specification power in Japan's concrete conditioner trade. Product chemistry, end-user procurement sophistication, and application requirements each reshape how formulations reach concrete surfaces across industrial and commercial projects.
Product Type:
Liquid conditioners and powder variants follow divergent paths to site—specification-driven commercial projects favor pre-certified liquids through applicator networks, while repair-grade powders move through distributor channels serving cost-sensitive maintenance crews.
- Liquid Conditioners:Silicate-based densifiers and lithium compounds penetrate capillary structures to form insoluble calcium silicate hydrates, creating permanent bonds that eliminate dusting. Greater Tokyo commercial developers specify these for warranty-backed industrial flooring where applicator certification carries contractual weight.
- Powder Conditioners:Dry-blend formulations require on-site mixing with water or carriers, offering flexibility for substrate condition assessment. Kansai region repair contractors favor these for MLIT-scheduled bridge rehabilitation where moisture content varies and rapid mobilization matters.
- Surface Treatments:Topical sealers and film-forming coatings provide immediate protection without deep penetration, serving decorative concrete applications in retail and hospitality where aesthetic finish compatibility dominates selection.
- Additives:Integral admixtures mixed during batching modify fresh concrete properties, flowing through ready-mix supplier channels to large infrastructure projects requiring uniform distribution throughout the slab.
Liquid conditioners dominate specification-driven revenue. Powder conditioners are where volume expansion concentrates in maintenance and repair cycles.
End User:
Procurement sophistication stratifies sharply—general contractors command technical specification authority, while fragmented downstream users prioritize availability and application support over formulation chemistry.
- Construction Companies:Taisei Corporation and Obayashi Corporation maintain approved product lists with JIS A 6204 certification requirements, directing conditioner selection through centralized procurement portals that compress distributor margins.
- Contractors:Specialized flooring applicators in Osaka and Nagoya clusters control certified installation capacity, creating bottlenecks for rural infrastructure projects requiring warranty-backed application and moisture-content diagnostics.
- DIY Enthusiasts:Small-scale residential users purchase through retail channels for garage and patio treatments, with limited technical guidance increasing failure rates and reputational risk for manufacturers.
- Homeowners:Individual property owners engage primarily through maintenance supply houses for decorative concrete restoration, representing price-sensitive demand with minimal specification influence.
Construction companies anchor premium formulation demand. Contractors represent the operational constraint on market expansion.
Application:
Performance requirements and aesthetic priorities diverge across use cases, with industrial functionality commanding premium chemistry while decorative applications drive formulation innovation.
- Industrial Flooring:Densifier-treated concrete withstands heavy forklift traffic in automotive and logistics facilities across Aichi Prefecture's manufacturing belt, reducing maintenance downtime through abrasion-resistant surfaces.
- Decorative Finishes:Lithium-silicate conditioners with aesthetic compatibility gain specification in Greater Tokyo retail and hospitality projects, climbing the fastest as developers prioritize visual concrete surfaces.
- Repair Works:Powder conditioners serve MLIT bridge and tunnel rehabilitation protocols, with scheduled ten-year maintenance cycles creating recurring demand for substrate-compatible formulations.
- Pavements:Exterior horizontal surfaces exposed to freeze-thaw cycling and deicing salts require chloride-permeability-resistant treatments, with public infrastructure tenders enforcing JIS performance benchmarks.
Industrial flooring holds the largest installed base. Decorative finishes are where specification innovation concentrates.
Distribution Channel:
Channel power is shifting as asset owners disintermediate general contractor markups, compressing traditional distributor roles while elevating technical support requirements.
- Direct Sales:BASF Japan and Sika AG maintain technical service networks for specification relationships with major general contractors, enabling direct engineer engagement on complex commercial projects.
- Wholesale Distributors:Industrial supply houses in Aichi Prefecture serve automotive facility managers driving the unbundling trend, demanding enhanced diagnostic capabilities alongside material delivery.
- Online Sales:Digital procurement portals are emerging for standardized product lines, though specification-driven commercial segments resist migration due to warranty and applicator certification requirements.
- Retail Stores:Home center channels reach DIY enthusiasts and small contractors with limited product ranges, lacking technical support for substrate assessment and failure prevention.
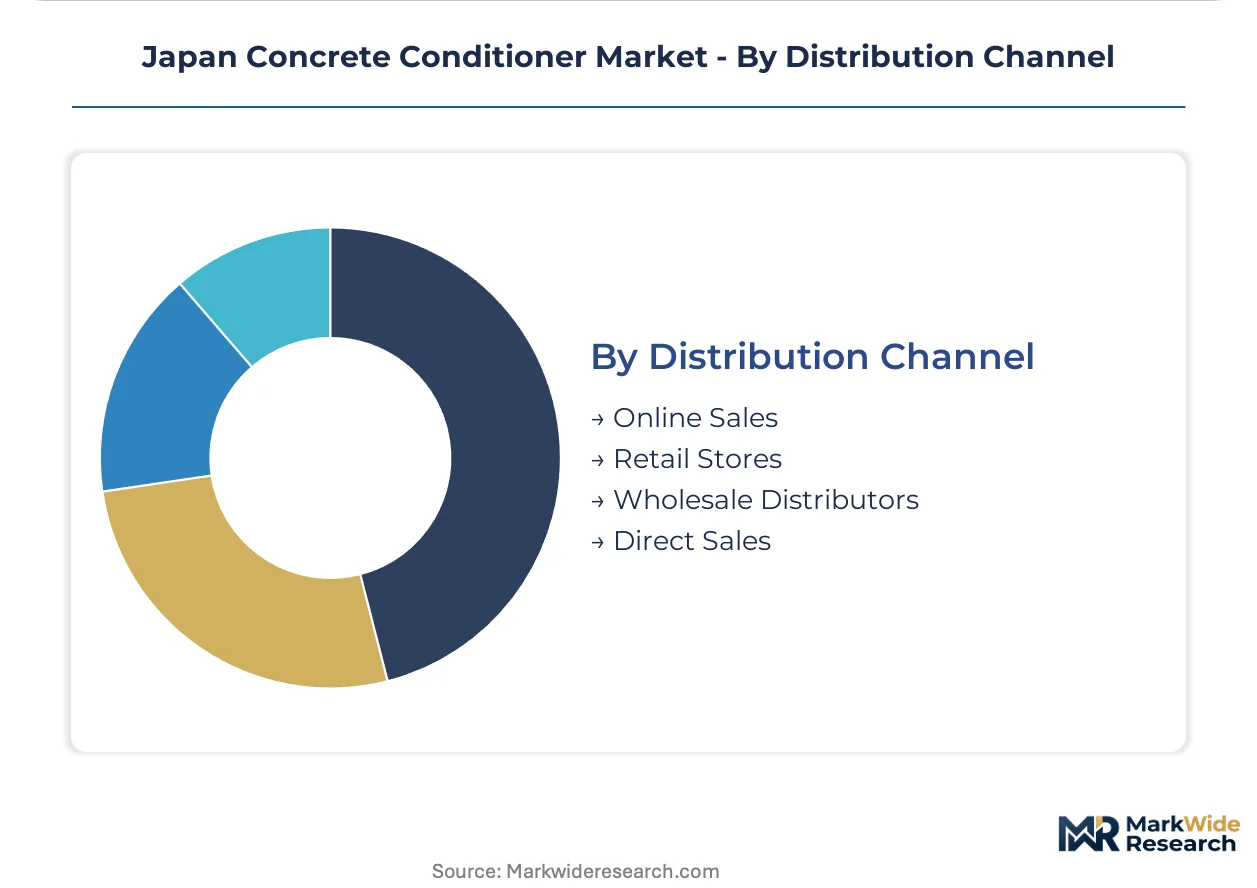
Direct sales dominate specification value. Wholesale distributors are where volume growth concentrates through maintenance supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's building material quality standards and MLIT infrastructure maintenance protocols concentrate concrete conditioner demand across Japan's industrial corridors. Prefectural housing authorities enforce JIS A 6204 compliance, redirecting procurement toward certified domestic suppliers.
Kanto
Greater Tokyo commercial developers specify lithium-silicate conditioners for decorative concrete finishes in retail and hospitality projects. METI's energy efficiency standards mandate low-VOC formulations for government-subsidized retrofits. Yokohama and Saitama pharmaceutical cleanroom contractors are adopting nano-scale lithium silicate dispersions for contamination-sensitive environments.
Kansai
Osaka's certified flooring applicator clusters control warranty-backed installation capacity for industrial projects. JIS A 6204's stricter abrasion resistance benchmarks disqualify uncertified imports from public tenders. Kobe and Kyoto bridge rehabilitation crews favor powder conditioners for MLIT-scheduled maintenance cycles where substrate moisture varies.
Chubu
Aichi Prefecture's automotive manufacturing belt drives densifier-treated concrete demand for heavy forklift traffic facilities. Asset owners here are disintermediating general contractor markups through maintenance supply house relationships. Nagoya's industrial facility managers are unbundling material procurement from application services.
Kyushu
Semiconductor fabrication plant construction around Kumamoto generates demand for ultra-clean, dust-free concrete surfaces in cleanroom-adjacent facilities. MLIT's ten-year bridge rehabilitation protocols create recurring demand for repair-grade formulations. Fukuoka's logistics distribution centers specify hardened concrete to reduce maintenance downtime.
Hokkaido
Freeze-thaw cycling and deicing salt exposure on exterior pavements require chloride-permeability-resistant treatments. JIS performance benchmarks govern public infrastructure tenders for road and airport surfaces. Sapporo's municipal contracts enforce fixed-price terms that compress formulator margins during petrochemical input volatility.
Japan Concrete Conditioner Market Competitive Landscape
Listed leaders compete with private specialists across specification relationships and technical service networks. The market structure tiers between multinational chemical conglomerates with localized manufacturing and domestic formulators with repair-system bundling capabilities. Three archetypes dominate: global admixture specialists, regional coating integrators, and construction chemical pure-plays. Competitive moves center on JIS certification acquisition and direct technical engagement with general contractor procurement portals.
Among the global admixture specialists, BASF Japan Ltd. and Sika AG exemplify the technical service archetype through specification relationships with major general contractors. MAPEI Japan Ltd. occupies a position within the repair-system bundling tier, integrating conditioners with complementary products. These three entities represent how multinational presence combines with localized certification compliance to anchor market positioning.
| Leading Market Players |
|---|
| BASF Japan Ltd. |
| PPG Industries |
| MAPEI Japan Ltd. |
| The Sherwin-Williams Company |
| 3M Company |
| Sika AG |
| Nippon Paint Holdings Co. |
| Mapei SpA |
| Fosroc International Ltd. |
| Others |
Pricing and Supply Chain Analysis
JIS A 6204 certification gates both supplier qualification and price differentiation simultaneously, compressing uncertified imports into discount tiers while elevating domestic formulators with approved product lists. METI's tightening low-VOC thresholds extend R&D timelines, forcing margin absorption or premium positioning on compliant formulations.
Pricing Analysis
Certification level creates the primary spread across the conditioner market, with JIS A 6204-compliant formulations commanding substantial premia over uncertified alternatives in public infrastructure tenders. Three-tier pricing structure separates specification-grade lithium silicates from standard densifiers and economy repair powders. Pricing pressure stems from petrochemical input volatility on acrylic resin carriers, squeezing margins on fixed-price municipal contracts. General contractors show lowest price sensitivity due to warranty transfer requirements, while DIY enthusiasts and small maintenance crews drive volume at the economy tier.
Supply Chain Analysis
Inbound logistics costs through Yokohama and Nagoya ports fluctuate with container availability on Asia-Japan trade lanes, affecting silicate precursor delivery schedules. Manufacturing concentrates in Japan, Germany, and Switzerland, with BASF Japan and Sika AG operating localized production facilities. Raw material dependencies include naphtha-derived acrylic resins, lithium carbonate for advanced silicates, and specialty surfactants from South Korean suppliers. Single-source vulnerability runs through certified applicator networks clustered in Osaka and Nagoya. Distribution runs through direct technical service teams for specification-driven projects and wholesale industrial supply houses for maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through general contractor procurement portals, with Taisei Corporation and Obayashi Corporation centralizing material selection and compressing distributor margins across specification-driven segments.
For Market Incumbents: Compound technical service capabilities with JIS certification maintenance to defend specification relationships against epoxy coating substitution in warehouse renovations. Deepen backward integration into silicate precursor production to buffer petrochemical input volatility. Prioritize low-VOC R&D investment ahead of METI's next amendment cycle to sustain eligibility for government-subsidized retrofit projects. For New Entrants and Emerging Players: Differentiate on substrate diagnostic capabilities for legacy concrete assessment, a capability gap that disqualifies smaller applicators from warranty-backed projects. Target Kyushu's semiconductor fabrication corridor, where ultra-clean surface requirements and limited local applicator presence create penetrable white space. Pursue distributor partnerships with Aichi Prefecture maintenance supply houses serving automotive facility managers driving procurement unbundling. For Investors and Strategic Acquirers: METI's 2024 Act on the Rational Use of Energy amendments reshape the acquisition landscape by devaluing solvent-based formulation assets and elevating low-VOC technology platforms. The viable window extends through the certification transition period, favoring targets with established JIS compliance and direct general contractor relationships. Monitor prefectural housing authority tender rejections as the inflection signal for stranded asset risk in non-compliant product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicate Precursors | Captive supply of lithium carbonate reduces exposure to South Korean import volatility and METI supply chain scrutiny. |
| JIS A 6204 Certification Investment | Approval unlocks public infrastructure tenders where Obayashi Corporation and Taisei Corporation direct specification authority. |
| Digital Specification Platform Partnership | Direct technical engagement with general contractor procurement portals bypasses distributor margin compression. |
| Applicator Network Expansion | Certified installation capacity in rural regions removes bottlenecks for MLIT bridge rehabilitation protocols. |
| Low-VOC Formulation Transition | Compliance preserves eligibility for Kanagawa and Chiba prefectural housing authority subsidized retrofit projects. |
Research Methodology
Operator-level perspectives from concrete flooring applicators, general contractor procurement officers, ready-mix supplier technical directors, and METI regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through JIS certification databases, MLIT infrastructure maintenance protocol documents, and customs trade data on silicate precursor imports. Bottom-up demand modeling from end-use segments triangulated against top-down supply capacity assessments from domestic manufacturing facilities.
Sensitivity analysis framed volume and value outputs across product chemistry tiers, application requirements, and regional procurement sophistication levels throughout the projection horizon. Segmentation dimensions included conditioner formulation type, end-user procurement authority, and distribution channel configuration alongside Japan-specific regulatory compliance tiers. CAGRs derived from historical adoption patterns in industrial flooring modernization and scheduled infrastructure maintenance cycles, with scenario weighting for METI amendment implementation timing and semiconductor fabrication construction momentum in Kyushu.
The analysis sits within stated boundaries; outcomes outside sustained JIS certification timelines and petrochemical input stability would require recalibration. Forecasts reflect documented assumptions on applicator certification expansion rates and general contractor portal adoption curves. Practitioners should keep alternative scenarios live as METI enforcement intensity and epoxy coating cure-time improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
US Geosynthetics Market