
 Dimension Stone Market | 2026-2036
Dimension Stone Market Size, Share, and Industry Trends Forecast 2026-2036
Dimension Stone Market Analysis
Master stonecutter availability is redrawing competitive boundaries across the dimension stone value chain. Polycor Inc. leverages captive quarry assets across North America to secure premium granite and marble feedstock. Levantina and Mineral Associates SA anchors Mediterranean limestone production through integrated extraction and slab fabrication. Aro Granite Industries Ltd. specializes in high-volume tile output from southern Indian quarries, competing on calibrated thickness consistency.
Dimension stone comprises naturally occurring rock masses—granite, marble, limestone, sandstone—extracted in blocks and processed to specified finishes for structural and decorative applications. Granite achieves compressive strengths exceeding 200 MPa, making it suitable for load-bearing cladding and heavy-traffic flooring in transit infrastructure. Marble commands premium positioning in luxury interiors and monuments due to distinctive veining and polish receptivity, while limestone dominates landscaping and heritage restoration for its workability and weathering compatibility. Slab and tile forms capture the bulk of fabrication value, though thin veneer is gaining traction in retrofit applications where structural load limits apply.
EPA quarry emissions guidelines and OSHA silica exposure limits shape extraction economics and worker safety investments across US operations. REACH compliance in Europe restricts certain surface treatment chemistries, redirecting R&D toward water-based sealants and mechanical polishing. ISO 13006 ceramic tile standards extend to stone tile dimensional tolerances, influencing export market access for Indian and Brazilian producers. Stakeholders must weigh capital allocation between automation-driven yield improvements and certification investments that unlock specification-driven projects.
Market Dynamics
Quarry automation and digital templating are decomposing traditional extraction economics, compressing yield loss from 35% to under 12% while redistributing competitive advantage toward capital-intensive operators with captive block reserves.
Growth Catalysts
- Urban infrastructure mandates:China's dual carbon goals and metro expansion programs are pulling premium granite and marble into transit station cladding and public monument contracts.
- REACH surface treatment restrictions:European ECHA compliance deadlines are redirecting specification-driven projects toward water-based sealant portfolios and mechanical polish systems.
- Thin veneer fabrication:Waterjet cutting tolerances now enable 15mm facade panels that retrofit onto load-limited structures without structural reinforcement.
Market Restraints
- Diesel fuel and diamond wire input volatility:Quarry extraction costs swing with energy pricing, squeezing margin on standard-grade limestone and sandstone orders.
- Master stonecutter scarcity:Mediterranean and Indian fabrication clusters face aging workforce pipelines with limited apprenticeship throughput.
- Engineered quartz substitution:Breton-style cast stone captures mid-market kitchen and bath specification with consistent patterning and lower installed cost.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea tourism developments specify premium facade stone at volumes exceeding domestic quarry capacity.
- Heritage restoration incentives:Italy's tax credits for historic building conservation are pulling weathering-compatible limestone into conservation-grade supply chains.
- Blockchain provenance tracking:Immutable chain-of-custody records are unlocking specification in LEED and BREEAM-certified commercial towers.
Industry Challenges
- ISO 13006 certification timelines:Indian and Brazilian exporters face 14-18 month approval cycles for dimensional tolerance compliance in EU specification markets.
- Silica exposure compliance:OSHA respirable crystalline silica limits demand dust suppression capex of $2-4 million per US quarry operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimension Stone Market |
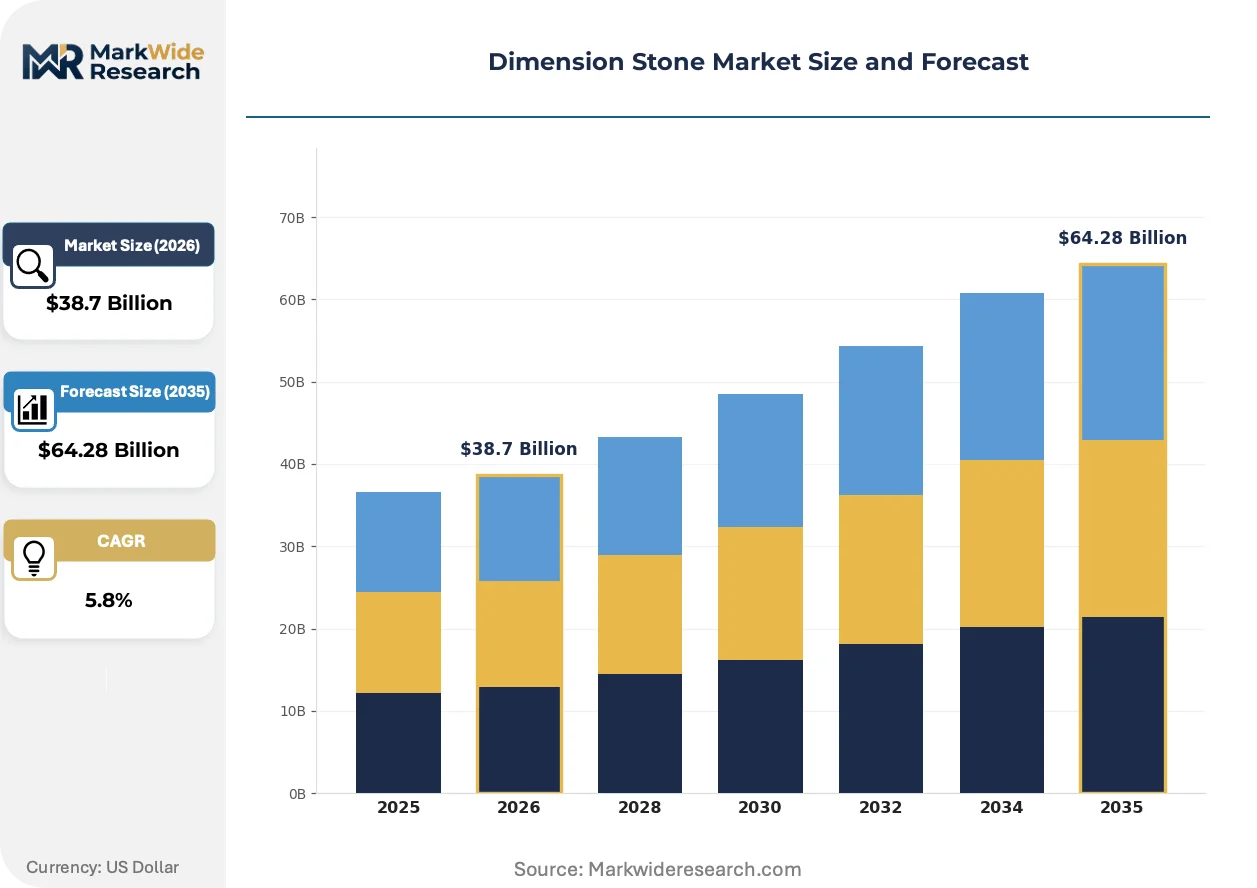
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granite, Marble, Limestone, Sandstone End Use Industry: Construction, Monuments, Interiors, Landscaping Form: Blocks, Slabs, Tiles, Thin Veneer Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Polycor Inc., Levantina and Mineral Associates SA, Artgo Holdings Ltd, Aro Granite Industries Ltd., Avid Marbles and Granites Pvt. Ltd., Caesarstone Ltd., Mohawk Industries Inc, MGT Stone Co., FHL Kiriakidis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimension Stone Market Emerging Trajectories
Digital quarrying workflows and water-based finishing chemistries are converging to reset yield economics and specification access across the value chain.
Waterjet-guided diamond wire sawing is decomposing traditional gang saw economics in granite block processing. Brazilian and Chinese quarry operators deploy these systems to extract 20% more slab surface per cubic meter of extracted block. The technology is compressing capital recovery timelines for mid-scale quarries while eroding the yield advantage previously held by integrated majors with captive gang saw halls.
EPA quarry emissions guidelines finalized in 2024 impose particulate matter monitoring and diesel equipment retrofit mandates on US extraction sites. Surface mining operators in Vermont and Georgia face $500,000-$1.2 million compliance investments per active pit. The regulation most affects dimension stone quarries within 50 miles of non-attainment zones, pushing some operators toward indefinite care and maintenance status.
Architects and facade engineers now specify stone through BIM-integrated material libraries that embed embodied carbon data and chain-of-custody documentation. This procurement pattern displaces traditional cut-sample and quarry-visit qualification workflows. The shift is most visible in London and Singapore commercial tower markets where BREEAM and Green Mark certification gates require granular EPD traceability.
Dimension Stone Market Segmentation

Dimension stone procurement patterns fragment across specification regimes, with facade engineers, conservation architects, and residential developers each imposing distinct certification and dimensional requirements. Segmentation clarity enables suppliers to align quarry output with channel economics and regulatory compliance tiers.
Product Type:
EPA quarry emissions guidelines and OSHA silica exposure limits in the US, REACH surface treatment restrictions in Europe, and China's dual carbon goals each reshape extraction investments and finish chemistry portfolios across stone categories.
- Granite:Igneous rock with compressive strengths exceeding 200 MPa suits load-bearing cladding and heavy-traffic flooring in transit infrastructure. Chinese metro expansion programs and Saudi giga-projects specify premium grades for station facades and monument cores, though diesel fuel and diamond wire input volatility squeezes margin on standard orders.
- Marble:Metamorphic limestone distinguished by distinctive veining and superior polish receptivity commands luxury interior and monument positioning. Italian tax credits for historic building conservation pull weathering-compatible varieties into conservation-grade supply chains, while Breton-style engineered quartz captures mid-market kitchen and bath specification.
- Limestone:Sedimentary carbonate dominates landscaping and heritage restoration for workability and natural weathering compatibility.
- Sandstone:Clastic sedimentary with variable grain binding suits rustic exterior paving and regional architectural vernaculars.
Established volume favors granite; emerging adoption favors marble in LEED and BREEAM-certified commercial towers.
End Use Industry:
Application-specific performance standards and warranty terms stratify procurement channels, with facade engineering firms, cemetery operators, hospitality designers, and municipal parks departments each maintaining distinct supplier qualification protocols.
- Construction:Commercial tower and transit infrastructure specification demands EPD traceability and BIM-integrated material libraries. NEOM and Red Sea tourism developments in Saudi Arabia specify premium facade stone at volumes exceeding domestic quarry capacity, while Indian and Brazilian exporters face 14-18 month ISO 13006 certification timelines for EU dimensional tolerance compliance.
- Interiors:Hospitality and residential specification emphasizes finish consistency and water-based sealant compatibility under REACH deadlines.
- Monuments:Cemetery and memorial markets prioritize freeze-thaw durability and long-term color stability.
- Landscaping:Municipal and commercial exterior hardscaping favors cost-efficient limestone and sandstone with slip-resistant thermal finishes.
Construction absorbs the largest block volumes; interiors generate the steepest expansion trajectory for thin veneer and waterjet-fabricated panels.
Form:
Yield economics and installation labor intensity diverge sharply across form factors, with waterjet cutting tolerances now enabling retrofit applications that gang saw halls cannot address.
- Slabs:Gang saw and wire-sawn plate stock captures the bulk of fabrication value in commercial facade and countertop specification. Brazilian and Chinese operators deploying waterjet-guided diamond wire sawing extract 20% more slab surface per cubic meter of block, compressing capital recovery timelines for mid-scale quarries.
- Thin Veneer:Waterjet cutting tolerances now enable 15mm facade panels that retrofit onto load-limited structures without structural reinforcement, gaining traction in London and Singapore commercial tower markets.
- Blocks:Rough-quarried masses trade to integrated fabricators or export markets for downstream processing.
- Tiles:Calibrated thickness output from southern Indian quarries competes on dimensional consistency for flooring and wall cladding.
Slabs dominate current fabrication throughput; thin veneer climbs the fastest as BIM-embedded embodied carbon data drives retrofit specification.
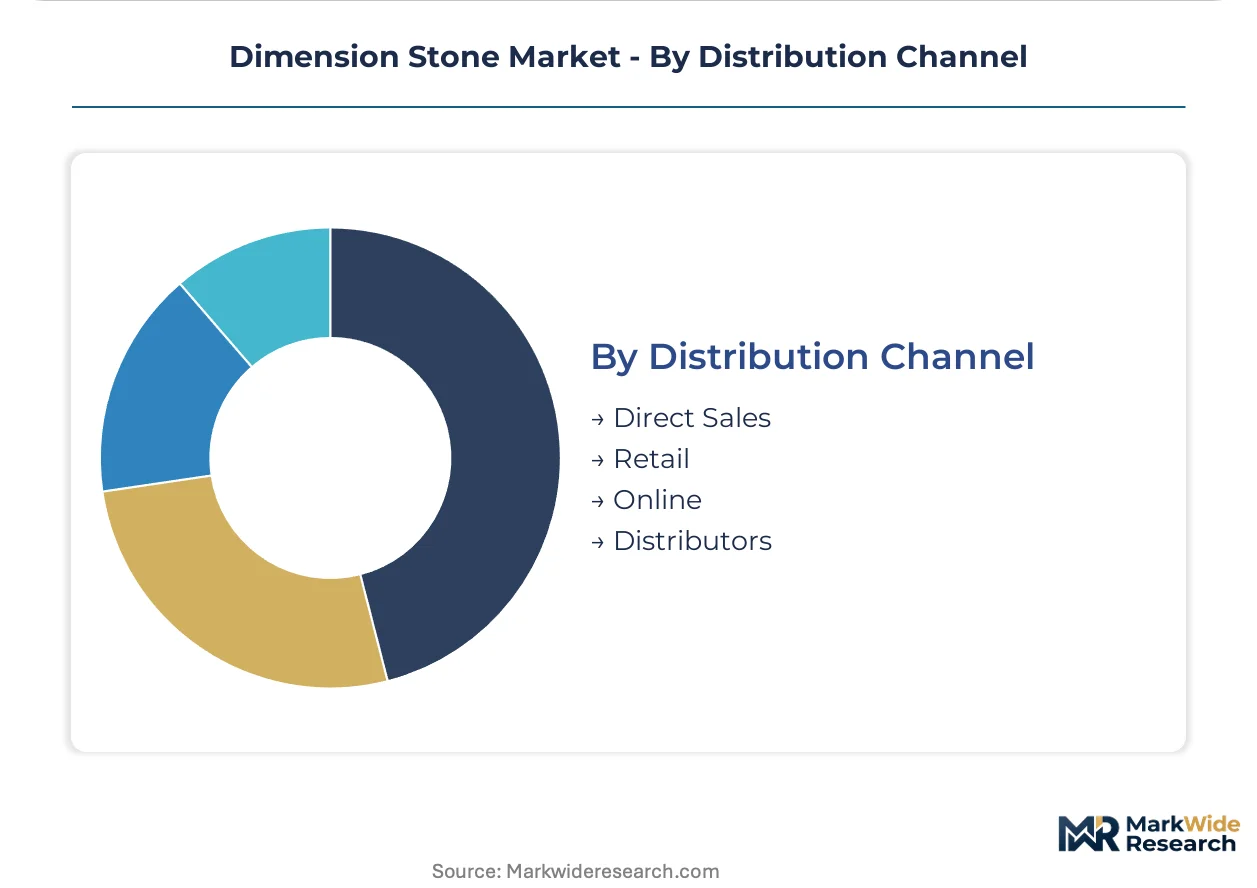
Distribution Channel:
Channel selection determines specification access and working capital intensity, with direct quarry relationships unlocking large-project pricing and inventory commitment terms that retail and digital channels cannot match.
- Direct Sales:Quarry-to-developer relationships dominate giga-project and transit infrastructure procurement, with blockchain provenance tracking unlocking LEED and BREEAM certification gates.
- Distributors:Regional stone yards aggregate inventory breadth for mid-scale commercial and residential contractors.
- Retail:Showroom-based selection persists in residential kitchen and bath replacement markets.
- Online:Digital templating and virtual sample workflows displace traditional cut-sample qualification in specification-driven segments.
Direct sales anchor project-scale volume; online channels gain share fastest among architects and facade engineers specifying through BIM-integrated libraries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys dimension stone primarily for transit infrastructure cladding, while Italy channels output toward heritage conservation and Saudi Arabia absorbs block volumes for giga-project facades. This consumption-mix differential shapes quarry investment patterns and finish chemistry portfolios across major producing regions.
China
Metro expansion programs in Chengdu, Xi'an, and Hangzhou pull premium granite into station cladding and public monument contracts. The country's dual carbon goals impose emissions intensity benchmarks on quarry operations in Fujian and Shandong provinces. Waterjet-guided diamond wire sawing clusters in Xiamen extract 20% more slab surface per cubic meter, compressing capital recovery timelines for mid-scale operators.
Italy
Tax credits for historic building conservation pull weathering-compatible limestone into conservation-grade supply chains for Rome, Florence, and Venice restoration projects. REACH surface treatment restrictions redirect specification toward water-based sealant portfolios and mechanical polish systems. Carrara and Massa-Carrara province quarries anchor Mediterranean marble production through integrated extraction and slab fabrication.
Saudi Arabia
NEOM and Red Sea tourism developments specify premium facade stone at volumes exceeding domestic quarry capacity. The national regulator mandates embodied carbon disclosure for materials in giga-project procurement. Riyadh and Jeddah fabrication yards import rough blocks from Brazil and India for local finishing and installation.
United States
Commercial tower markets in New York, Chicago, and Miami specify stone through BIM-integrated material libraries that embed EPD traceability. EPA quarry emissions guidelines and OSHA silica exposure limits demand dust suppression capex of $2-4 million per active pit. Vermont and Georgia surface mining operators face $500,000-$1.2 million compliance investments, pushing some toward care and maintenance status.
Brazil
Export-oriented granite quarries in Minas Gerais and Espírito Santo supply block stock to Chinese and Saudi fabrication markets. Diesel fuel and diamond wire input volatility squeezes margin on standard-grade orders. Cachoeiro de Itapemirim and Vila Velha processing clusters deploy waterjet-guided systems to erode the yield advantage previously held by integrated majors with captive gang saw halls.
Dimension Stone Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with quarry automation and digital templating redistributing advantage toward capital-intensive operators with captive block reserves. The structure fragments across extraction geography, finish capability, and specification access tiers. Three archetypes dominate: North American integrated quarry-to-fabrication operators, Mediterranean limestone specialists with heritage conservation positioning, and Indian high-volume tile producers competing on calibrated thickness consistency. Competitive moves concentrate on backward integration into captive quarry assets and certification investments that unlock LEED and BREEAM specification gates.
Among North American integrated operators, Polycor Inc. occupies a position exemplifying captive quarry asset leverage across multiple stone categories. Levantina and Mineral Associates SA represents the Mediterranean archetype with integrated extraction and slab fabrication positioning. Aro Granite Industries Ltd. anchors the Indian high-volume tier, with southern Indian quarry operations supporting calibrated thickness output for flooring and wall cladding specification. These three illustrate how geographic origin and structural form shape competitive access to premium project pipelines.
| Leading Market Players |
|---|
| Polycor Inc. |
| Levantina and Mineral Associates SA |
| Artgo Holdings Ltd |
| Aro Granite Industries Ltd. |
| Avid Marbles and Granites Pvt. Ltd. |
| Caesarstone Ltd. |
| Mohawk Industries Inc |
| MGT Stone Co. |
| FHL Kiriakidis Group |
| Others |
Supply Flow & Price Mechanics
ISO 13006 certification timelines simultaneously gate EU market access and stratify price realization across Indian and Brazilian export tiers, compressing margins for uncertified operators while unlocking specification premiums for compliant suppliers. This regulatory filter fuses supply qualification with pricing power, redirecting capital toward certification investments that recover through project-scale contract premiums.
Pricing Analysis
Long-term offtake contracts dominate giga-project procurement in Saudi Arabia, while spot market transactions persist for standard-grade limestone and sandstone orders subject to diesel fuel volatility. Three-tier pricing structure across premium, standard, and economy levels separates LEED-certified facade stone from uncertified block stock and quarry-run material. Cost compression in standard-grade tiers is intensifying because Breton-style engineered quartz captures mid-market kitchen specification. Residential developers exhibit highest price sensitivity; conservation architects and facade engineers demonstrate lowest sensitivity due to specification-lock and warranty requirements.
Supply Chain Analysis
Strategic stockpiling of premium granite and marble blocks characterizes integrated operators in Brazil and India, while just-in-timenventory management prevails among European fabrication yards dependent on Mediterranean limestone extraction. Supply concentrates in China, Brazil, and India for rough block production; Italy and Spain anchor finished slab fabrication. Diamond wire, diesel fuel, and waterjet cutting consumables constitute critical input dependencies. Single-source vulnerability runs through Carrara and Massa-Carrara province quarries for heritage-grade marble. Distribution runs through direct quarry-to-developer relationships for large projects, with regional stone yards aggregating breadth for mid-scale contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among facade engineering firms and giga-project developers with BIM-integrated procurement systems, fragmenting traditional distributor influence. This consolidation among specification gatekeepers elevates certification and provenance documentation to competitive prerequisites.
For Market Incumbents: Secure captive quarry reserves in Minas Gerais and Espírito Santo to defend feedstock position against yield-optimized Chinese competitors deploying waterjet-guided systems. Invest in blockchain provenance tracking to meet BREEAM and LEED certification gates that specification-driven projects now require. Master stonecutter apprenticeship pipelines represent a critical capability lever against aging workforce attrition in Mediterranean and Indian fabrication clusters. For New Entrants and Emerging Players: ISO 13006 fast-track certification unlocks EU specification markets where 14-18 month approval cycles currently block Indian and Brazilian exporters. Target thin veneer fabrication for London and Singapore commercial tower retrofit applications, where 15mm waterjet-cut panels address load-limited structures without structural reinforcement. Lead with BIM-integrated material libraries that embed embodied carbon data, displacing traditional cut-sample qualification workflows among facade engineers. For Investors and Strategic Acquirers: EPA quarry emissions guidelines finalized in 2024 reshape the acquisition landscape toward operators with dust suppression capex already deployed. Five-to-ten year viability favors integrated quarry-to-fabrication operators with captive block reserves and waterjet cutting capability. Acquisition target archetype: mid-scale Brazilian or Indian quarries with unexploited premium grades and compliance investment gaps. Watch for OSHA silica enforcement intensity as inflection indicator for US operator distress and consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Acquisition | Secures premium granite and marble feedstock against yield-optimized competitors in Xiamen clusters. |
| Waterjet Cutting Deployment | Extracts 20 percent more slab surface per cubic meter, compressing capital recovery timelines for mid-scale operators. |
| Blockchain Provenance Implementation | Unlocks LEED and BREEAM certification gates in London and Singapore commercial tower markets. |
| ISO 13006 Certification Investment | Enables EU specification access where dimensional tolerance compliance gates project-scale contracts. |
| Master Stonecutter Apprenticeship Pipeline | Addresses aging workforce attrition that constrains fabrication throughput in Mediterranean and Indian clusters. |
Methodological Framework
The analysis maps granite, marble, limestone, and sandstone extraction and fabrication segments, each validated through quarry operations managers, facade engineering specification leads, and conservation architect procurement officers. Primary interviews with stone yard distribution partners and heritage restoration contractors combined with secondary validation from SEC filings of listed producers, customs and trade flow databases, and EPA enforcement records. Bottom-up quarry capacity modeling and top-down construction spend allocation triangulate volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework models product type, end-use industry, form factor, and regional production hub segmentation. CAGRs derive from regression-adjusted capacity expansion schedules and specification-driven demand elasticity. Waterjet cutting adoption curves and REACH surface treatment compliance timelines constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained urban infrastructure investment levels or abrupt regulatory enforcement shifts would require recalibration. Forecasts reflect assumptions regarding quarry automation diffusion and certification timeline stability. Revision becomes warranted when diesel fuel and diamond wire input volatility crosses thresholds that compress standard-grade operator margins to care and maintenance triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Europe Particle Board Market