
 Asia Pacific Sanitaryware Market | 2026-2036
Asia Pacific Sanitaryware Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sanitaryware Market Insights
WaterSense-equivalent and premium vitreous china grades are reorganizing procurement priorities across the Asia Pacific Sanitaryware Market. TOTO leverages its ceramic glazing R&D intensity to command specification lists in Japan's commercial retrofit segment. RAK Ceramics anchors large-format production across the UAE-India supply corridor, sustaining cost advantages in Gulf re-export markets.
Sanitaryware encompasses ceramic, plastic, metal, and glass fixtures engineered for water delivery, waste removal, and hygiene maintenance in built environments, with vitreous china fired above 1,200°C to achieve non-porous, acid-resistant surfaces suitable for high-frequency institutional use. Toilets and faucets capture the dominant volume positions, while wall-mounted installations are gaining share in premium residential towers across Mumbai and Bangkok where floor-space optimization commands price premiums. Ceramic retains the core material position, though metal and glass variants are carving margin pools in luxury hospitality specifications.
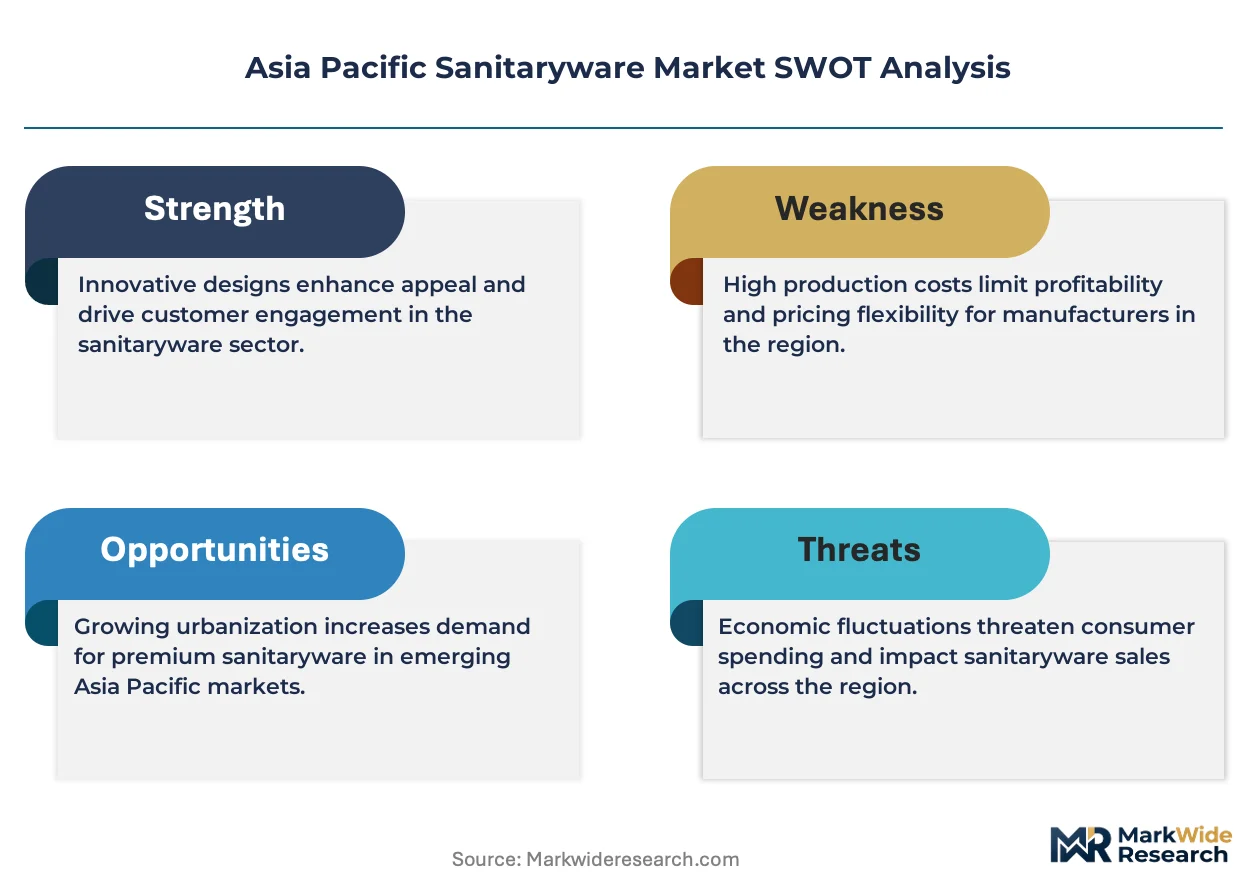
India's BIS water-efficiency grading, Australia's WELS labeling, and Japan's JIS standards collectively shape product compliance costs and market access thresholds across the region. Australia's Water Efficiency Labelling and Standards scheme directly restricts import eligibility for non-compliant fixtures, forcing manufacturers to redesign flush mechanisms for the Oceania channel. Stakeholders must monitor diverging national water-efficiency thresholds as a source of portfolio complexity rather than harmonization.
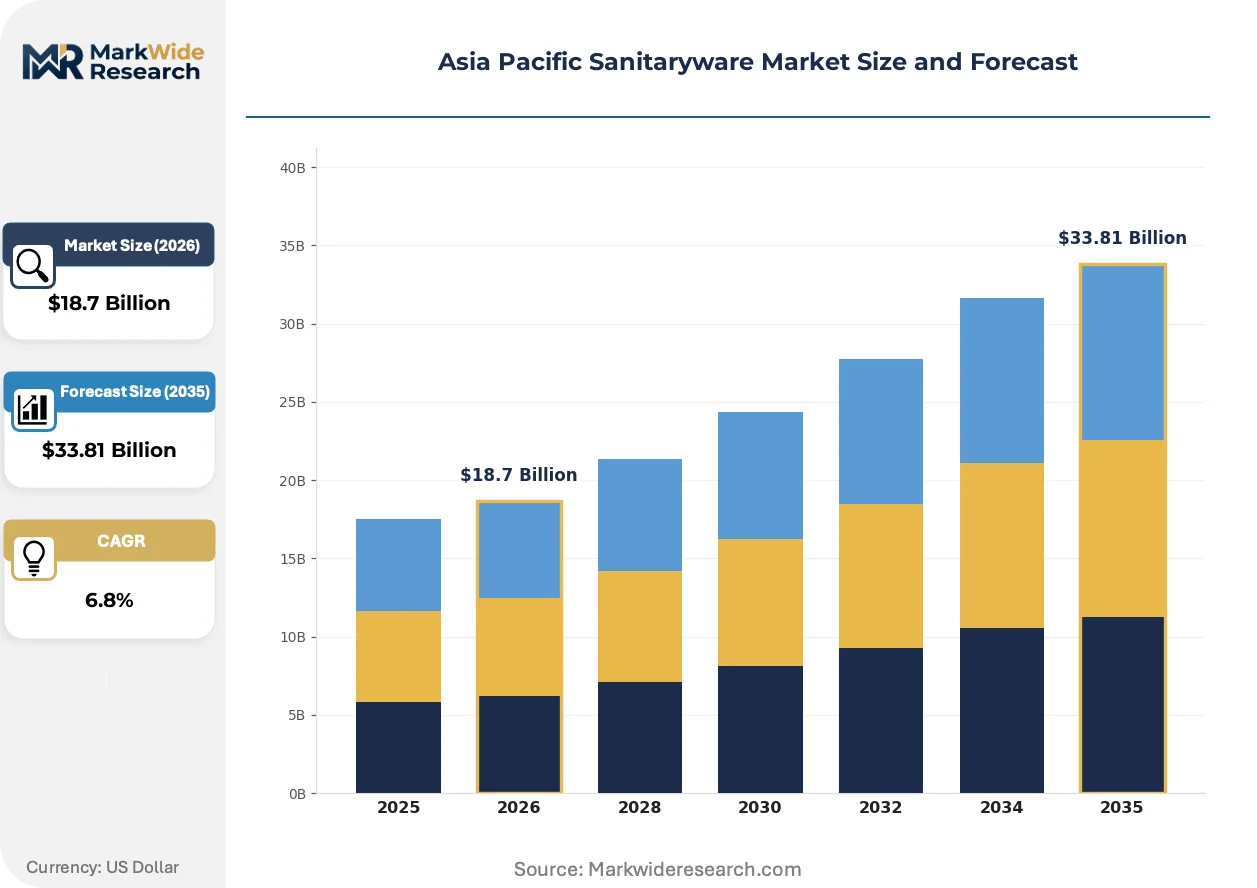
Market Dynamics
India's BIS water-efficiency grading and Australia's WELS labeling are tightening compliance thresholds across the Asia Pacific Sanitaryware Market, forcing manufacturers to redesign flush mechanisms and glazing chemistries to maintain channel access.
Growth Catalysts
- Urban housing densification:Southeast Asian megacities are retrofitting aging plumbing infrastructure in high-rise residential towers, creating specification pull for wall-mounted fixtures that optimize floor plates.
- BIS certification mandates:India's Bureau of Indian Standards is tightening ceramic water-efficiency grades, compelling domestic and import manufacturers to upgrade kiln firing protocols and glaze formulations.
- Industrial corridor expansion:Vietnam's manufacturing belt is generating institutional demand for acid-resistant vitreous china in worker housing and commercial facilities.
Market Restraints
- Feldspar and kaolin cost volatility:Ceramic raw material prices fluctuate with energy costs and mining restrictions in China and India, compressing margin stability for mid-tier producers.
- Gulf re-export concentration:RAK Ceramics anchors large-format production across the UAE-India corridor, creating supply-side dependency risks for regional distributors.
- Flush mechanism technical limits:Dual-flush valve reliability under hard-water conditions remains inconsistent, limiting water-efficiency claims in limestone-heavy supply zones.
Strategic Opportunities
- Tier-two Indian cities:Lucknow, Indore, and Coimbatore show underpenetrated premium sanitaryware penetration relative to Mumbai and Delhi, with rising disposable incomes shifting replacement cycles.
- Smart fixture convergence:Sensor-activated flush systems paired with IoT water-monitoring platforms are opening specification channels in Japan's commercial retrofit segment.
- E-commerce direct distribution:Platform-led procurement is bypassing traditional dealer networks in Indonesia and the Philippines, enabling margin capture for OEMs with logistics infrastructure.
Industry Challenges
- Glaze chemistry specialization:Non-porous vitreous china firing above 1,200°C requires ceramic engineers with rare kiln-management expertise, creating talent scarcity in Vietnam and Indonesia.
- Multi-jurisdiction certification timelines:Manufacturers must sequence BIS, WELS, and JIS testing sequentially rather than in parallel, extending product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sanitaryware Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Faucets, Showers, Sinks Material: Ceramic, Plastic, Metal, Glass Installation Type: Wall-mounted, Floor-standing, Integrated, Modular End User: Residential, Commercial, Institutional, Industrial |
| Companies Covered | TOTO, RAK Ceramics, Roca, Kohler, Lixil Group Corporation, Kerovit, Jaquar, Hindware Home Innovation Limited, Cera Sanitaryware Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sanitaryware Market Trends and Innovations
Water-efficiency labeling regimes and ceramic glazing R&D intensity are reorganizing procurement priorities across the Asia Pacific Sanitaryware Market. Specification lists now weight certification grade above brand heritage in institutional channels.
Rimless bowl designs are fragmenting traditional washdown configurations across premium residential towers in Mumbai and Bangkok. Architects specify these units for hygiene visibility and reduced cleaning labor. The technology is compressing specification share for legacy rimmed geometries in new construction.
Australia's Water Efficiency Labelling and Standards scheme restricts import eligibility for non-compliant fixtures, forcing manufacturers to redesign flush mechanisms specifically for the Oceania channel. Distributors report inventory segmentation between WELS-compliant and general-Asian-market SKUs. This regulatory friction is elevating compliance costs for mid-tier exporters without dedicated Australian product lines.
Project developers in Vietnam's industrial corridor are unbundling after-sales service from initial fixture procurement, contracting maintenance separately through facility-management platforms. This behavior compresses OEM service revenue while opening third-party service-provider markets. The shift is most visible in Ho Chi Minh City and Binh Duong province manufacturing zones.
Asia Pacific Sanitaryware Market Segmentation
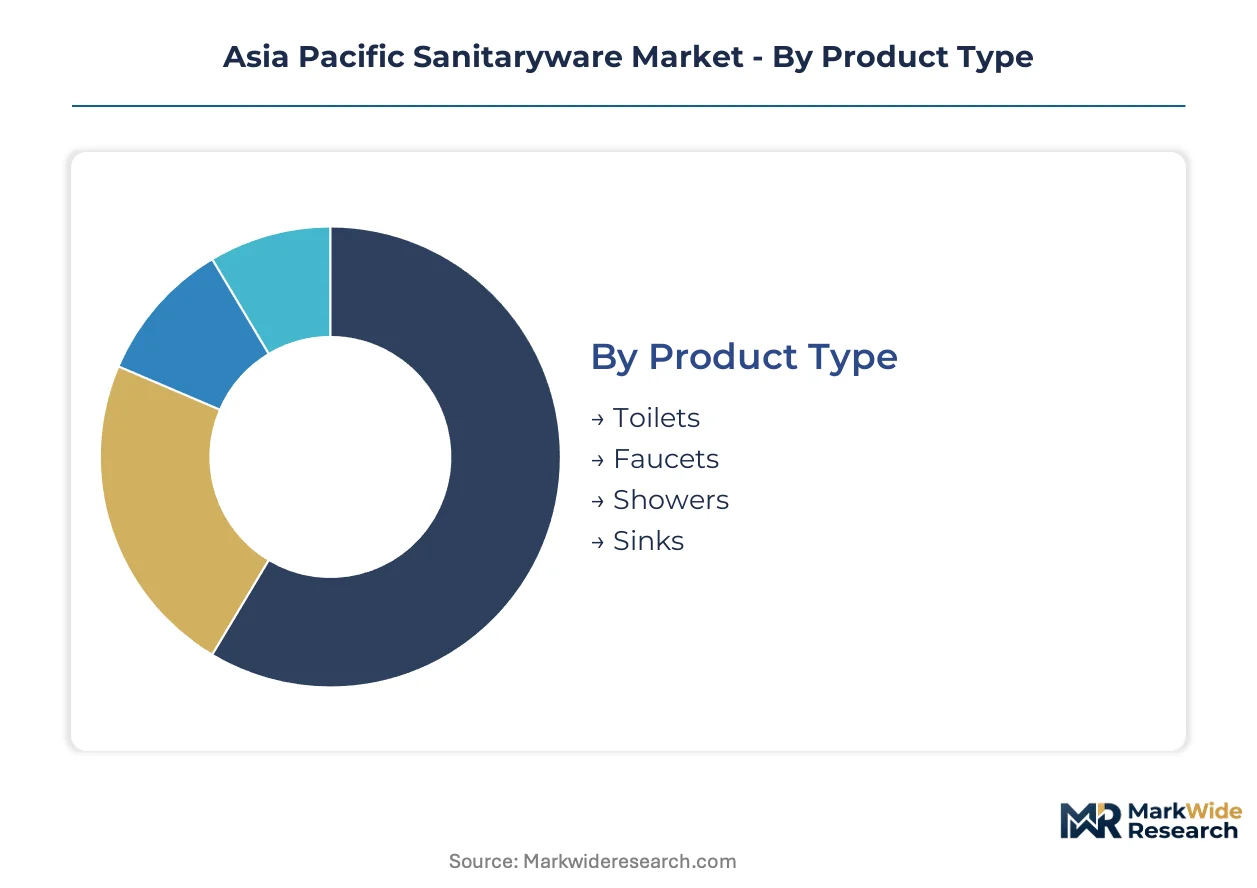
Segmentation in Asia Pacific sanitaryware reveals where specification power concentrates and where substitution threats reshape procurement. Product type and material categories show the clearest divergence between volume anchors and margin expansion zones.
Product Type:
Substitution pressure runs strongest against legacy washdown configurations as rimless geometries and sensor-integrated alternatives capture specification share in premium towers.
- Toilets:Vitreous china bowls fired above 1,200°C dominate institutional specifications across India's tier-two cities and Vietnam's industrial corridor, with BIS water-efficiency grading forcing flush mechanism redesigns for channel access. Dual-flush variants face reliability constraints under hard-water conditions in limestone-heavy supply zones.
- Faucets:Metal and ceramic cartridge assemblies command price premiums in Japan's commercial retrofit segment, where sensor-activated flow control pairs with IoT water-monitoring platforms to meet METI efficiency guidelines.
- Showers:Thermostatic mixer valves are gaining traction in Bangkok and Mumbai residential towers where water pressure inconsistency demands precision temperature control.
- Sinks:Countertop and undermount configurations split procurement between cost-driven mass housing and design-led hospitality specifications across Southeast Asia.
Toilets anchor the volume base while faucets gain share at the steepest rate.
Material:
Cost tier stratification separates premium specification channels from mass-market replacement cycles, with raw material volatility compressing margins at the mid-market position.
- Ceramic:Vitreous china retains core specification status across institutional and commercial channels, though feldspar and kaolin cost volatility from Chinese and Indian mining restrictions pressures producer margins. Non-porous glazing above 1,200°C firing temperatures meets acid-resistance requirements for high-frequency use in Vietnam's manufacturing belt.
- Metal:Brass and stainless-steel alloys carve margin pools in luxury hospitality specifications across Japan and Australia's WELS-labeled markets, where durability claims support price positioning.
- Plastic:ABS and polypropylene variants serve cost-sensitive replacement demand in Indonesia and the Philippines, where e-commerce platform procurement bypasses traditional dealer markups.
- Glass:Tempered glass basins occupy niche premium positioning in design-led residential towers across Mumbai and Bangkok, constrained by fragility concerns in high-traffic commercial applications.
Ceramic retains the dominant volume position while metal climbs the fastest in value terms.
Installation Type:
Application-driven divergence separates space-optimized premium towers from infrastructure-heavy institutional projects, with installation complexity determining contractor specialization requirements.
- Wall-mounted:Floating configurations optimize floor plates in Mumbai and Bangkok high-rise residential towers, commanding price premiums through reduced cleaning labor and visual spaciousness. Concealed cistern systems require specialized plumbing contractor networks that concentrate in metropolitan construction clusters.
- Floor-standing:Traditional close-coupled units dominate replacement cycles in India's tier-two cities where existing drainage infrastructure limits retrofit flexibility.
- Integrated:Pre-fabricated bathroom pods streamline construction timelines in Vietnam's industrial corridor worker housing, compressing on-site skilled labor requirements.
- Modular:Component-based systems enable specification flexibility in Australia's commercial retrofit segment, where WELS compliance upgrades must accommodate existing floor plans.
Floor-standing fixtures anchor replacement volume while wall-mounted systems expand most quickly in new construction specifications.
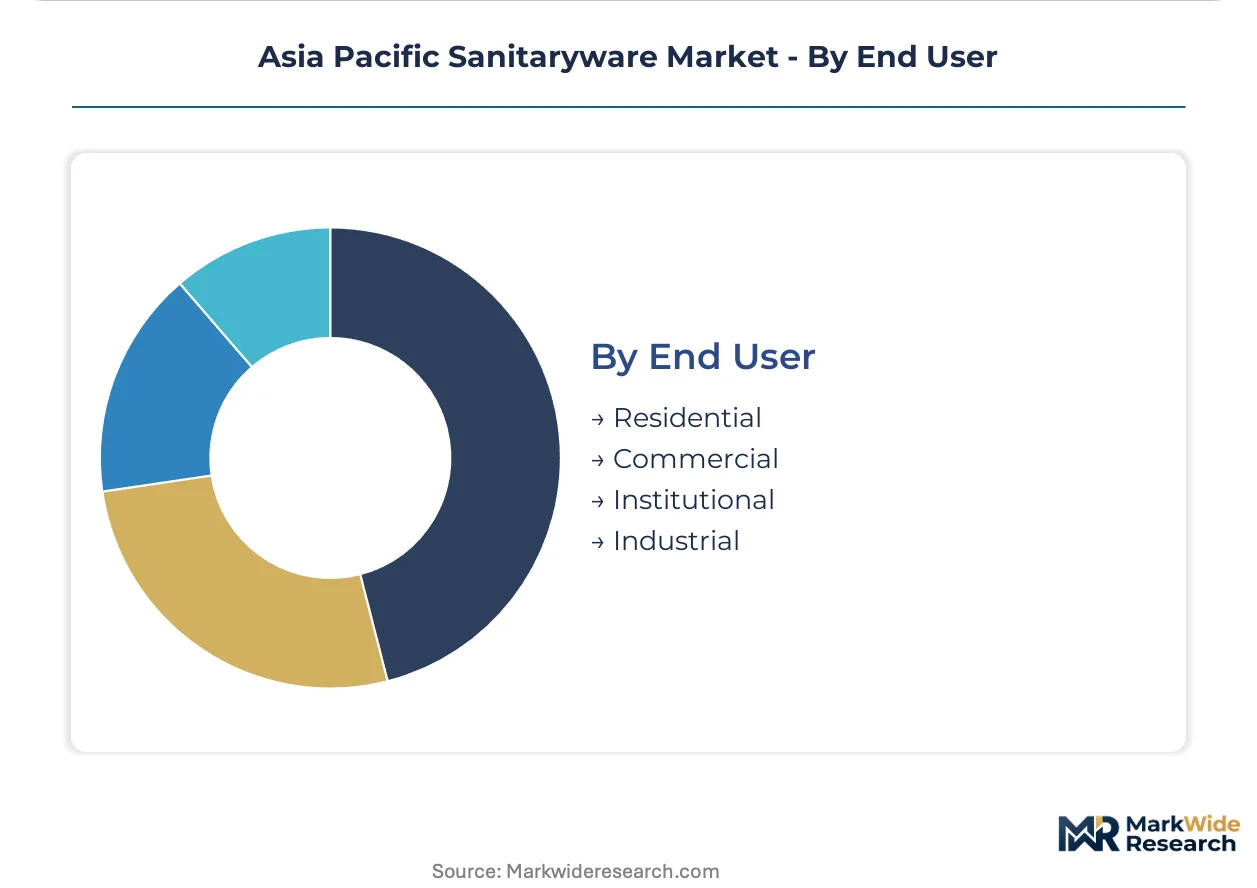
End User:
Customer type determines certification burden and service attachment, with institutional procurement unbundling after-sales support from initial fixture supply.
- Residential:Premium tower specifications in Mumbai, Bangkok, and Ho Chi Minh City drive demand for rimless geometries and water-efficient dual-flush systems, with replacement cycles shortening in India's tier-two cities as disposable incomes rise.
- Commercial:Australia's WELS labeling restricts import eligibility, forcing inventory segmentation between compliant and general-Asian-market SKUs that elevates compliance costs for mid-tier exporters.
- Institutional:Vietnam's manufacturing belt generates demand for acid-resistant vitreous china in worker housing and commercial facilities, with facility-management platforms increasingly contracting maintenance separately from initial procurement.
- Industrial:Heavy-duty specifications in processing facilities require specialized glaze chemistries that resist chemical exposure, creating specification concentration among producers with captive R&D capabilities.
Residential channels anchor absolute volume while institutional procurement shows the steepest service-unbundling trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RAK Ceramics anchors large-format production across the UAE-India corridor, creating supply-side dependencies for distributors serving Gulf re-export markets. China's feldspar and kaolin mining restrictions ripple through regional raw material costs, compressing margins for mid-tier ceramic producers.
India
Lucknow, Indore, and Coimbatore show underpenetrated premium sanitaryware demand relative to Mumbai and Delhi, with rising disposable incomes shortening replacement cycles. BIS water-efficiency grading mandates force domestic and import manufacturers to upgrade kiln firing protocols and glaze formulations. Maharashtra and Gujarat host concentrated ceramic production clusters serving institutional procurement in tier-two cities.
Japan
Commercial retrofit activity in Tokyo and Osaka drives specification pull for sensor-activated flush systems paired with IoT water-monitoring platforms. METI efficiency guidelines shape product development priorities for fixture manufacturers. The Kanto region concentrates R&D-intensive ceramic glazing operations targeting high-frequency institutional use.
Australia
WELS labeling directly restricts import eligibility for non-compliant fixtures, forcing inventory segmentation between compliant and general-Asian-market SKUs. Sydney and Melbourne construction activity generates demand for modular bathroom systems in commercial retrofit applications. Distributors report elevated compliance costs for mid-tier exporters without dedicated Australian product lines.
Vietnam
Ho Chi Minh City and Binh Duong province manufacturing zones generate institutional demand for acid-resistant vitreous china in worker housing and commercial facilities. Facility-management platforms increasingly unbundle after-sales service from initial fixture procurement. The industrial corridor expansion creates specification concentration for durable glazing chemistries.
Thailand
Bangkok high-rise residential towers command price premiums for wall-mounted fixtures optimizing floor plates and reducing cleaning labor. Thermostatic mixer valves gain traction where water pressure inconsistency demands precision temperature control. Central Thailand construction clusters concentrate plumbing contractor networks specializing in concealed cistern installations.
Asia Pacific Sanitaryware Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific Sanitaryware Market. The vendor base stratifies into three tiers: premium specification leaders with captive R&D capabilities, scale-driven mass-market producers, and regional specialists serving price-sensitive replacement demand. Strategic moves concentrate on ceramic glazing chemistry specialization and e-commerce direct distribution infrastructure. Geographic expansion through Gulf re-export corridors and tier-two Indian city penetration dominate competitive positioning.
Among Japan-based fixture developers, TOTO and Lixil Group Corporation exemplify technology-intensive archetypes with R&D-driven specification power in commercial retrofit segments. RAK Ceramics anchors the scale-driven tier with large-format production positioning across the UAE-India supply corridor. Indian domestic specialists including Cera Sanitaryware Limited and Hindware Home Innovation Limited occupy positions serving BIS-compliant demand in tier-two cities and mass-market replacement cycles.
| Leading Market Players |
|---|
| TOTO |
| RAK Ceramics |
| Roca |
| Kohler |
| Lixil Group Corporation |
| Kerovit |
| Jaquar |
| Hindware Home Innovation Limited |
| Cera Sanitaryware Limited |
| Others |
Pricing and Supply Chain Analysis
Plastic-to-ceramic material substitution in cost-sensitive replacement demand simultaneously reshapes supply geography toward Indonesia and the Philippines while compressing pricing economics for mid-tier vitreous china producers in India and Vietnam. This input shift redirects procurement flows through e-commerce platforms that bypass traditional dealer markups, fragmenting established pricing hierarchies across Southeast Asian distribution networks.
Pricing Analysis
BIS water-efficiency grading dictates the pricing tier structure across India's tier-two cities, where certification-compliant vitreous china commands premiums over uncertified imports. Pricing stratifies across premium sensor-integrated fixtures, standard dual-flush systems, and economy plastic variants. Cost compression in mid-market ceramic segments is intensifying because feldspar and kaolin volatility from Chinese mining restrictions squeezes producer margins. Mass housing developers in Vietnam's industrial corridor exhibit the highest price sensitivity, while Japan's commercial retrofit segment shows lowest sensitivity due to METI efficiency mandates.
Supply Chain Analysis
Strategic stockpiling of ceramic raw materials dominates inventory strategy among Indian producers facing feldspar supply interruptions from Chinese export restrictions. Manufacturing concentrates in India, China, and Vietnam, with the UAE-India corridor anchoring Gulf re-export flows. Supply chains rest on kaolin deposits, feldspar processing capacity, and glaze chemistry specialization. Single-source vulnerability runs through China's dominance in ceramic raw material refining. Distribution runs through traditional dealer networks in tier-two Indian cities and platform-led procurement in Indonesia and the Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates switching costs. BIS, WELS, and JIS certification requirements lock in specification relationships and extend product launch timelines, protecting incumbent positions.
For Market Incumbents: Fortify specification relationships by deepening captive R&D capabilities in ceramic glazing chemistry and kiln firing protocols. Invest in parallel certification testing infrastructure to compress sequential BIS-WELS-JIS launch windows. Capacity addition in Maharashtra and Gujarat production clusters defends against Gulf re-export supply disruptions. Channel control through direct e-commerce distribution in Indonesia and the Philippines captures margin pools threatened by platform disintermediation.
For New Entrants and Emerging Players: Anchor in Lucknow, Indore, and Coimbatore where premium sanitaryware penetration lags Mumbai and Delhi replacement cycles. Target facility-management platforms in Vietnam's industrial corridor that unbundle after-sales service from initial procurement, creating third-party service-provider white space. Pursue go-to-market angles through IoT water-monitoring platform partnerships in Japan's commercial retrofit segment, bypassing entrenched specification lists.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier producers with captive ceramic engineering talent and existing BIS compliance infrastructure across India's tier-two city networks. Long-term viability hinges on regulatory entrenchment deepening through diverging national water-efficiency thresholds rather than harmonization. Acquisition target archetypes include regional specialists with logistics infrastructure for e-commerce direct distribution. The signal to watch is facility-management platform procurement volume crossing thresholds that permanently unbundle service revenue from fixture supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Glazing R&D Intensification | TOTO's commercial retrofit specification power in Japan demonstrates technology leadership moats. |
| Parallel Certification Testing Infrastructure | Compressed BIS-WELS-JIS launch windows defend against eight-to-fourteen-month competitive delays. |
| E-commerce Direct Distribution Buildout | Platform-led procurement in Indonesia and Philippines bypasses traditional dealer margin extraction. |
| Tier-two Indian City Penetration | Lucknow and Coimbatore disposable income growth shortens replacement cycles versus saturated metros. |
| Facility-Management Platform Partnership | Vietnam's industrial corridor unbundling creates third-party service revenue pools separate from fixture supply. |
Research Methodology
Desk research of trade customs data, BIS certification registries, and WELS product databases preceded structured interviews with ceramic plant managers, procurement leads at institutional developers, distribution channel partners, and technical R&D directors specializing in glaze chemistry. Primary fieldwork across Mumbai, Ho Chi Minh City, and Bangkok construction clusters validated secondary findings on specification trends and installation-type preferences. Bottom-up volume modeling triangulated against top-down macroeconomic projections across the analysis window.
Variance decomposition across product type, material grade, installation configuration, and end-user channel anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory modeling incorporating urban housing densification rates, regulatory compliance cost curves, and raw material price elasticity. Industry-specific forecast inputs included BIS water-efficiency grading adoption curves and facility-management platform procurement penetration rates.
Material uncertainties — feldspar export restriction severity, dual-flush valve reliability under hard-water conditions, and e-commerce platform consolidation patterns — sit outside the modeled envelope. Forecasts reflect assumptions on certification timeline stability and ceramic raw material supply continuity. Revision becomes warranted when BIS grading enforcement intensity crosses thresholds that eliminate non-compliant import channel access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market