
 PU Roof Window Market | 2026-2036
PU Roof Window Market Size, Share, and Industry Trends Forecast 2026-2036
PU Roof Window Market Insights
Polyurethane foam-in-place insulation is reconfiguring how roof window manufacturers achieve thermal bridging performance without sacrificing daylight aperture. Velux Group leverages captive R&D facilities across Denmark and Poland to refine pultruded PU frame profiles that outperform aluminum thermally. Fakro anchors its competitive stance through backward integration into polymer compounding, securing supply continuity for high-density polyurethane formulations. Roto Frank AG differentiates via hardware systems engineered specifically for the heavier load profiles of triple-glazed PU composite frames.
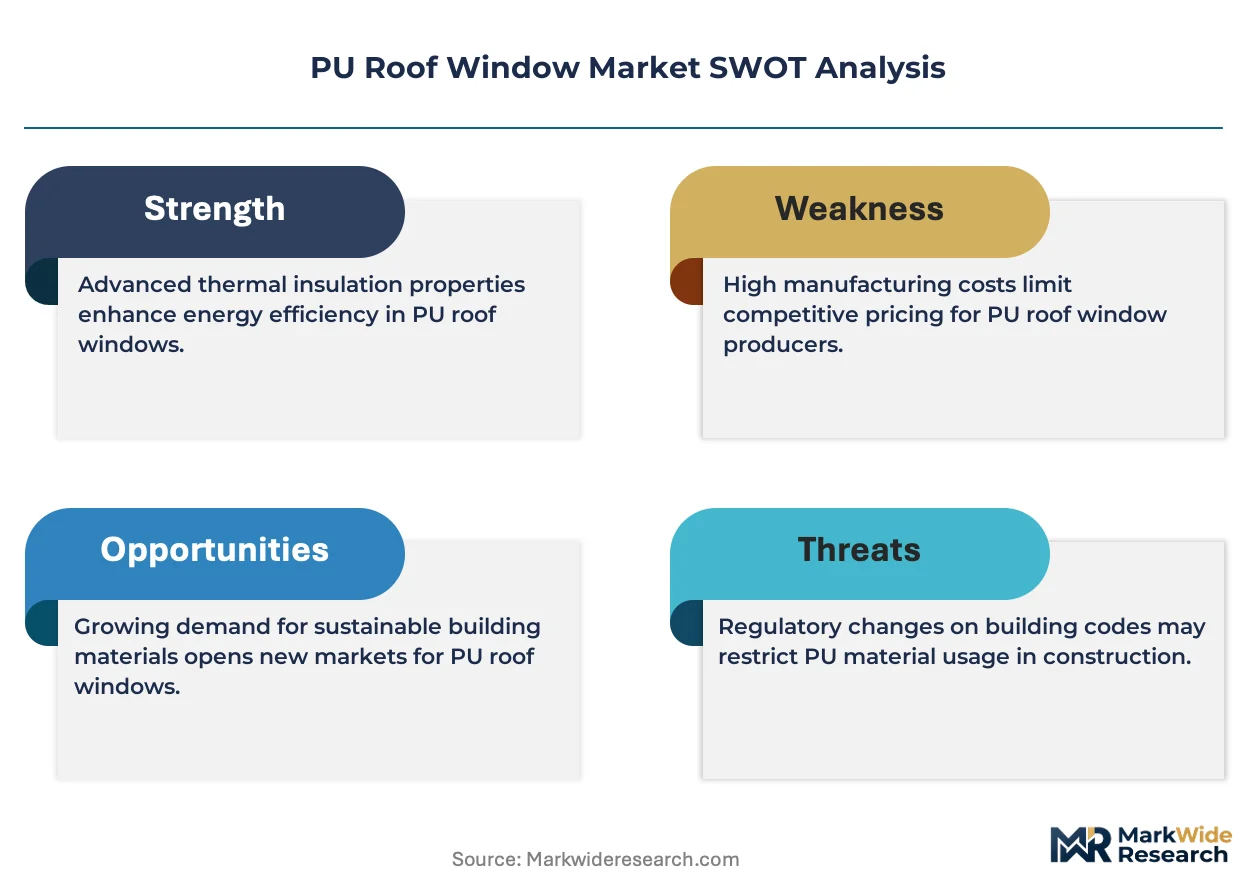
A PU roof window is an overhead glazing unit whose frame incorporates rigid polyurethane foam as the primary thermal break and structural core, typically achieving U-values below 0.8 W/m²K while supporting laminated safety glass up to 60 kg per sash. The product serves commercial and residential buildings where roof-plane daylighting must comply with stringent energy conservation codes without triggering condensation risk at the frame perimeter. Electric operated units lead value generation because motorized chain drives integrate cleanly with PU frame cavities that conceal wiring channels and motor housings. Solar powered variants represent the fastest-expanding niche, as photovoltaic-integrated actuators eliminate external electrical rough-in and suit remote attic installations where wiring retrofits prove costly. Retrofit projects command disproportionate margin pools because existing roof cutouts demand custom flashings and adaptive frame extensions that new construction rarely requires.
EU Green Deal renovation wave targets and REACH compliance for isocyanate handling shape formulation choices and factory certification requirements across the European manufacturing base. Germany's KBA and France's ANSM do not directly regulate this category, but CE marking under Construction Products Regulation and national building codes in Denmark, Sweden, and Poland mandate declared thermal performance and weather tightness testing. Stakeholders must monitor how the EU F-Gas Regulation's phase-down of blowing agents affects polyurethane core density specifications and whether national green building certification schemes elevate demand for solar powered and ventilating configurations in public procurement.
Market Dynamics
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is forcing polyurethane core reformulation across manufacturing facilities, compressing margins for producers unable to pivot to pentane or water-blown alternatives while elevating compliance costs for smaller fabricators.
Growth Catalysts
- EU Green Deal renovation wave:Mandatory building envelope upgrades in Germany, Denmark, and Sweden are accelerating attic conversion permits and triggering replacement cycles for thermally inefficient legacy skylights.
- Polyurethane pultrusion advances:Continuous fiber-reinforced PU frame profiles now achieve U-values below 0.8 W/m²K, enabling triple-glazed configurations that satisfy Passive House certification thresholds without aluminum thermal bridging.
- Poland and Czech Republic housing stock:Elevated attic conversion rates in post-war residential districts are concentrating demand clusters for custom-dimensioned roof windows with integrated thermal breaks.
Market Restraints
- Isocyanate feedstock volatility:MDI and TDI pricing swings tied to crude oil indices and European refinery capacity constraints compress gross margins unpredictably for PU frame producers.
- REACH authorization timelines:ECHA's substance evaluation protocols for novel blowing agents extend certification cycles by 18-24 months, freezing product pipeline velocity for reformulated cores.
- Aluminum-PVC hybrid substitution:Lower-cost thermally broken aluminum frames with polyamide strips retain share in commercial new construction where daylight aperture specifications are less stringent.
Strategic Opportunities
- Solar-powered actuation convergence:Photovoltaic-integrated motor housings paired with PU frame wiring channels eliminate electrical rough-in costs for remote attic installations.
- Public procurement green certification:Denmark's voluntary sustainability class for public buildings and France's RE2020 environmental regulations are elevating demand for ventilating and solar-configured units in institutional retrofits.
- Retrofit customization services:Adaptive flashing systems and frame extension kits for non-standard roof cutouts command premium pricing pools unavailable in new construction specification.
Industry Challenges
- Polymer compounding talent scarcity:Formulation chemists with expertise in high-density PU systems and blowing agent transitions are concentrated among legacy automotive suppliers, creating recruitment friction for window manufacturers.
- CE marking test protocol complexity:Construction Products Regulation compliance for declared thermal performance and weather tightness requires multi-laboratory coordination across Denmark, Poland, and Germany, extending time-to-market.
- Triple-glazed hardware integration:Heavier sash loads from 60 kg laminated safety glass configurations demand recalibrated hinge and chain drive systems, complicating supply chain synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PU Roof Window Market |
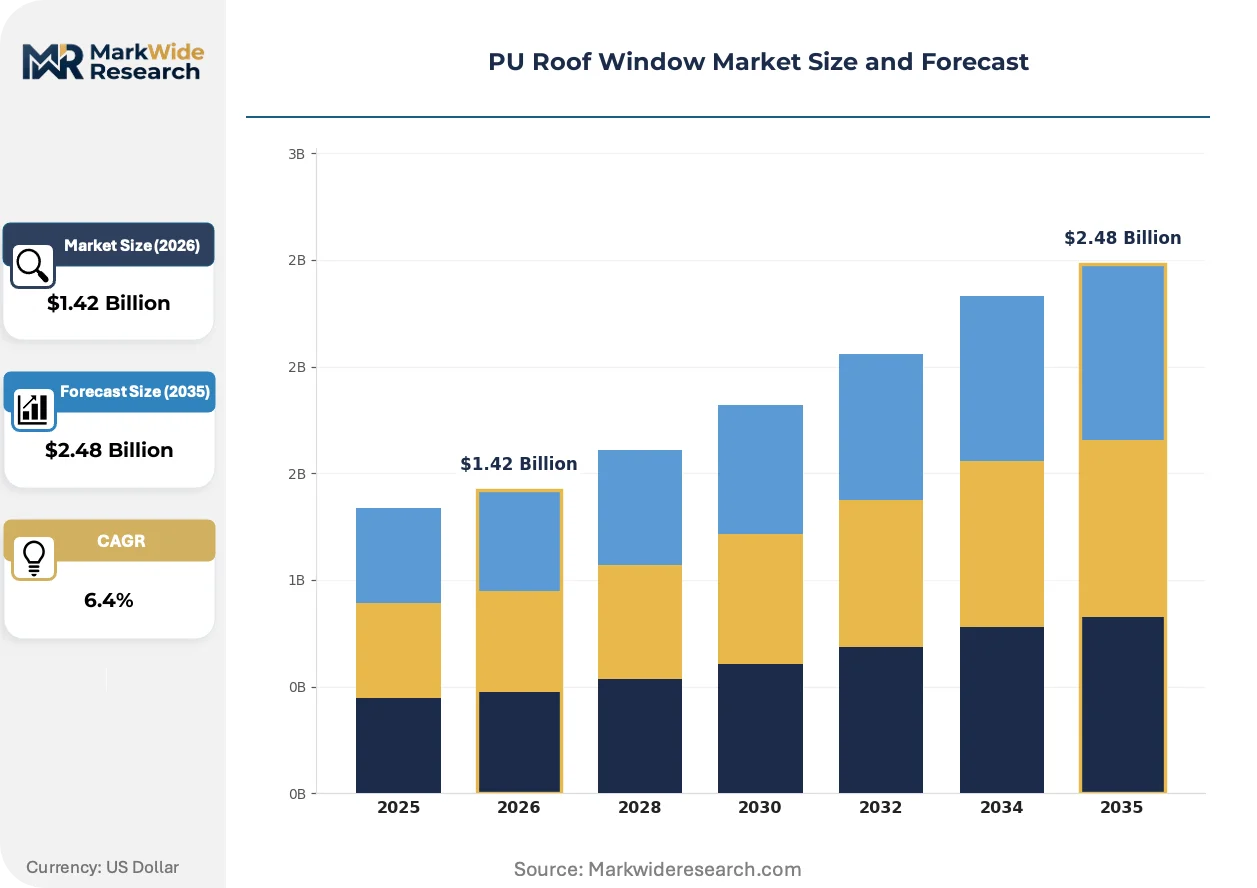
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Operated, Electric Operated, Solar Powered, Ventilating, Fixed Material: Polyurethane, PVC, Aluminum, Wood, Fiberglass End User: Residential Buildings, Commercial Complexes, Educational Institutions, Hospitality Venues, Cultural Centers Installation Type: New Construction, Retrofit Projects, Modular Buildings, Prefabricated Structures, Green Roofs |
| Companies Covered | Velux Group, Fakro, Roto Frank AG, Keylite Roof Windows, LAMILUX Heinrich Strunz Group, Dakea, Sunlux Roof Windows, Faelux, Alwitra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PU Roof Window Market Trends and Innovations
Pultruded polyurethane frame technology is collapsing the thermal performance gap between synthetic composites and traditional materials, while regulatory chemistry mandates and procurement model evolution are reshaping how value is captured across the value chain.
Water-blown and pentane-based PU core formulations are collapsing the cost premium historically attached to low-global-warming-potential insulation systems. Residential renovation contractors in Scandinavia and northern Germany are specifying these reformulated frames at accelerating rates to preempt future regulatory liability. The structural consequence is compressing the viable supplier base to manufacturers with captive polymer compounding capabilities and ECHA-authorized substance handling protocols.
The EU F-Gas Regulation's staged reduction in HFC blowing agent quotas is tightening supply availability for conventional PU foam production. Frame fabricators dependent on imported core materials face reformulation deadlines that strain R&D budgets and factory certification timelines. Solar-powered and electrically actuated roof window variants are most affected, as their integrated motor housings demand precise cavity tolerances that reformulated foam densities must accommodate without dimensional drift.
Specification authority is migrating from general contractors to energy auditors and building envelope consultants who prioritize documented U-values over brand preference. Distributors in Poland and the Czech Republic are unbundling installation services from product supply, creating direct procurement channels between fabricators and certified installer networks. This pattern is most visible in German attic conversion markets, where Passive House consultants specify PU frame profiles by thermal bridge calculation rather than manufacturer catalog.
PU Roof Window Market Segmentation
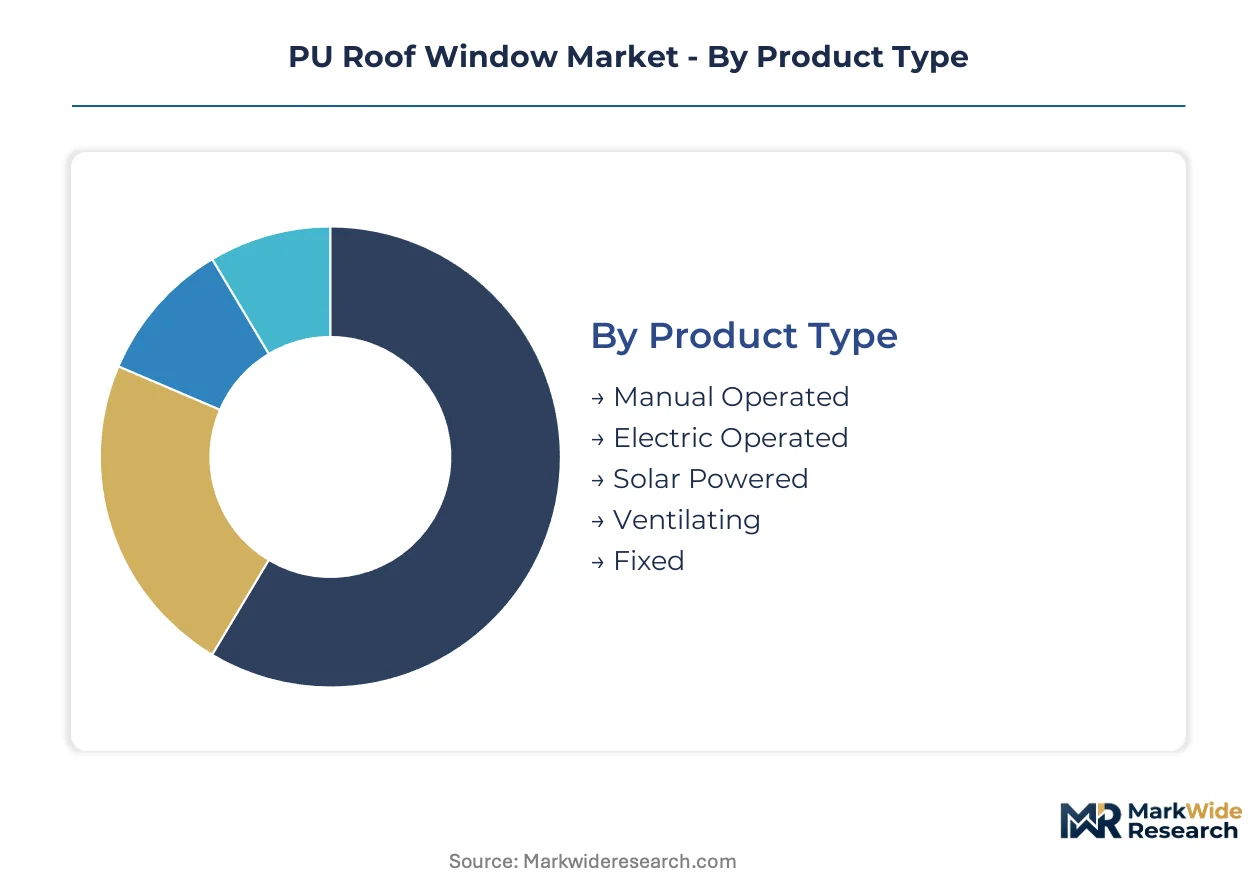
PU roof window segmentation reveals distinct replacement cadences across product configurations, with motorized and ventilating units cycling faster than fixed alternatives due to actuator wear and regulatory refresh mandates. Material and end-use stratification further concentrates margin capture in polymer-intensive frames and heritage building retrofits where thermal bridge calculations dominate specification authority.
Product Type:
Replacement frequency diverges sharply across actuation methods, with electrically motorized units turning over every 12-15 years versus 25-30 year lifespans for fixed glazing.
- Manual Operated:Hand-crank chain drive systems with exposed hardware endure mechanical fatigue in coastal and high-humidity zones. German attic conversion contractors favor these for cost-sensitive renovation waves where electrical rough-in proves prohibitive.
- Electric Operated:Concealed motor housings integrated within PU frame cavities enable remote operation and rain sensor automation. Denmark's building code mandates for accessible roof-level ventilation are concentrating demand in multi-unit residential retrofits.
- Solar Powered:Photovoltaic-integrated actuators eliminate external wiring and suit remote installations. Polish and Czech Republic housing stocks with difficult attic access drive specification.
- Ventilating:Integrated trickle vents and automated flap systems manage stack effect air exchange. Passive House consultants in Scandinavia specify these for humidity control in deep energy retrofits.
- Fixed:Non-operable glazing units with minimal thermal bridging achieve lowest U-values. Heritage building constraints in France and Belgium preserve demand despite zero ventilation functionality.
Electric operated units anchor the volume base while solar powered configurations gain share at the steepest rate.
Material:
Cost tier stratification separates premium polyurethane cores from commodity alternatives, with thermal performance certification acting as the price delimiter.
- Polyurethane:Rigid foam-in-place cores with fiber-reinforced pultruded profiles achieve sub-0.8 W/m²K U-values. EU F-Gas Regulation compliance costs are compressing the viable supplier base to manufacturers with captive compounding capabilities.
- PVC:Extruded vinyl frames with multi-chamber construction dominate budget residential new construction. REACH authorization timelines for plasticizer alternatives extend procurement cycles for German fabricators.
- Aluminum:Thermally broken profiles with polyamide strips retain commercial specification where daylight aperture requirements are less stringent. Polish distribution channels favor these for rapid-turn warehouse and logistics building projects.
- Wood:Laminated timber cores with exterior aluminum cladding serve heritage aesthetic mandates. Swedish and Finnish markets sustain niche demand despite higher maintenance burden.
- Fiberglass:Pultruded glass-reinforced polymer offers dimensional stability without thermal bridging. Czech Republic modular building manufacturers specify these for transport tolerance.
PVC frames dominate unit shipments while polyurethane cores command the most rapid specification migration in energy-code jurisdictions.
End User:
Application-driven specification separates envelope-performance-critical retrofits from cost-optimized new construction procurement.
- Residential Buildings:Single-family and multi-unit attic conversions requiring thermal bridge-free daylighting. Germany's KBA-adjacent building energy regulations mandate documented U-value performance.
- Commercial Complexes:Office and retail atrium installations with integrated Building Management System controls. France's RE2020 environmental regulations elevate demand for automated ventilating configurations.
- Educational Institutions:Daylighting mandates for classroom cognitive performance drive specification. Denmark's voluntary sustainability class for public procurement favors solar-powered actuation.
- Hospitality Venues:Guest room ventilation and blackout requirements combine in custom configurations. Boutique hotel retrofits in Prague and Krakow concentrate demand for adaptive flashing systems.
- Cultural Centers:Conservation-grade glazing for artifact protection with UV-filtering laminates. Belgian and Dutch museum renovation projects specify fixed triple-glazed units with inert gas fills.
Residential buildings sustain the installed base while educational institutions expand most quickly under green public procurement mandates.
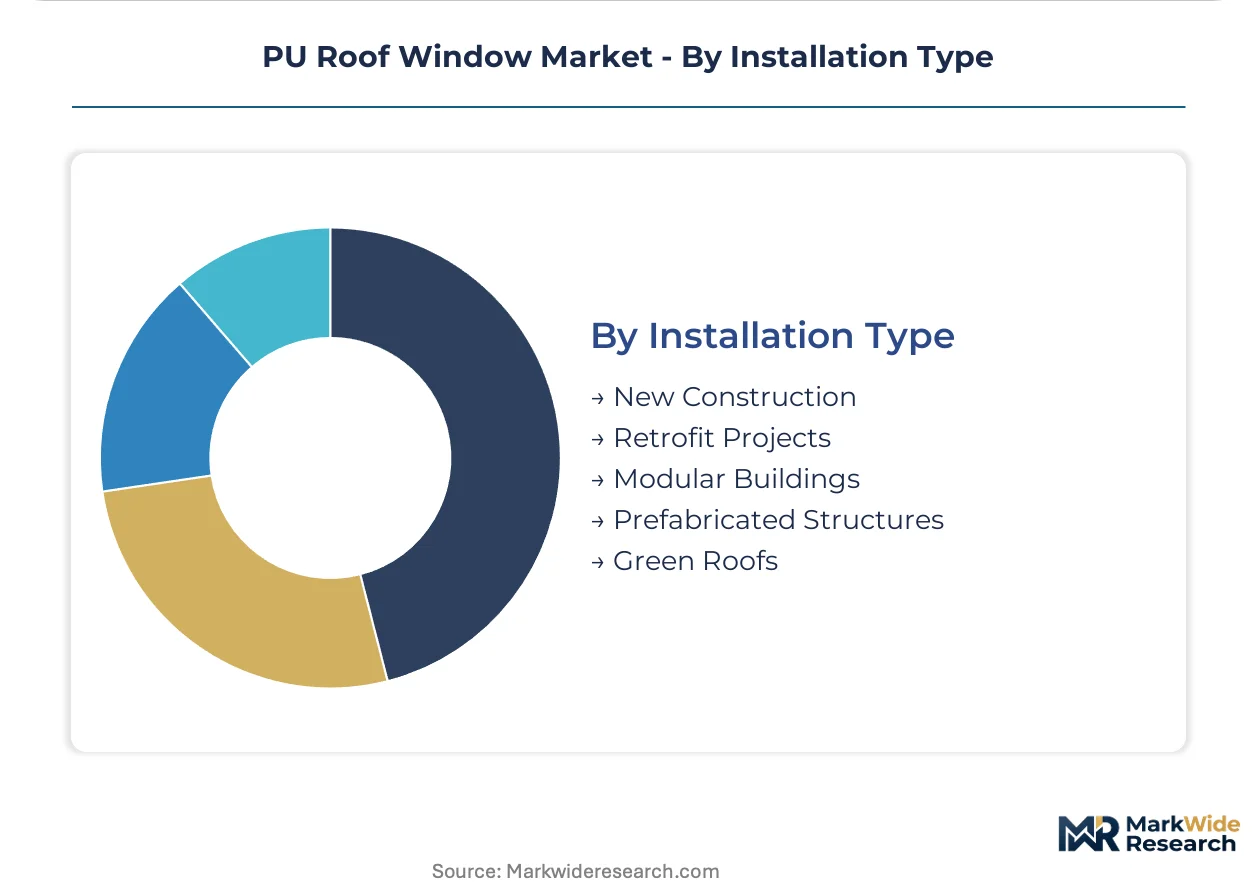
Installation Type:
Supply concentration favors retrofit customization services where non-standard roof cutouts command premium pricing unavailable in volume new construction.
- New Construction:Standardized rough openings enable catalog specification and rapid installation. Polish residential development corridors absorb volume production with minimal customization.
- Retrofit Projects:Existing roof plane modifications demand adaptive flashings and frame extension kits. German energy auditor specification authority concentrates margin in certified installer networks.
- Modular Buildings:Factory-integrated glazing units installed before site delivery. Czech and Slovak manufacturing clusters favor PU frames for transport durability.
- Prefabricated Structures:Panelized construction with pre-cut window openings. Scandinavian volume housing producers specify electric operated variants for smart home integration.
- Green Roofs:Vegetated roof systems requiring specialized curb flashings and drainage integration. Berlin and Copenhagen municipal building codes mandate these for new institutional construction.
New construction absorbs the highest unit volumes while retrofit projects deliver superior margin per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European PU roof window trade flows reveal a pronounced export surplus concentrated in Danish and Polish manufacturing clusters, while import dependency characterizes markets in southern Europe lacking captive polymer compounding infrastructure. Cross-border specification patterns increasingly favor thermal bridge calculations over manufacturer catalog preferences.
Germany
Attic conversion permits in post-war residential districts of Berlin and Hamburg drive specification for triple-glazed configurations. The KBA-adjacent building energy regulations mandate documented U-value performance below 0.8 W/m²K for envelope upgrades. Bavarian fabricators concentrate pultrusion R&D investment to preempt REACH authorization delays for novel blowing agents.
Denmark
Multi-unit residential retrofits absorb electrically motorized variants with concealed motor housings. The voluntary sustainability class for public procurement elevates demand for solar-powered actuation in institutional projects. Copenhagen municipal building codes mandate specialized curb flashings for green roof integrations on new construction.
Poland
Attic conversion rates in Krakow and Wroclaw residential corridors sustain demand for custom-dimensioned units with adaptive flashing systems. National building codes aligned with EU Green Deal renovation wave targets accelerate replacement cycles for thermally inefficient legacy skylights. Silesian manufacturing clusters supply reformulated pentane-blown cores to preempt F-Gas Regulation quota constraints.
Sweden
Passive House consultants in Stockholm and Gothenburg specify ventilating configurations for humidity control in deep energy retrofits. Tightening building envelope codes under the EU Green Deal accelerate polyurethane core adoption over conventional PVC frames. Scandic distribution channels unbundle installation services from product supply, creating direct procurement channels to certified installer networks.
Czech Republic
Modular building manufacturers in Prague specify PU frames for transport durability in prefabricated panelized construction. Elevated attic conversion rates in Brno and Ostrava post-war housing stocks concentrate demand clusters for integrated thermal breaks. ECHA substance evaluation protocols for isocyanate handling extend certification cycles for local fabricators dependent on imported core materials.
PU Roof Window Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with captive polymer compounding capabilities and ECHA-authorized substance handling protocols. Three strategic archetypes dominate: vertically integrated specialists controlling formulation chemistry, hardware-integrated assemblers sourcing cores from qualified suppliers, and regional fabricators serving retrofit customization niches. Competitive intensity centers on backward integration into high-density polyurethane systems and strategic partnerships with certified installer networks.
Among European fabricators, Velux Group and Fakro exemplify the vertically integrated archetype through in-house control over polymer formulation and pultrusion processes. Roto Frank AG occupies a position on the hardware-integrated vector, specializing in chain drive systems engineered for heavier sash loads. These three anchors represent distinct competitive positioning strategies: formulation chemistry control, supply continuity assurance, and mechanical system integration respectively.
| Leading Market Players |
|---|
| Velux Group |
| Fakro |
| Roto Frank AG |
| Keylite Roof Windows |
| LAMILUX Heinrich Strunz Group |
| Dakea |
| Sunlux Roof Windows |
| Faelux |
| Alwitra |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Copenhagen freight corridor cost volatility feeds directly into PU core pricing differentials between Danish pultrusion specialists and Polish compounders, compressing margins for fabricators without captive logistics while amplifying price spreads between pentane-blown and legacy HFC-based formulations.
Pricing Analysis
Next-generation water-blown and pentane-based PU cores command 15-20% premiums over HFC-dependent prior-generation formulations, while current-generation electric-operated units with integrated motor housings price above manual alternatives. Three-tier pricing structure across premium certified, standard CE-marked, and economy non-ventilating levels separates buyers by thermal performance documentation requirements. Cost compression in economy PVC-alternative tiers intensifies because aluminum-polyamide hybrid frames undercut PU composites on upfront project costs. Residential renovation contractors in Poland exhibit highest price sensitivity, while German energy auditors specifying Passive House compliance show least sensitivity to frame premiums.
Supply Chain Analysis
Tariff exposure between Germany and China for MDI isocyanate feedstocks dominates supply risk calculus for frame fabricators without backward integration into polymer compounding. Manufacturing gravity centers on Denmark, Poland, and Germany, with Silesian clusters supplying pentane-blown cores and Danish facilities anchoring pultrusion R&D. Raw material dependencies rest on MDI/TDI isocyanates, glass fiber rovings, and laminated safety glass from float lines. Single-source vulnerability concentrates in specialized hinge and chain drive hardware from Roto Frank AG's German production. Distribution runs through certified installer networks in Germany and unbundled distributor channels in Poland and Czech Republic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's staged HFC phaseout constitutes a regulatory inflection that will eliminate one-third of current PU core suppliers by the analysis window's midpoint, concentrating margin capture among formulation-capable incumbents.
For Market Incumbents: Pre-empt REACH authorization delays by securing ECHA substance handling protocols for pentane and water-blown alternatives before competitor pipeline freezes. Backward integration into captive polymer compounding insulates against MDI price volatility while denying formulation expertise to emerging hardware-integrated assemblers. Defensive patent filing around pultruded cavity geometries for motor housing integration blocks new entrant access to electric-operated segment growth.
For New Entrants and Emerging Players: Build out retrofit customization capabilities targeting non-standard roof cutouts in German attic conversion markets where energy auditor specification authority concentrates margin pools unavailable to catalog-standard competitors. Polish distributor channel partnerships offer the most penetrable geographic entry point given unbundled installation services and direct fabricator-to-installer procurement trends. Solar-powered actuation for remote attic access represents the highest-velocity white-space application.
For Investors and Strategic Acquirers: Regional fabricators with ECHA-authorized handling protocols and established certified installer network relationships in Germany or Scandinavia represent the optimal acquisition target archetype for exposure to green public procurement expansion. Long-term viability hinges on formulation chemistry control rather than assembly scale. The signal to watch is Denmark's voluntary sustainability class for public buildings mandating solar-powered or ventilating configurations, which would accelerate specification migration and compress hardware-only assemblers' relevance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive MDI formulation capability insulates margin from feedstock volatility and REACH delays. |
| Solar-Powered Actuation Product Line Launch | Photovoltaic-integrated motor housings unlock Polish and Czech remote attic installation demand. |
| Certified Installer Network Partnership | Direct procurement channels in Germany bypass distributor markups and capture energy auditor specification authority. |
| Pentane-Blown Core Manufacturing Scale-Up | Silesian production expansion preempts F-Gas Regulation quota constraints on HFC alternatives. |
| Adaptive Flashing System Development | Custom retrofit kits command premium pricing unavailable in standardized new construction specification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polymer formulation chemists, attic conversion contractors in Germany and Poland, building envelope consultants specifying Passive House compliance, and procurement leads at major distribution channels. Secondary validation drew from ECHA substance registration databases, EU F-Gas Regulation quota tracking, national building code filings in Denmark and Germany, and construction permit data for attic conversions. Bottom-up unit shipment estimates by product configuration and top-down market sizing by country were triangulated against polyurethane raw material consumption patterns reported by Cefic.
Calibration against historical thermal performance certification trends and regulatory compliance cost trajectories anchored the projection framework across the analysis window. Segmentation dimensions modeled include actuation method, core material formulation, end-use building type, and installation context. CAGRs were derived from regression analysis of replacement cycle acceleration under EU Green Deal renovation targets, with specific inputs from attic conversion permit growth rates in Berlin and Hamburg and Passive House consultant specification surveys in Scandinavia.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by hardware-only assemblers or rapid REACH authorization by Chinese MDI suppliers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North Africa Cement Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Silos Market
Building & Construction Materials
Fiberglass Light Poles Market