
 North America Concrete Conditioner Market | 2026-2036
North America Concrete Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
North America Concrete Conditioner Market Analytics
Preventive maintenance subscription programs is shifting how concrete conditioners move through distribution channels, bundling surface treatments with scheduled reapplication protocols. BASF SE leverages its chemical manufacturing scale to supply bulk liquid additives directly to ready-mix plants across the Midwest. Sika AG anchors its position through specialty distribution partnerships with regional concrete repair contractors. MAPEI Corporation competes on formulation breadth, sustaining R&D investment in VOC-compliant penetrating sealers.
A concrete conditioner encompasses chemical formulations—silane-siloxane blends, lithium silicate densifiers, or acrylic copolymer emulsions—applied to cured or curing concrete to reduce permeability, resist chloride ingress, or extend service life in freeze-thaw environments. These treatments function by either reacting with calcium hydroxide to form insoluble calcium silicate hydrate barriers, or by creating hydrophobic surface films that repel water and dissolved salts. Liquid additives dominate volume flows due to spray-application efficiency on horizontal infrastructure surfaces, while coatings command premium positioning in industrial containment settings where chemical resistance thresholds are specified. Road construction applications show structural momentum as state agencies integrate conditioner specifications into pavement preservation contracts, shifting spend from reactive repair to programmed surface extension.
The US Federal Highway Administration sets performance benchmarks through its Long-Term Pavement Performance program, indirectly conditioning state-level material approvals. EPA VOC regulations under 40 CFR Part 59 constrain solvent-based formulation options, pushing manufacturers toward waterborne and exempt-compound chemistries. ASTM C309 and AASHTO specifications provide the technical substrate for product qualification across US and Canadian jurisdictions. Stakeholders must monitor how evolving domestic-content thresholds in federal infrastructure awards reshape supplier qualification criteria and regional sourcing requirements.
Market Dynamics
US state DOTs and Canadian provincial agencies are redirecting capital from new construction toward pavement preservation, compressing conditioner procurement cycles and bundling surface treatments into multi-year maintenance contracts.
Growth Catalysts
- US Inflation Reduction Act domestic content provisions:Federally funded infrastructure projects now mandate domestic sourcing for concrete treatment chemicals, accelerating qualification of regional formulators.
- Bridge deck chloride ingress specifications:State transportation agencies in coastal zones are mandating penetrating sealers for reinforced concrete superstructures exposed to de-icing salts.
- Silane-siloxane hydrophobic technology:Spray-application efficiency on horizontal surfaces is displacing roller-applied coatings in highway maintenance contracts.
Market Restraints
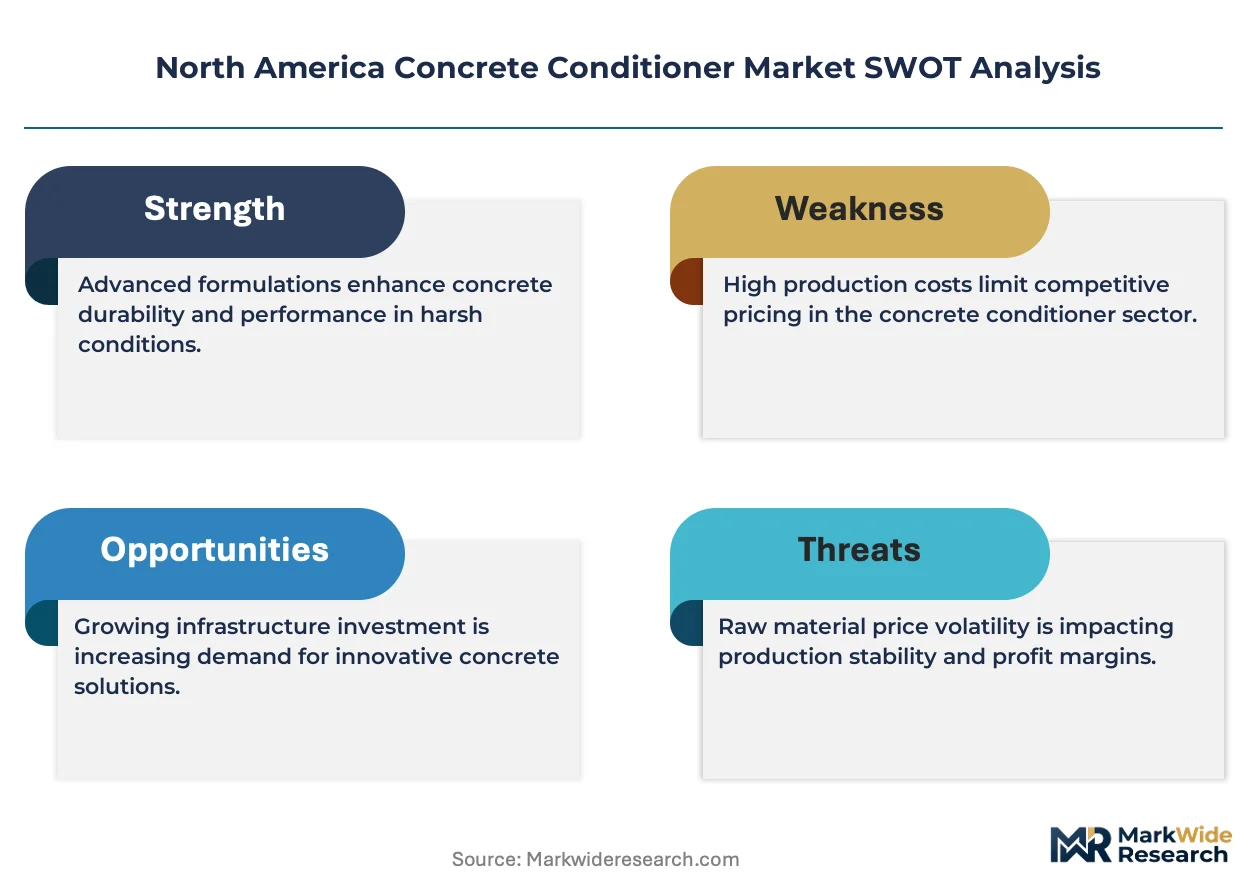
- Petrochemical feedstock volatility:Acrylic copolymer emulsions depend on propylene derivatives subject to Gulf Coast refinery output fluctuations.
- Formulation concentration in Midwest chemical manufacturing:Bulk liquid additive production clusters around Chicago and Houston corridors, creating hurricane and logistics exposure.
- Freeze-thaw performance ceiling:Lithium silicate densifiers show diminished efficacy below minus 25 degrees Celsius, constraining Canadian Prairie applications.
Strategic Opportunities
- Quebec infrastructure rehabilitation backlog:Provincial concrete bridge inventory exceeds 50 years average age, creating specification pull for penetrating sealers.
- Industrial containment chemical resistance tier:Petrochemical facilities along the US Gulf Coast are specifying high-build epoxy-modified conditioners for secondary containment.
- Subscription-based reapplication protocols:Asset management firms are bundling initial treatment with scheduled maintenance, shifting revenue from product to service.
Industry Challenges
- Certified applicator pipeline:SSPC and ICRI surface preparation credentials require 18-month training cycles, constraining contractor capacity during peak construction seasons.
- Legacy specification inertia:Municipal procurement departments retain ASTM C309 membrane-curing compound language, delaying adoption of penetrating silane alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Concrete Conditioner Market |
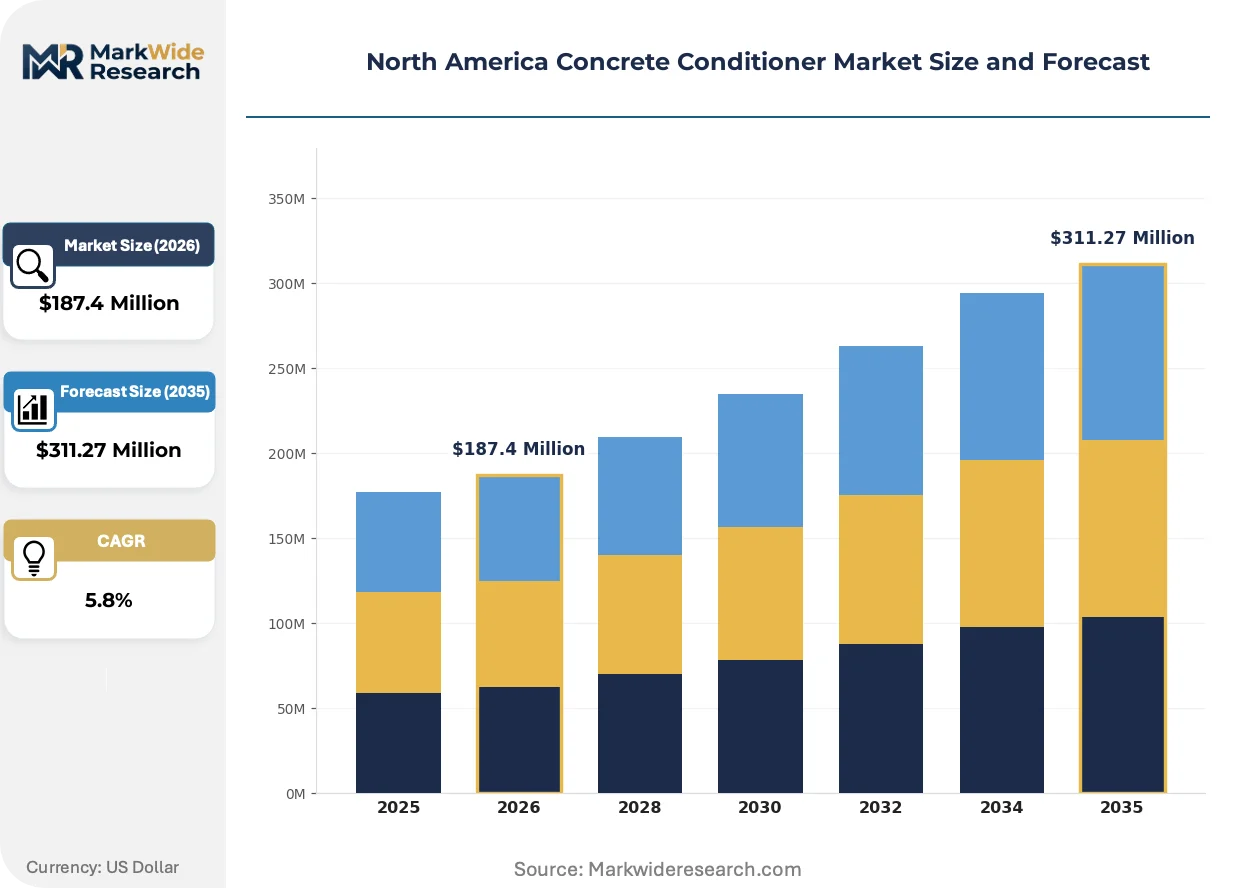
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Additives, Powder Additives, Films, Coatings Application: Residential Pouring, Commercial Pouring, Industrial Use, Road Construction End User: Construction Companies, Contractors, DIY Enthusiasts, Government Agencies Distribution Channel: Online Retailers, Home Improvement Stores, Specialty Shops, Direct Sales |
| Companies Covered | Fosroc International Limited, MAPEI Corporation, BASF SE, The Euclid Chemical Company, RPM International Inc., Sika AG, W. R. Meadows, Inc., LATICRETE International, Inc., GCP Applied Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Concrete Conditioner Market Evolving Landscape
Formulation chemistry and procurement architecture are diverging simultaneously. Manufacturers are pursuing VOC-compliant waterborne systems while buyers restructure contracts around performance guarantees rather than material volumes.
Nano-modified lithium silicate densifiers are integrating photocatalytic titanium dioxide for air-purifying surface functionality. Transit authorities in California and Texas are piloting these treatments on urban bus terminals and parking structures. The technology is integrating air quality mandates into concrete maintenance budgets, expanding addressable spend beyond traditional waterproofing.
EPA 40 CFR Part 59 VOC regulations are eliminating solvent-based silane carriers from federal and state contracts. Formulators are migrating to exempt-compound alcohol carriers and waterborne emulsion platforms. The regulatory pressure is compressing product development timelines, with manufacturers submitting amended SDS packages to approved product lists ahead of 2025 specification cycles.
State agencies are consolidating conditioner procurement through cooperative purchasing agreements, displacing individual municipal RFP processes. The Texas Department of Transportation and California DOT are pooling specifications for penetrating sealers, reducing supplier qualification overhead. This concentration is visible most acutely in the US Southwest, where Arizona and New Mexico have adopted Caltrans-approved product lists verbatim.
North America Concrete Conditioner Market Segmentation
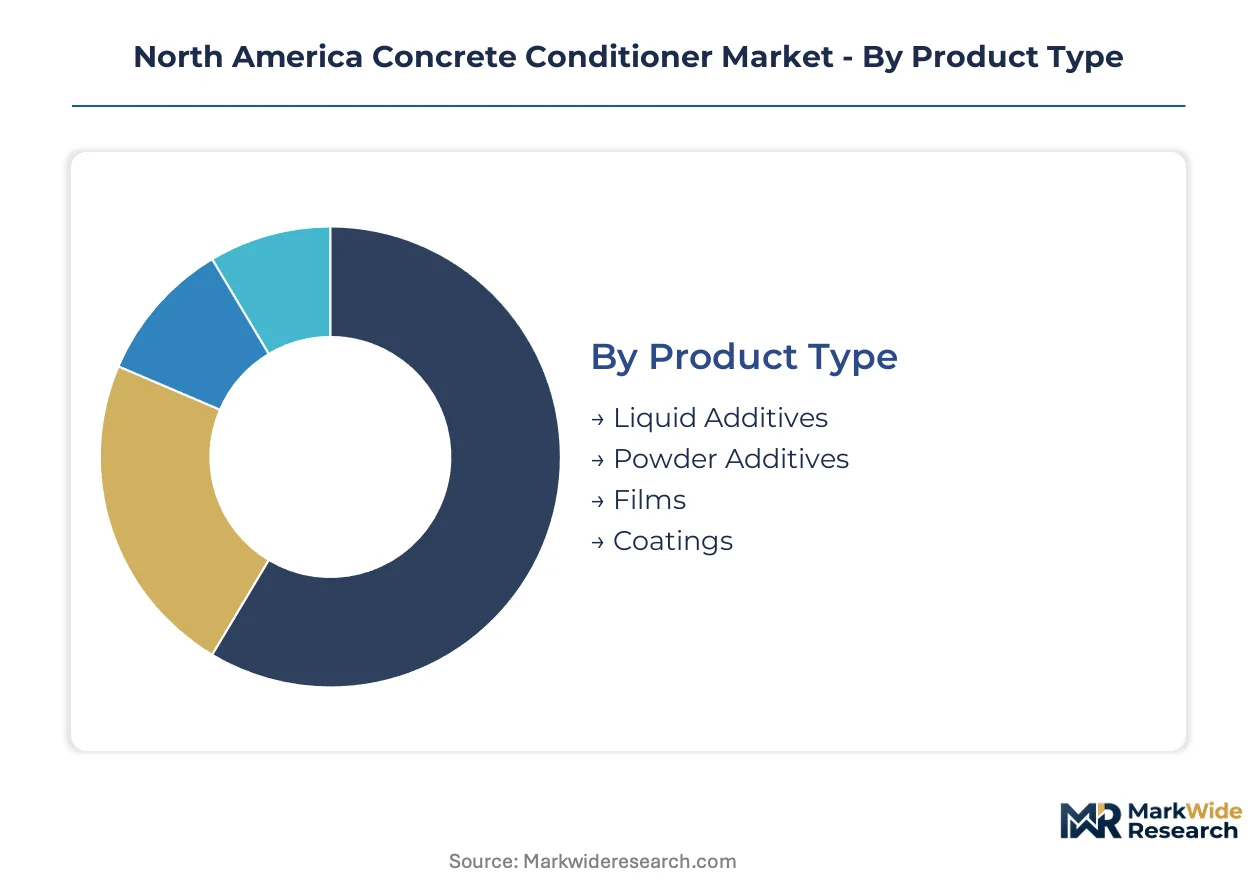
Concrete conditioner procurement patterns diverge sharply across application contexts, with infrastructure specifications demanding certified performance while residential projects prioritize application convenience. Understanding these segment boundaries clarifies where formulation investments concentrate versus where distribution efficiency drives margin capture.
Product Type:
Capital intensity clusters around liquid additive manufacturing, where continuous reactor systems and bulk storage infrastructure dominate fixed asset deployment.
- Liquid Additives:Silane-siloxane blends and lithium silicate densifiers formulated for spray-application on horizontal infrastructure surfaces. State DOT specifications in Texas and California mandate these for bridge deck chloride protection, compressing procurement into cooperative purchasing agreements.
- Coatings:High-build epoxy-modified and acrylic copolymer systems engineered for industrial containment chemical resistance. Petrochemical facilities along the US Gulf Coast specify these for secondary containment, commanding premium positioning through performance guarantees rather than material volumes.
- Powder Additives:Integral admixtures blended at ready-mix plants, requiring lower formulation equipment investment but higher logistics coordination with batching operations.
- Films:Curing membranes conforming to ASTM C309 specifications, facing displacement by penetrating sealers in municipal procurement language updates.
Liquid additives absorb the bulk of installed capacity; coatings are expanding most quickly through industrial specification upgrades.
Application:
Contract value scales determine whether procurement flows through multi-year maintenance subscriptions or spot-market material purchases.
- Road Construction:Pavement preservation contracts bundling surface treatments with scheduled reapplication protocols. The US Federal Highway Administration's Long-Term Pavement Performance program indirectly conditions state-level material approvals, consolidating spend around qualified penetrating sealers.
- Industrial Use:Secondary containment and chemical processing floor specifications requiring VOC-compliant waterborne systems under EPA 40 CFR Part 59. Canadian Prairie applications face efficacy constraints where lithium silicate densifiers perform poorly below minus 25 degrees Celsius.
- Commercial Pouring:Parking structures and bus terminals piloting nano-modified photocatalytic treatments to satisfy California and Texas air quality mandates.
- Residential Pouring:Driveway and foundation treatments purchased through home improvement retail, with application convenience outweighing technical specification density.
Road construction commands the largest contract values; industrial use is gaining share fastest through petrochemical corridor expansion.
End User:
Credential requirements fragment the applicator base, with certified contractor capacity constraining peak-season throughput for infrastructure segments.
- Government Agencies:US state DOTs and Canadian provincial agencies redirecting capital from new construction toward pavement preservation. SSPC and ICRI surface preparation credentials require 18-month training cycles, limiting qualified contractor availability.
- Construction Companies:Large-scale pour operations integrating liquid additives directly at ready-mix plants, leveraging bulk procurement relationships with Midwest and Houston corridor manufacturers.
- Contractors:Regional concrete repair specialists sourcing through specialty distribution partnerships, competing on application speed and warranty terms.
- DIY Enthusiasts:Small-volume purchasers driving retail packaging formats and waterborne emulsion accessibility for residential film applications.
Government agencies dominate specification-setting authority; construction companies are expanding fastest through ready-mix integration.
Distribution Channel:
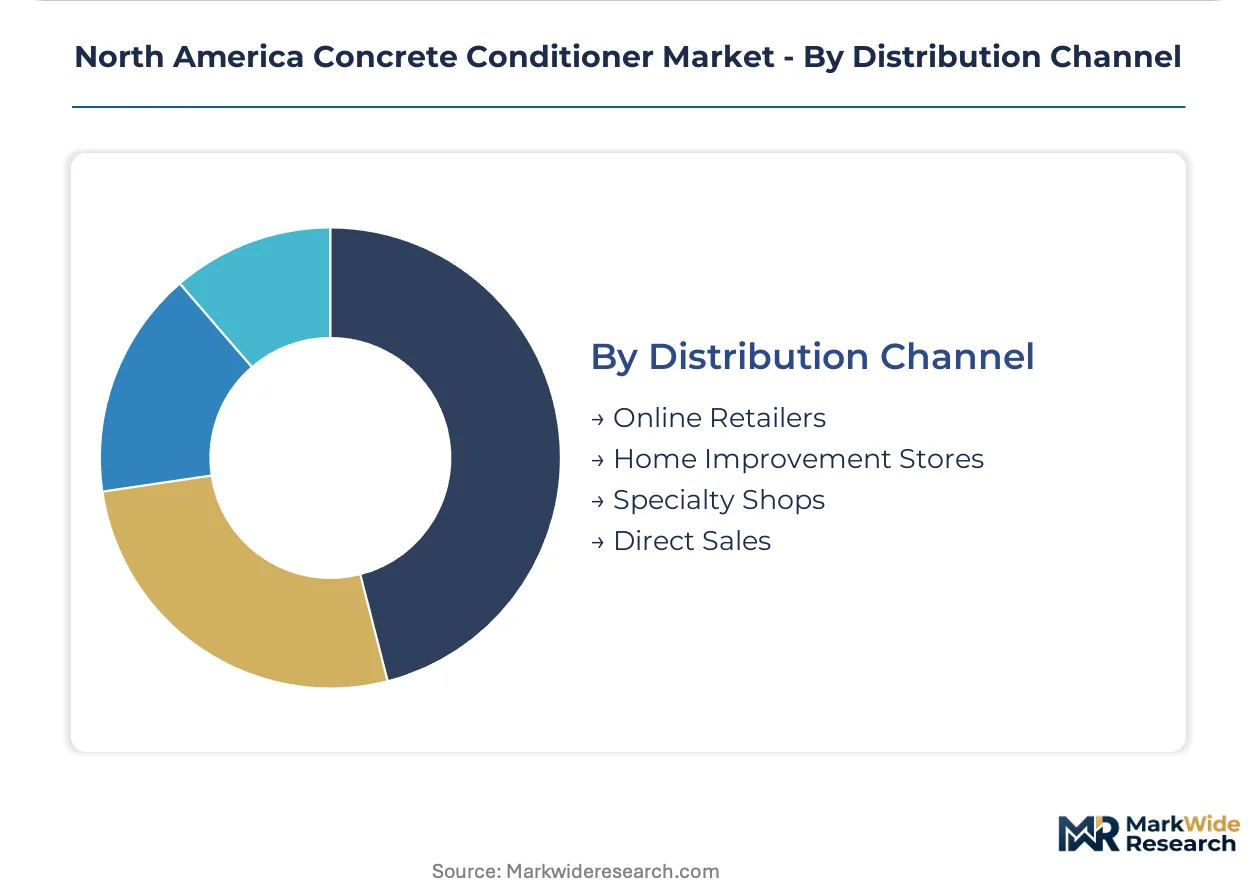
Channel selection tracks project scale and specification complexity, with direct sales capturing infrastructure volume while retail serves uncontracted demand.
- Direct Sales:Bulk liquid additive supply from formulators to ready-mix plants and state DOT cooperative purchasing agreements. Domestic content provisions in the US Inflation Reduction Act accelerate qualification of regional formulators for federal awards.
- Specialty Shops:Technical product support and certified applicator training for penetrating sealer specifications in coastal zone bridge deck restoration.
- Home Improvement Stores:Film and coating retail for residential and light commercial projects, with VOC-compliant waterborne systems displacing solvent-based inventory.
- Online Retailers:Emerging channel for specification-grade product access in remote Canadian Prairie markets underserved by specialty distribution.
Direct sales capture the majority of volume tonnage; specialty shops are climbing the fastest through specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest chemical manufacturing corridors supply bulk liquid additives to infrastructure projects across the continent, while Gulf Coast petrochemical clusters drive demand for industrial containment specifications. Canadian Prairie provinces and Mexican border states absorb conditioning chemicals through distinct procurement channels shaped by climate exposure and federal funding access.
United States
State DOTs in Texas and California consolidate penetrating sealer procurement through cooperative purchasing agreements that pool specifications and reduce supplier qualification overhead. The Federal Highway Administration's Long-Term Pavement Performance program indirectly conditions material approvals, compressing procurement cycles toward qualified silane-siloxane blends. The US Gulf Coast petrochemical corridor—spanning Houston to Lake Charles—specifies high-build epoxy-modified conditioners for secondary containment, commanding premium positioning through performance guarantees.
Canada
Provincial agencies in Quebec and Ontario redirect capital toward bridge deck restoration as concrete inventory exceeds 50 years average age, creating specification pull for chloride-resistant treatments. Health Canada's PMRA regulates VOC content in surface preparation chemicals, pushing formulators toward exempt-compound carriers. The Prairie Provinces—Manitoba, Saskatchewan, Alberta—face efficacy constraints where lithium silicate densifiers perform poorly below minus 25 degrees Celsius, narrowing applicable chemistry ranges.
Mexico
Northern border states—Chihuahua, Nuevo León, Tamaulipas—absorb conditioning chemicals through cross-border contractor networks serving maquiladora industrial parks and federally funded highway rehabilitation. The Secretariat of Infrastructure, Communications and Transportation (SICT) adopts ASTM-equivalent specifications for pavement preservation contracts, easing US product registration. Mexico City Metro's urban bus terminals pilot photocatalytic surface treatments to satisfy local air quality mandates, expanding addressable spend beyond traditional waterproofing.
North America Concrete Conditioner Market Competitive Landscape
Capital-heavy producers with continuous reactor systems and bulk storage infrastructure compete with asset-light formulators outsourcing manufacturing to toll operators. The vendor base concentrates around Midwest and Houston corridor chemical manufacturing, with tiering between multinational diversified suppliers and regional specialists focused on penetrating sealer niches. Three archetypes dominate: diversified chemical conglomerates leveraging manufacturing scale, specialty distribution-anchored repair specialists, and formulation-focused innovators pursuing VOC-compliant waterborne platforms. Competitive moves center on qualification for state DOT approved product lists and backward integration into captive silane-siloxane feedstock supply.
Within the diversified chemical tier, BASF SE and Sika AG occupy positions shaped by manufacturing footprint breadth and distribution channel control. BASF anchors supply relationships directly with ready-mix plants across the Midwest, while Sika sits within specialty distribution partnerships with regional concrete repair contractors. MAPEI Corporation represents the formulation-breadth archetype, sustaining R&D positioning in VOC-compliant penetrating sealers without vertical integration into upstream chemical production.
| Leading Market Players |
|---|
| Fosroc International Limited |
| MAPEI Corporation |
| BASF SE |
| The Euclid Chemical Company |
| RPM International Inc. |
| Sika AG |
| W. R. Meadows, Inc. |
| LATICRETE International, Inc. |
| GCP Applied Technologies Inc. |
| Others |
Value Network & Pricing Analysis
State DOT cooperative purchasing agreements are compressing procurement cycles and forcing suppliers to absorb certification costs upfront, squeezing margin structures while rewarding formulators with approved product list status. The US Inflation Reduction Act's domestic content mandates further reshape supplier economics by disqualifying imported feedstocks from federal awards.
Pricing Analysis
Margin tightening in liquid additives reflects EPA 40 CFR Part 59 compliance costs and silane-siloxane feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates high-build epoxy-modified systems for Gulf Coast petrochemical containment from spray-applied penetrating sealers and ASTM C309 membrane films. Pricing pressure stems from cooperative purchasing concentration in Texas and California, which strips brand premiums from qualified products. DIY enthusiasts exhibit highest price sensitivity; industrial containment buyers prioritize performance guarantees over unit cost.
Supply Chain Analysis
US Inflation Reduction Act domestic content provisions are accelerating regional formulator qualification and reshaping raw material sourcing away from Asian silane intermediates. Manufacturing concentrates in the United States, specifically Chicago and Houston chemical corridors, with Canadian toll blending for Prairie Provinces distribution. Propylene derivatives for acrylic copolymers, silane-siloxane intermediates, and lithium silicate precursors constitute critical input dependencies. Hurricane exposure along the Gulf Coast creates single-source vulnerability for bulk liquid additive production. Distribution runs through direct sales to ready-mix plants and state DOT cooperative agreements, with specialty shops handling certified applicator training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA 40 CFR Part 59 VOC regulations erect a compliance moat that favors incumbents with amended SDS packages already lodged on approved product lists, while marginalizing solvent-based formulators lacking waterborne R&D investment.
For Market Incumbents: Extend specification capture by embedding photocatalytic titanium dioxide functionality into lithium silicate densifiers for California and Texas air quality mandates. Deepen captive supply of silane-siloxane feedstocks through backward integration into Gulf Coast chemical manufacturing to hedge propylene derivative volatility. Secure SSPC and ICRI training partnerships to lock up certified applicator capacity ahead of peak construction seasons. For New Entrants and Emerging Players: Quebec provincial bridge deck rehabilitation programs represent an underserved buyer archetype with specification pull for chloride-resistant penetrating sealers and limited incumbent saturation. Target online retail channels in Canadian Prairie markets where specialty distribution gaps create direct access to remote contractors. Lead with VOC-compliant waterborne emulsion platforms to bypass legacy solvent-based specification inertia in municipal procurement departments. For Investors and Strategic Acquirers: The window for entry favors formulation-focused innovators with exempt-compound alcohol carrier expertise and Health Canada PMRA registration pathways. Long-term viability hinges on qualification for state DOT approved product lists rather than manufacturing scale alone. Monitor domestic-content threshold evolution in federal infrastructure awards as the inflection signal for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Feedstocks | Captive supply of propylene derivatives hedges Gulf Coast refinery output volatility for formulators. |
| Photocatalytic Surface Treatment Development | Titanium dioxide integration expands addressable spend into California and Texas air quality compliance budgets. |
| Certified Applicator Training Partnerships | SSPC and ICRI credential pipelines constrain peak-season contractor capacity for infrastructure segments. |
| Quebec Infrastructure Rehabilitation Entry | Provincial bridge inventory exceeding 50 years average age creates specification pull for penetrating sealers. |
| Cooperative Purchasing Agreement Qualification | Texas and California DOT pooled specifications reduce supplier qualification overhead and compress procurement cycles. |
Research Methodology
US Federal Highway Administration Long-Term Pavement Performance program documentation, EPA 40 CFR Part 59 regulatory filings, and state DOT approved product list databases formed the secondary backbone for demand-side quantification. Primary interviews with ready-mix plant procurement managers, regional concrete repair contractors, SSPC-certified applicators, and chemical manufacturing R&D directors validated specification trends and pricing dynamics. Bottom-up and top-down triangulation reconciled volume flows from cooperative purchasing agreements with capacity utilization rates across Midwest and Houston corridor production facilities.
Bottom-up modeling anchored forecasts in segment-level penetration rates for silane-siloxane blends, lithium silicate densifiers, and epoxy-modified systems across road construction, industrial containment, commercial pouring, and residential applications. Top-down cross-checks applied macro infrastructure spending trajectories from US and Canadian federal budget allocations. CAGRs derived from regression analysis of historical specification adoption curves and projected DOT pavement preservation contract awards. Key inputs included Health Canada PMRA registration timelines, freeze-thaw performance thresholds for Prairie Province applications, and domestic-content compliance thresholds in federal awards.
Revisions become necessary when EPA VOC regulatory amendments accelerate solvent-based formulation phase-outs, when hurricane disruption exceeds historical Gulf Coast refinery outage patterns, or when state DOTs abandon cooperative purchasing for decentralized municipal RFP processes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Europe Particle Board Market