
 Australia Artificial Organs and Bionic Implants Market | 2026-2036
Australia Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Artificial Organs and Bionic Implants Market Outlook
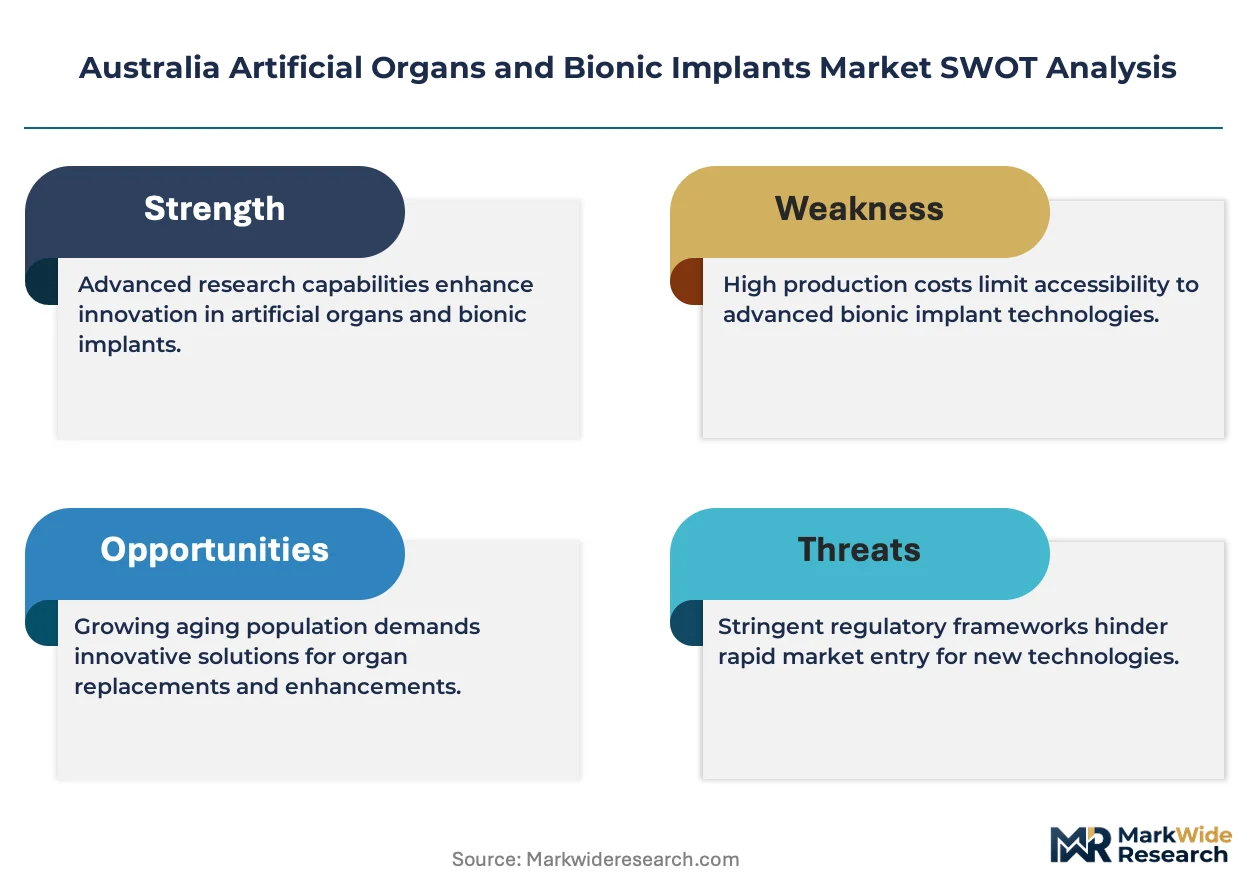
Biomedical engineering talent is rotating toward neuroprosthetics and bioelectronics specializations, tightening supply for cardiac implant manufacturers. Cochlear Ltd leverages its Sydney-based R&D campus to sustain leadership in auditory implant innovation. Medtronic PLC anchors its Asia-Pacific distribution strategy through Melbourne logistics hubs. Boston Scientific Corp competes in renal device segments by controlling specialized dialysis access product lines.
Artificial organs and bionic implants comprise electromechanical or biologically integrated systems designed to replace or augment native physiological functions, typically incorporating biocompatible alloys, polymer substrates, and embedded microelectrode arrays for signal transduction. These devices restore motor, sensory, or metabolic capabilities in patients with organ failure, traumatic injury, or degenerative conditions. Cardiac implants occupy the largest revenue pool among product types due to established reimbursement for pacemakers and ventricular assist devices, while neuroprosthetics represent the fastest-expanding category driven by spinal cord stimulation and brain-computer interface development. Bioelectronics technology commands premium margins over conventional biomaterials as manufacturers integrate closed-loop feedback systems and wireless power transfer.
TGA regulates pre-market assessment of implantable medical devices through its conformity assessment procedures, while ISO 14155 governs clinical investigation standards for bionic implant trials conducted in Australian hospitals. The Therapeutic Goods Administration's alignment with EU MDR transition timelines is compressing approval cycles for manufacturers with existing CE marking. Health Technology Assessment processes through the Medical Services Advisory Committee determine reimbursement eligibility for novel artificial organs, directly shaping hospital procurement volumes. Stakeholders must monitor TGA's evolving software-as-a-medical-device guidance for AI-enabled bionic systems.
Market Dynamics
Biomedical engineering talent is rotating toward neuroprosthetics and bioelectronics specializations, tightening supply for cardiac implant manufacturers and compressing development timelines for established device categories.
Growth Catalysts
- TGA Breakthrough Device Pathway:The Therapeutic Goods Administration's expedited review for novel bionic systems is accelerating market entry for spinal cord stimulators and brain-computer interfaces.
- Metropolitan Hospital Clusters:Concentrated demand in Sydney and Melbourne creates economies of scale for implant procurement and specialized surgical training programs.
- Closed-Loop Bioelectronics:Integration of wireless power transfer and real-time feedback systems is expanding addressable patient populations beyond conventional device limitations.
Market Restraints
- Biocompatible Alloy Supply Concentration:Dependence on specialized titanium and cobalt-chrome suppliers exposes manufacturers to input cost volatility and long lead times.
- ISO 14155 Compliance Burden:Clinical investigation standards for bionic implant trials impose extended validation periods that delay product commercialization.
- Reimbursement Gatekeeping:Medical Services Advisory Committee assessments create uncertainty for novel artificial organ categories without established health economic evidence.
Strategic Opportunities
- Regional Victoria Expansion:Aging population clusters outside Melbourne present underpenetrated demand for renal and cardiac implant services.
- AI-Enabled Bionic Systems:TGA's evolving software-as-a-medical-device guidance creates regulatory runway for adaptive neuroprosthetics with machine learning components.
- Telehealth Integration:Remote monitoring capabilities for implantable devices open new service revenue streams through digital health platform partnerships.
Industry Challenges
- Microelectrode Array Fabrication Expertise:Scarcity of specialized cleanroom technicians and MEMS engineers constrains production scaling for advanced neuroprosthetics.
- EU MDR Alignment Complexity:TGA's convergence with European medical device regulations requires dual compliance investments from manufacturers with existing CE marking.
- Legacy System Interoperability:Integration of next-generation wireless implants with hospital IT infrastructure demands costly cybersecurity and data protocol upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Artificial Organs and Bionic Implants Market |
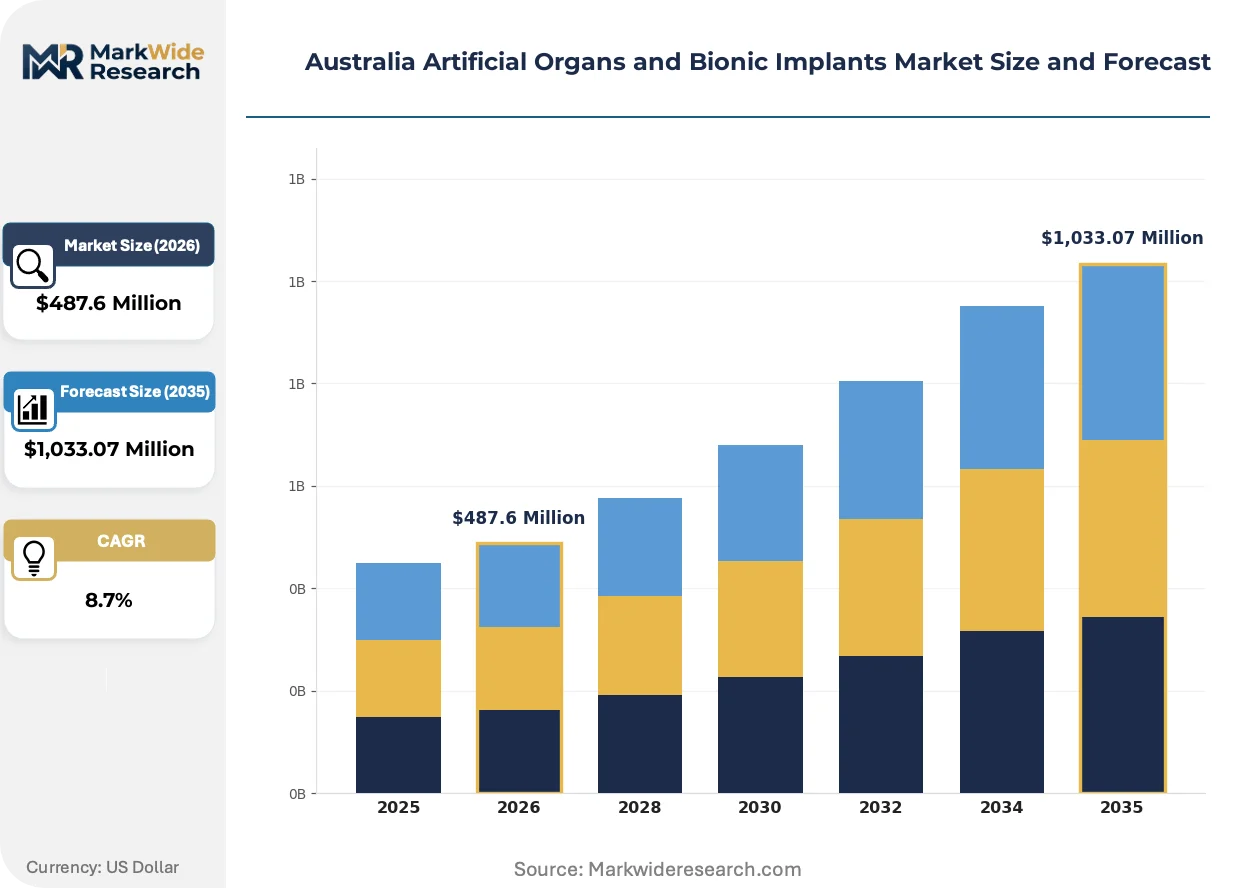
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Implants, Renal Devices, Neuroprosthetics, Ophthalmic Implants Technology: Biomaterials, Robotics, Microelectronics, Bioelectronics End User: Hospitals, Rehabilitation Centers, Homecare, Research Institutions Application: Trauma Care, Chronic Disease Management, Cosmetic Surgery, Reconstruction Surgery |
| Companies Covered | Cochlear Ltd, Bionic Vision Technologies, Abiomed Inc, LivaNova PLC, Össur hf, Medtronic PLC, Zimmer Biomet Holdings Inc, Boston Scientific Corp, Edwards Lifesciences Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Artificial Organs and Bionic Implants Market Strategic Shifts
Bioelectronics technology is commanding premium margins as manufacturers integrate closed-loop feedback systems, while regulatory alignment and procurement evolution are compressing traditional commercialization pathways.
Polymer substrate platforms with embedded conductive traces are decomposing the traditional metal-housing dominance in implantable pulse generators. Cardiac rhythm management departments in New South Wales public hospitals are piloting these flexible form factors for pediatric and anatomically challenging cases. The shift is decomposing established supply relationships with conventional titanium enclosure suppliers and enabling miniaturization trajectories previously blocked by material constraints.
TGA's alignment with EU MDR transition timelines is compressing approval cycles for manufacturers with existing CE marking while raising barriers for first-time entrants. The convergence eliminates redundant technical documentation requirements but demands updated quality management system certifications. Spinal cord stimulation devices face the steepest compliance adjustment due to reclassification under higher risk categories.
Hospital procurement committees are consolidating vendor relationships through multi-year implant supply agreements that bundle devices with surgical training and remote monitoring services. This concentration is displacing transactional purchasing through distributor networks in Queensland and Western Australia. The model shift favors manufacturers with integrated service capabilities and captive clinical education infrastructure.
Australia Artificial Organs and Bionic Implants Market Segmentation
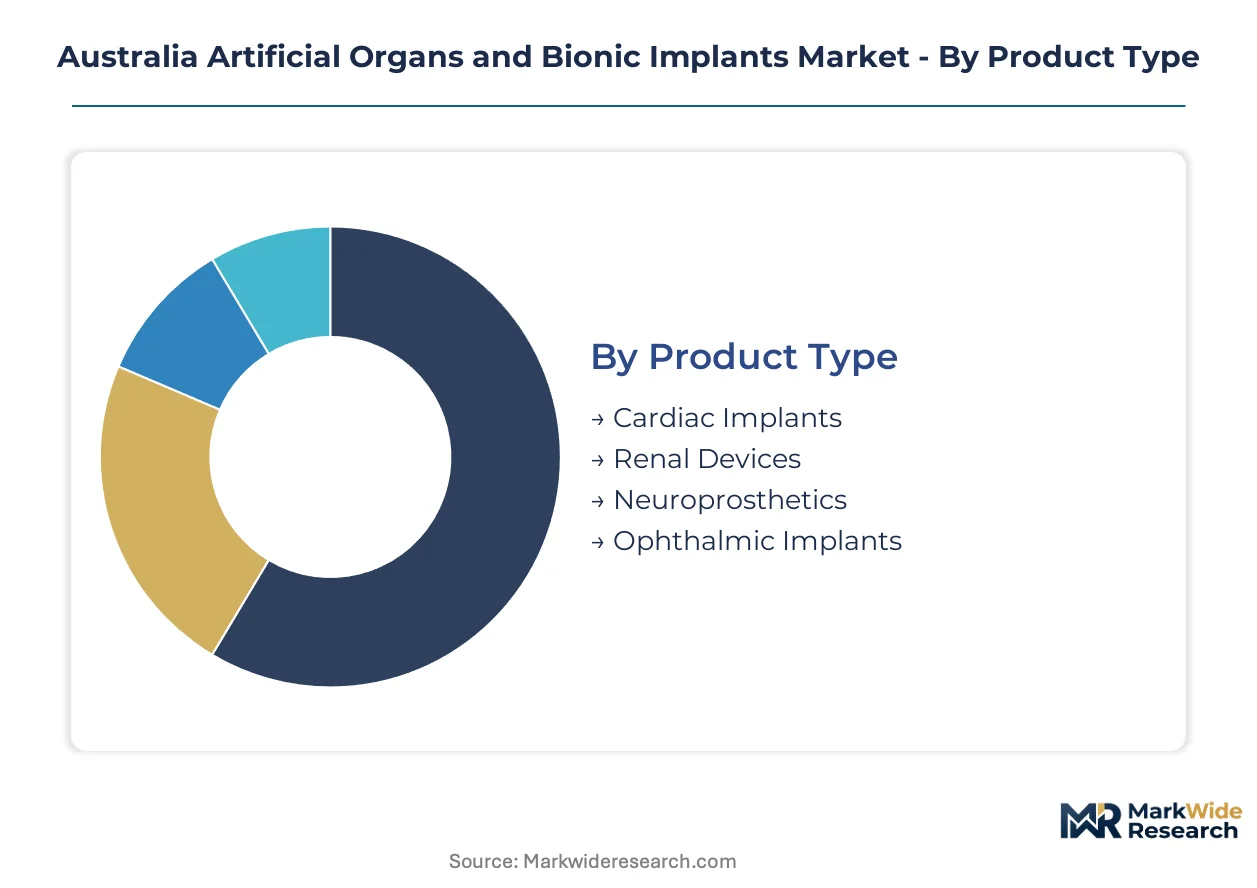
Segmentation reveals where procurement power and margin concentration diverge across Australia's artificial organs and bionic implants landscape. Hospital procurement committees weight product type and technology tier differently when evaluating long-term supply agreements versus spot purchasing.
Product Type:
Margin pools concentrate in cardiac and neuroprosthetic categories where TGA breakthrough pathways and specialized surgical training create pricing power.
- Cardiac Implants:Pacemakers and ventricular assist devices incorporate biocompatible titanium enclosures with embedded microelectrode arrays. Procurement in New South Wales and Victoria public hospital systems drives volume concentration, though reimbursement certainty through Medical Services Advisory Committee assessments constrains price elasticity.
- Neuroprosthetics:Spinal cord stimulators and brain-computer interfaces command premium positioning through closed-loop feedback architectures. Melbourne metropolitan hospital clusters generate concentrated demand as specialized neurosurgical programs expand implantable pulse generator volumes.
- Renal Devices:Dialysis access systems and artificial kidney prototypes serve chronic kidney disease populations across regional Victoria expansion zones.
- Ophthalmic Implants:Retinal prostheses and artificial corneas address degenerative vision conditions in Sydney's aging demographic corridors.
Cardiac implants hold installed capacity. Neuroprosthetics is rotating up the share rankings.
Technology:
Technology tier determines compliance burden and manufacturing complexity, with bioelectronics facing steeper TGA scrutiny than conventional biomaterials.
- Bioelectronics:Wireless power transfer and real-time signal processing enable adaptive therapeutic responses. TGA's software-as-a-medical-device guidance creates regulatory runway for machine learning-enabled systems in Sydney and Melbourne hospital pilots.
- Microelectronics:MEMS fabrication and microelectrode array integration constrain production scaling due to cleanroom technician scarcity. Queensland procurement committees prioritize these devices for pediatric applications where miniaturization determines surgical feasibility.
- Biomaterials:Polymer substrates with conductive traces decompose traditional metal-housing dominance in implantable pulse generators.
- Robotics:Surgical robotic interfaces for implant placement are gaining traction in Western Australia tertiary centers.
Bioelectronics captures the steepest expansion trajectory. Biomaterials maintains volume leadership through established supply relationships.
End User:
End user structure reflects care setting migration and reimbursement pathway fragmentation across Australian health jurisdictions.
- Hospitals:Tertiary centers in Sydney and Melbourne dominate complex implant procedures requiring specialized surgical infrastructure. Multi-year supply agreements bundling devices with training and remote monitoring services are displacing transactional purchasing.
- Rehabilitation Centers:Post-implant functional training and device programming services generate recurring revenue streams. Victoria's regional expansion creates underpenetrated demand for neuroprosthetic rehabilitation protocols.
- Homecare:Remote monitoring capabilities for cardiac and neuroprosthetic devices open digital health platform partnerships.
- Research Institutions:Clinical investigation standards under ISO 14155 govern trial conduct for novel bionic systems.
Hospitals anchor procurement volume. Homecare is climbing the fastest as telehealth integration accelerates.
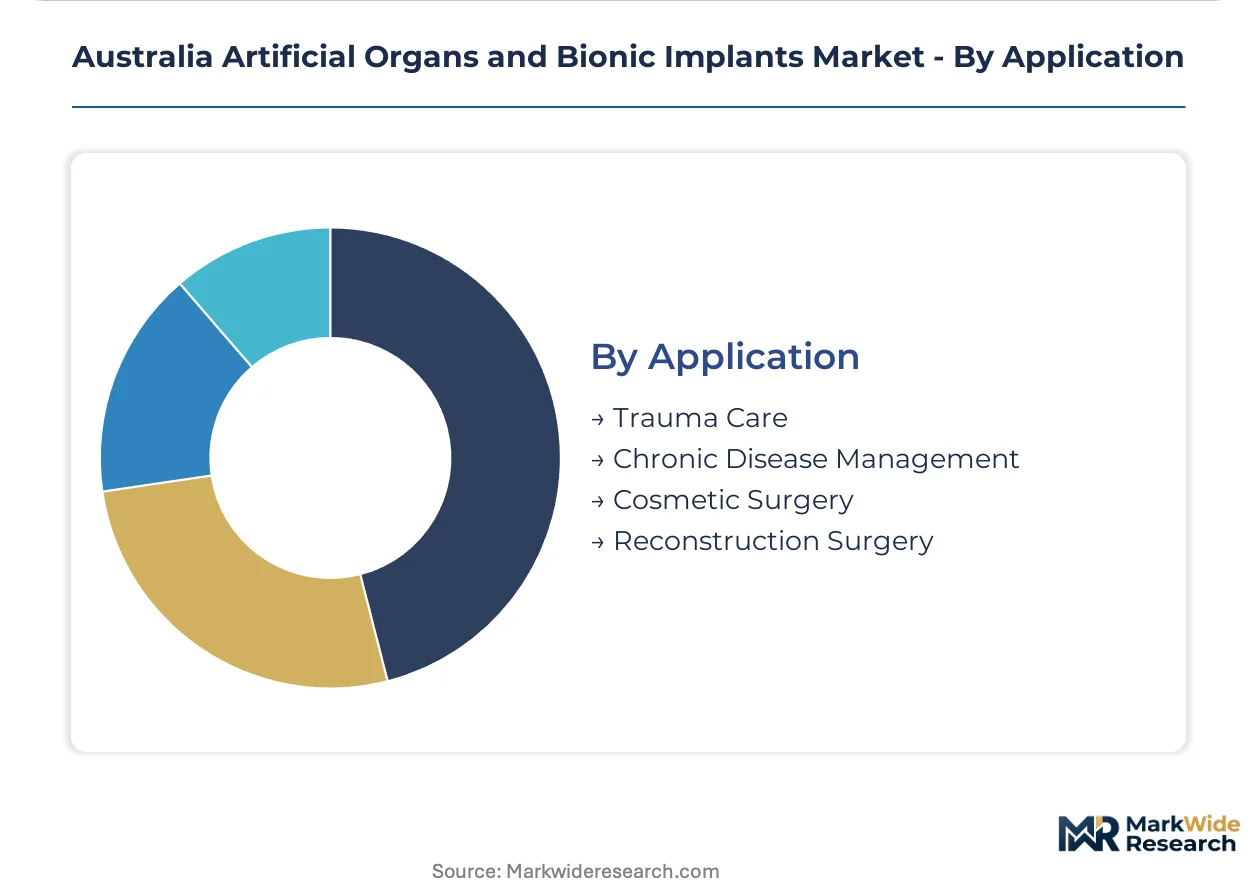
Application:
Application focus determines regulatory pathway length and health economic evidence requirements for reimbursement eligibility.
- Chronic Disease Management:Long-term implant therapy for heart failure, renal dysfunction, and neurodegenerative conditions generates predictable replacement cycles. Australia's aging population clusters in metropolitan Melbourne and Sydney concentrate addressable patient populations.
- Trauma Care:Acute implant deployment following traumatic injury requires rapid procurement protocols and surgeon training availability. New South Wales public hospital emergency departments prioritize these capabilities.
- Reconstruction Surgery:Post-oncologic and post-traumatic anatomical restoration utilizes custom implant geometries.
- Cosmetic Surgery:Elective aesthetic implants face private payment constraints without public reimbursement support.
Chronic disease management holds procedure volume. Trauma care is gaining share fastest through emergency department integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Sydney and Melbourne concentrate cardiac implant consumption through tertiary hospital networks, while regional Victoria and Queensland exhibit divergent demand patterns favoring renal devices and trauma-care applications.
New South Wales
Public hospital procurement in Sydney drives pacemaker and ventricular assist device volumes through established reimbursement pathways. TGA breakthrough device designations for spinal cord stimulators accelerate regulatory entry for neuroprosthetic innovators. The Westmead Health Precinct anchors specialized implant surgical training and clinical investigation protocols.
Victoria
Melbourne metropolitan clusters generate concentrated demand for brain-computer interfaces and cochlear implant services. Medical Services Advisory Committee assessments determine reimbursement eligibility for novel bionic categories entering Victorian hospital formularies. Regional expansion zones outside Geelong and Ballarat present underpenetrated demand for dialysis access systems.
Queensland
Brisbane tertiary centers prioritize pediatric microelectronic implants where miniaturization determines surgical feasibility. ISO 14155 clinical investigation standards govern trial conduct for novel renal devices across Queensland Health jurisdictions. The Gold Coast University Hospital corridor concentrates trauma-care implant deployment capabilities.
Western Australia
Perth-based surgical robotic interfaces for implant placement gain traction in resource-intensive tertiary settings. State health procurement committees evaluate multi-year supply agreements bundling devices with remote monitoring services. The Fiona Stanley Hospital network pilots closed-loop bioelectronics for chronic disease management populations.
South Australia
Adelaide metropolitan hospitals concentrate ophthalmic implant procedures for degenerative vision conditions. TGA software-as-a-medical-device guidance creates regulatory runway for AI-enabled bionic pilots in South Australian public health networks. The Royal Adelaide Hospital anchors specialized neuroprosthetic rehabilitation protocols.
Australia Artificial Organs and Bionic Implants Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational device manufacturers controlling distribution infrastructure while regional innovators capture niche neuroprosthetic segments. The market structure favors players with captive clinical education capabilities and multi-year hospital supply contracts. Three archetypes dominate: Asia-Pacific distribution anchors, auditory implant specialists, and cardiac rhythm management integrators. Competitive moves center on bundling surgical training with device procurement and securing TGA breakthrough designations for novel bioelectronic categories.
Within the integrated multinational tier, Medtronic PLC and Boston Scientific Corp exemplify distribution-heavy positioning through Melbourne logistics hubs and bundled service offerings. Cochlear Ltd occupies a distinct archetype as a Sydney-based R&D anchor leveraging proximity to specialized surgical clusters. These three represent contrasting strategic positions: distribution scale, auditory specialization, and regional innovation capture.
| Leading Market Players |
|---|
| Cochlear Ltd |
| Bionic Vision Technologies |
| Abiomed Inc |
| LivaNova PLC |
| Össur hf |
| Medtronic PLC |
| Zimmer Biomet Holdings Inc |
| Boston Scientific Corp |
| Edwards Lifesciences Corp |
| Others |
Value Chain & Pricing Dynamics
Polymer substrate platforms with embedded conductive traces are displacing traditional titanium enclosures in implantable pulse generators, simultaneously shifting procurement geography toward Asia-Pacific polymer foundries and compressing material cost premiums for cardiac rhythm management devices. This substitution dynamic redistributes value capture from conventional metal-housing suppliers to flexible electronics manufacturers while creating tiered cost structures across pediatric and anatomically challenging implant cases.
Pricing Analysis
Long-term multi-year supply agreements bundling devices with surgical training and remote monitoring services dominate hospital procurement in New South Wales and Victoria, displacing spot purchasing through distributor networks. Price differentiation hinges on TGA breakthrough device designation status and captive clinical education infrastructure bundled with device contracts. Cost compression in standard cardiac implant tiers is intensifying because polymer substrate alternatives erode traditional titanium enclosure premiums. Public hospital procurement committees exhibit highest price sensitivity, while private tertiary centers prioritize device performance and training integration over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standardized cardiac implants, whereas strategic stockpiling of specialized biocompatible alloys and microelectrode arrays buffers against long lead times for neuroprosthetic components. Manufacturing concentration rests on Germany, Switzerland, and the United States for precision titanium and cobalt-chrome alloys, while polymer substrate fabrication feeds from South Korean and Japanese electronics suppliers. Single-source vulnerability in MEMS cleanroom capacity constrains production scaling for advanced neuroprosthetics. Distribution runs through Melbourne logistics hubs serving Asia-Pacific markets with secondary channels through Sydney-based clinical education centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement committee consolidation across New South Wales and Victoria public health systems, fragmenting vendor relationships into multi-year bundled agreements that displace transactional distributor purchasing.
For Market Incumbents: Fortify market position by deepening backward integration into polymer substrate manufacturing to capture margin migration from metal enclosures, and secure TGA breakthrough device designations for spinal cord stimulators before EU MDR alignment raises compliance barriers for first-time entrants. Threat from emerging neuroprosthetic specialists with AI-enabled adaptive systems demands preemptive certification investment in software-as-a-medical-device pathways. For New Entrants and Emerging Players: Anchor in regional Victoria's underpenetrated dialysis access market outside Melbourne metropolitan clusters, where aging population corridors lack specialized renal implant services. Target pediatric microelectronic applications in Queensland where miniaturization requirements create surgical feasibility barriers for established cardiac-focused incumbents. Partner with telehealth platform providers to bundle remote monitoring capabilities with device deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed auditory implant specialists possessing Sydney-based R&D infrastructure and captive surgical training programs. Long-term viability over the next decade hinges on regulatory runway for AI-enabled bioelectronics and reimbursement pathway expansion through Medical Services Advisory Committee assessments. Watch TGA software-as-a-medical-device guidance finalization as inflection indicator for machine learning-enabled neuroprosthetic valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Breakthrough Device Designation | Accelerates regulatory entry for spinal cord stimulators and brain-computer interfaces ahead of EU MDR alignment. |
| Hospital System Partnership | Multi-year supply agreements bundling devices with surgical training displace transactional distributor purchasing in Queensland. |
| Software Companion Development | Remote monitoring capabilities for cardiac implants open digital health platform revenue streams through telehealth integration. |
| Backward Integration into Polymers | In-house production of conductive substrate platforms captures margin migration from traditional titanium enclosure suppliers. |
| Reimbursement Strategy | Health Technology Assessment submissions through Medical Services Advisory Committee determine hospital formulary eligibility for novel categories. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineering directors, hospital procurement committee members, TGA regulatory affairs specialists, and neurosurgical program leads, then refined through secondary validation against TGA conformity assessment databases, hospital procurement contract registries, ISO 14155 clinical investigation filings, and Medical Services Advisory Committee reimbursement determinations. Bottom-up demand modeling across product type and technology tiers was triangulated with top-down market sizing from Asia-Pacific distribution channel assessments.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics and technology substitution effects. Segmentation dimensions modeled include product category, bioelectronics versus conventional biomaterial technology tier, end-user care setting, and application focus spanning chronic disease management through trauma care. CAGRs were derived from installed base replacement cycles and expansion coefficients for emerging neuroprosthetic categories, with specific inputs from TGA approval timeline compression and metropolitan hospital cluster procurement concentration patterns.
Decision-makers should treat outputs as directional under assumptions of continued TGA-EU MDR alignment and stable Medical Services Advisory Committee reimbursement pathways; material deviation would warrant model refresh. Revision becomes warranted when biocompatible alloy supply disruptions or AI-enabled device regulatory reclassification crosses threshold impact on commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Vascular Boot Market
Medical Devices
Plethysmograph Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Kirschner Wires Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Intracranial Pressure Monitors Market