
 Global Traumatic Brain Injury Assessment and Management Devices Market | 2026-2036
Global Traumatic Brain Injury Assessment and Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Traumatic Brain Injury Assessment and Management Devices Market Foresight
Portable electroencephalography and optical sensor integration is reshaping how clinicians assess traumatic brain injury at the point of care. BrainScope leverages handheld EEG-based technology to differentiate structural from functional brain injuries in emergency settings. Integra Lifesciences anchors its position through intracranial pressure monitoring systems that dominate neurocritical care workflows. Natus Medical specializes in diagnostic instrumentation that extends from bedside monitoring through post-acute rehabilitation tracking.
Traumatic brain injury assessment and management devices encompass instruments that measure intracranial pressure, capture electrical brain activity, image cerebral structures, and deliver targeted rehabilitation protocols, typically operating within precision ranges of 0-100 mmHg for pressure monitoring and 0.5-70 Hz for EEG signal acquisition. These systems serve to detect secondary brain injury, guide surgical intervention, and optimize recovery trajectories. Diagnostic imaging systems command substantial investment flows as hospitals replace aging CT and MRI fleets with AI-enhanced platforms. Intracranial pressure devices sustain entrenched demand in intensive care units where continuous monitoring prevents herniation events. Rehabilitation equipment represents an emerging margin pool as payers expand coverage for cognitive and motor recovery programs.
FDA premarket notification requirements under 21 CFR Part 882 shape device classification pathways for neurological diagnostic instruments, while the EU Medical Device Regulation imposes clinical evidence thresholds that filter market entrants. Japan's PMDA enforces Japan Industrial Standards conformity for electromagnetic compatibility in brain monitoring equipment, creating compliance costs for overseas manufacturers. Stakeholders must monitor how reimbursement coding for remote neurocritical monitoring evolves across Medicare, NHS England, and Germany's G-BA to capture shifting care delivery economics.
Market Dynamics
Portable neurological assessment tools are compressing diagnostic timelines at trauma centers, forcing incumbent device manufacturers to reconfigure product portfolios around point-of-care deployment rather than hospital-based laboratory workflows.
Growth Catalysts
- EU MDR compliance acceleration:The Medical Device Regulation's clinical evidence thresholds are filtering marginal competitors from the European market, concentrating procurement budgets among validated suppliers with robust technical documentation.
- Trauma center infrastructure expansion:Specialized neurocritical care units in the United States, Germany, and Japan are scaling continuous intracranial pressure monitoring capabilities to prevent secondary brain injury progression.
- Optical sensor miniaturization:Advances in near-infrared spectroscopy are enabling non-invasive cerebral oxygenation monitoring at bedside, reducing dependency on invasive catheter-based measurements.
Market Restraints
- Reimbursement coding fragmentation:Divergent remote neurocritical monitoring coverage policies across Medicare, NHS England, and Germany's G-BA create revenue recognition uncertainty for device vendors operating across multiple jurisdictions.
- Electromagnetic compatibility certification costs:Japan's PMDA enforces JIS standards conformity for brain monitoring equipment, imposing compliance expenditures that disproportionately burden mid-scale overseas manufacturers.
- Specialized neurocritical care workforce scarcity:The limited pool of trained intensivists capable of interpreting continuous EEG and ICP data restricts deployment velocity even where capital budgets permit equipment acquisition.
Strategic Opportunities
- Post-acute rehabilitation coverage expansion:Payers in the United States are extending reimbursement for cognitive and motor recovery programs, opening margin pools in rehabilitation equipment previously constrained to acute-care sales cycles.
- AI-enhanced diagnostic imaging replacement cycles:Hospital systems are retiring aging CT and MRI fleets, creating procurement windows for platforms integrating automated lesion detection and severity stratification algorithms.
- Handheld EEG differentiation:Emergency departments are adopting portable electroencephalography systems capable of distinguishing structural from functional brain injuries, displacing reliance on transport-dependent neuroimaging.
Industry Challenges
- FDA 510(k) pathway navigation:Premarket notification requirements under 21 CFR Part 882 for neurological diagnostic instruments demand substantial predicate device alignment efforts, compressing time-to-market for novel sensor architectures.
- Legacy neuroimaging integration complexity:New assessment devices must interface with established PACS and EMR infrastructures, requiring interoperability certification investments that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Traumatic Brain Injury Assessment and Management Devices Market |
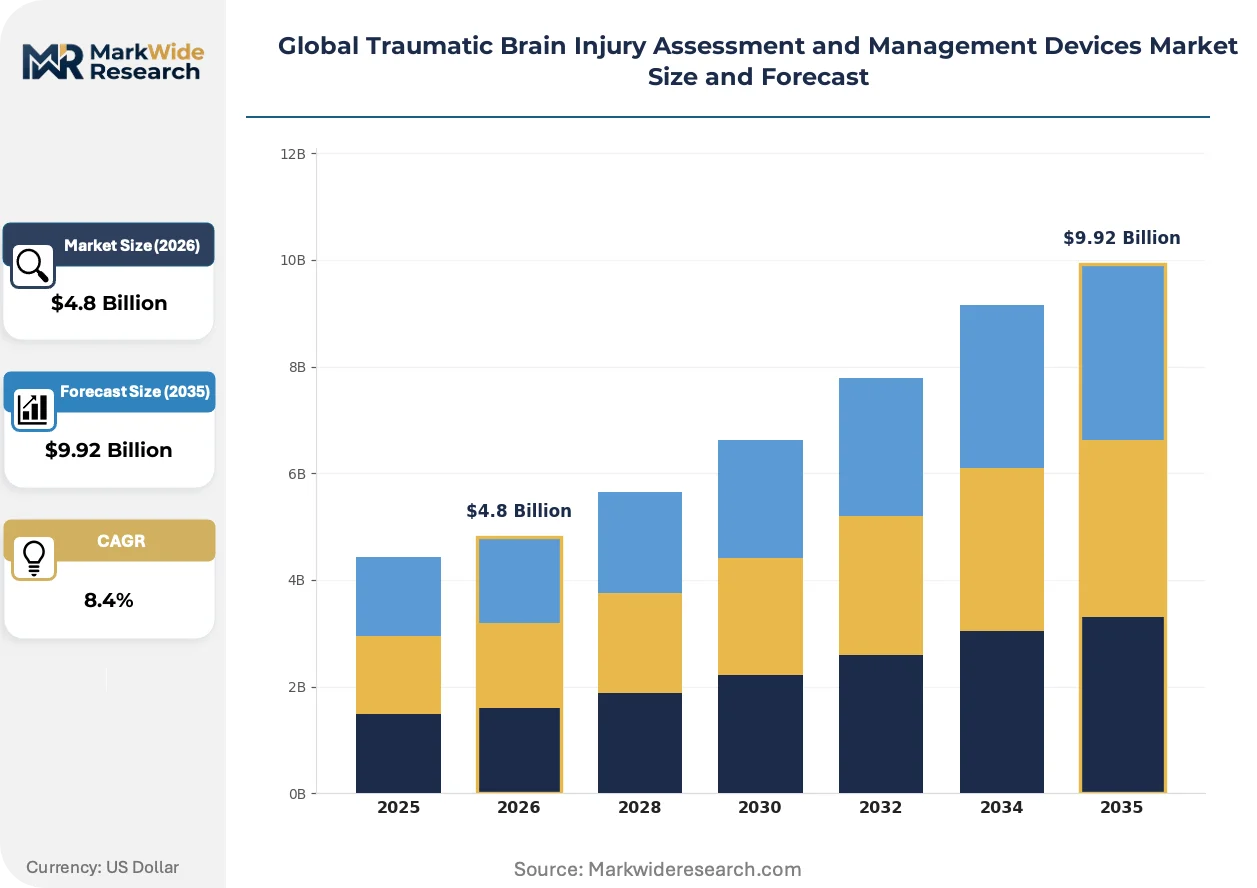
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurological Monitors, Intracranial Pressure Devices, Head Injury Telemetry, Diagnostic Imaging Systems, Rehabilitation Equipment Technology: Optical Sensors, Electroencephalography, Computed Tomography, Magnetic Resonance Imaging, Ultrasound Application: Emergency Care, Neurocritical Monitoring, Post-Treatment Evaluation, Cognitive Rehabilitation, Surgical Assistance End User: Trauma Centers, Neurorehabilitation Facilities, Intensive Care Units, Specialized Clinics, Research Laboratories |
| Companies Covered | BrainScope, Integra Lifesciences, NanoDx, Natus Medical, Elekta AB, Compumedics, Nihon Kohden Corporation, Neural Analytics, Advanced Brain Monitoring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Traumatic Brain Injury Assessment and Management Devices Market Shifts & Advancements
Artificial intelligence integration is restructuring how clinicians interpret neurological data streams, shifting diagnostic authority from specialist interpretation toward algorithm-assisted decision support at the point of injury.
Machine learning algorithms embedded in CT and MRI platforms are digitizing radiological workflow by flagging intracranial hemorrhage and mass effect indicators for priority review. Academic medical centers in the United States and university hospitals in Germany are deploying these tools to compress time-to-diagnosis for severe traumatic brain injury presentations. The technology is digitizing triage protocols by enabling non-radiologist clinicians to initiate appropriate interventions before specialist consultation.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa and above neurological devices. Manufacturers must now maintain updated technical documentation and periodic safety reporting throughout product lifecycles, elevating regulatory affairs staffing ratios. European trauma centers are responding by consolidating procurement around vendors with demonstrated post-market clinical evidence generation capabilities.
Service unbundling is separating device hardware from interpretation and maintenance contracts in neurocritical care settings. Hospital procurement departments in Japan are negotiating standalone equipment purchases while sourcing EEG reading services from specialized telemedicine providers. This pattern is most visible in metropolitan Tokyo and Osaka healthcare systems where intensivist coverage gaps create demand for remote specialist interpretation.
Global Traumatic Brain Injury Assessment and Management Devices Market Segmentation
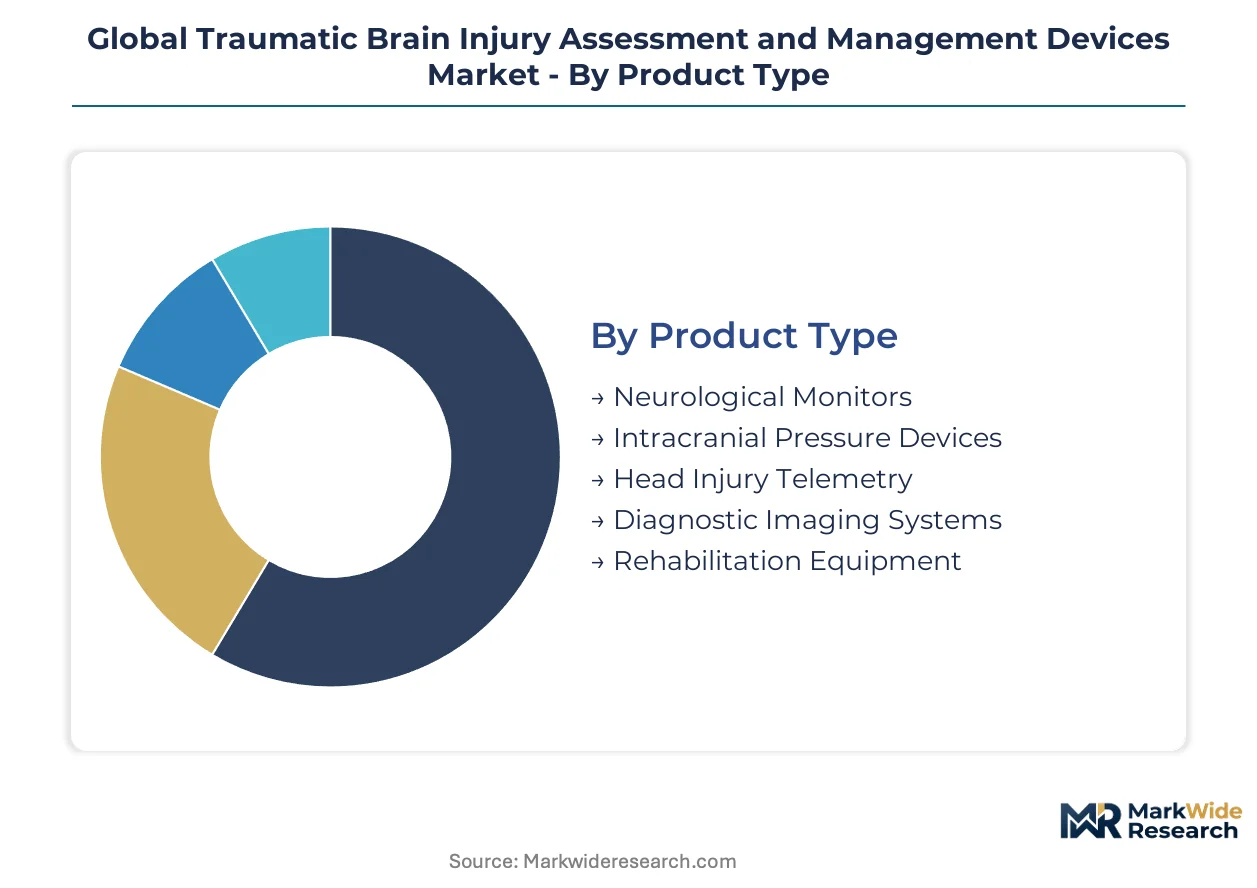
Device segmentation in traumatic brain injury assessment reveals how clinical workflows fragment across acute intervention, continuous monitoring, and recovery phases. Technology choices and procurement authority vary sharply between emergency departments managing throughput pressure and neurocritical care units optimizing long-term outcomes.
Product Type:
Mature categories dominate hospital capital budgets while emerging segments capture margin expansion from payer coverage shifts.
- Neurological Monitors:Continuous EEG and multimodal platforms tracking cerebral electrical activity, blood flow, and oxygenation through integrated sensor arrays. Demand concentrates in United States academic medical centers scaling continuous automated analysis to compensate for intensivist shortages.
- Intracranial Pressure Devices:Invasive catheter-based systems measuring ventricular or parenchymal pressure within 0-100 mmHg precision ranges to detect herniation risk. German and Japanese trauma centers sustain entrenched procurement as specialized neurocritical care infrastructure expands.
- Head Injury Telemetry:Wearable and implantable sensors transmitting real-time physiological data for ambulatory monitoring.
- Diagnostic Imaging Systems:CT and MRI platforms with AI-enhanced lesion detection for structural injury identification.
- Rehabilitation Equipment:Cognitive and motor recovery systems targeting post-acute functional restoration.
Intracranial pressure devices retain volume leadership; rehabilitation equipment holds the steepest expansion curve.
Technology:
Cost tiers separate invasive precision instrumentation from non-invasive screening modalities with broader deployment potential.
- Optical Sensors:Near-infrared spectroscopy devices measuring cerebral oxygenation and hemodynamics through skull penetration without catheter insertion. Japanese metropolitan hospitals in Tokyo and Osaka deploy these for bedside monitoring where invasive placement carries excessive risk.
- Electroencephalography:Portable and fixed systems capturing electrical brain activity across 0.5-70 Hz frequency bands to detect seizures and functional disruption. United States emergency departments adopt handheld configurations to differentiate structural from functional injuries before neuroimaging transport.
- Computed Tomography:X-ray-based cross-sectional imaging for rapid hemorrhage and fracture detection.
- Magnetic Resonance Imaging:High-resolution soft tissue imaging for diffuse axonal injury and subtle pathological changes.
- Ultrasound:Transcranial Doppler and point-of-care imaging for midline shift and blood flow assessment.
Computed tomography maintains the highest procedure volume; optical sensors are climbing the fastest.
Application:
Customer type determines whether procurement prioritizes speed, precision, or longitudinal outcome tracking.
- Emergency Care:Rapid triage and initial injury stratification protocols demanding portable, interpretation-light tools. German trauma centers integrate AI-enhanced imaging to compress time-to-diagnosis for severe presentations.
- Neurocritical Monitoring:Continuous multimodal surveillance in intensive care to prevent secondary brain injury progression. United States neuro-ICUs drive demand for integrated ICP-EEP-cerebral oxygenation platforms.
- Post-Treatment Evaluation:Structured assessment protocols tracking recovery trajectory and complication emergence.
- Cognitive Rehabilitation:Targeted interventions for memory, attention, and executive function recovery.
- Surgical Assistance:Intraoperative monitoring and navigation support for hematoma evacuation and decompressive procedures.
Neurocritical monitoring commands the largest installed base; cognitive rehabilitation shows the sharpest demand acceleration.
End User:
Procurement authority and budget source vary across facility types with distinct clinical missions and reimbursement pathways.
- Trauma Centers:Level I and II facilities managing high-acuity injury volumes with 24-hour neurosurgical coverage. United States trauma centers drive portable assessment tool adoption to reduce transfer-dependent diagnostic delays.
- Intensive Care Units:Neurocritical care units and general ICUs managing secondary injury prevention through continuous monitoring. Japanese ICUs confront workforce constraints that favor automated alarm systems and remote interpretation services.
- Neurorehabilitation Facilities:Dedicated centers for post-acute cognitive and motor recovery programs.
- Specialized Clinics:Outpatient neurology and concussion management practices.
- Research Laboratories:Academic and commercial settings developing novel biomarkers and intervention protocols.
Intensive care units anchor equipment volume; neurorehabilitation facilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision intracranial pressure monitoring systems to trauma centers across the United States and Japan, while American portable EEG innovators supply emergency departments in Germany and metropolitan Japanese hospital systems.
United States
Level I trauma centers in Baltimore and Houston deploy handheld EEG systems to compress diagnostic timelines for concussion presentations. FDA 510(k) pathways under 21 CFR Part 882 accelerate clearance for novel neurological diagnostics. The Greater Boston medical device cluster anchors development of AI-enhanced imaging platforms for automated hemorrhage detection.
Germany
University hospitals in Munich and Heidelberg scale continuous multimodal monitoring to prevent secondary brain injury progression. EU Medical Device Regulation clinical evidence thresholds filter procurement toward validated suppliers with robust technical documentation. The Baden-Württemberg precision engineering corridor manufactures catheter-based pressure measurement systems for export to neurocritical care units across Europe.
Japan
Metropolitan Tokyo and Osaka healthcare systems confront intensivist shortages through automated alarm systems and remote EEG interpretation services. PMDA enforces JIS standards conformity for electromagnetic compatibility in brain monitoring equipment. The Kansai medical technology cluster specializes in optical sensor miniaturization for non-invasive cerebral oxygenation monitoring.
United Kingdom
NHS England trauma networks in London and Manchester integrate portable assessment tools to reduce transfer-dependent diagnostic delays. Divergent remote neurocritical monitoring coverage policies create revenue recognition uncertainty for device vendors operating across jurisdictions. The Oxford-Cambridge life sciences arc develops rehabilitation equipment targeting post-acute cognitive recovery programs.
South Korea
Seoul National University Hospital and Samsung Medical Center deploy AI-enhanced CT platforms for rapid hemorrhage stratification. MFDS enforces clinical evidence requirements for Class III neurological diagnostic devices. The Seoul Capital Area medical device cluster manufactures diagnostic imaging components for integration into global OEM supply chains.
Global Traumatic Brain Injury Assessment and Management Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Multinational conglomerates with established neurocritical care portfolios leverage hospital GPO relationships to defend installed base positions. Mid-scale specialists concentrate on single-modality excellence in EEG or pressure monitoring. Emerging technology developers pursue FDA breakthrough device designation to compress regulatory timelines. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and portfolio diversification into adjacent rehabilitation segments.
Among United States-based innovators, BrainScope and Natus Medical exemplify the portable diagnostic archetype, while Integra Lifesciences anchors the established neurocritical care tier. BrainScope occupies a position within handheld EEG differentiation, Natus Medical sits within diagnostic instrumentation spanning bedside through rehabilitation settings, and Integra Lifesciences represents the invasive monitoring incumbent with entrenched ICU relationships.
| Leading Market Players |
|---|
| BrainScope |
| Integra Lifesciences |
| NanoDx |
| Natus Medical |
| Elekta AB |
| Compumedics |
| Nihon Kohden Corporation |
| Neural Analytics |
| Advanced Brain Monitoring |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese optical sensor foundries is compressing lead times for near-infrared spectroscopy modules, forcing device manufacturers to prepay for wafer capacity while passing component premiums through to hospital procurement committees in Germany and the United States.
Pricing Analysis
Next-generation AI-enhanced imaging platforms command substantial premiums over legacy CT and MRI fleets, while handheld EEG systems price at mid-tier points between fixed laboratory configurations and basic screening tools. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated diagnostic suites from conventional imaging hardware and refurbished secondary-market equipment. Cost compression in standard-tier intracranial pressure monitors is intensifying because German and Japanese trauma centers are consolidating procurement around vendors with demonstrated EU MDR technical documentation. Emergency departments exhibit the highest price sensitivity due to throughput pressure and capital budget constraints, while neurocritical care units prioritize precision specifications over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing strategy for electromagnetic shielding materials and precision pressure transducers. Manufacturing concentrates in Germany for catheter-based pressure measurement systems, Japan for optical sensor miniaturization, and the United States for AI-enhanced imaging software development. Production draws from specialized semiconductor substrates, biocompatible polymers, and rare-earth magnet assemblies. Single-source vulnerability in Japanese JIS-certified electromagnetic compatibility testing facilities creates bottleneck risk for overseas manufacturers seeking PMDA market access. Distribution runs through hospital GPO contracts in the United States, regional procurement consortia in Germany, and centralized NHS supply frameworks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The traumatic brain injury device market is recovering from reimbursement coding fragmentation that compressed vendor margins, with cyclical uplift now supported by expanding neurocritical care infrastructure investments across United States academic medical centers.
For Market Incumbents: Harden installed base positions in intracranial pressure monitoring by embedding proprietary data formats that complicate rival platform switching, while acquiring FDA breakthrough device designations for next-generation optical sensor architectures to compress regulatory timelines against emerging EEG specialists. Vertical integration into biocompatible polymer molding for catheter components reduces exposure to medical-grade silicone supply volatility. For New Entrants and Emerging Players: Establish a beachhead in post-acute rehabilitation equipment where payer coverage expansion in the United States is opening margin pools previously constrained to acute-care sales cycles. Cognitive recovery systems for memory and executive function represent the most penetrable segment given limited incumbent specialization. Go-to-market execution should prioritize telemedicine-enabled remote interpretation partnerships that address intensivist shortages in Japanese metropolitan healthcare systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform vendors bundling device hardware with software subscription tiers for automated EEG analysis and predictive alarm systems. Long-term viability over the coming decade favors vendors with demonstrated post-market clinical evidence generation capabilities under EU MDR surveillance requirements. Acquisition targets should display robust technical documentation libraries and established hospital GPO relationships. The signal to monitor is Medicare reimbursement coding finalization for remote neurocritical monitoring, which would validate service-unbundling business models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Navigation | Accelerates time-to-market for novel handheld EEG architectures under 21 CFR Part 882. |
| CE Marking Pathway | EU MDR clinical evidence thresholds filter procurement toward validated technical documentation. |
| Hospital System Partnership | Academic medical centers in Baltimore and Houston provide clinical validation for portable assessment tools. |
| Software Companion Development | AI-enhanced lesion detection algorithms digitize radiological workflow for non-specialist clinicians. |
| Reimbursement Strategy | Medicare, NHS England, and Germany's G-BA coding evolution determines service-unbundling economics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and GPO contract disclosures. Clinicians, hospital purchasing committees, biomedical engineers, and regulatory affairs specialists provided operational perspective on device deployment workflows. Bottom-up triangulation against manufacturer shipment data and top-down validation through trauma center infrastructure investment tracking ensured cross-verified demand estimates.
Forecast inputs include continuous EEG adoption rates in United States emergency departments, intracranial pressure monitor replacement cycles in German neurocritical care units, and optical sensor miniaturization cost curves from Japanese component suppliers. Segmentation modeling spans product type, technology modality, clinical application, and end-user facility tier across the projection horizon. CAGRs derive from installed base expansion, procedure volume growth, and average selling price trajectories for AI-enhanced platforms versus conventional imaging hardware.
Stress conditions across Medicare reimbursement coding finalization, EU MDR post-market surveillance stringency, and Japanese PMDA electromagnetic compatibility certification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding trauma center infrastructure buildout and payer coverage expansion for cognitive rehabilitation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
External Defibrillator Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global Photomedicine Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Asia-Pacific General Surgical Devices Market