
 Implant-Borne Prosthetics Market | 2026-2036
Implant-Borne Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Implant-Borne Prosthetics Market Foresight
The gap between premium titanium implant systems and commodity-grade alternatives is realigning procurement patterns across dental and orthopedic channels. Straumann Group leverages its Swiss manufacturing heritage to sustain premium positioning in immediate-load dental applications. Osstem Implant Co., Ltd. anchors volume leadership across Asia-Pacific through cost-optimized titanium fixture lines. Dentsply Sirona Inc. competes by integrating digital workflow hardware with its implant portfolio, narrowing the traditional divide between chairside scanning and surgical placement.
Implant-borne prosthetics are medical devices surgically embedded into bone or soft tissue to support functional or aesthetic replacement structures, typically fabricated from titanium alloys with surface modifications like plasma-sprayed hydroxyapatite to enhance osseointegration. Their primary purpose is to restore masticatory function, skeletal stability, or limb mobility without relying on adjacent tissue adhesion. Dental implants command the largest revenue pool among product types, though craniofacial applications are gaining share as maxillofacial trauma reconstruction protocols advance. Titanium dominates material selection due to decades of clinical validation, yet zirconia ceramic alternatives are carving margin-rich niches in anterior aesthetic zones where soft tissue response and color masking matter.
The FDA enforces Class II and Class III device controls through 510(k) and PMA pathways, while ISO 13485 certification remains mandatory for supply access into regulated markets. The EU Medical Device Regulation imposes stricter clinical evidence requirements through EMA-coordinated notified body oversight, extending approval timelines for novel surface technologies. Stakeholders must monitor reimbursement code consolidation and real-world evidence mandates, as payers on both sides of the Atlantic tighten criteria for implant-prosthetic coverage expansion.
Market Dynamics
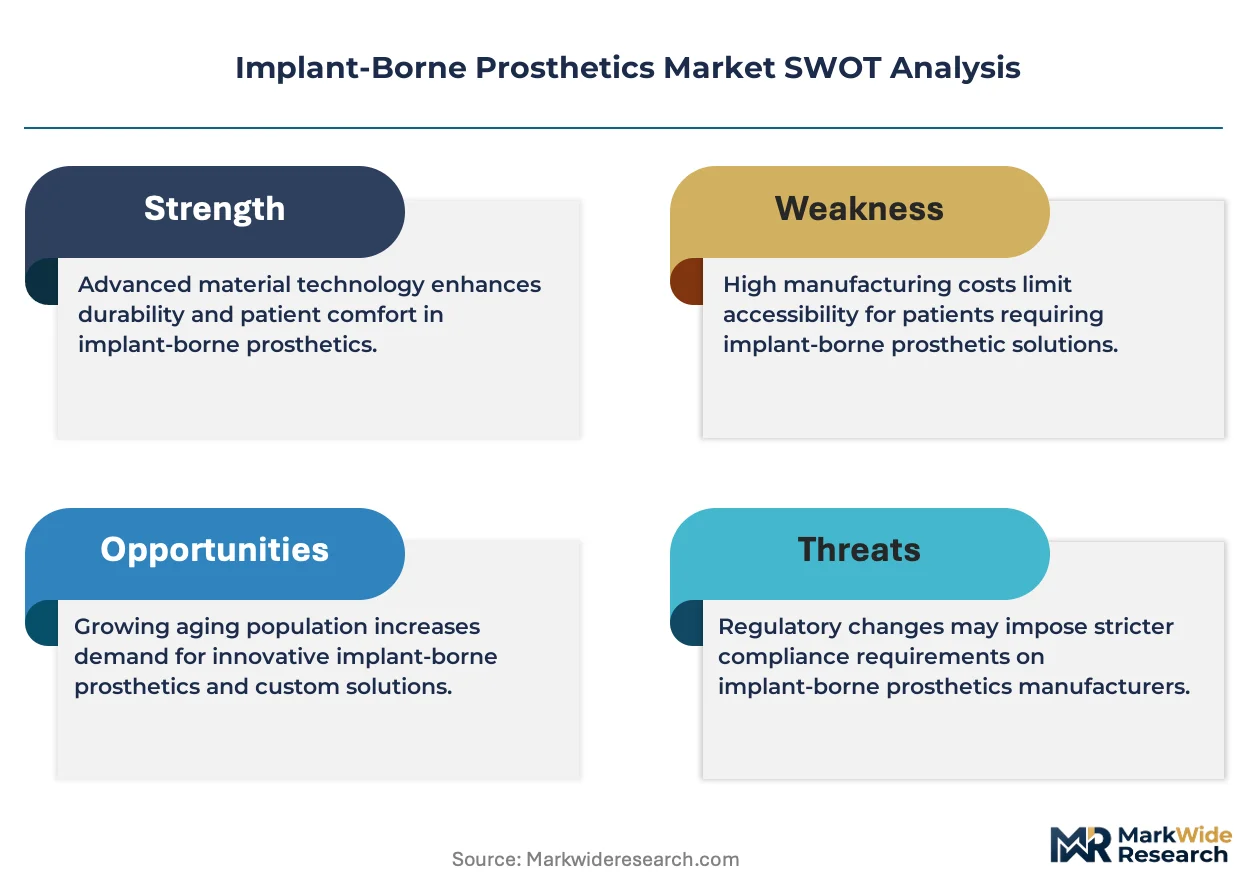
The implant-borne prosthetics sector faces intensifying pressure from the EU Medical Device Regulation's clinical evidence mandates, which are compressing approval timelines for novel surface technologies and forcing manufacturers to restructure their regulatory affairs functions.
Growth Catalysts
- Reimbursement code expansion:Germany's statutory health insurance framework now covers immediate-load dental protocols previously classified as elective, accelerating procedural volume in outpatient clinics.
- Surface engineering advances:Plasma-sprayed hydroxyapatite coatings with nanotopographic modifications are shortening osseointegration timelines from twelve weeks to six weeks in load-bearing applications.
- Aging demographic concentration:South Korea's over-65 population share crossed twenty percent in 2023, creating sustained demand for mandibular reconstruction and full-arch restoration procedures.
Market Restraints
- Titanium feedstock volatility:Sponge titanium prices fluctuate with aerospace sector demand cycles, compressing margins for mid-tier fixture manufacturers without long-term supply contracts.
- Notified body capacity constraints:EMA-coordinated oversight under MDR has created eighteen-month backlogs for Class III implant re-certifications, freezing product line extensions.
- Adjacent tissue adhesion substitutes:Mini-implant retained overdentures and adhesive-based removable prosthetics retain preference among cost-sensitive patient segments in emerging markets.
Strategic Opportunities
- Digital workflow convergence:Chairside intraoral scanning combined with surgical navigation systems enables same-day provisional placement, capturing premium pricing in aesthetic zone applications.
- Craniofacial trauma protocols:Maxillofacial reconstruction using patient-specific titanium meshes represents an underdeveloped revenue pool with higher reimbursement rates than standard dental implants.
- MFDS streamlined pathways:South Korea's regulator offers accelerated review for 3D-printed patient-matched implants, attracting foreign manufacturers seeking faster Asian market entry.
Industry Challenges
- Prosthodontist training pipeline:The American Dental Association reports insufficient fellowship positions for advanced implant surgery, creating procedural bottlenecks in high-demand metropolitan markets.
- ISO 13485 audit complexity:Transition to the 2016 revision requires documented risk management files for every design change, extending quality system implementation timelines by eight to fourteen months.
- Legacy CAD/CAM interoperability:Proprietary file formats from dominant intraoral scanner manufacturers block seamless data transfer to third-party milling centers, fragmenting digital workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implant-Borne Prosthetics Market |
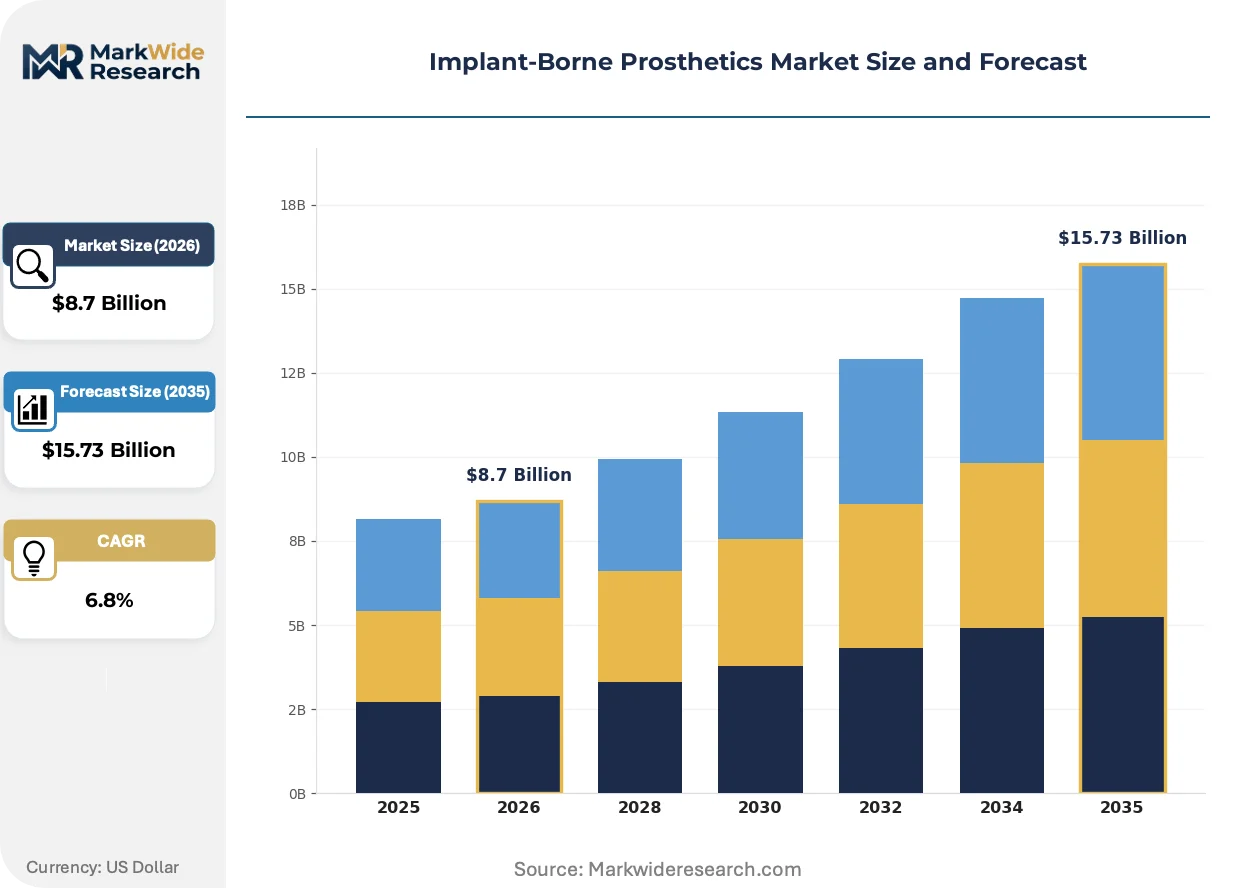
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Orthopedic Implants, Craniofacial Implants, Limb Prosthetics Application: Restorative Surgery, Cosmetic Surgery, Rehabilitation, Amputation Material: Titanium, Zirconia, Polyethylene, Biocompatible Alloys End User: Hospitals, Rehabilitation Centers, Dental Clinics, Home Care |
| Companies Covered | Zimmer Biomet Holdings, BioHorizons IPH, Inc., Straumann Group, CAMLOG Biotechnologies GmbH, Bicon, LLC, Nobel Biocare Services AG, Osstem Implant Co., Ltd., MegaGen Implant Co., Ltd., Dentsply Sirona Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implant-Borne Prosthetics Market Shifts & Advancements
Digital manufacturing and biomaterial science are compressing the traditional separation between surgical planning and final prosthetic fabrication, collapsing what were once distinct supplier categories into integrated solution providers.
Additive manufacturing of titanium alloy implants with lattice-structured pore architectures is consolidating the historically separate markets for standard fixtures and bone graft substitutes. Oral surgeons in university hospital settings are adopting these patient-matched devices for complex ridge deficiencies. The technology is consolidating procurement decisions around single-source providers capable of both design optimization and regulatory filing.
The FDA's 510(k) clearance pathway for breakthrough devices now requires comparative effectiveness data against predicate devices rather than mere equivalence demonstrations. This elevates clinical trial costs for surface-modified implants. Dental implant manufacturers with established predicate portfolios are responding by acquiring smaller firms with novel coating intellectual property rather than developing internally.
Group purchasing organizations now aggregate procurement for multi-location dental service organizations, replacing individual practice autonomy with centralized vendor selection. The DSO channel favors suppliers offering bundled implant-abutment-crown systems with predictable pricing over three-year contracts. This concentration is most visible in the southwestern United States, where private equity-backed dental platforms control forty percent of implant placement volume in major metropolitan statistical areas.
Implant-Borne Prosthetics Market Segmentation
Implant-borne prosthetics serve distinct patient populations with divergent clinical priorities, reimbursement pathways, and procurement cycles. Segmentation reveals where premium pricing power concentrates versus where volume scale dominates.
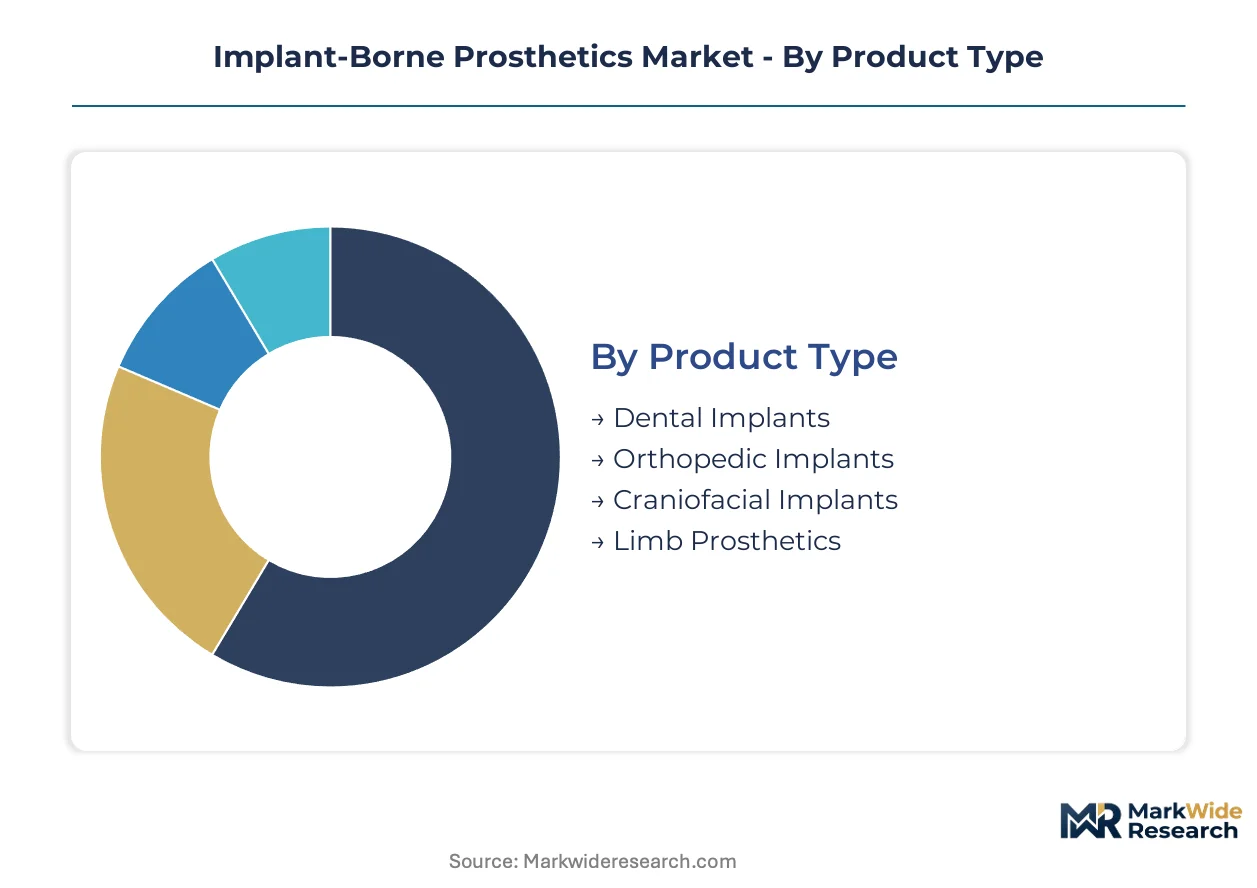
Product Type:
Dental clinics prioritize immediate-load capability and aesthetic outcomes, while orthopedic buyers emphasize mechanical durability under cyclic loading.
- Dental Implants:Titanium alloy fixtures with surface-modified osseointegration layers command the largest revenue pool. Demand clusters in Germany and South Korea where statutory reimbursement expansion covers immediate-load protocols previously classified as elective.
- Orthopedic Implants:Load-bearing hip and knee replacement systems fabricated from cobalt-chrome-molybdenum alloys face procurement consolidation through hospital group purchasing organizations. The FDA's 510(k) pathway dominates regulatory entry, though EU MDR clinical evidence mandates are extending approval timelines for novel bearing surfaces.
- Craniofacial Implants:Patient-specific titanium meshes for maxillofacial trauma reconstruction represent higher-margin, lower-volume applications.
- Limb Prosthetics:Osseointegrated transcutaneous implants for amputee rehabilitation remain niche, constrained by surgical complexity and limited prosthetist training pipelines.
Volume sits with dental and orthopedic systems; growth tilts toward craniofacial patient-matched devices.
Application:
Procedure reimbursement status and surgical invasiveness separate high-volume routine interventions from discretionary aesthetic placements.
- Restorative Surgery:Functional reconstruction following trauma or disease resection constitutes the procedural backbone. German statutory health insurance frameworks now cover immediate-load dental protocols, accelerating outpatient clinic throughput.
- Rehabilitation:Post-amputation osseointegration and post-oncologic mandibular reconstruction require multidisciplinary surgical teams. South Korea's aging demographic concentration sustains demand for mandibular reconstruction procedures.
- Cosmetic Surgery:Elective aesthetic enhancements face payer scrutiny and out-of-pocket payment requirements.
- Amputation:Transcutaneous implant integration for limb replacement remains limited to specialized tertiary centers.
Reimbursement-supported restorative procedures dominate volume; cosmetic applications expand most quickly where private payment capacity is strongest.
Material:
Biocompatibility certification grade and manufacturing method determine cost structure and clinical indication suitability.
- Titanium:Commercially pure and alloyed grades with plasma-sprayed hydroxyapatite coatings retain clinical validation advantages. Sponge titanium feedstock price volatility tied to aerospace demand cycles compresses margins for manufacturers lacking long-term supply contracts.
- Zirconia:Yttria-stabilized tetragonal polycrystalline ceramic alternatives carve margin-rich niches in anterior aesthetic zones where soft tissue response and color masking matter.
- Biocompatible Alloys:Cobalt-chrome and tantalum formulations serve orthopedic load-bearing applications.
- Polyethylene:Cross-linked ultra-high molecular weight grades function as bearing surfaces in total joint arthroplasty.
Titanium commands installed base dominance; zirconia gains share fastest in visible-zone aesthetic applications.
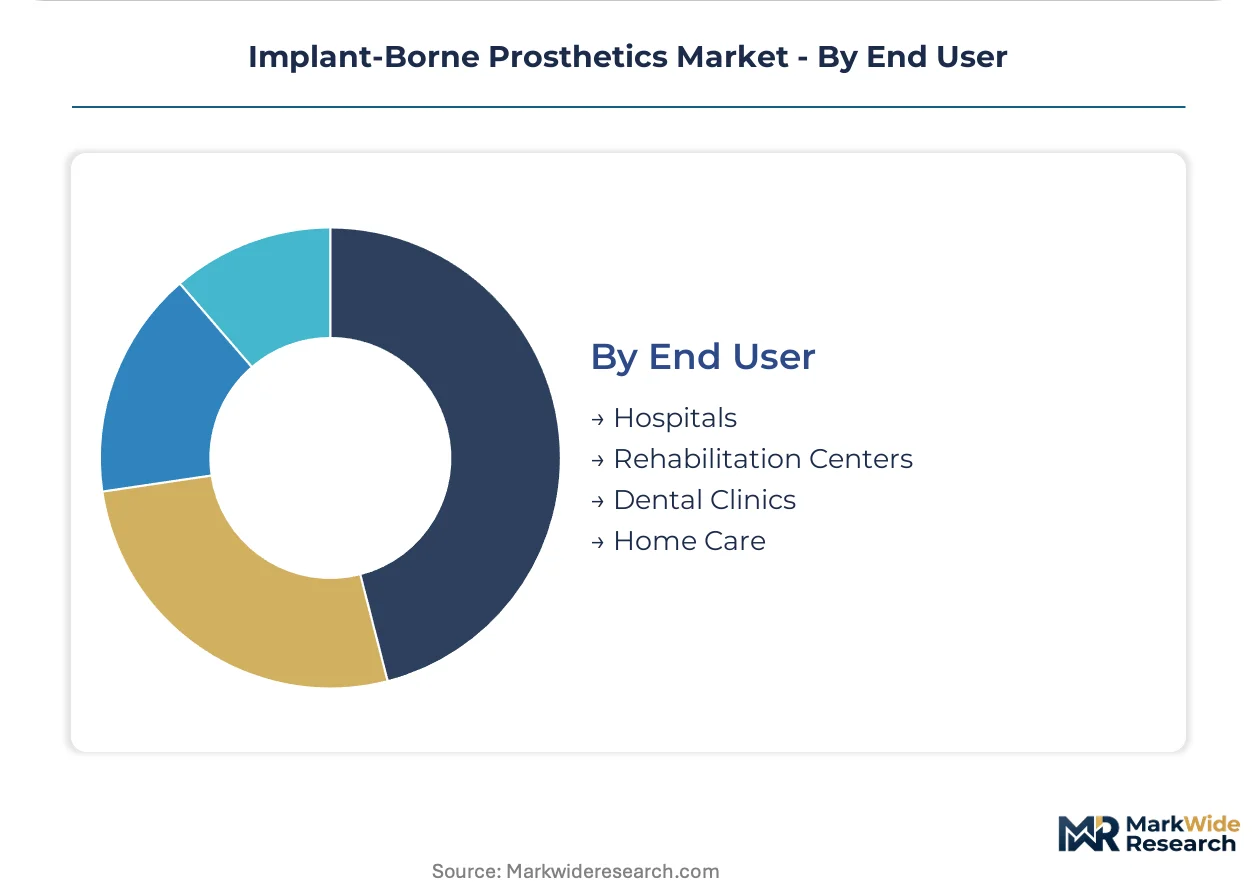
End User:
Capital intensity and regulatory compliance burden filter supplier access across institutional categories.
- Dental Clinics:Outpatient settings drive implant placement volume through digital workflow integration. Chairside intraoral scanning combined with surgical navigation enables same-day provisional placement, capturing premium pricing.
- Hospitals:Academic medical centers adopt additive-manufactured patient-matched implants for complex ridge deficiencies and craniofacial trauma. ISO 13485 audit complexity and EU MDR notified body backlogs freeze product line extensions.
- Rehabilitation Centers:Prosthetic fitting and gait training facilities coordinate with surgical centers for osseointegrated limb systems.
- Home Care:Minimal penetration due to surgical implantation requirement and infection risk management protocols.
Procedure concentration favors dental clinics for volume; hospitals capture the steepest expansion trajectory in patient-matched craniofacial reconstruction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors procedural volume in implant-borne prosthetics, with the capital's dental clinics driving adoption of immediate-load protocols and digital workflow integration across South Korea's aging demographic base.
United States
Private equity-backed dental service organizations concentrate procurement decisions in southwestern metropolitan areas, replacing individual practice autonomy with centralized vendor selection for implant-abutment-crown systems. The FDA's 510(k) pathway dominates regulatory entry, though breakthrough device designations now demand comparative effectiveness data rather than simple predicate equivalence. Greater Boston's academic medical centers pioneer additive-manufactured patient-matched implants for complex craniofacial reconstruction.
Germany
Statutory health insurance frameworks now cover immediate-load dental protocols previously classified as elective, accelerating outpatient clinic throughput in Bavaria and Baden-Württemberg. The EU Medical Device Regulation imposes stricter clinical evidence requirements through EMA-coordinated notified body oversight, extending approval timelines for novel surface technologies. Stuttgart's industrial corridor hosts precision manufacturing clusters serving premium titanium fixture production.
South Korea
The over-65 population share crossed twenty percent in 2023, creating sustained demand for mandibular reconstruction and full-arch restoration procedures in Seoul and Busan. MFDS offers accelerated review pathways for 3D-printed patient-matched implants, attracting foreign manufacturers seeking faster Asian market entry. Daegu-Gyeongbuk's medical device cluster specializes in cost-optimized titanium fixture lines for regional export.
Switzerland
Swissmedic maintains rigorous quality standards that reinforce premium positioning for immediate-load dental applications originating from Basel and Zurich manufacturing corridors. ISO 13485 certification remains mandatory for supply access into regulated markets, with the 2016 revision requiring documented risk management files for every design change. The country's precision engineering heritage sustains margin-rich positioning in surface-modified osseointegration technologies.
Japan
PMDA oversight aligns with international harmonization initiatives while maintaining distinct clinical evidence requirements for novel biomaterials entering Tokyo and Osaka metropolitan markets. METI coordinates industrial policy supporting domestic manufacturing of zirconia ceramic alternatives for anterior aesthetic zones. Nagoya's Chubu region concentrates prosthodontist training programs addressing pipeline constraints in advanced implant surgery.
Implant-Borne Prosthetics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across surface technology and digital workflow integration capabilities, with the gap between Swiss-manufactured heritage brands and Asian volume leaders realigning procurement patterns across dental and orthopedic channels. The vendor base organizes into three strategic archetypes: integrated digital workflow providers combining hardware with implant portfolios, cost-optimized volume manufacturers serving price-sensitive Asian markets, and precision heritage specialists leveraging decades of clinical validation. Dominant competitive moves include acquisitions of smaller firms with novel coating intellectual property and backward integration into titanium feedstock supply.
Among Swiss and German heritage manufacturers, Straumann Group and Nobel Biocare Services AG exemplify premium-tier positioning built on immediate-load clinical validation and surface engineering heritage. Osstem Implant Co., Ltd. anchors the volume-driven tier through cost-optimized manufacturing serving Asia-Pacific price sensitivity. Zimmer Biomet Holdings occupies a diversified position spanning orthopedic load-bearing systems alongside dental applications, representing the cross-segment consolidation archetype.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings |
| BioHorizons IPH, Inc. |
| Straumann Group |
| CAMLOG Biotechnologies GmbH |
| Bicon, LLC |
| Nobel Biocare Services AG |
| Osstem Implant Co., Ltd. |
| MegaGen Implant Co., Ltd. |
| Dentsply Sirona Inc. |
| Others |
Supply & Pricing Matrix
Sponge titanium price benchmarks tied to aerospace demand cycles cascade through implant manufacturing into three distinct pricing tiers. Cost-optimized fixture lines from South Korean producers capture volume-sensitive dental clinics, while Swiss heritage brands command premium positioning through surface engineering validation and ISO 13485 certification pedigree.
Pricing Analysis
Outcome-linked pricing anchors the premium tier, with immediate-load dental protocols commanding higher reimbursement rates in Germany's statutory health insurance framework. Pricing stratifies across premium, standard, and economy tiers based on surface technology sophistication and brand clinical validation heritage. Cost compression in the mid-tier fixture segment is intensifying due to group purchasing organization concentration among US dental service organizations. Price sensitivity concentrates among outpatient clinics in emerging Asian markets, while academic medical centers in Boston and Stuttgart exhibit lowest sensitivity for patient-matched craniofacial applications.
Supply Chain Analysis
South Korea's domestic-content preferences for medical device procurement are reshaping sourcing patterns for foreign manufacturers seeking MFDS accelerated review pathways. Manufacturing gravity centers on Switzerland for precision surface-modified fixtures, Germany for orthopedic load-bearing systems, and South Korea for cost-optimized titanium lines. Feedstock draws from sponge titanium suppliers in Japan and Kazakhstan, with plasma-sprayed hydroxyapatite coatings sourced from specialized German and US chemical processors. Single-source vulnerability concentrates in aerospace-tethered titanium sponge supply. Distribution runs through hospital group purchasing organizations in North America and dental service organization procurement platforms in the southwestern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The implant-borne prosthetics market operates as a supply-constrained environment where notified body capacity bottlenecks under EU MDR prop pricing power for certified incumbents. Eighteen-month re-certification backlogs freeze product line extensions, entrenching established players with predicate device portfolios.
For Market Incumbents: Anchor premium positioning through backward integration into titanium feedstock supply and acquisition of novel coating intellectual property from smaller firms. Surface engineering advances represent the critical defensive lever against commodity-grade Asian competitors. ISO 13485:2016 transition completion separates compliant suppliers from frozen product lines. For New Entrants and Emerging Players: Capture the craniofacial trauma reconstruction white space where patient-specific titanium meshes command higher reimbursement rates than standard dental fixtures. South Korea's MFDS accelerated pathways for 3D-printed implants offer the most penetrable regulatory entry point. A digital workflow bundling strategy combining intraoral scanning hardware with implant portfolios narrows the competitive gap with integrated incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier fixture manufacturers with established EU MDR technical documentation but constrained notified body access in Germany and Switzerland. Long-term viability over the coming decade hinges on surface technology differentiation rather than pure manufacturing scale. The signal to monitor is notified body capacity expansion announcements from EMA-coordinated oversight bodies.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership | Secures EU MDR certification capacity for Class III implant re-certifications amid eighteen-month backlogs. |
| Surface Technology Acquisition | Acquires novel coating IP to satisfy FDA breakthrough device comparative effectiveness requirements. |
| Digital Workflow Integration | Combines chairside intraoral scanning with surgical navigation for same-day provisional placement capture. |
| Titanium Feedstock Contracting | Locks sponge titanium supply pricing through long-term agreements with Japanese and Kazakh producers. |
| MFDS Accelerated Filing | Exploits South Korea's streamlined 3D-printed implant review for faster Asian market entry. |
Research Methodology
Document review covered FDA 510(k) clearances, EMA MDR technical documentation, and ISO 13485 audit records, complemented by interviews with prosthodontists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers. Secondary validation drew from CMS Medicare reimbursement databases, hospital procurement registries, and medical device trade customs records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Cross-referencing historical approval timelines against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-user institutional category, and regional regulatory cluster. CAGRs derived from procedure volume trajectories weighted by reimbursement code expansion patterns and demographic aging curves. Forecast inputs incorporated surface technology adoption rates and digital workflow penetration benchmarks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to notified body capacity resolution, titanium feedstock price volatility, and reimbursement code consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Morcellators Market
Medical Devices
Spherical IOL Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Artificial Respirator Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
Ocular Trauma Devices Market