
 Global Medical Tricorder Device Market | 2026-2036
Global Medical Tricorder Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Tricorder Device Market Foresight
Fragmentation among telemedicine providers and home healthcare buyers is recalibrating procurement patterns across the Global Medical Tricorder Device Market. AliveCor Inc. anchors its position through cardiac rhythm specialization and FDA-cleared algorithms. Basil Leaf Technologies LLC leverages extensive R&D partnerships with academic medical centers. Omron Healthcare Inc. dominates blood pressure monitoring integration within its device ecosystem.
A medical tricorder device combines multiple non-invasive biosensors, optical scanners, and electromagnetic detectors into a single portable or wearable unit capable of measuring vital signs, detecting biomarkers, and screening for acute conditions without invasive sample collection. Handheld tricorders currently occupy the largest revenue share due to clinician familiarity and established reimbursement pathways, while wearable tricorders represent the fastest-expanding category as continuous monitoring protocols gain traction in ambulatory and home settings. Biosensor technology leads deployment volumes, though ultrasonic modules are gaining ground in point-of-care emergency response applications where tissue imaging adds diagnostic depth.
FDA Software as a Medical Device frameworks and EU MDR Class IIa certification requirements shape product development roadmaps and market access timelines for manufacturers targeting the United States and European Union. The WHO's prequalification standards for diagnostic devices influence procurement criteria in emerging markets and humanitarian supply chains. Stakeholders must monitor evolving cybersecurity mandates for connected health devices as regulatory bodies tighten data integrity requirements alongside clinical performance benchmarks.
Market Dynamics
Telemedicine reimbursement compression in the United States is forcing manufacturers to redesign tricorder architectures around remote patient monitoring billing codes rather than premium hardware margins.
Growth Catalysts
- FDA Software as a Medical Device pathway:The streamlined 510(k) clearance process for algorithm-based diagnostics accelerates commercialization timelines for sensor-software hybrid platforms targeting home healthcare deployment.
- Home healthcare agencies:Medicare's expansion of remote therapeutic monitoring codes creates reimbursable endpoints for continuous vital sign capture in post-acute care settings.
- Photoplethysmography miniaturization:Advances in optical biosensor integration enable multi-parameter monitoring within wrist-worn form factors previously restricted to clinical environments.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korea dominate fabrication capacity for microelectromechanical pressure sensors, exposing supply chains to geopolitical disruption and capacity allocation conflicts with consumer electronics.
- EU MDR Class IIa clinical evidence requirements:The expanded need for prospective validation studies extends certification timelines and elevates documentation burdens for multifunction diagnostic devices.
- Smartphone-based health apps:Consumer-grade camera and accelerometer combinations deliver sufficient vital sign approximation for wellness segments, constraining pricing power at the entry tier.
Strategic Opportunities
- Brazil's ANVISA accelerated pathway:The priority review track for portable diagnostics enables first-mover positioning in Latin America's largest healthcare procurement market ahead of local manufacturing requirements.
- AI-interpreted ultrasonic imaging:Convergence of edge-computing neural networks with compact transducer arrays creates handheld ultrasound capabilities without radiologist dependency in emergency medicine and rural clinics.
- Direct-to-employer contracting:Self-insured corporations in the United States are bypassing traditional distribution through group purchasing organizations to secure population health monitoring at scale.
Industry Challenges
- Firmware validation engineering:The scarcity of embedded systems specialists with medical device cybersecurity expertise constrains development velocity for connected tricorder platforms requiring IEC 62304 compliance.
- Health system EHR integration:Proprietary data formats and API access restrictions at major electronic health record vendors create deployment friction requiring custom interface development per installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Tricorder Device Market |
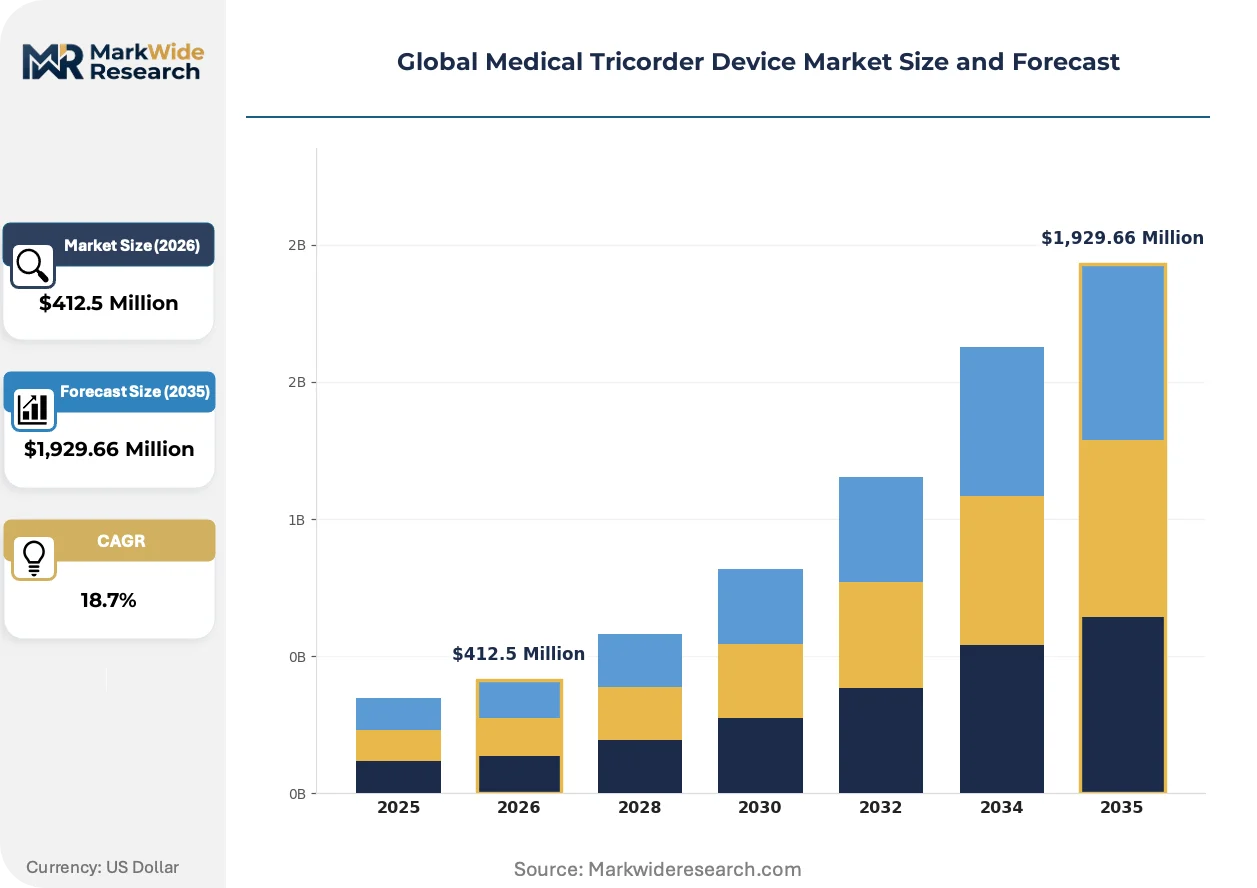
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Tricorder, Wearable Tricorder, Fixed Tricorder, Portable Scanner Technology: Optical Sensors, Biosensors, RFID, Ultrasonic, Electromagnetic Application: Vital Signs Monitoring, Disease Diagnosis, Patient Screening, Emergency Response, Remote Health Assessment End User: Hospitals, Ambulatory Care Centers, Telemedicine Providers, Home Healthcare, Research Laboratories |
| Companies Covered | Healthy.io Ltd., Medipense Inc., Cloud DX Inc., VitalConnect Inc., AliveCor Inc., Scanadu Inc., Aidar Health Inc., Omron Healthcare Inc., Basil Leaf Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Tricorder Device Market Shifts & Advancements
Edge AI inference is compressing diagnostic decision-making from cloud servers to handheld units, eliminating latency dependencies that previously constrained real-time clinical utility in ambulatory settings.
Multi-sensor fusion architectures combining photoplethysmography, bioimpedance spectroscopy, and thermopile arrays is decentralizing hematological assessment from centralized laboratories to point-of-care environments. Hospital-at-home programs in Germany and the Netherlands are deploying these platforms for post-surgical monitoring. The structural consequence is collapsing the traditional specimen transport and batch processing infrastructure that defined outpatient diagnostics.
EU MDR's Unique Device Identification mandate and enhanced post-market surveillance requirements are elevating lifecycle traceability obligations for manufacturers. Device history records must now span component-level genealogy through end-user deployment. Wearable tricorder categories face the steepest compliance elevation due to their software update cadence and patient contact duration.
Subscription-based device provisioning is displacing capital purchase models in North American health systems seeking to convert fixed diagnostic infrastructure costs into variable operational expenditures aligned with patient volume fluctuations. Risk-bearing accountable care organizations in Minnesota and California pioneered this shift. The model transfers obsolescence risk to manufacturers while locking in multi-year sensor consumable commitments.
Global Medical Tricorder Device Market Segmentation
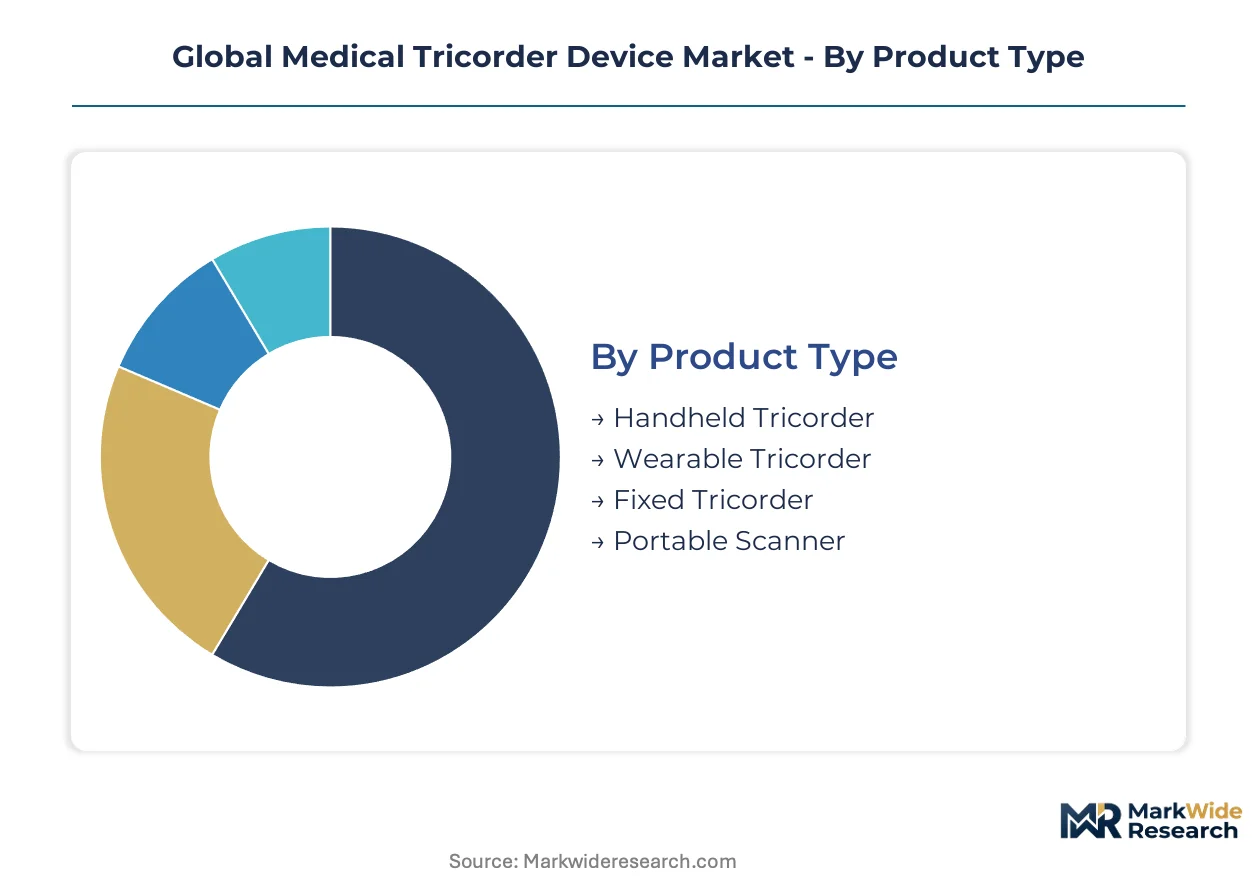
Medical tricorder architectures vary dramatically in integration depth, from standalone handheld units to embedded sensor networks within hospital infrastructure. Procurement decisions hinge on whether devices operate as independent diagnostic endpoints or feed data into broader clinical workflows. This segmentation framework captures how form factor, sensing modality, clinical application, and care setting collectively determine commercial viability and reimbursement pathways.
Product Type:
Handheld units dominate standalone deployment where clinician mobility matters most, while wearable and fixed installations embed deeper into continuous monitoring ecosystems.
- Handheld Tricorder:Combines multiple biosensors, optical scanners, and electromagnetic detectors into a single portable unit for point-of-care vital sign capture and acute condition screening. Demand concentrates in United States hospital emergency departments where FDA-cleared 510(k) pathways enable rapid procurement. Clinician familiarity with familiar smartphone-like form factors accelerates training adoption.
- Wearable Tricorder:Integrates photoplethysmography, bioimpedance spectroscopy, and thermopile arrays into wrist-worn or patch-based formats for continuous ambulatory monitoring. Home healthcare agencies in Germany and the Netherlands deploy these for post-surgical hospital-at-home programs. Medicare's remote therapeutic monitoring reimbursement codes now cover continuous vital sign capture in post-acute settings.
- Fixed Tricorder:Wall-mounted or cart-based installations with hardwired power and data connectivity for high-throughput screening environments.
- Portable Scanner:Compact imaging-focused devices emphasizing ultrasonic or optical modules for tissue assessment without full vital sign suites.
Handheld tricorders lead volumes today; wearable tricorders are gaining share fastest.
Technology:
Cost tiers separate mature optical and biosensor platforms from emerging ultrasonic and electromagnetic modalities requiring heavier R&D investment.
- Optical Sensors:Photoplethysmography and spectroscopic methods enable non-invasive blood oxygen, pulse rate, and hemoglobin estimation through tissue illumination. Miniaturization advances now pack multi-parameter optical monitoring into wrist-worn formats previously restricted to clinical environments.
- Biosensors:Electrochemical and bioimpedance approaches detect biomarkers through sweat, interstitial fluid, or skin surface analysis without invasive sample collection. Deployment volumes lead across all product categories due to established manufacturing economies and FDA predicate device availability.
- RFID:Passive and active radio-frequency identification for patient-device pairing and medication tracking integration.
- Ultrasonic:Compact transducer arrays with edge-AI interpretation enabling handheld imaging without radiologist dependency in emergency medicine.
- Electromagnetic:Low-field MRI and electrical impedance tomography for tissue characterization without ionizing radiation.
Biosensors dominate current procurement volumes; ultrasonic modules show the steepest expansion trajectory as point-of-care imaging gains clinical acceptance.
Application:
Application segments map to distinct customer maturity levels, from commoditized vital signs monitoring to experimental AI-assisted disease diagnosis protocols.
- Vital Signs Monitoring:Continuous or episodic capture of heart rate, blood pressure, respiratory rate, temperature, and oxygen saturation. Telemedicine providers in the United States anchor demand here as reimbursement rules now cover remote patient monitoring codes for these metrics.
- Disease Diagnosis:Algorithm-interpreted multi-sensor fusion for specific condition identification such as cardiac arrhythmia or respiratory infection. AliveCor's FDA-cleared cardiac rhythm algorithms demonstrate commercial viability in this segment.
- Patient Screening:Rapid triage and risk stratification in high-volume settings such as occupational health and primary care intake.
- Emergency Response:Pre-hospital and disaster medicine deployment where device durability and rapid deployment outweigh precision requirements.
- Remote Health Assessment:Asynchronous diagnostic data capture for store-and-forward telemedicine consultations.
Vital signs monitoring commands the largest installed base; disease diagnosis applications are climbing fastest as AI-interpreted sensor fusion matures.
End User:
Customer type determines pricing tolerance and integration complexity, from health system enterprise procurement to direct-to-consumer research laboratory acquisitions.
- Hospitals:Acute care facilities requiring FDA-cleared devices with EHR integration, cybersecurity compliance, and biomedical engineering support infrastructure. North American health systems are expanding procurement of handheld diagnostic units as subscription-based provisioning displaces capital purchase models.
- Telemedicine Providers:Virtual-first care organizations prioritizing patient-operated devices with cloud connectivity and automated data transmission. Reimbursement compression is forcing architectural redesign around remote patient monitoring billing codes rather than premium hardware margins.
- Ambulatory Care Centers:Outpatient clinics and urgent care facilities with intermediate throughput and staffing constraints.
- Home Healthcare:Post-acute and chronic care management agencies serving Medicare and Medicaid populations.
- Research Laboratories:Academic medical centers and pharmaceutical trials units tolerating investigational-device status for novel biomarker validation.
Hospitals retain the largest procurement volumes; telemedicine providers represent the most rapidly expanding customer segment as virtual care reimbursement stabilizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in the United States, Germany, and Japan anchor tricorder development, while manufacturing scale concentrates in Taiwan and South Korea for sensor fabrication.
United States
Hospital-at-home programs in Minnesota and California drive demand for continuous monitoring devices. FDA's Software as a Medical Device pathway compresses 510(k) clearance timelines for algorithm-based diagnostics. The Boston-Cambridge corridor hosts multiple startups integrating edge AI with compact biosensor arrays.
Germany
Hospital-at-home initiatives in Bavaria and North Rhine-Westphalia deploy wearable tricorders for post-surgical monitoring. EU MDR Class IIa certification requirements mandate enhanced clinical evidence for multifunction diagnostic devices. The Stuttgart region concentrates precision sensor manufacturing for automotive-to-medical crossovers.
Japan
Aging demographics and rural physician shortages accelerate adoption of remote diagnostic tools in home healthcare. PMDA streamlined review pathways for AI-interpreted medical devices reduce regulatory lag. The Kansai region around Osaka maintains dense clusters of optical component suppliers serving both consumer electronics and medical device sectors.
South Korea
MEMS foundry capacity for pressure sensors supplies global tricorder manufacturers, creating supply chain leverage. MFDS digital health device frameworks accommodate software-update-heavy products under expedited review. Seoul's Digital Healthcare Cluster incubates ventures combining smartphone integration with clinical-grade sensing.
Brazil
Public health system procurement for remote primary care expands addressable market for cost-optimized handheld units. ANVISA's accelerated pathway for portable diagnostics enables faster market entry ahead of local manufacturing requirements. São Paulo's medical device corridor attracts regional distribution headquarters serving Latin American telemedicine providers.
Global Medical Tricorder Device Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Global Medical Tricorder Device Market. The vendor base separates into three tiers: multinational health technology conglomerates with broad diagnostic portfolios, mid-sized sensor-software hybrid specialists, and venture-backed startups targeting single-application dominance. Consolidation pressure intensifies as reimbursement compression favors scale economies in regulatory compliance and EHR integration. Strategic partnerships with academic medical centers and direct-to-employer contracting represent the dominant competitive vectors.
Within the cardiac rhythm specialization tier, AliveCor Inc. exemplifies algorithm-first positioning through FDA-cleared diagnostic workflows. Basil Leaf Technologies LLC and Omron Healthcare Inc. anchor contrasting approaches to multi-sensor integration, with the former representing venture-backed hardware-software convergence and the latter exemplifying diversified health technology conglomerate leverage in blood pressure monitoring ecosystems.
| Leading Market Players |
|---|
| Healthy.io Ltd. |
| Medipense Inc. |
| Cloud DX Inc. |
| VitalConnect Inc. |
| AliveCor Inc. |
| Scanadu Inc. |
| Aidar Health Inc. |
| Omron Healthcare Inc. |
| Basil Leaf Technologies LLC |
| Others |
Supply & Pricing Matrix
Silicon wafer spot indices and MEMS sensor contract rates cascade through tricorder manufacturing into three distinct pricing tiers, with Taiwan foundry capacity allocation decisions directly compressing margins on economy-grade handheld units while premium wearable segments absorb optical component premiums through subscription bundling.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for biosensor modules, forcing economy-tier manufacturers toward razor-thin hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared algorithm suites from basic vital sign capture and unvalidated wellness approximations. Cost compression in the entry tier intensifies because smartphone-based health apps deliver sufficient consumer-grade monitoring. Telemedicine providers exhibit the highest price sensitivity, while hospital purchasing committees prioritize cybersecurity certification over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke patterns for European and Asia-Pacific deployment. Component sourcing concentrates in Taiwan, South Korea, and Japan for MEMS pressure sensors, optical emitters, and edge-AI processors. Raw material dependencies include silicon wafers, rare-earth magnetics for electromagnetic modules, and specialized polymers for biocompatible housings. Single-source vulnerability in Taiwan foundry exposure creates structural risk. Distribution runs through group purchasing organizations and direct-to-employer channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical tricorder procurement has shifted toward premium specifications as hospital-at-home programs demand continuous monitoring reliability over intermittent screening, making this a late-cycle quality story where certification depth trumps price competition.
For Market Incumbents: Acquire embedded firmware engineering teams with IEC 62304 compliance expertise to close the cybersecurity capability gap. Consolidate EHR integration partnerships with Epic and Cerner to lock out challengers through API access restrictions. Smartphone-based diagnostic apps represent the substitute threat requiring defensive algorithm investment in AI-interpreted sensor fusion. For New Entrants and Emerging Players: The mid-tier price gap between AliveCor's premium cardiac algorithms and unvalidated wellness devices creates entry space for FDA-cleared single-parameter specialists. Brazil's ANVISA accelerated pathway offers the most penetrable regulatory environment ahead of local manufacturing mandates. Direct-to-employer contracting bypasses GPO gatekeepers entirely. For Investors and Strategic Acquirers: Asymmetric upside sits with sensor-software hybrid specialists holding FDA 510(k) clearances in remote therapeutic monitoring categories. Five-to-ten year viability hinges on reimbursement code alignment rather than hardware innovation cycles. Watch for CMS expansion of continuous glucose monitoring-style coverage to multi-parameter vital sign capture as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | 510(k) clearance for algorithm-based diagnostics accelerates commercialization timelines for home healthcare deployment. |
| CE Marking Pathway under EU MDR Class IIa | Enhanced clinical evidence requirements extend certification timelines but unlock procurement access across German hospital-at-home programs. |
| Hospital System Partnership | Subscription-based provisioning with Minnesota and California health systems converts fixed infrastructure costs into variable operational expenditures. |
| Software Companion Development | Edge-AI inference modules eliminate cloud latency dependencies for real-time clinical utility in ambulatory emergency response. |
| Reimbursement Strategy Alignment | Medicare remote therapeutic monitoring codes now cover continuous vital sign capture in post-acute care settings. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and GPO contracts managers, secondary validation against FDA 510(k) filings and CMS Medicare reimbursement databases, and customs records for MEMS sensor trade flows — were reconciled through bottom-up and top-down triangulation. Hospital purchasing committees, telemedicine platform CTOs, and regulatory affairs specialists at emerging device manufacturers provided operational context. ClinicalTrials.gov registrations and EU MDR notified body documentation supplied secondary validation.
Historical shipment data was cross-referenced against panel input from component suppliers and distribution channel partners. The analytical framework segments by product type, technology modality, application intensity, and end-user procurement sophistication across the projection horizon. CAGRs were derived from installed base growth curves and replacement cycle assumptions. Edge-AI processing adoption rates and photoplethysmography miniaturization timelines served as industry-specific forecast inputs.
Caveats apply where FDA SaMD pathway revisions or EU MDR clinical evidence requirement changes could materially shift the outlook. Geopolitical disruption in Taiwan MEMS foundry capacity represents a supply-side revision trigger. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Blood Irradiator Device Market
Medical Devices
Artificial Implants Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Rapid Infuser Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Blood Lancet Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Global Ventilators Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
Spinal Stenosis Implant Market